Key Takeaways
- A fund with $1.04 billion in US stocks nearly doubled its Meta Platforms (META) stake in the Q3, added around 70% more Danaher (DHR) shares and bought Boeing (BA) for the first time.
- Analysts’ average targets sit 36% above the price for Meta and Boeing, and 12% above it for Danaher.
- Boeing’s average target is at its lowest of the past year after a slower 737 ramp, and Meta’s AI spending has pushed its expected free cash flow below zero.
- Meta has the best case of the three: 26% revenue growth last quarter at a forward P/E below its five-year average.
A fund with $1.04 billion in US stocks just showed its hand. Its three biggest new or added positions of the Q3 were Meta Platforms, Danaher and Boeing.
The fund is Nan Fung Trinity (HK) Ltd. Its 13F for the quarter ended Sept. 30, filed Nov. 6, lists 55 positions. (A 13F shows only US-listed stocks, so anything the fund holds elsewhere isn’t in it.)
Analysts see upside in all three. But the numbers back one far better than the other two.
Meta is now the fund’s biggest bet
Nan Fung ended September with 73,403 Meta shares worth $53 million, up 96% from the quarter before. That made Meta its No. 1 holding, at 5.1% of its US stocks.
The stock is down 14% since Sept. 30, though that’s the price alone, since a 13F doesn’t show what the fund paid.
The business gives the bet plenty to work with. Q3 revenue rose 26% to $64.6 billion, and management guides Q4 revenue to $73 billion to $76 billion.
And JPMorgan just picked Meta over Alphabet for its Analyst Focus List, with a $940 target.
Analysts’ average target for Meta has stayed close to $850 all year:
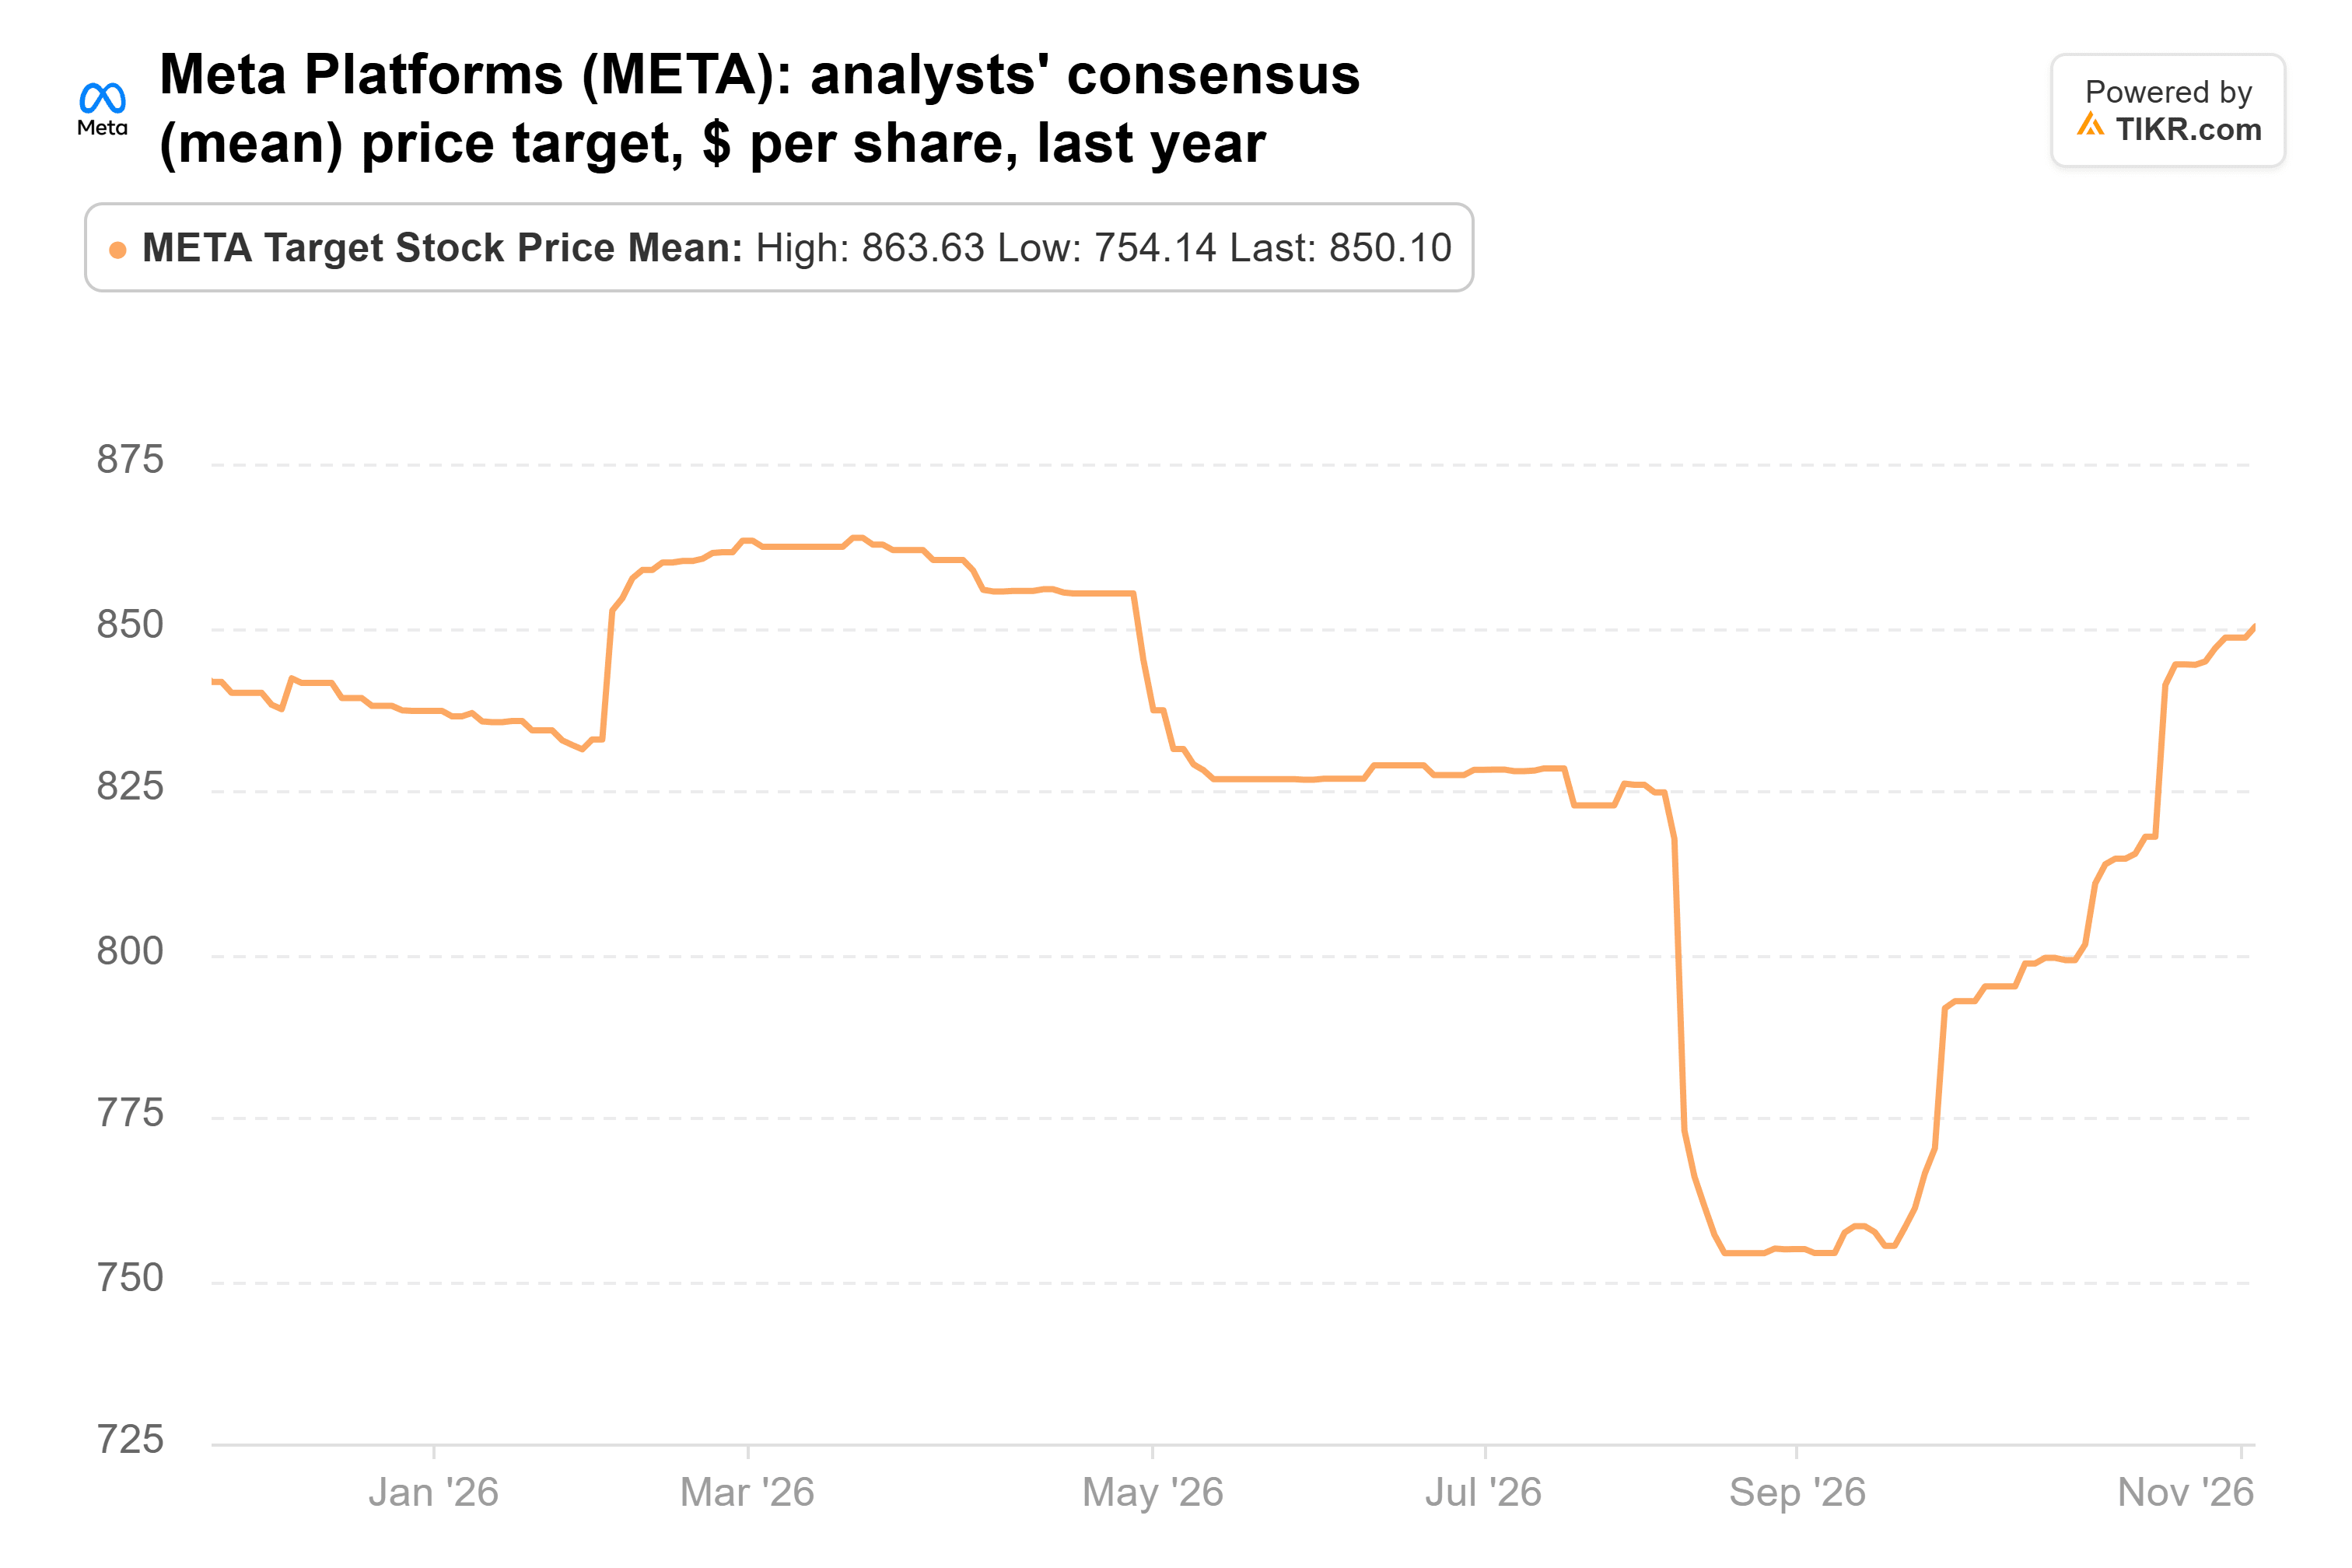
At $850.10 from 63 analysts, it sits 36% above the last close of $623.61. Meta also trades at about 19x forward earnings, below the 21.4x it averaged at quarter-ends over the past five years.
TIKR tracks 63 analysts on Meta Platforms. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Meta Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Meta Platforms’ Analyst Ratings
Danaher is getting better, and investors have noticed
Nan Fung added around 70% more Danaher shares in the quarter. It ended with 171,200 shares worth $38 million, its No. 8 holding at 3.6%. Danaher is the only one of the three that’s up since Sept. 30, by 4%.
Danaher beat on the Q3 and saw improving trends across its end markets. Its Oct. 21 release showed revenue up 8.5% to $6.6 billion and adjusted EPS up 11.5% to $2.11. Core revenue rose 3.0%, held back by shrinking respiratory testing sales. Without them, core growth sped up to 5.5% from 4.5% in the Q2.
The Street’s average target has barely moved over the year, though it dipped in the summer:
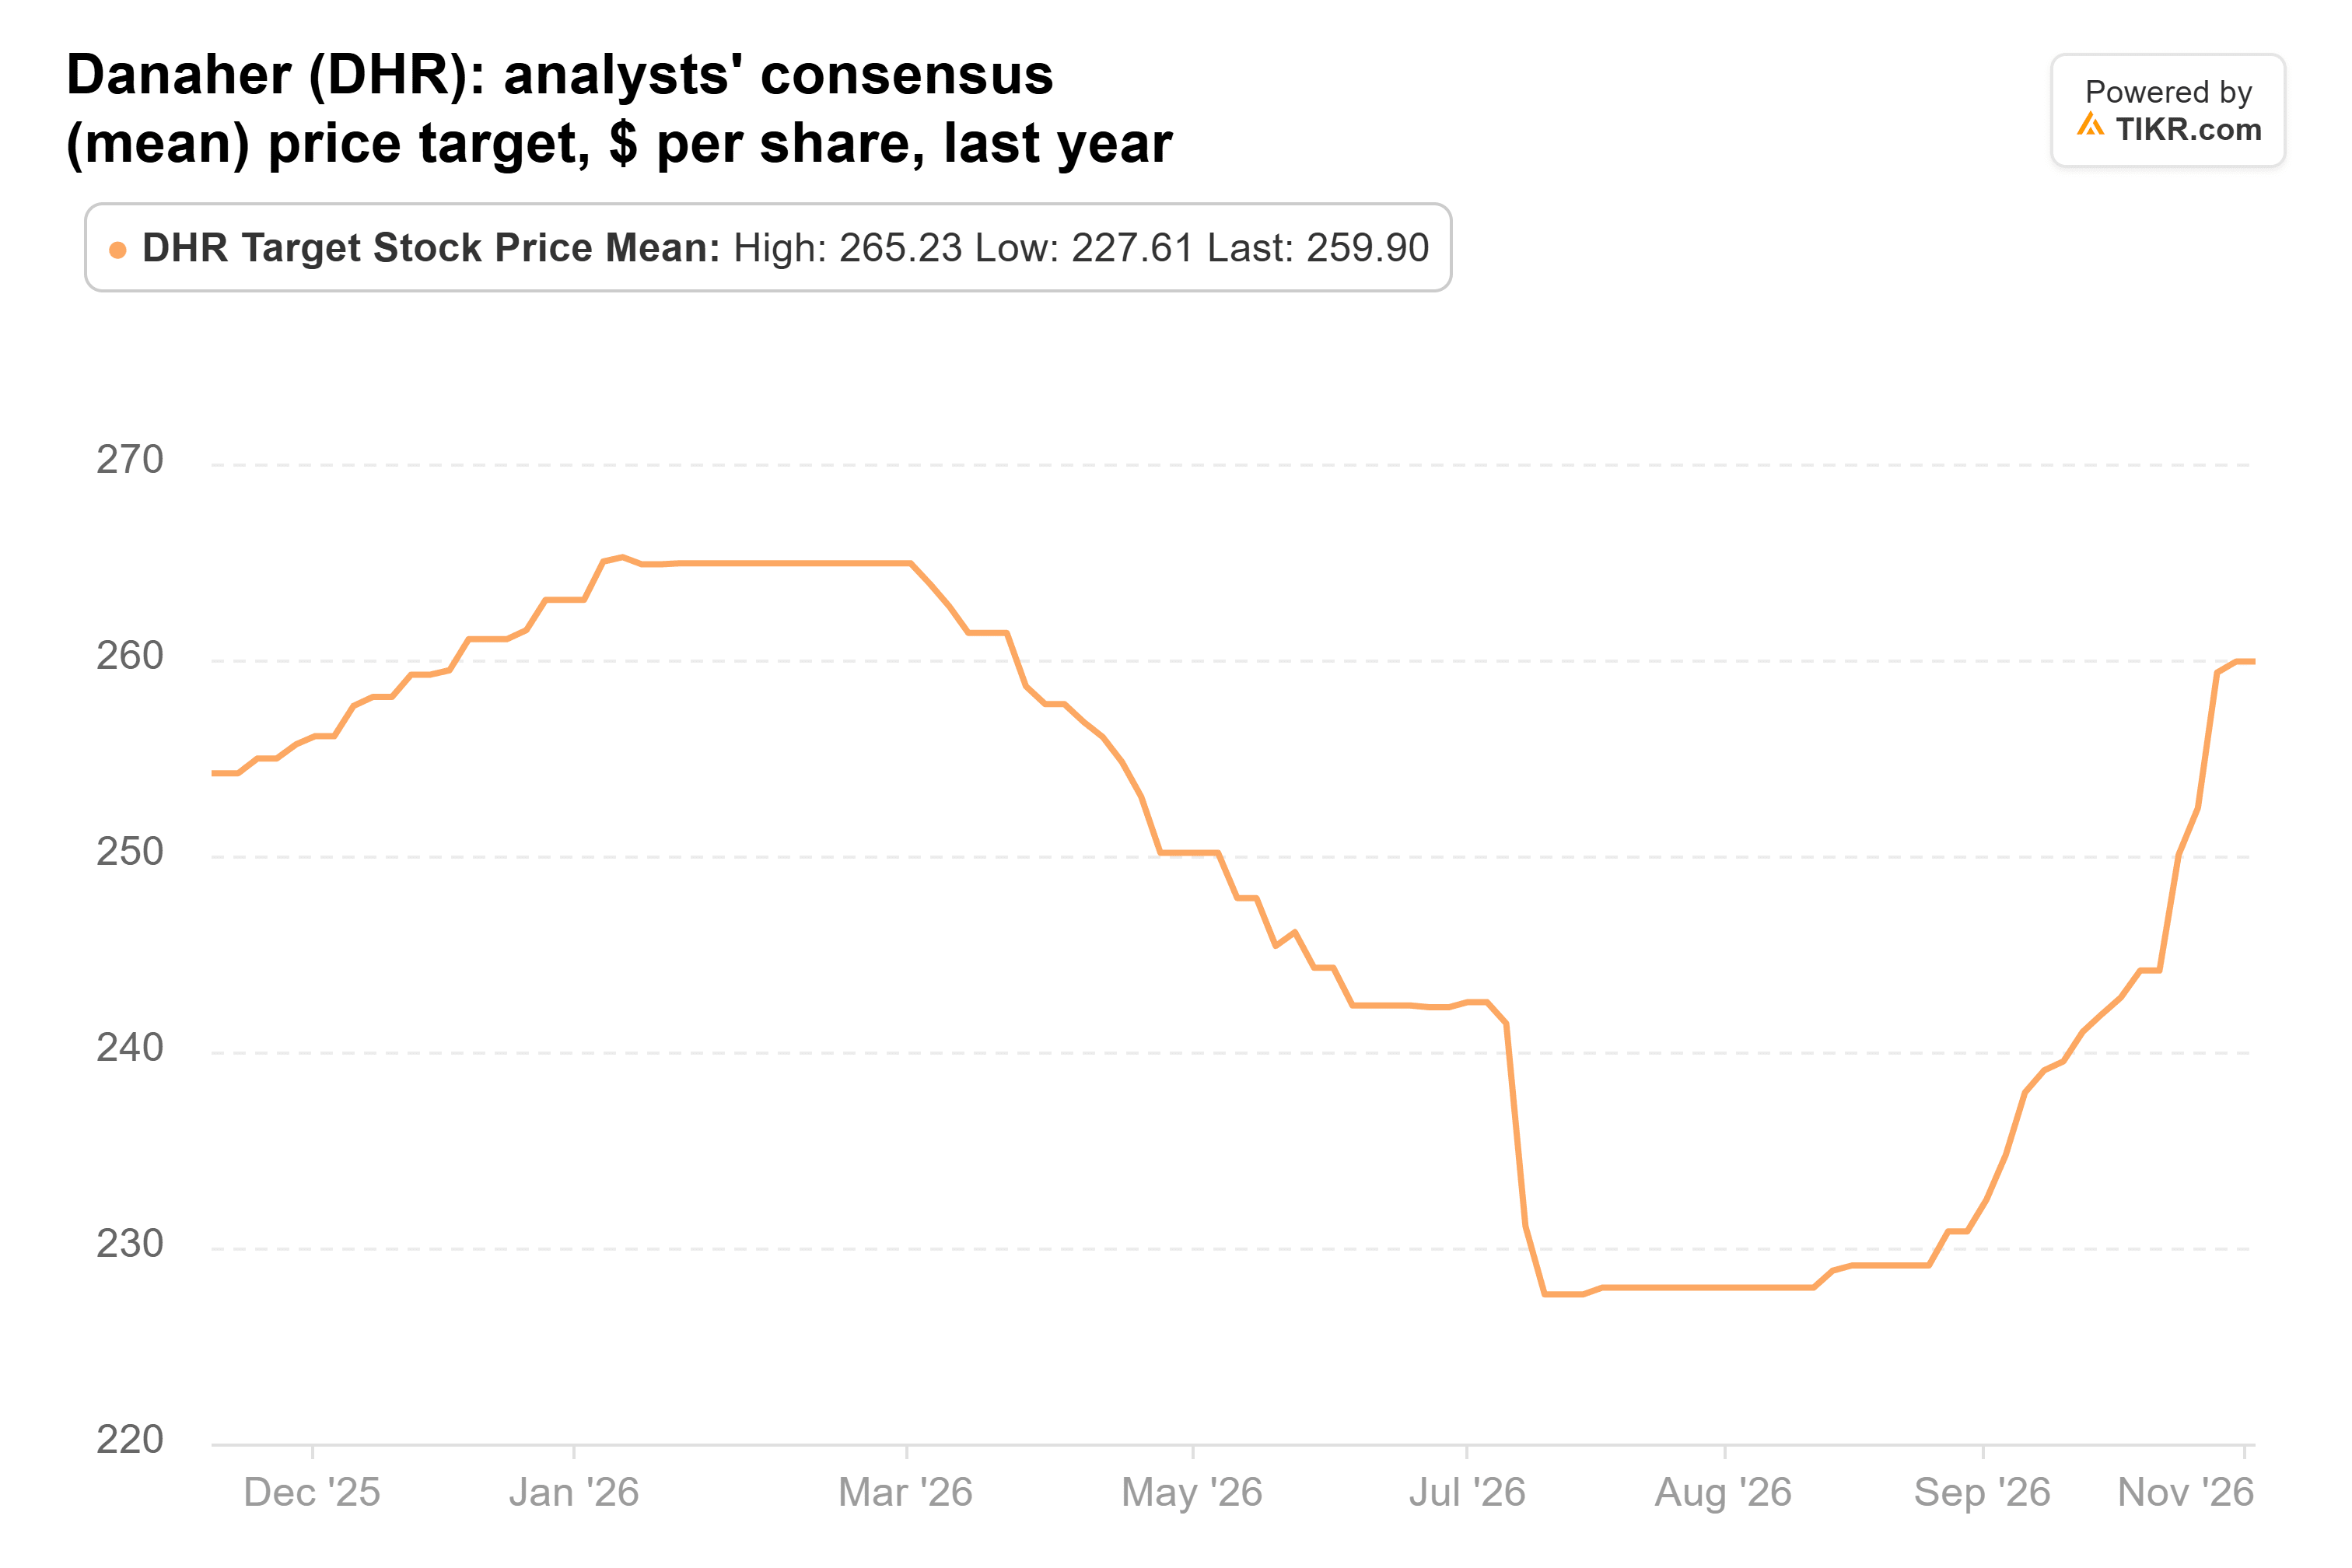
At $259.90 from 24 analysts, it’s just 12% above the last close of $232.16.
The stock has climbed from a May low near $162 to within 4% of its 52-week high. At about 26x forward earnings, much of the recovery is already in the price.
Boeing’s targets keep coming down
Boeing is the only new name of the three. Nan Fung held 190,700 shares worth $35 million at Sept. 30, its No. 9 holding at 3.4%. The stock is down 8% since.
Its Q3 report on Oct. 27 is a big reason why. Commercial Airplanes lost $697 million, a -6.5% margin against -2.7% in the Q2, and 737 output ran near 41 a month.
CEO Kelly Ortberg said “it is taking us longer than we had expected to demonstrate performance at rate 47,” and Boeing now targets 52 a month in the second half of 2027.
Management also set free cash flow targets of $3 billion for 2027 and about $6 billion for 2028, below what analysts had expected.
Analysts’ average target is now at its lowest of the past year:
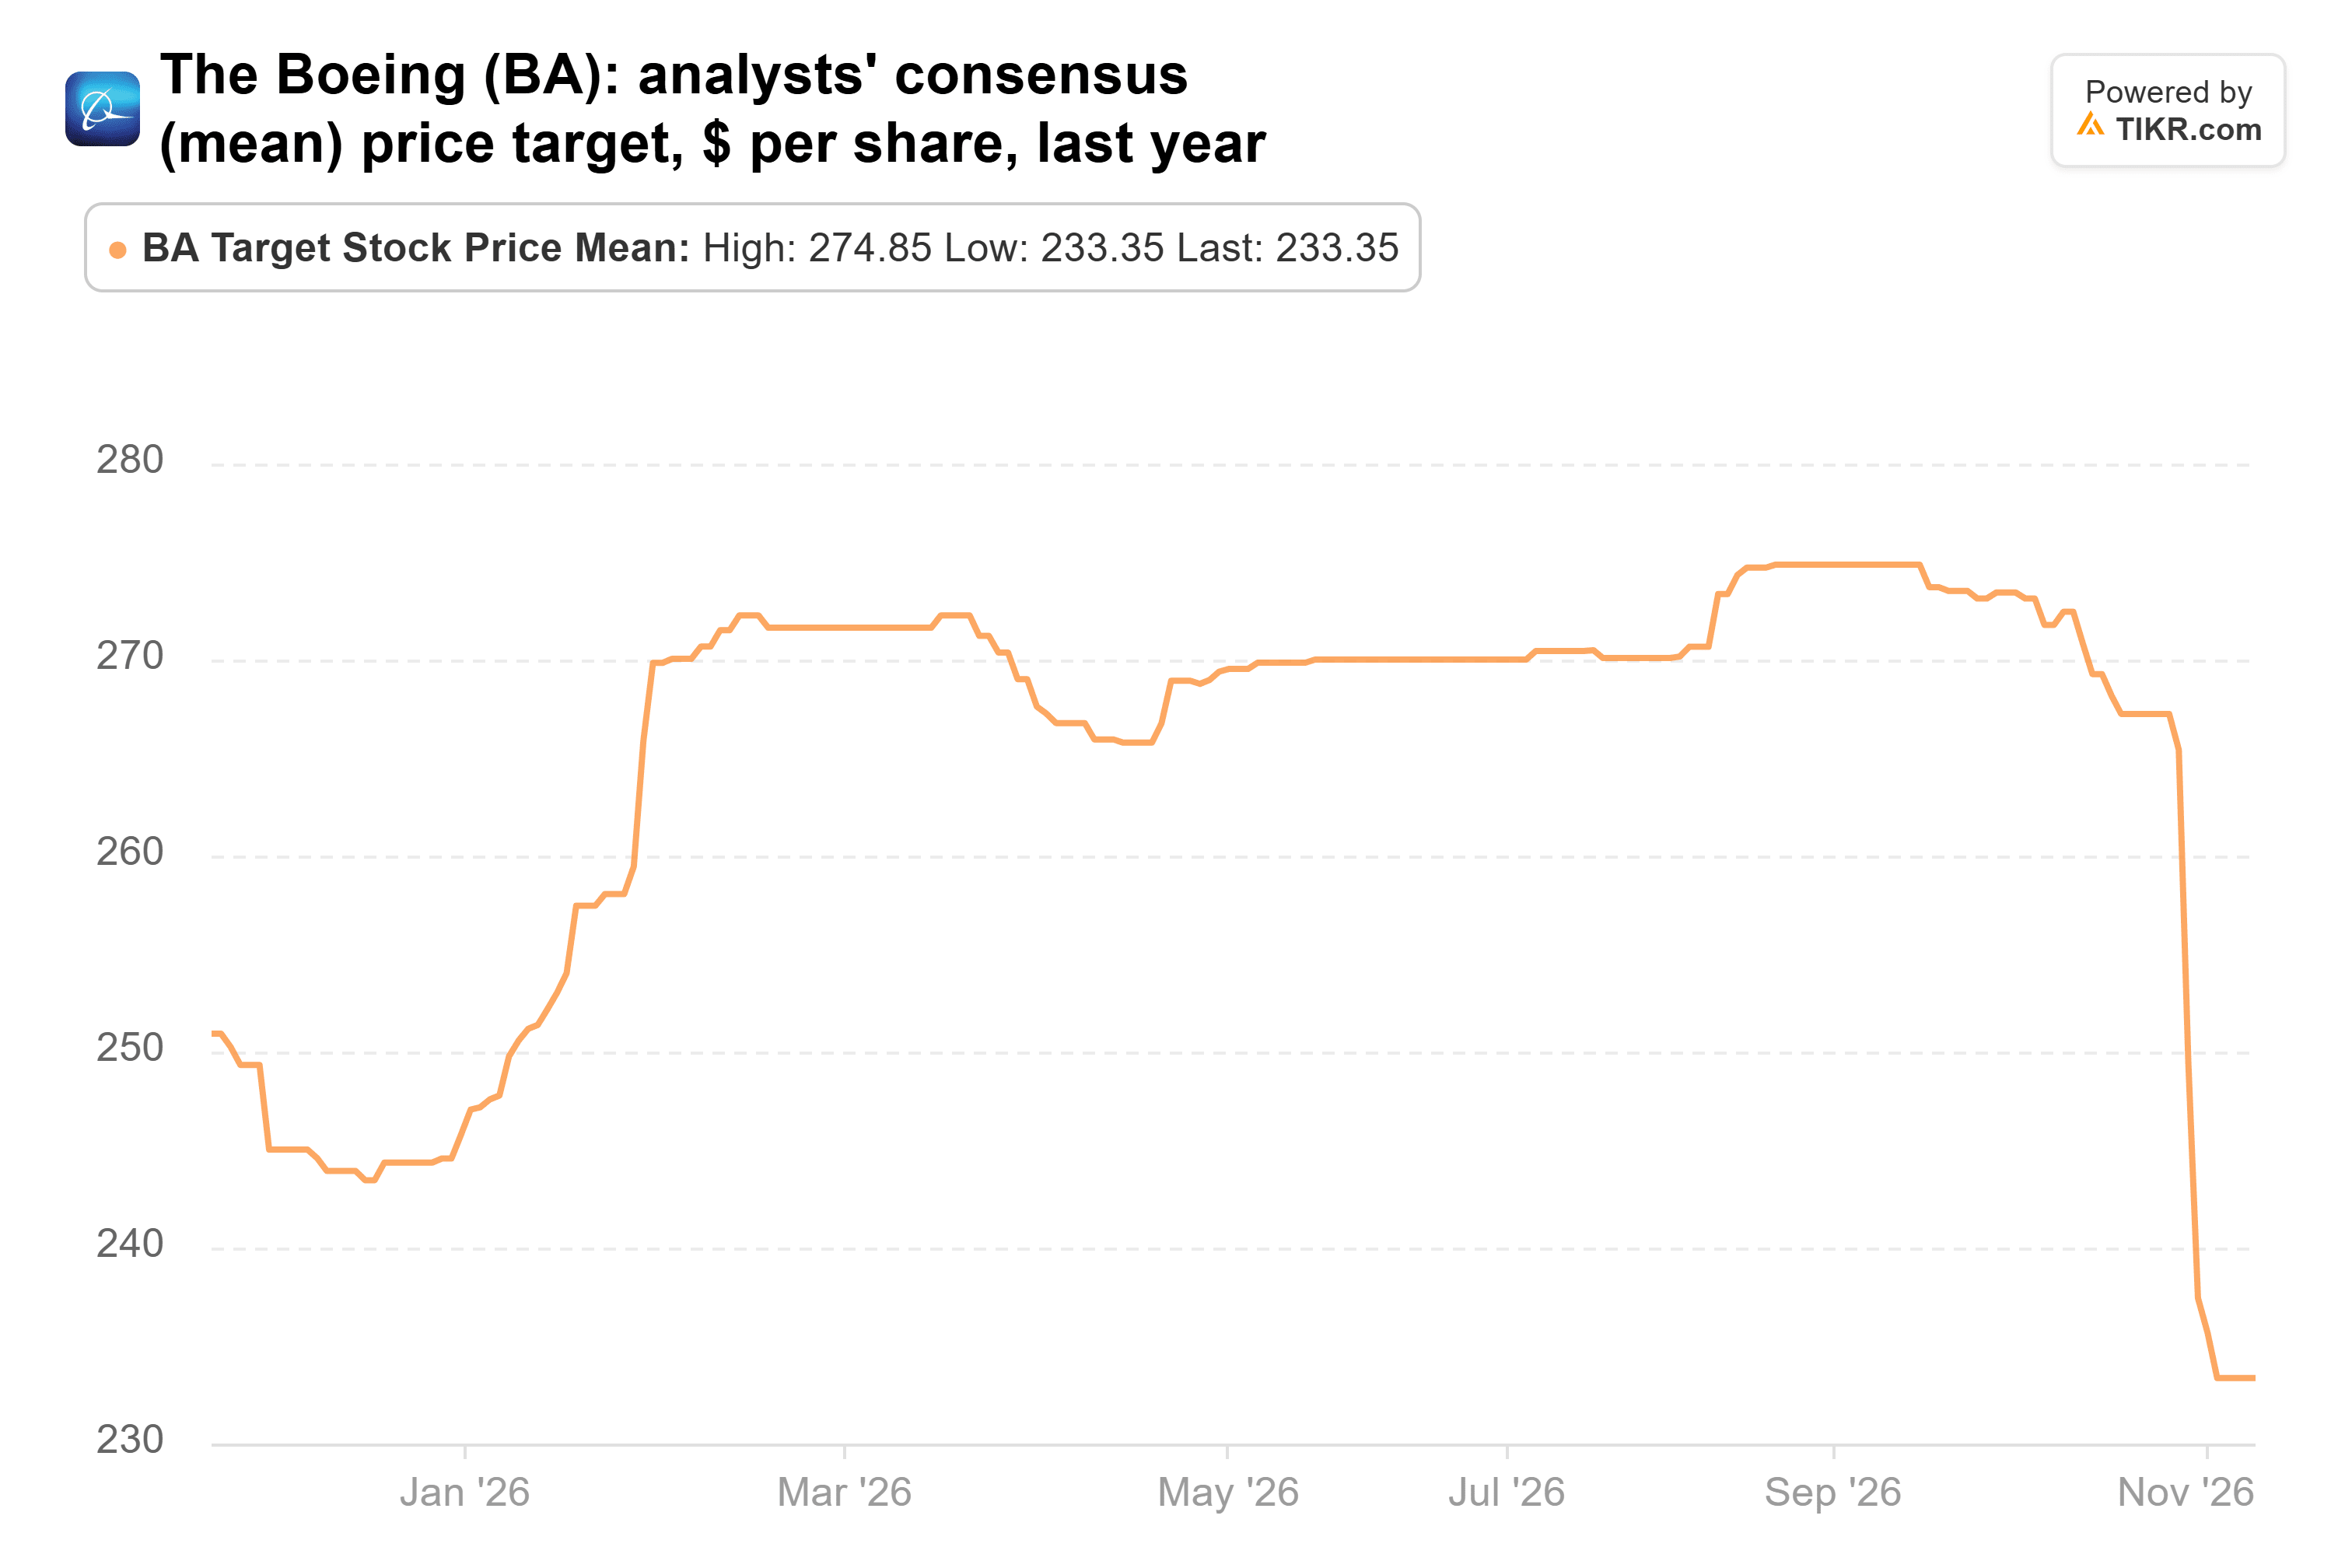
At $233.35 from 27 analysts, it’s down from $274.85 in August, though still 35% above the last close of $171.55.
Earnings estimates have fallen harder: consensus 2027 EPS is $2.16, against $6.46 at the end of September 2025.
With earnings that thin, Boeing’s forward P/E of more than 250x isn’t much use. At the 18.8x it averaged from 2014 to 2019, analysts’ $5.94 of 2028 EPS works out to about $110 a share, below today’s price.
Meta is the pick of the three
Meta has a real risk of its own: the AI build. It guides 2026 capital spending to $135 billion to $145 billion, up from $72.2 billion in 2025, and consensus has its free cash flow negative in 2026, 2027 and 2028. S&P cut its outlook on Meta’s credit rating to negative on Oct. 30 over that cash gap.
Still, if I could only buy one of Nan Fung’s three, it’d be Meta. Its ad business is growing fastest, and its multiple sits below its own history.
Danaher’s recovery looks largely priced in, and Boeing’s estimates haven’t stopped falling.
Meta’s Q4 report in late January, with its first look at 2027 spending, will show us whether that cash gap is still widening. And Nan Fung’s next 13F, due in mid-February, will show whether the fund held on.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!