Key Takeaways
- Snap stock fell 17% in the past month, mostly after a third-quarter report with 4% ad growth and a user miss.
- Meta Platforms, Pinterest and Reddit all grew revenue far faster than Snap’s ads, so the slowdown looks like Snap’s own.
- Subscriptions and cost cuts are working, but Snap’s 7x forward P/E leaves out about $1.05 billion of stock pay this year.
- February’s fourth-quarter report has to show ads picking up before the stock is worth loading up on.
Snap (SNAP) stock is down 17% in the past month, closing at $5.09 on Nov. 16. Most of the drop came from a 14% fall the day after its Nov. 4 third-quarter report. CEO Evan Spiegel admitted as much: “While advertising revenue growth remains below our ambitions, advertisers are seeing the benefits of our performance improvements.”
The month opened with a scare for the whole group. On Oct. 29, Pinterest (PINS) guided its fourth quarter below expectations and is down 16% since Oct. 16. Reddit (RDDT) warned that falling search traffic could shrink its daily users. But Meta Platforms (META) grew third-quarter ad revenue 26%, so advertisers are still spending.
Snap’s Ad Problem Is Its Own
Revenue rose 14% to $1.72 billion, and daily users of 495 million missed the 499 million expected. Advertising grew just 4% to $1.37 billion as brand ads fell from a year earlier. Rivals didn’t have that problem: Pinterest still grew revenue 12%, Reddit grew 53%, and Meta’s ad prices rose 14%. The money is out there, and less of it is going to Snapchat.
The user mix makes it worse. North American daily users fell 6% to 92 million, and each one brought in $11.07 of revenue in the quarter, nearly 10 times the $1.13 from a user outside North America and Europe. Snap’s growth is coming from its cheapest users, and from the first quarter of 2027, it will stop reporting daily users by region.
TIKR Tracks 41 Analysts on Snap. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snap, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snap’s Analyst Ratings
Cheap at About 7x, Until You Count Stock Pay
Paid subscribers passed 30 million, up 5 million since February, and subscription-led revenue grew 84% to $350 million. Costs rose just 1%, so adjusted EBITDA more than doubled to $383 million. Analysts raised their 2026 normalized EPS estimate to $0.64 from $0.61 in late October, and they expect more growth after that:
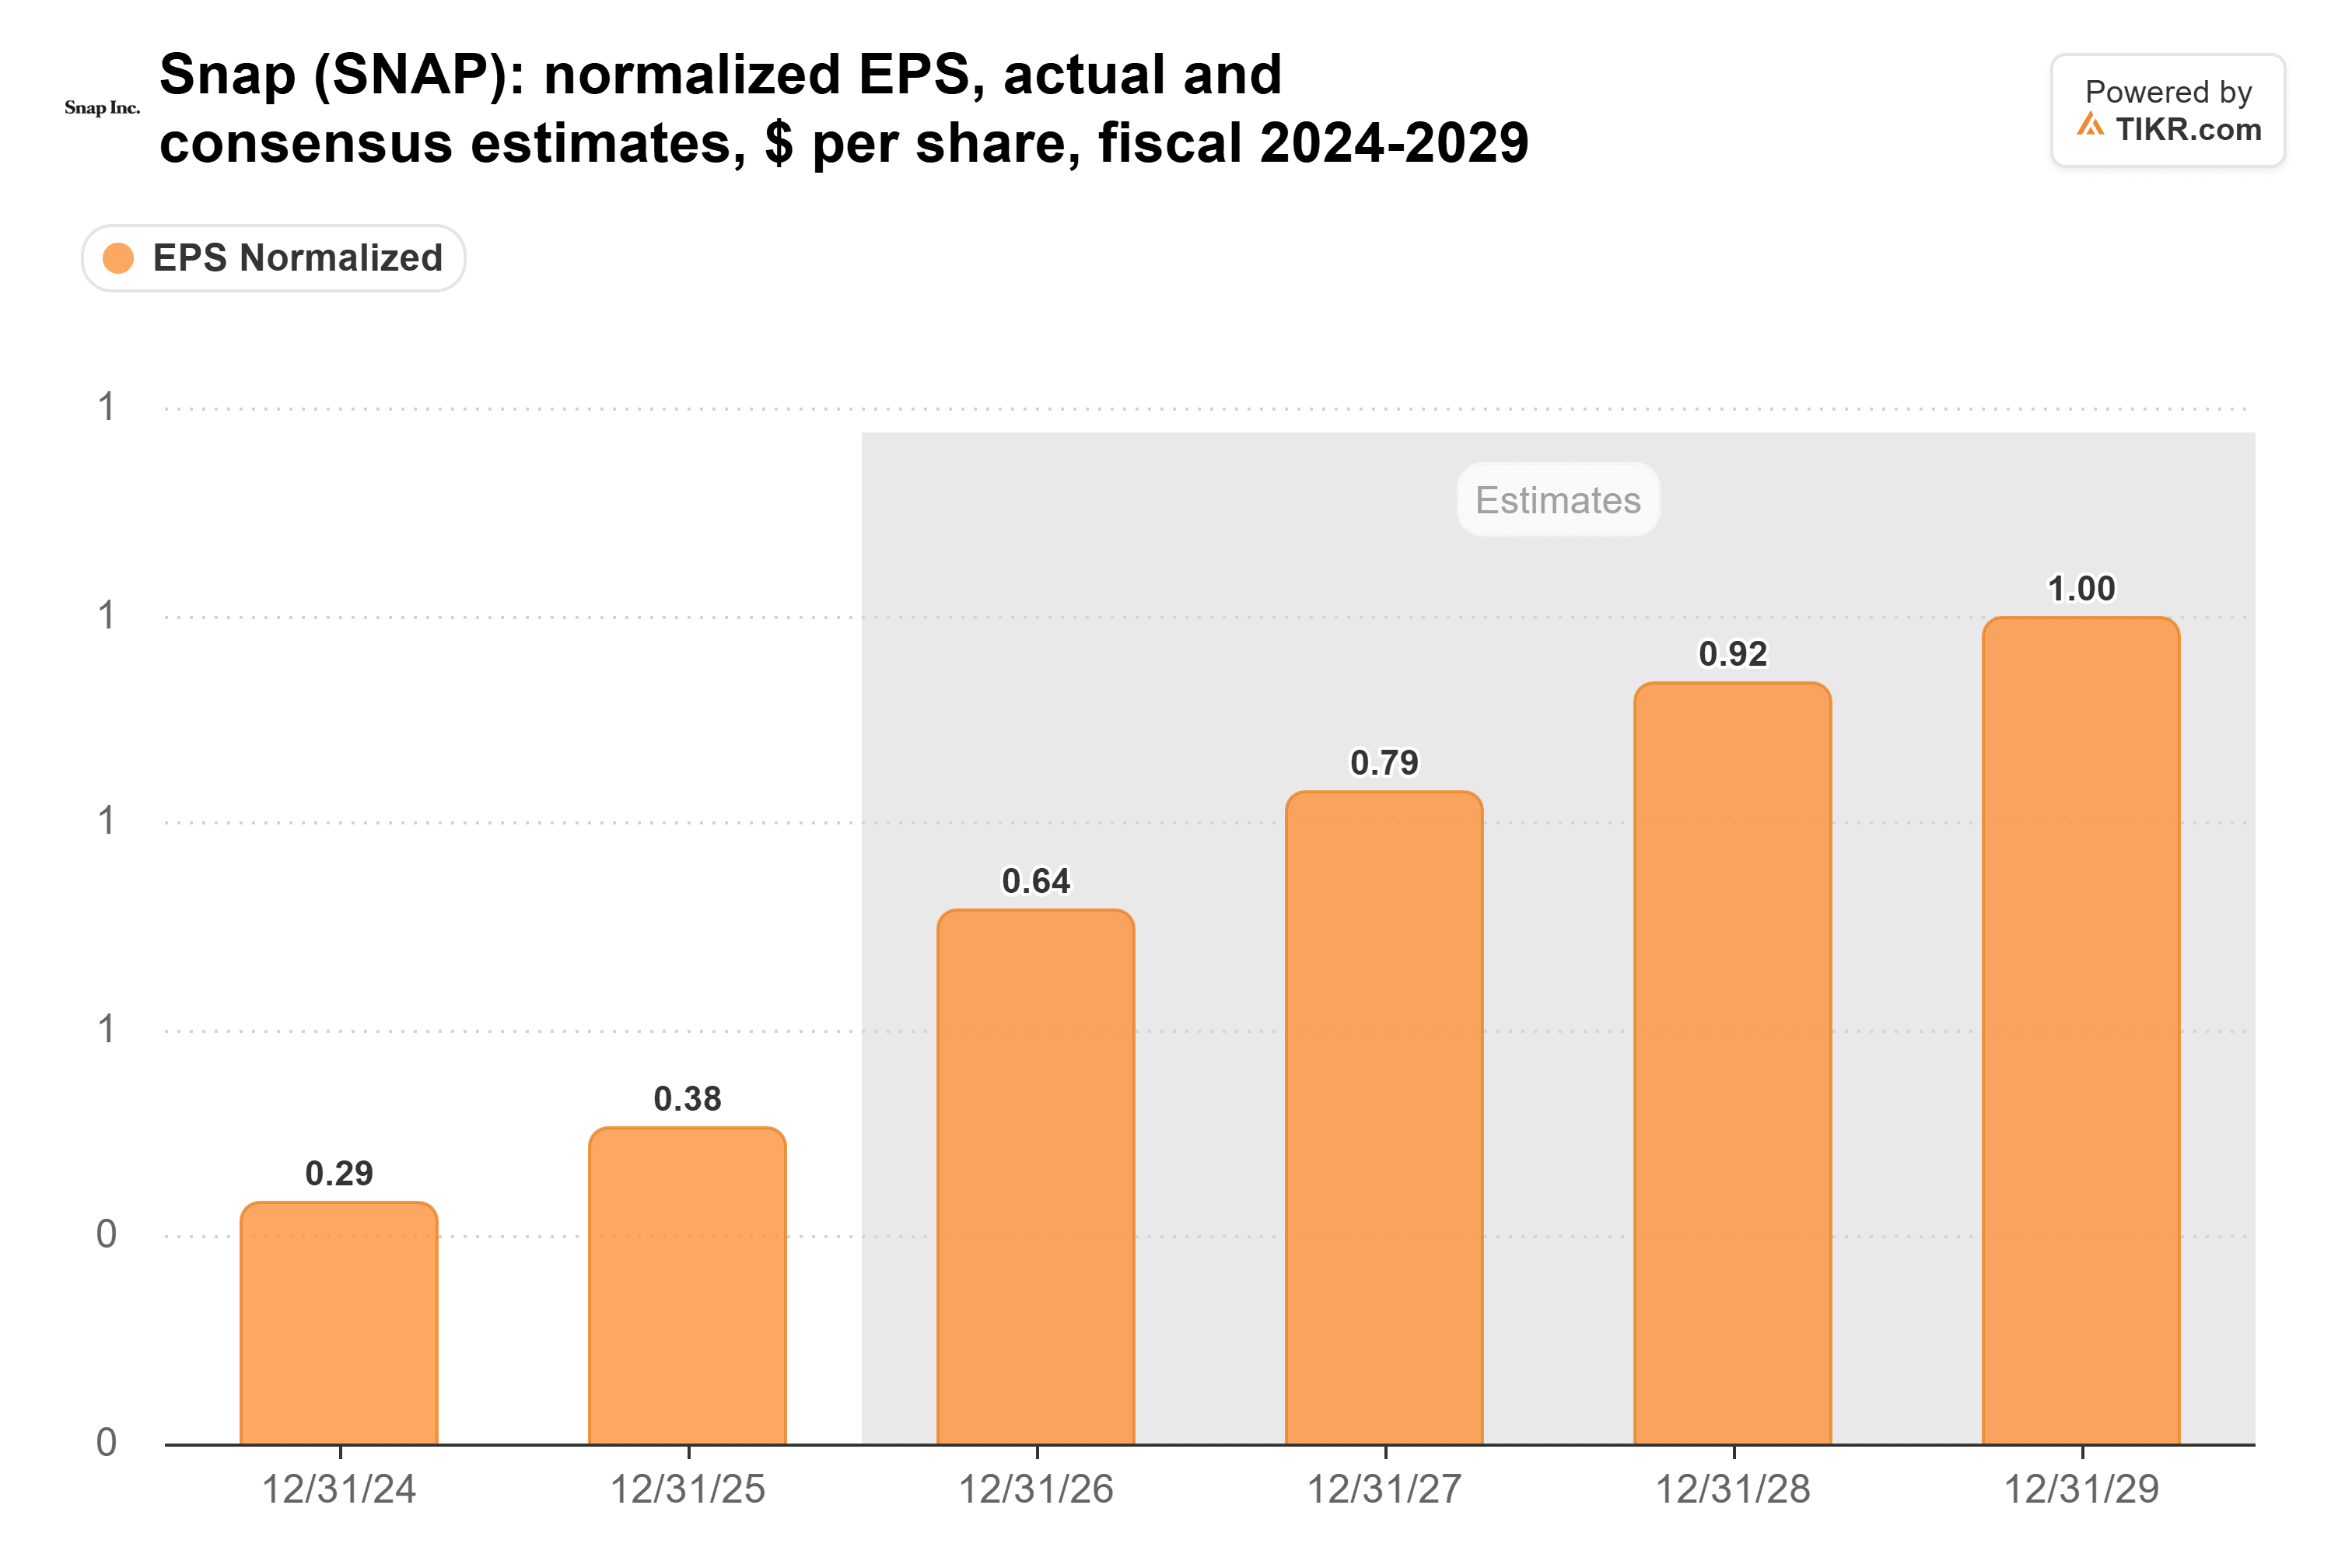
On those estimates, Snap trades at about 7x forward earnings, against nearly 12x on average over the past year. But they leave out stock pay of about $1.05 billion this year, more than the $777 million of free cash flow Snap made over the last 12 months. CFO Doug Hott is aiming for a stable fully diluted share count in 2027. For now, it’s 1.93 billion, up from 1.86 billion a year earlier.
February Is Snap’s Next Real Test
I wouldn’t sell at this price with subscription revenue up 84%. But cost cuts won’t fix the ads, so I’d wait for the fourth-quarter report, due in early February, before loading up. It needs to show ad growth heading back toward double digits from 4%. Thousands of social media addiction suits are also still pending, even after Snap settled two teenagers’ claims on Nov. 2, with jury selection already underway in Los Angeles.
So What Is Snap Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snap could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!