Key Takeaways
- Apple lost about $140 billion of market value after hours on Nov. 2, after CEO John Ternus called memory pricing “unprecedented” and Apple guided December-quarter gross margin to 45% to 46%.
- Memory makers hold the pricing power right now, so the cost squeezing Apple turns into profit for companies like Micron.
- Micron’s quarterly gross margin went from -0.7% in late 2023 to 86.8% in its latest quarter, and analysts expect its normalized EPS to more than double in fiscal 2027.
- Apple can absorb a few hard quarters. For Micron, the big risks are supply catching up with demand, and higher prices starting to cost Apple sales.
Apple (AAPL) beat Wall Street’s estimates on Monday, then lost about $140 billion of market value after hours anyway. (It’s regained some of that, just down about 2% as of now.)
The reason, very simply, was memory. On his first earnings call as CEO, John Ternus said, “What we’re seeing with memory pricing right now is unprecedented.”
Every extra dollar Apple pays for memory goes to the handful of companies that make it, Micron Technology (MU) among them. (Micron’s shares rose Tuesday morning as chip stocks rebounded.)
Bloomberg Intelligence’s Anurag Rana was asked on Bloomberg’s Apple earnings special what his top question would be for Apple’s executives. He went straight to it: “Tell me how are you going to maintain gross margins over the next, I would say, three to four quarters with memory prices up, going so high?”
Apple’s answer: it won’t, at least not in the December quarter.
That’s the hit investors were watching for going into the report. Apple guided December-quarter gross margin to 45% to 46%. That’s below the 46.3% analysts expected and down from 47.9% in the September quarter, when tariff refunds added about a point. CFO Kevan Parekh said that once those refunds are stripped out, higher memory costs account for most of the drop to the midpoint. (A Services growth guide of 8% to 9%, below the roughly 10.7% analysts expected, didn’t help either.)
TIKR tracks 49 analysts on Micron. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
And Ternus doesn’t see relief coming soon: “looking beyond the December quarter, we see the pricing for memory purchases continuing to increase.”
Micron is on the other side of that bill
Only a few companies are collecting that money. Tim Cook, Apple’s CEO until September, said on its July call that the DRAM market has three suppliers. Micron is one of them.
Analysts expect Micron’s normalized EPS to more than double again, from $75.52 a share in fiscal 2026 (which ended in early September) to $176.50 in fiscal 2027.
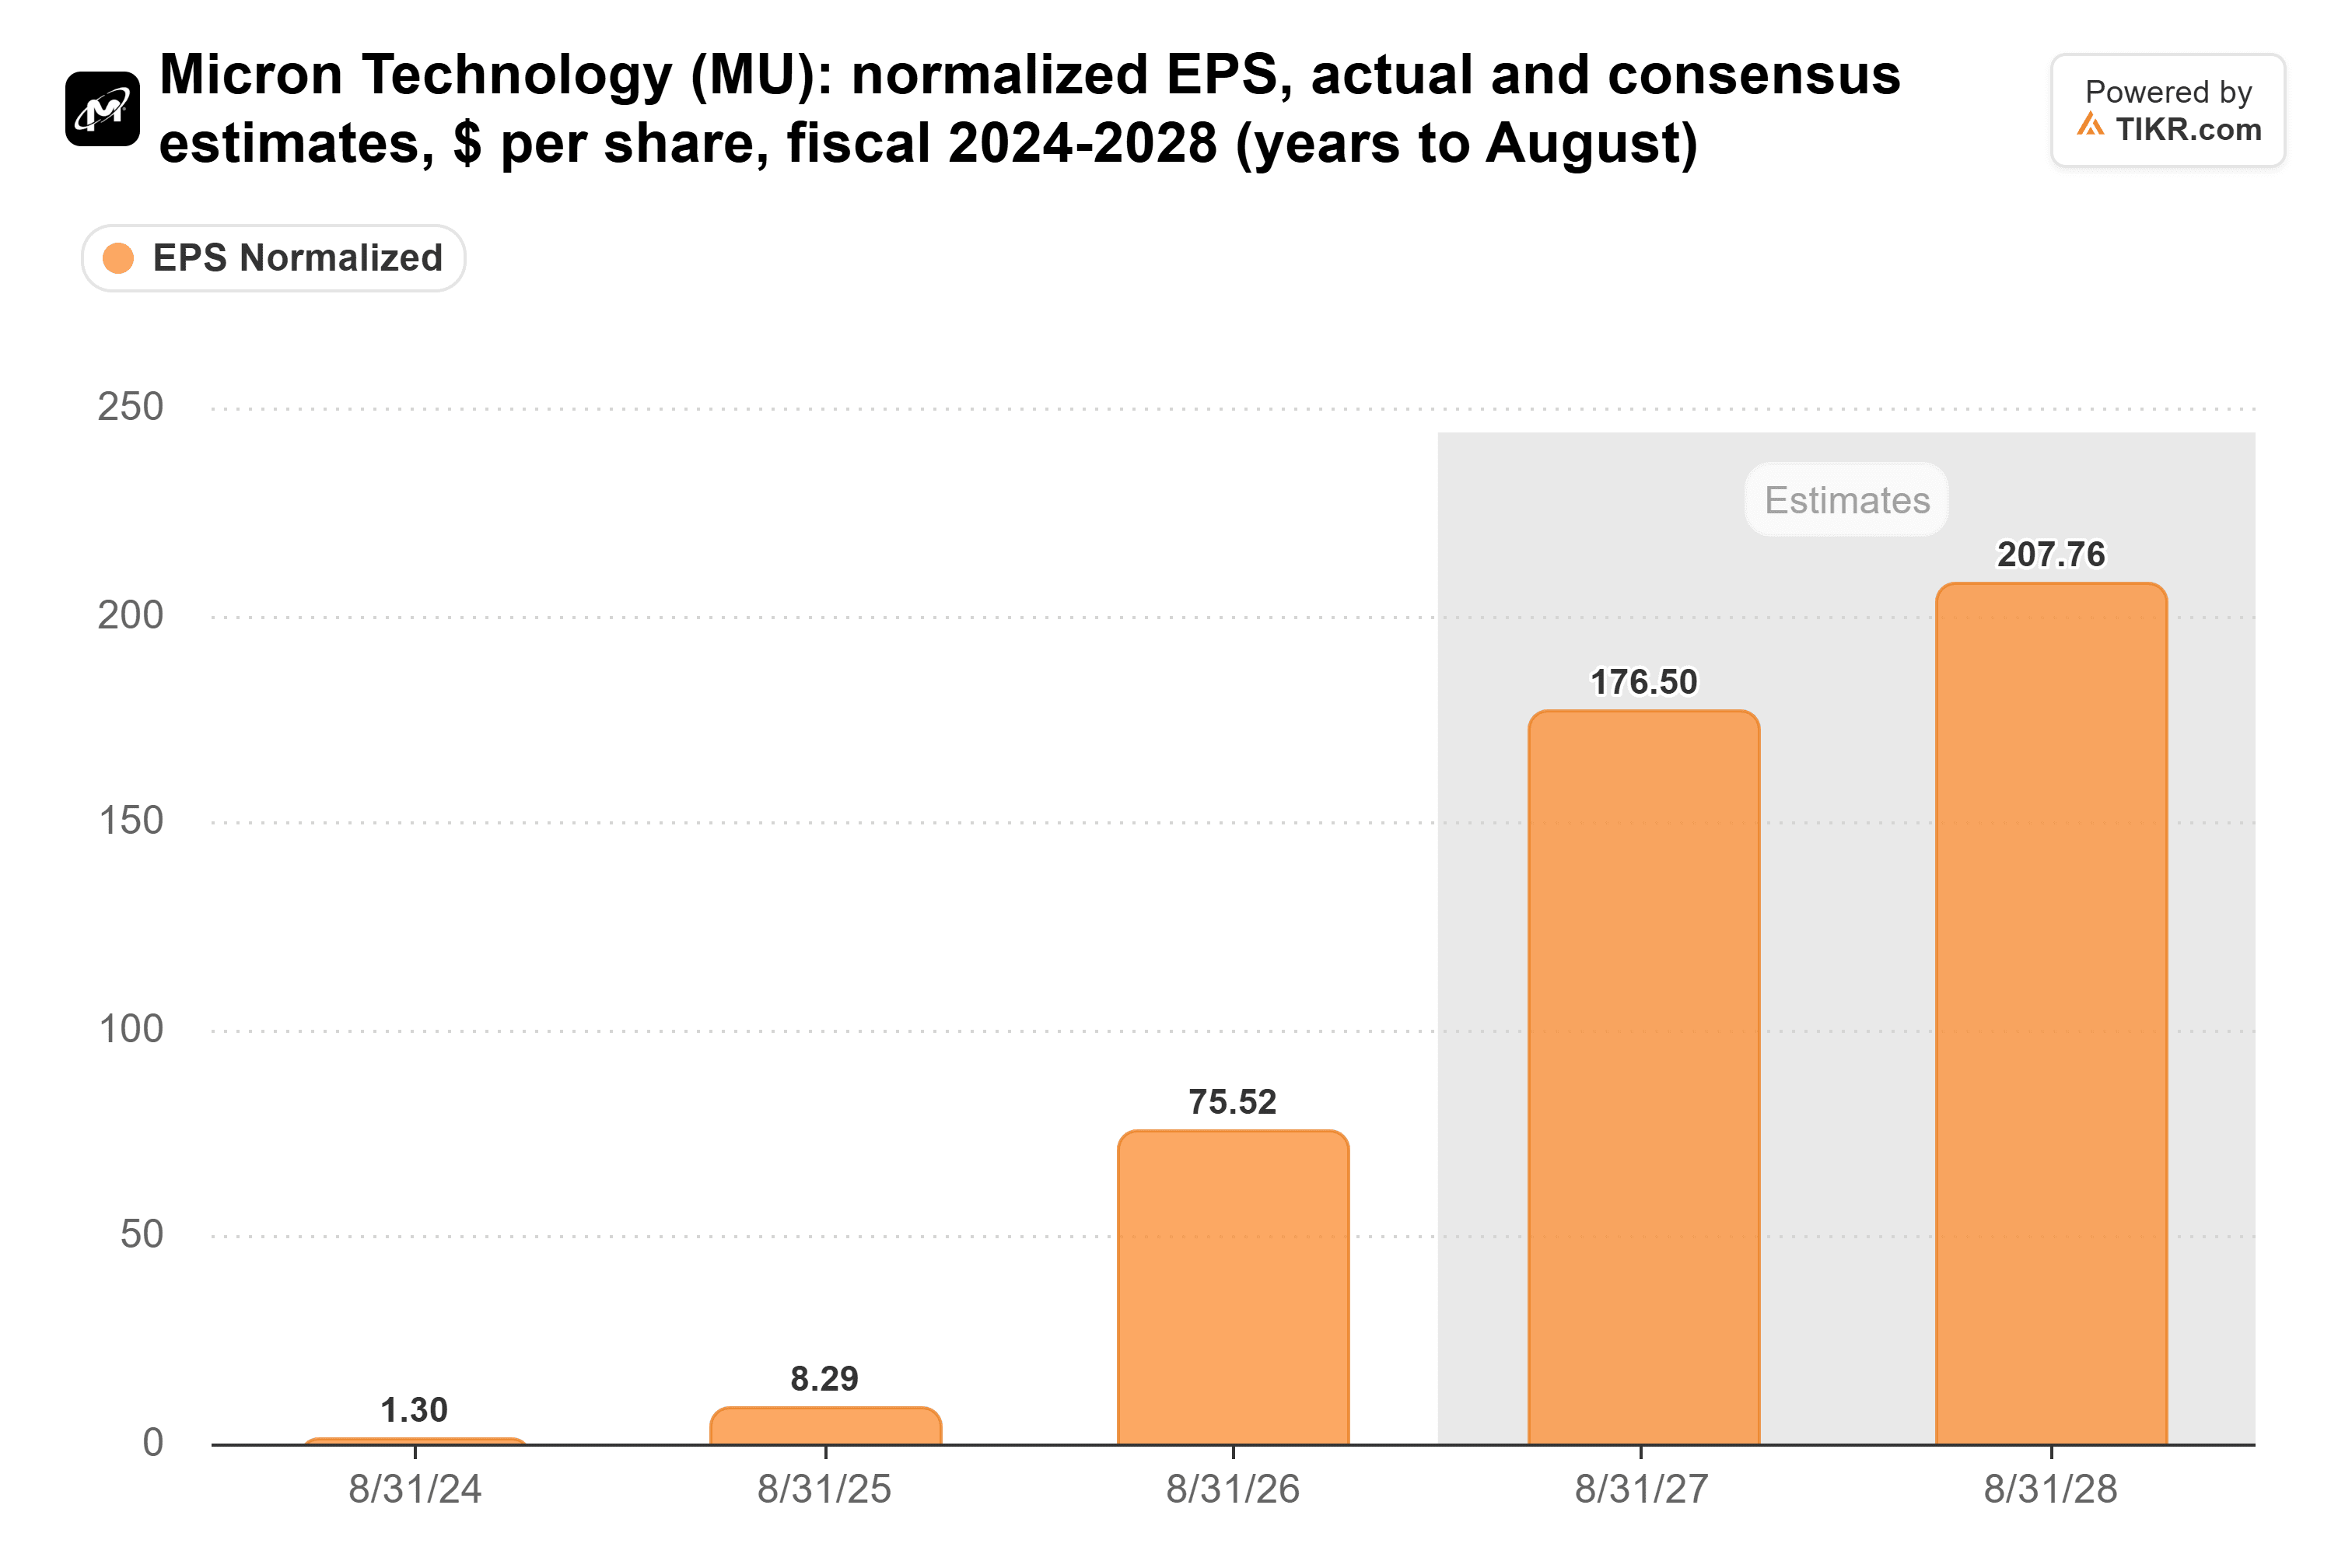
If anything, Ternus just gave analysts a reason to raise those numbers.
You can see the pricing power in Micron’s gross margin. It went from -0.7% in the quarter ended November 2023 to 86.8% in the quarter ended Sept. 3, 2026.

That’s higher than the 76.3% gross margin of Apple’s Services business, its highest-margin line, in the nine months to June 27.
Apple can absorb a few hard quarters
Of course, Apple isn’t helpless. Its gross margin rose for four straight quarters, to 50.1% in the quarter ended June 27 (tariff refunds added about 2 points of that):

Even the top of the December guide would be lower than any quarter on that chart, though. And in each of the past two years, Apple’s December-quarter margin was higher than its September one.
Apple has started passing the cost on. It raised Mac and iPad prices at the end of June and iPhone prices in September. Parekh said “it’s really early to really assess any elasticity impact.”
So far, demand is holding. Apple guided December-quarter revenue growth to 7% to 10%, above the 6.1% analysts expected. Chief operating officer Sabih Khan said memory is the main reason Apple can’t make enough Macs and iPads this quarter.
For Micron, that’s about as good as it gets: a customer that’s short of memory and still paying up for it.
Micron wins until supply catches up
The way I see it, the memory makers have the pricing power right now, and I’d rather own the company sending the bill than the company who has to pay it. (Sort of like knowing you’re always losing to the insurance company.)
Memory is still a cyclical business, and Micron’s gross margin was below zero less than three years ago. People also disagree on how long the shortage lasts. SK hynix has predicted it runs through 2030, while Dell, after tripling its inventory, says chip supply is a lot closer to demand.
Apple’s December-quarter results, due in late January, will show whether its margin lands in that 45% to 46% range. If Apple starts selling fewer devices at its new prices, Micron will feel that too.
So what is Micron stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!