Key Takeaways
- Bill Ackman said on CNBC on Tuesday that he picked up Visa (V) and Mastercard (MA) in the low 20s times earnings, and he called them a royalty on consumer spending.
- Analysts expect Mastercard’s normalized EPS to grow about 16% a year from 2026 to 2028, faster than the roughly 14% a year they expect from Visa.
- Mastercard’s forward P/E has climbed back to 30x from 23x in June, which is still a little below its five-year average of 31x.
- The estimates support Ackman’s case for Mastercard, but both networks depend on consumers continuing to spend.
Bill Ackman thinks the stock market is broken. He also thinks Mastercard and Visa are a rare kind of business, and he finally got to buy them at his price.
On Tuesday’s Election Day episode of CNBC’s Squawk Pod, Ackman said the market spent this year chasing chips and semiconductors.
Everything else was “sort of ignored,” so he could buy businesses he’d always wanted to own but had found too expensive. When the host asked what was on that list, he named the two card networks:
“It’s sort of a royalty on people spending money. It’s one of the greatest businesses in the world. Always too expensive for us. These were well into the 30s times earnings. We were able to pick them up in the low 20s.”
That’s strong praise from an investor who runs a famously concentrated portfolio.
But he named both networks in the same breath. Mastercard is up 15% in the past month and sits 2% below its 52-week high.
Anyone buying it now needs Wall Street to expect more from Mastercard than from Visa.
TIKR tracks 41 analysts on Mastercard. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Mastercard, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Mastercard’s Analyst Ratings
Wall Street expects faster growth from Mastercard
Analysts expect Mastercard’s normalized EPS to rise from $17.01 in 2025 to $26.89 in 2028:
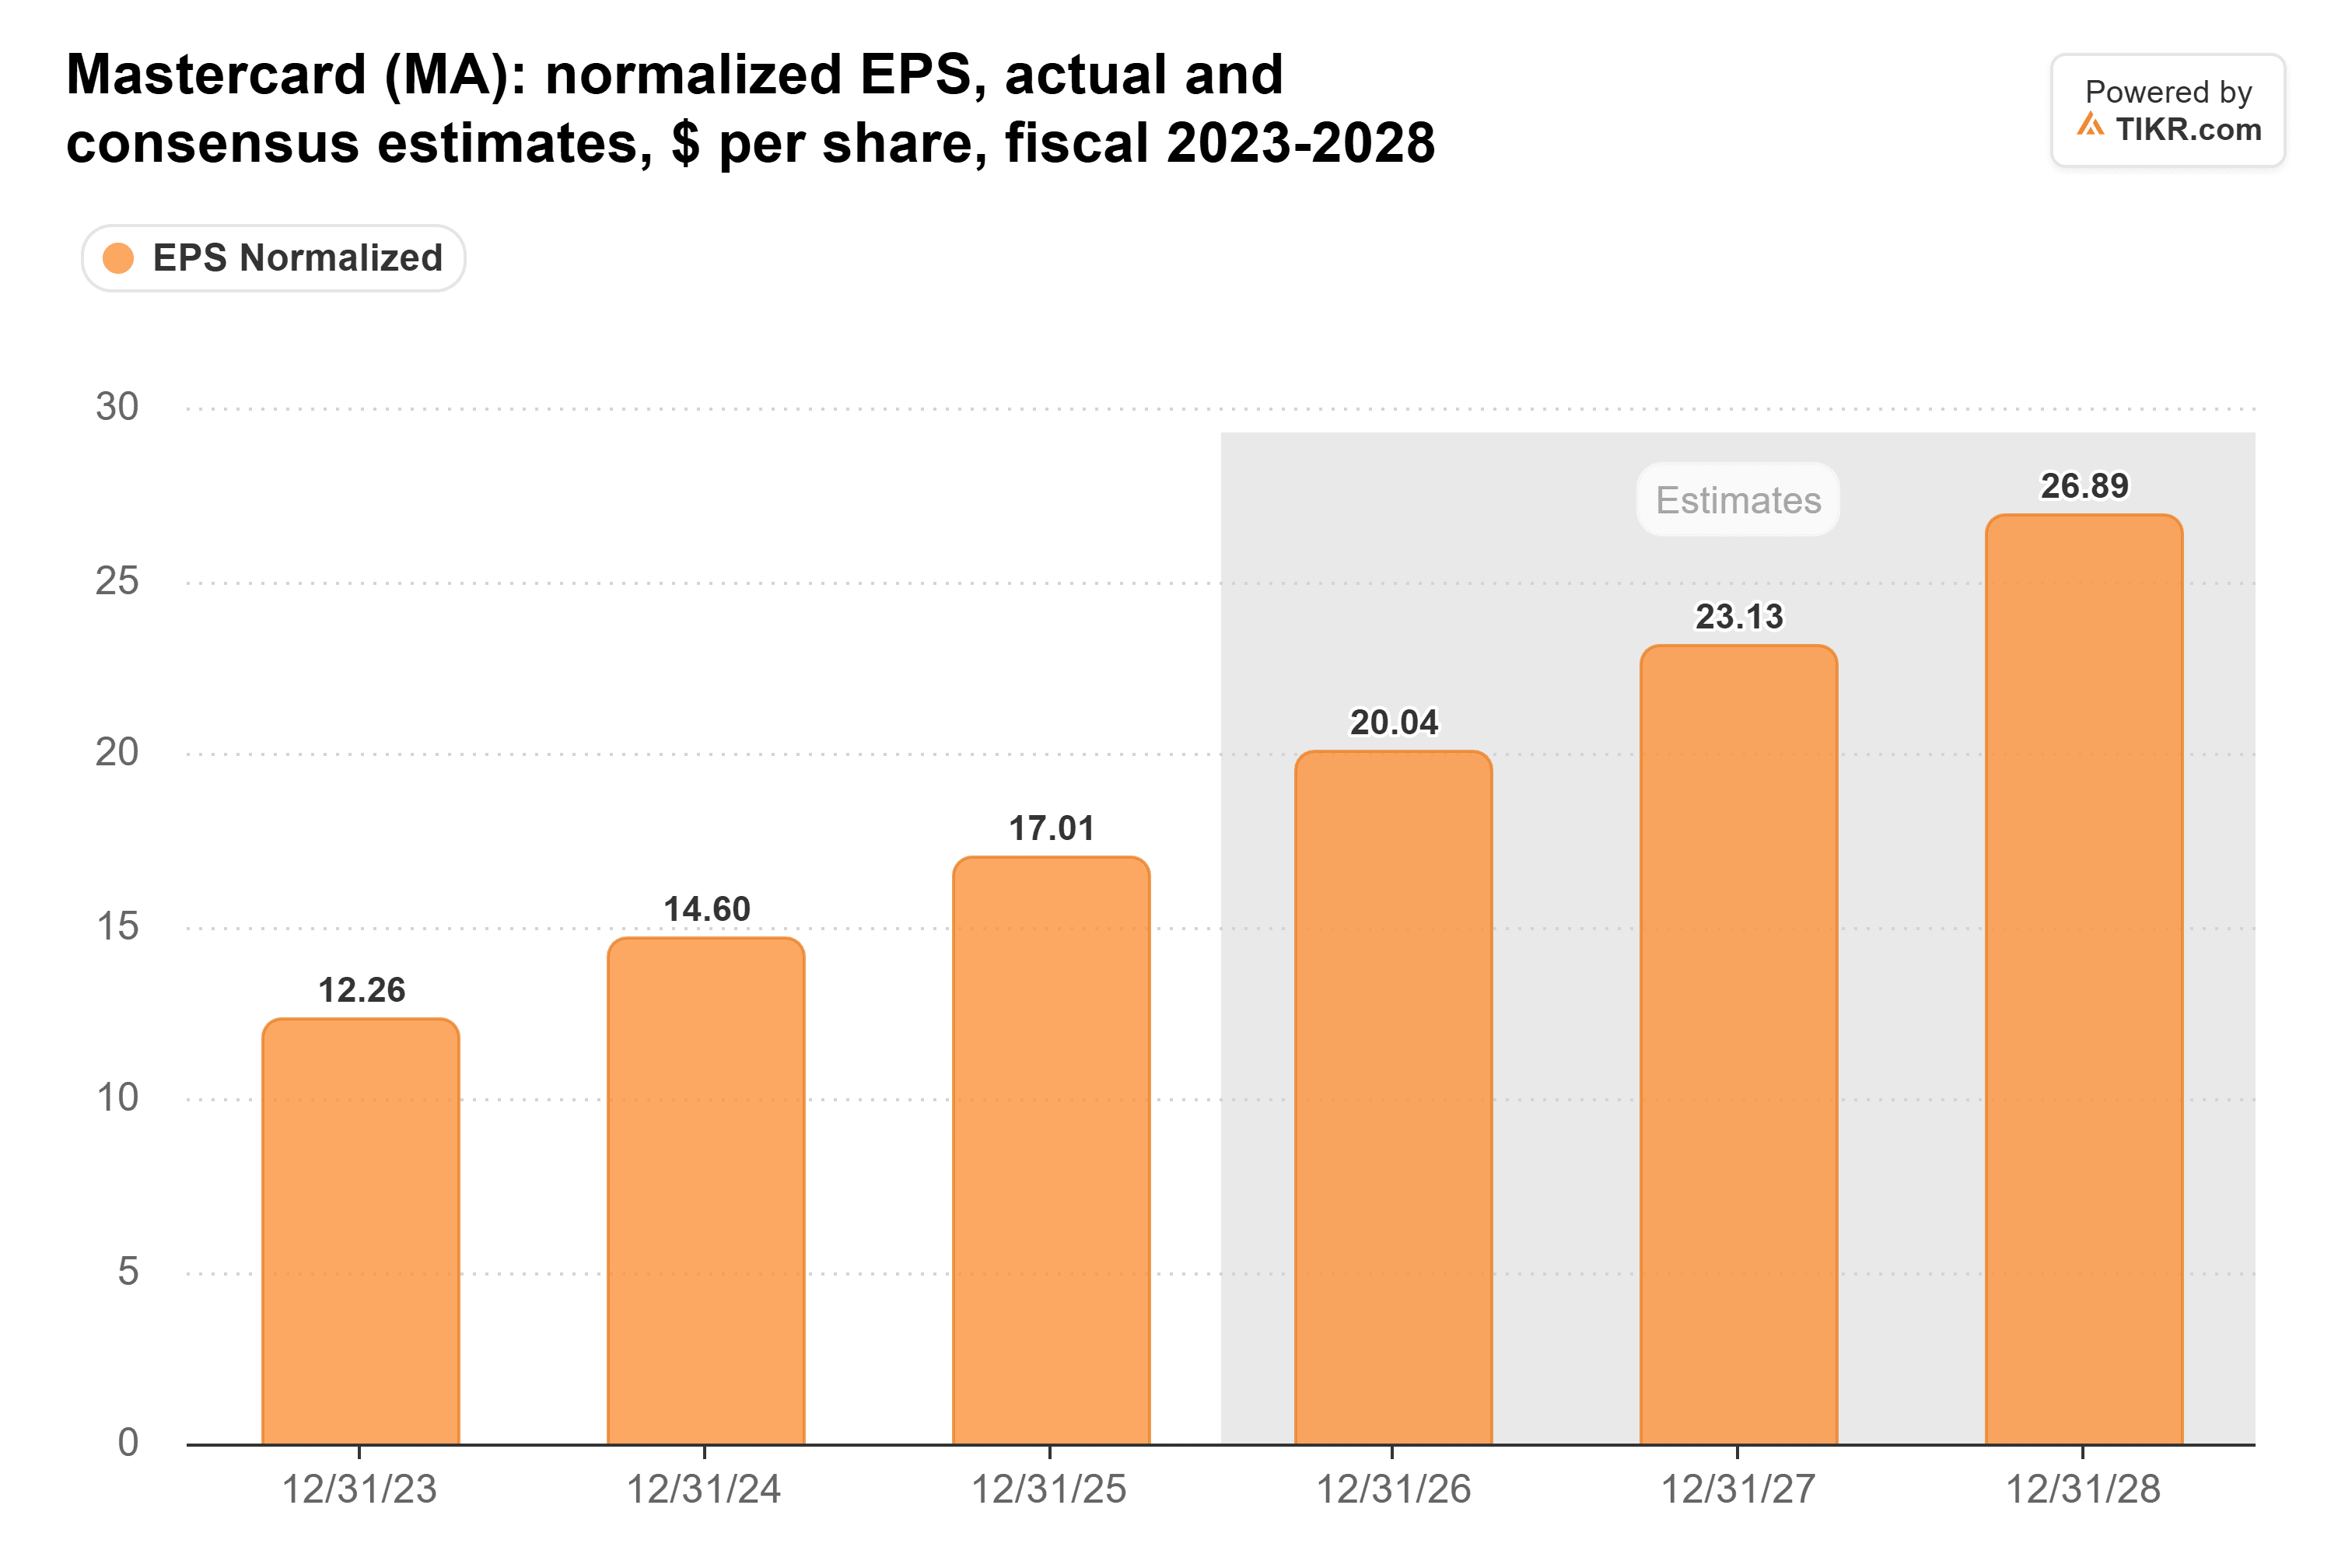
From this year’s expected $20.04, that works out to about 16% a year through 2028.
Visa’s earnings are expected to grow too, from $13.27 in the fiscal year that ended in September to $17.13 in fiscal 2028:

That’s about 14% a year. (Visa’s year ends in September, so the two don’t line up exactly.)
Mastercard’s edge comes from its services and its margins. Q3 net revenue rose 14% to $9.81 billion, and services grew 19% on a currency-neutral basis.
Its adjusted operating margin rose from 58.0% in 2023 to 59.2% in 2025, then reached 61.0% in the first half of 2026. When margins keep rising like that, earnings grow faster than revenue.
The discount Ackman got is gone
Mastercard’s forward P/E bottomed at 23x in June. It’s back to 30x now:

That’s still a bit below its five-year average of 31x, and well short of the 38x it reached in early 2022.
So today’s buyer pays about Mastercard’s usual multiple for earnings that analysts expect to grow in the mid-teens.
That’s a fair price for a business this profitable, but it’s no longer the bargain Ackman got.
Both networks depend on the same shoppers
A royalty on spending is still a bet on spending. If consumers pull back, estimates for both networks will fall together, and Mastercard’s faster growth won’t protect it much.
Mastercard also keeps giving more back to the banks that issue its cards. Rebates and incentives took 52.4% of its gross network fees in Q2 2026, up from 49.9% a year earlier.
New CFO Ling Hai said that share will be higher in Q4 than in Q3.
Ackman has the numbers on his side
Wall Street’s figures back up Ackman’s view of Mastercard. Analysts expect it to grow earnings faster than its closest rival, and the stock still trades a little below its own five-year average multiple.
I’d buy Mastercard at this price, even without Ackman’s low-20s entry point.
Of course, Hai already warned that part of the Q3 beat was pulled forward from Q4. The Q4 report in late January, along with his first full-year outlook for 2027, will show whether that 16% pace holds up.
So what is Mastercard stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Mastercard could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!