Key Takeaways
- Marvell’s all-stock offer for Lumentum was worth $1,132 a share at Marvell’s Oct. 28 price, before talks were reported, and about $550 at Friday’s prices.
- Lumentum CEO Michael Hurlston says the shift from copper to fiber in AI data centers, including Nvidia’s, will drive growth in 2027 and beyond.
- Marvell trades near 22x forward earnings, against a one-year average of 38x, even as analysts expect its EPS to grow 75% next fiscal year.
- Amphenol’s datacom sales are still surging, and Marvell’s early-December report is the first test.
Marvell Technology (MRVL) agreed on Nov. 2 to buy Lumentum (LITE) for $115 billion, paid entirely in Marvell stock. Marvell’s shares closed at $122.28 on Nov. 20, down 51% from their Oct. 28 close, and the deal’s price tag fell with them.
Lumentum’s CEO doesn’t sound worried. On Mad Money this week, Michael Hurlston told Jim Cramer:
“The laws of physics are working in favor of fiber, and they’re working in favor of the technology we have.”
That’s a bet on what goes inside NVIDIA (NVDA) data centers, where copper connections from suppliers like Amphenol (APH), whose third-quarter sales jumped 65%, still dominate. For anyone buying Marvell today, that bet just got a lot cheaper.
A $1,132 Offer for Lumentum, Now Worth About $550
Lumentum holders get 4.5 Marvell shares for each share they own. At Marvell’s Oct. 28 close, before talks were reported, that was worth $1,132 a share, a 24% premium to Lumentum’s $914 close that day. At Friday’s close it’s worth about $550, and Lumentum trades 16% below that, at $460.54.
The exchange ratio hasn’t budged, though. Since Marvell’s stock now sets Lumentum’s price, a Marvell share bought today buys into Lumentum’s business far more cheaply than in late October.
Lumentum Is Nearly Sold Out for 2029
Lumentum’s business is heading the other way. Cramer said its CEO “says some products are already nearly sold out for 2029.” September-quarter revenue jumped 136.5% to $1.26 billion, and Lumentum has guided the December quarter to about $1.6 billion.
Hurlston’s bigger lever is “that content shift from copper into the optical domain.” Analysts expect revenue to more than double, from fiscal 2026’s $3.01 billion to $6.66 billion this fiscal year:
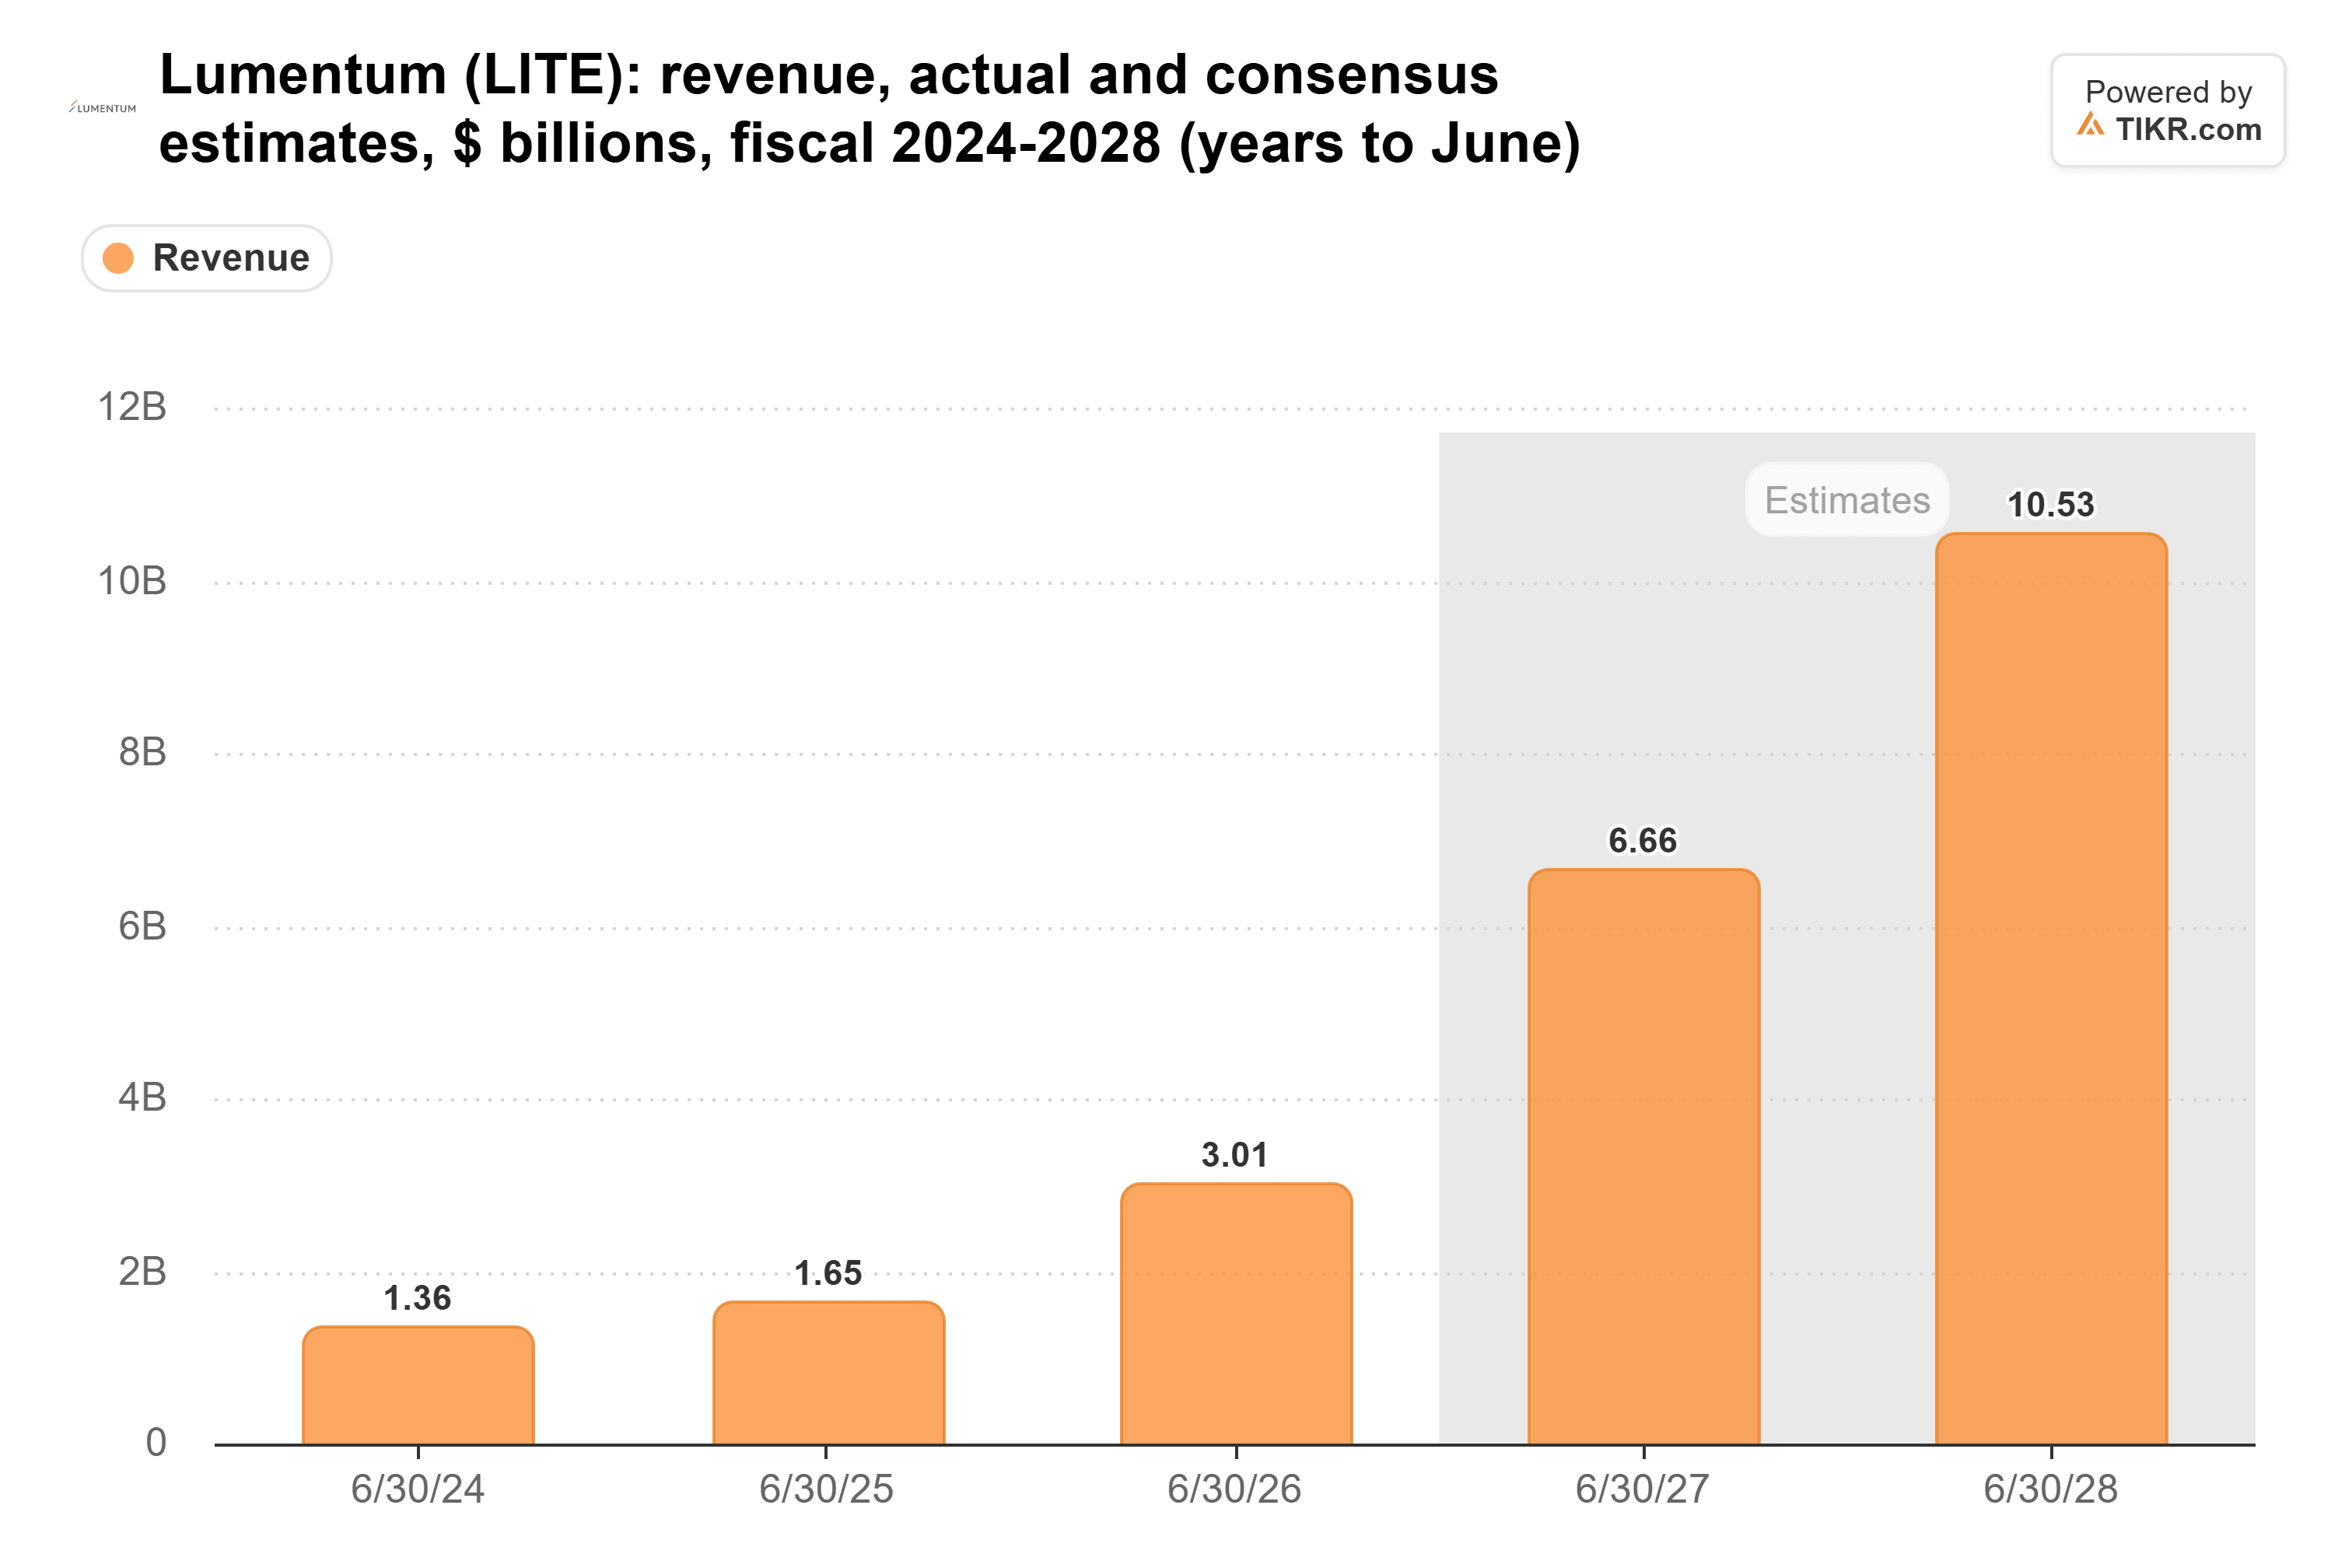
Getting to $6.66 billion takes about $1.9 billion a quarter in the back half of the year, a step up from December’s $1.6 billion guide.
TIKR Tracks 25 Analysts on Lumentum. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Lumentum, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Lumentum’s Analyst Ratings
Marvell’s Estimates Held Up
Hurlston promises shareholders waiting on the close “tremendous EPS uplift.” Even before counting Lumentum, analysts expect Marvell’s normalized EPS to climb from $2.84 in fiscal 2026 to $4.22 in the year ending January 2027, and $7.37 the year after:
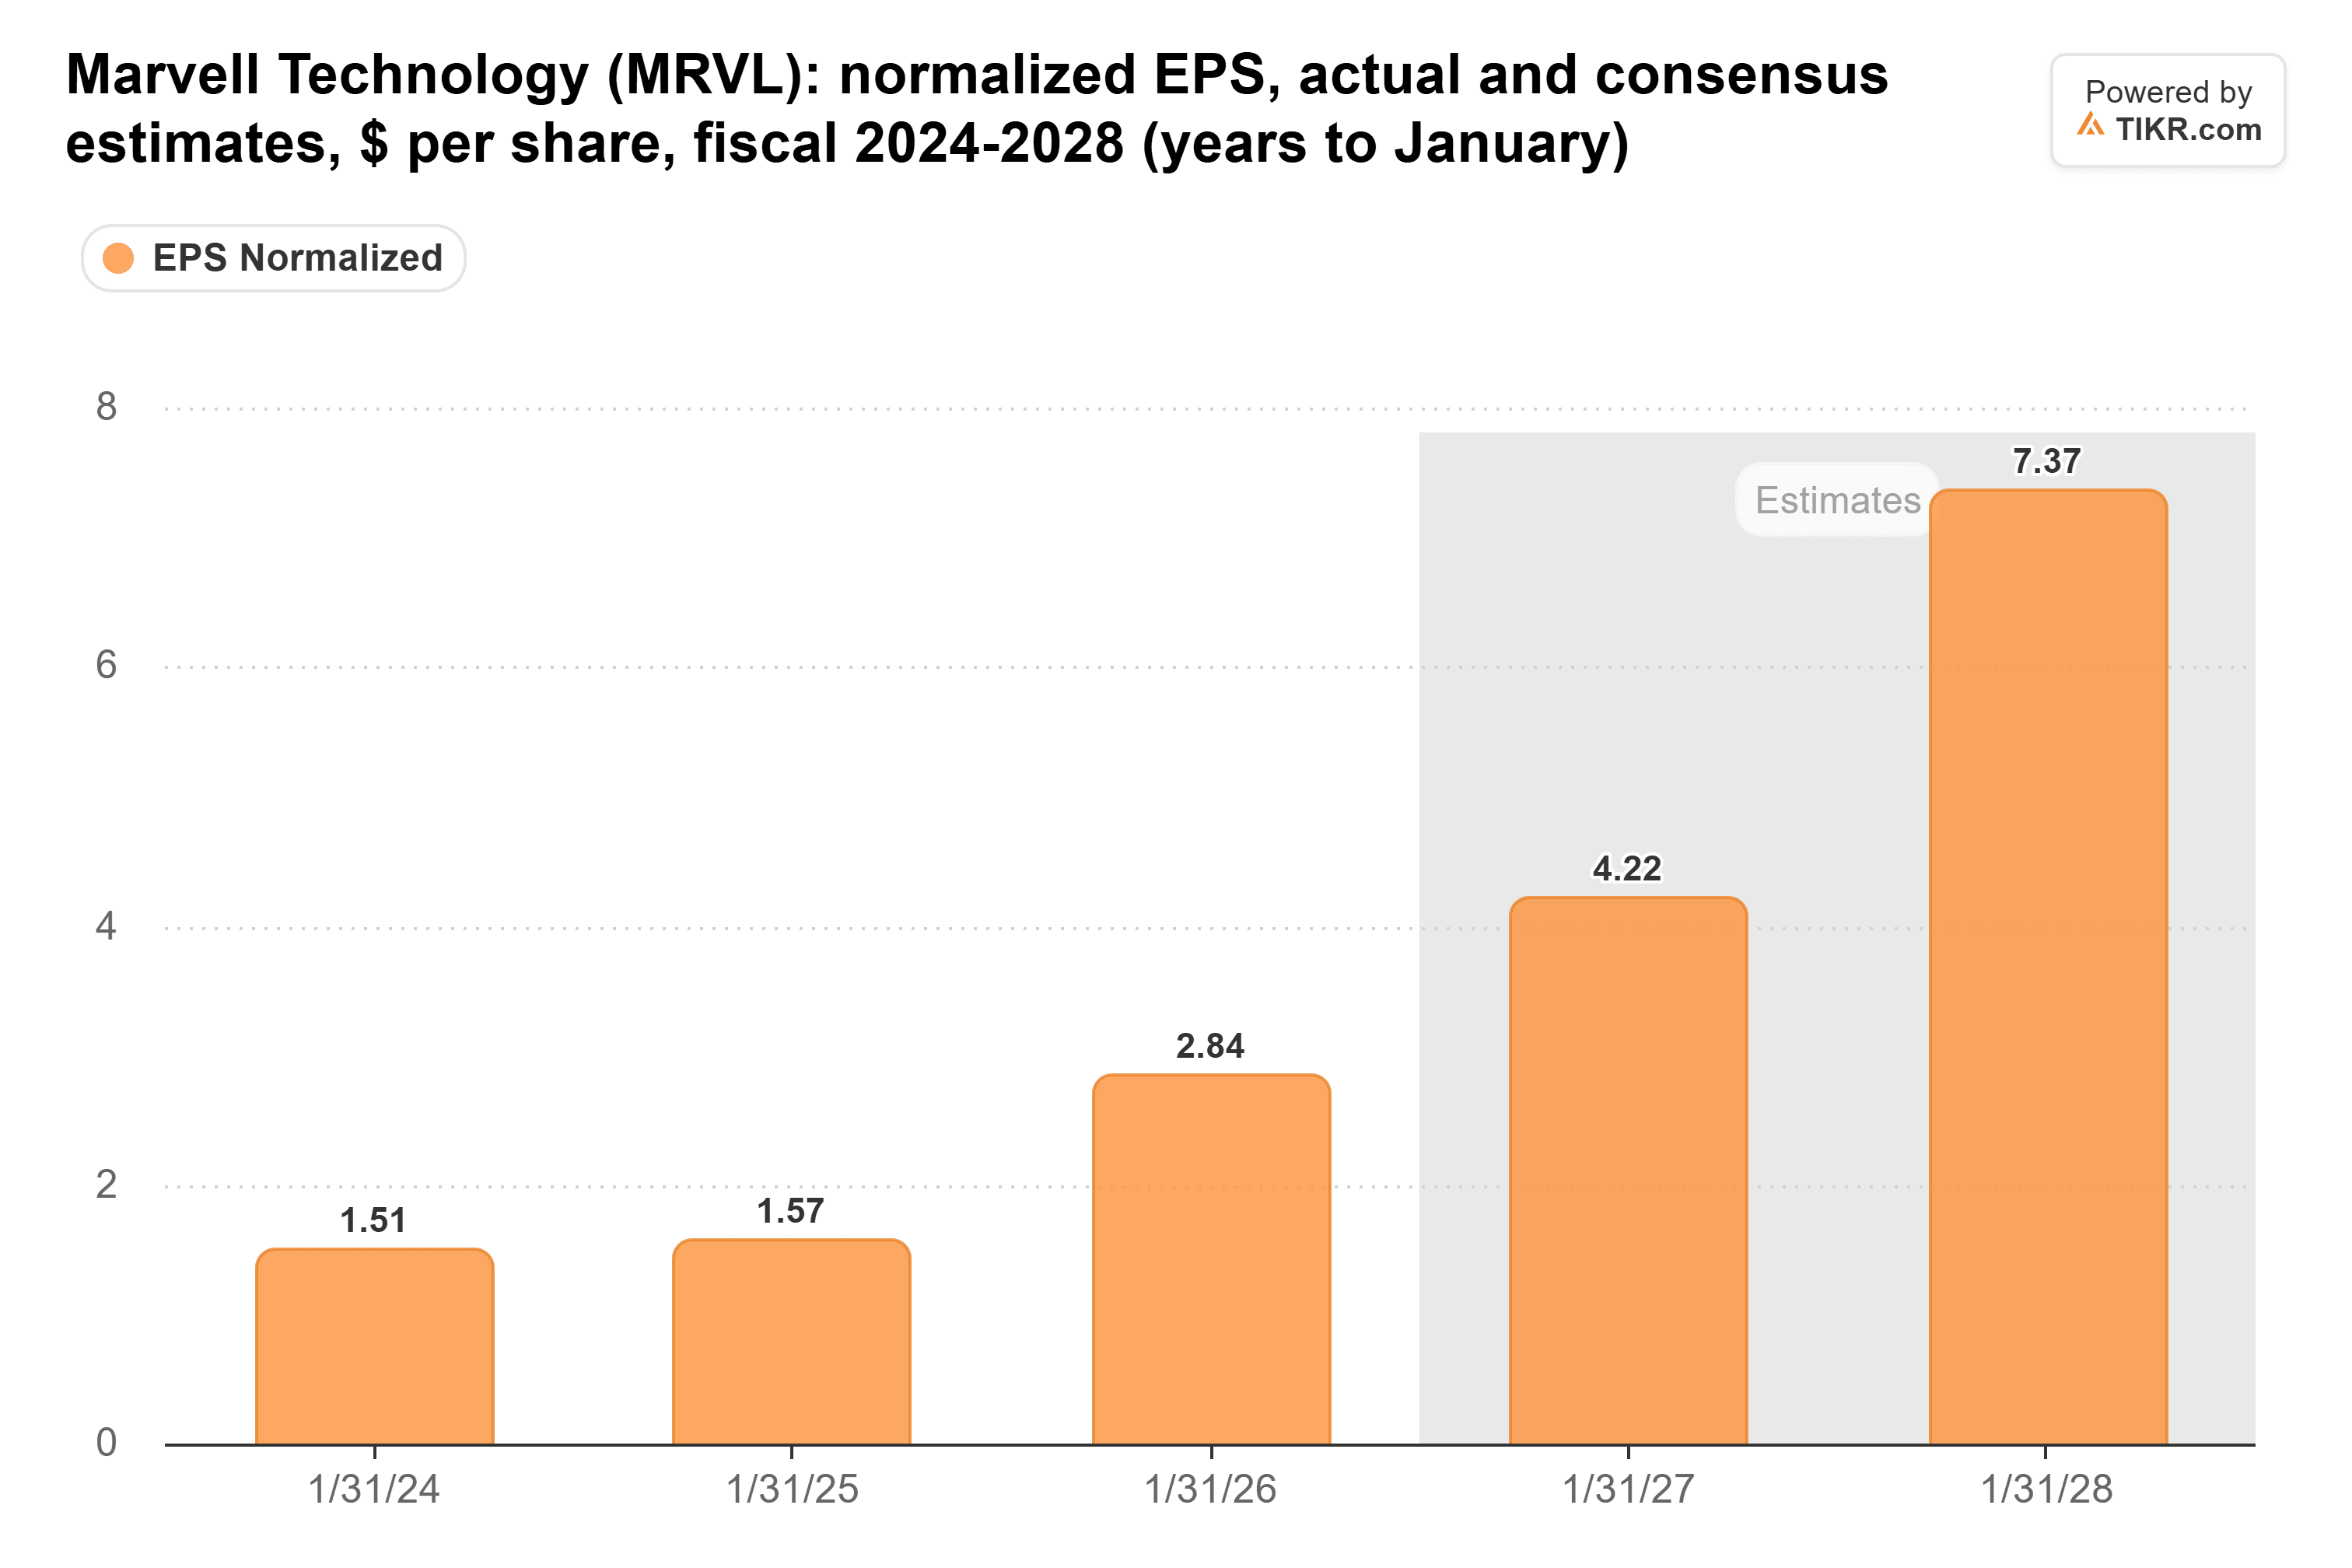
Investors are paying a lot less for those earnings. Marvell traded at 24.6x forward earnings at Thursday’s close, against a one-year average of 37.9x and a June high of 69.7x:
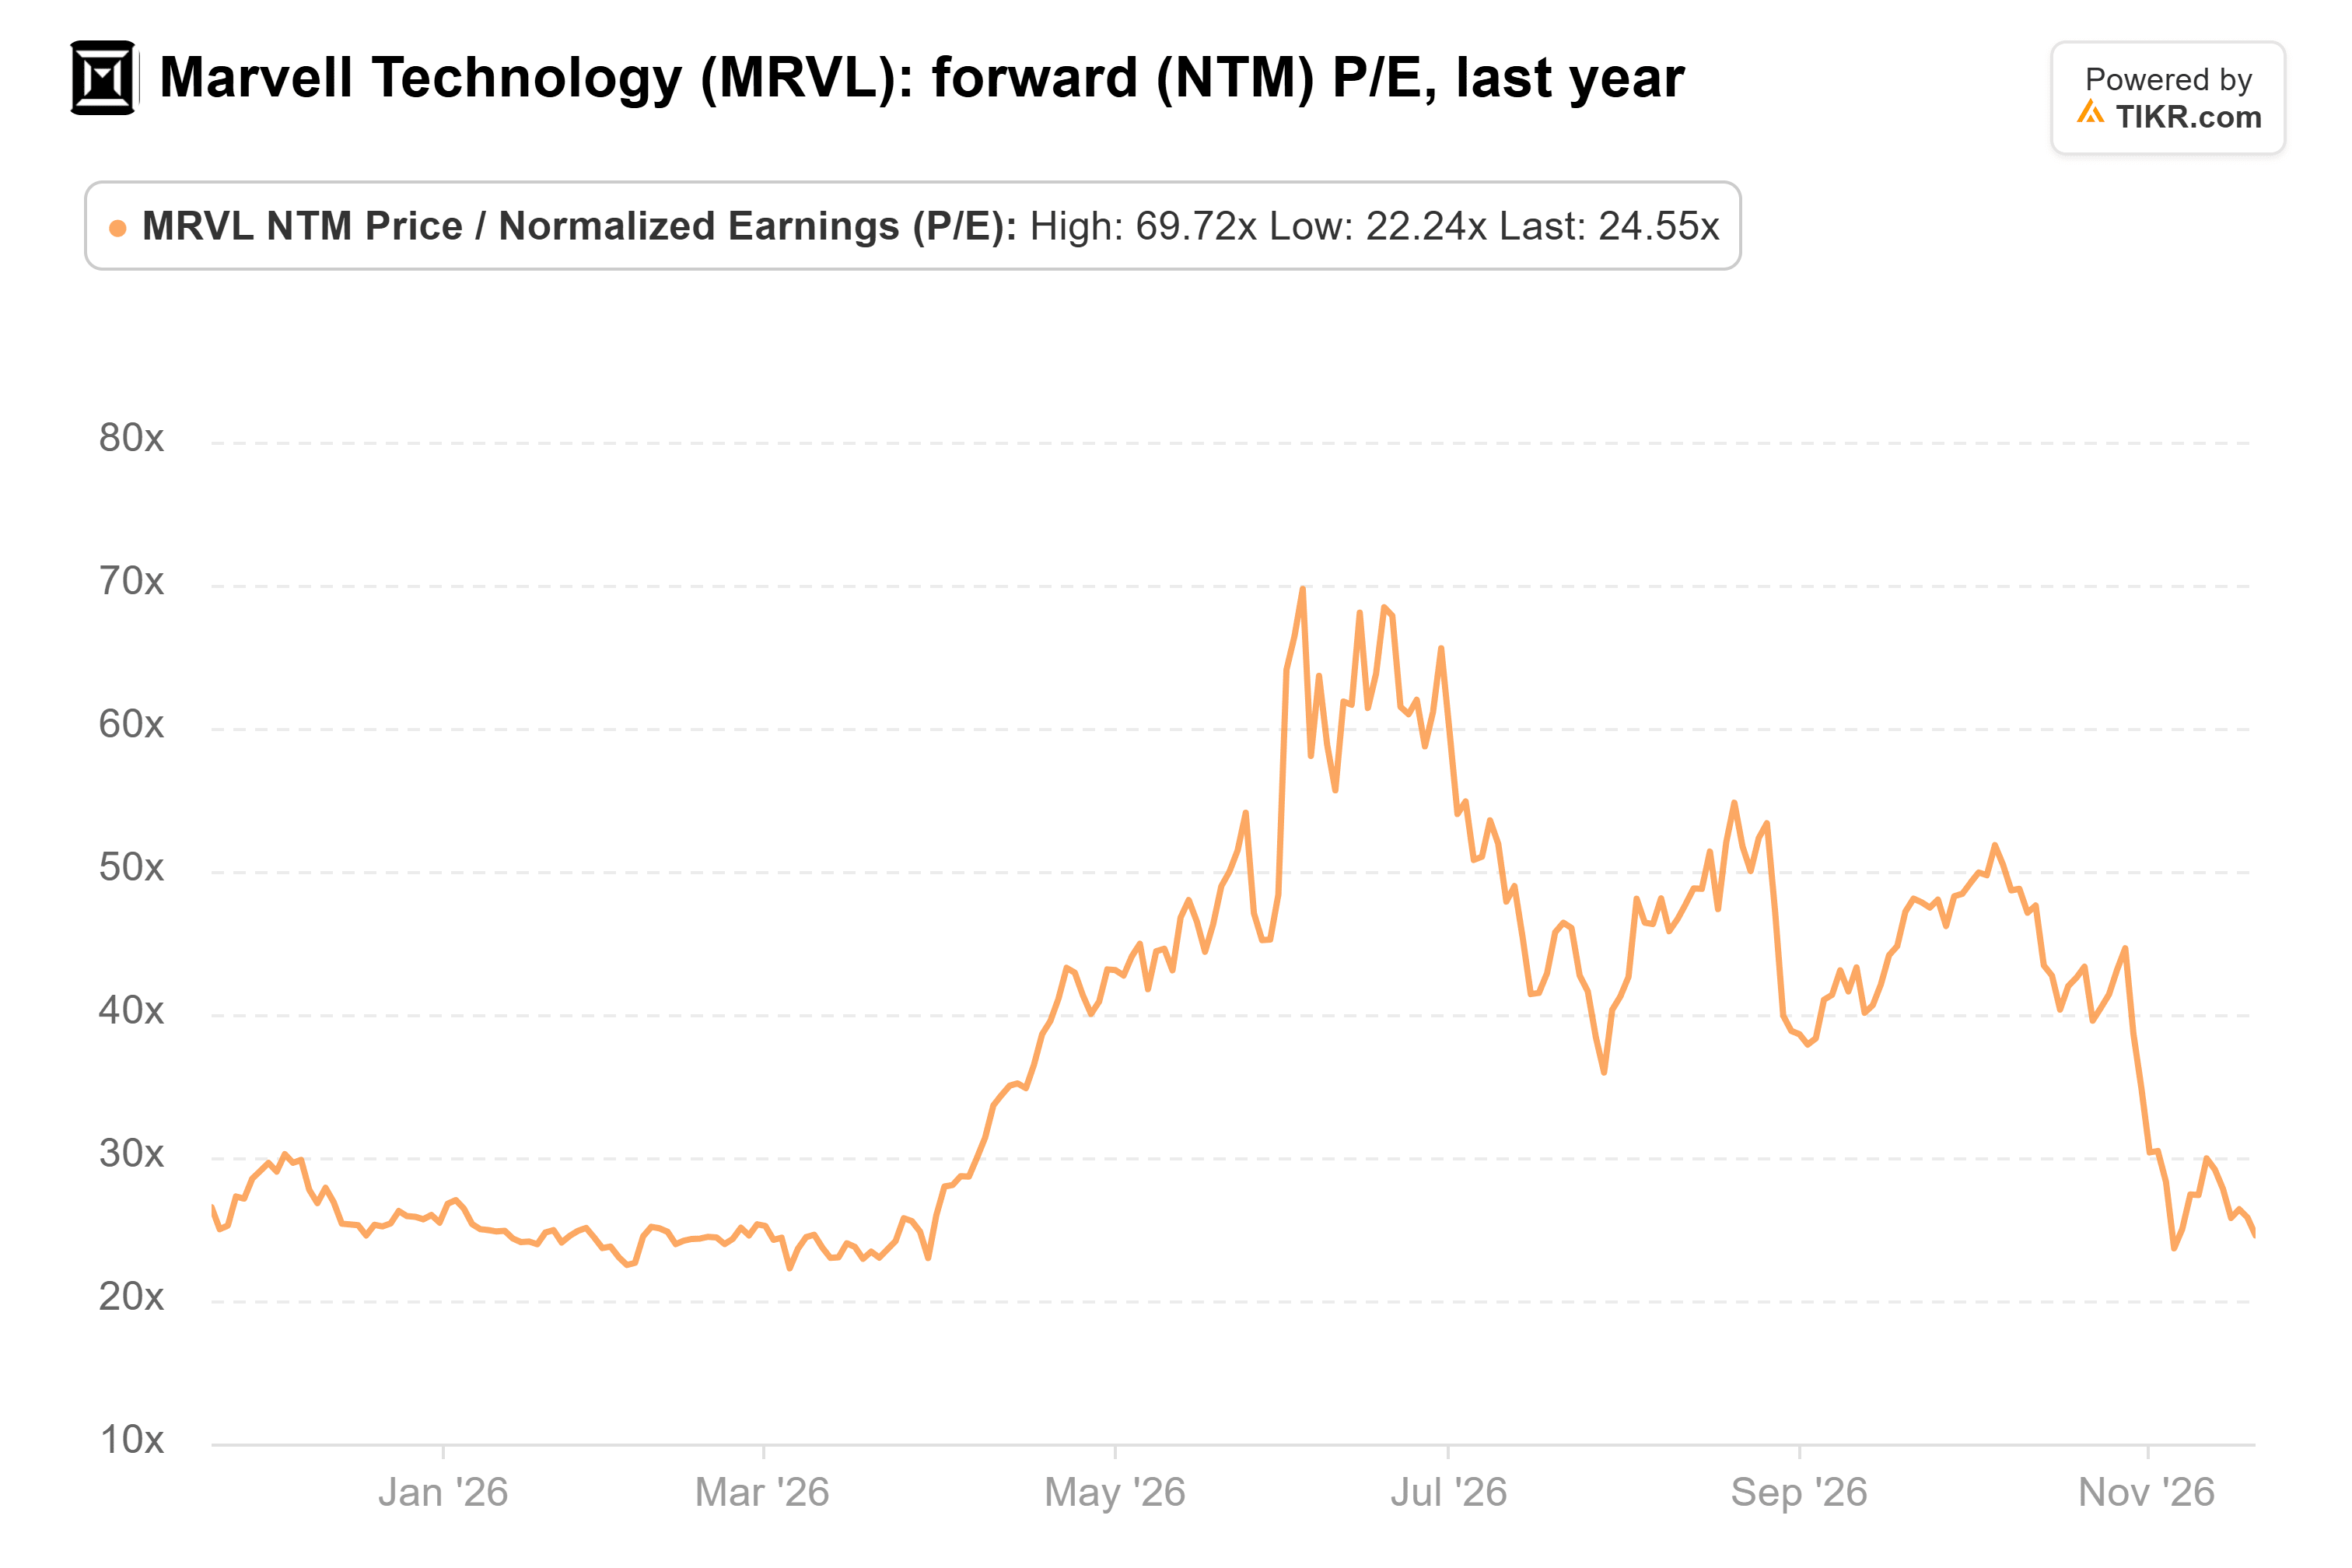
At Friday’s $122.28, the same estimates put it near 22x.
Copper Still Has a Cost Edge
Hurlston admits copper is cheaper: “even NVIDIA said, hey, if we had the choice, we’d keep copper in as long as we can.” At these speeds, he argues, NVIDIA doesn’t get the choice.
Copper’s suppliers aren’t slowing yet. Amphenol’s third-quarter sales jumped 65% to $10.2 billion, up 37% organically, on what CEO Adam Norwitt called “continued exceptional organic growth in the IT datacom market.” Analysts expect its normalized EPS to grow about 27% in 2027.
A Cheaper Way Into Marvell, With a Long Wait
The way I see it, today’s Marvell buyers are getting the better end of this selloff: Marvell’s own growth, with Lumentum’s thrown in, at a multiple well below its one-year average.
There are catches. Lumentum’s 53.2% non-GAAP gross margin last quarter sits below Marvell’s guide, the 4.5-for-1 share issue dilutes Marvell holders, and the deal isn’t expected to close until the first half of 2028. It still needs regulators’ approval, China’s included. If they block it, Marvell owes Lumentum a $3.2 billion fee.
The first test comes in early December, when Marvell reports a quarter it guided to $3.15 billion of revenue, give or take 5%. Hitting that, with non-GAAP gross margin inside the 57.5%-58.5% guide, would back Hurlston’s call that Marvell is going to “really, really surprise.”
So What Is Marvell Stock Actually Worth If the Deal Doesn’t Go Through?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!