


Key Takeaways
- A $6.6 billion fund’s three biggest buys of the third quarter were Meta Platforms, US Foods and Burlington Stores, its latest 13F shows.
- Analysts’ average targets sit 51% above Meta’s price and 42% above Burlington’s, but only 11% above US Foods, which trades near its high.
- Meta’s spending now outruns its operating cash flow, and Burlington guided its third quarter below what analysts expected.
- At about 17x forward earnings, well below its five-year average, Meta is the one the numbers back best.
Dorsal Capital Management’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows eight stocks it bought or added to. The three biggest were Meta Platforms (META), US Foods (USFD) and Burlington Stores (BURL), and right now they couldn’t look much more different.
The firm manages $6.64 billion in all, and its 13F holds $2.86 billion of US stocks across just 20 positions. So each of these three is a real bet.
Meta’s ads are still growing fast
The fund added 27% to its Meta stake in the third quarter, ending the quarter with 280,000 shares worth $203 million. That’s 7.1% of its 13F stocks and its fourth-largest position. Meta is down 23% since Sept. 30.
Its ad business grew revenue 26% to $64.6 billion in the third quarter, with price per ad up 14%. But Meta’s spending has outrun its cash: capex of $34.9 billion topped operating cash flow of $32.8 billion in the quarter, and analysts now have free cash flow bottoming at negative $48 billion in 2027. That’s why the stock trades at about 17x forward earnings, against a five-year average of 21.4x.
Analysts’ average target has barely moved, from $840 a year ago to $848 now:
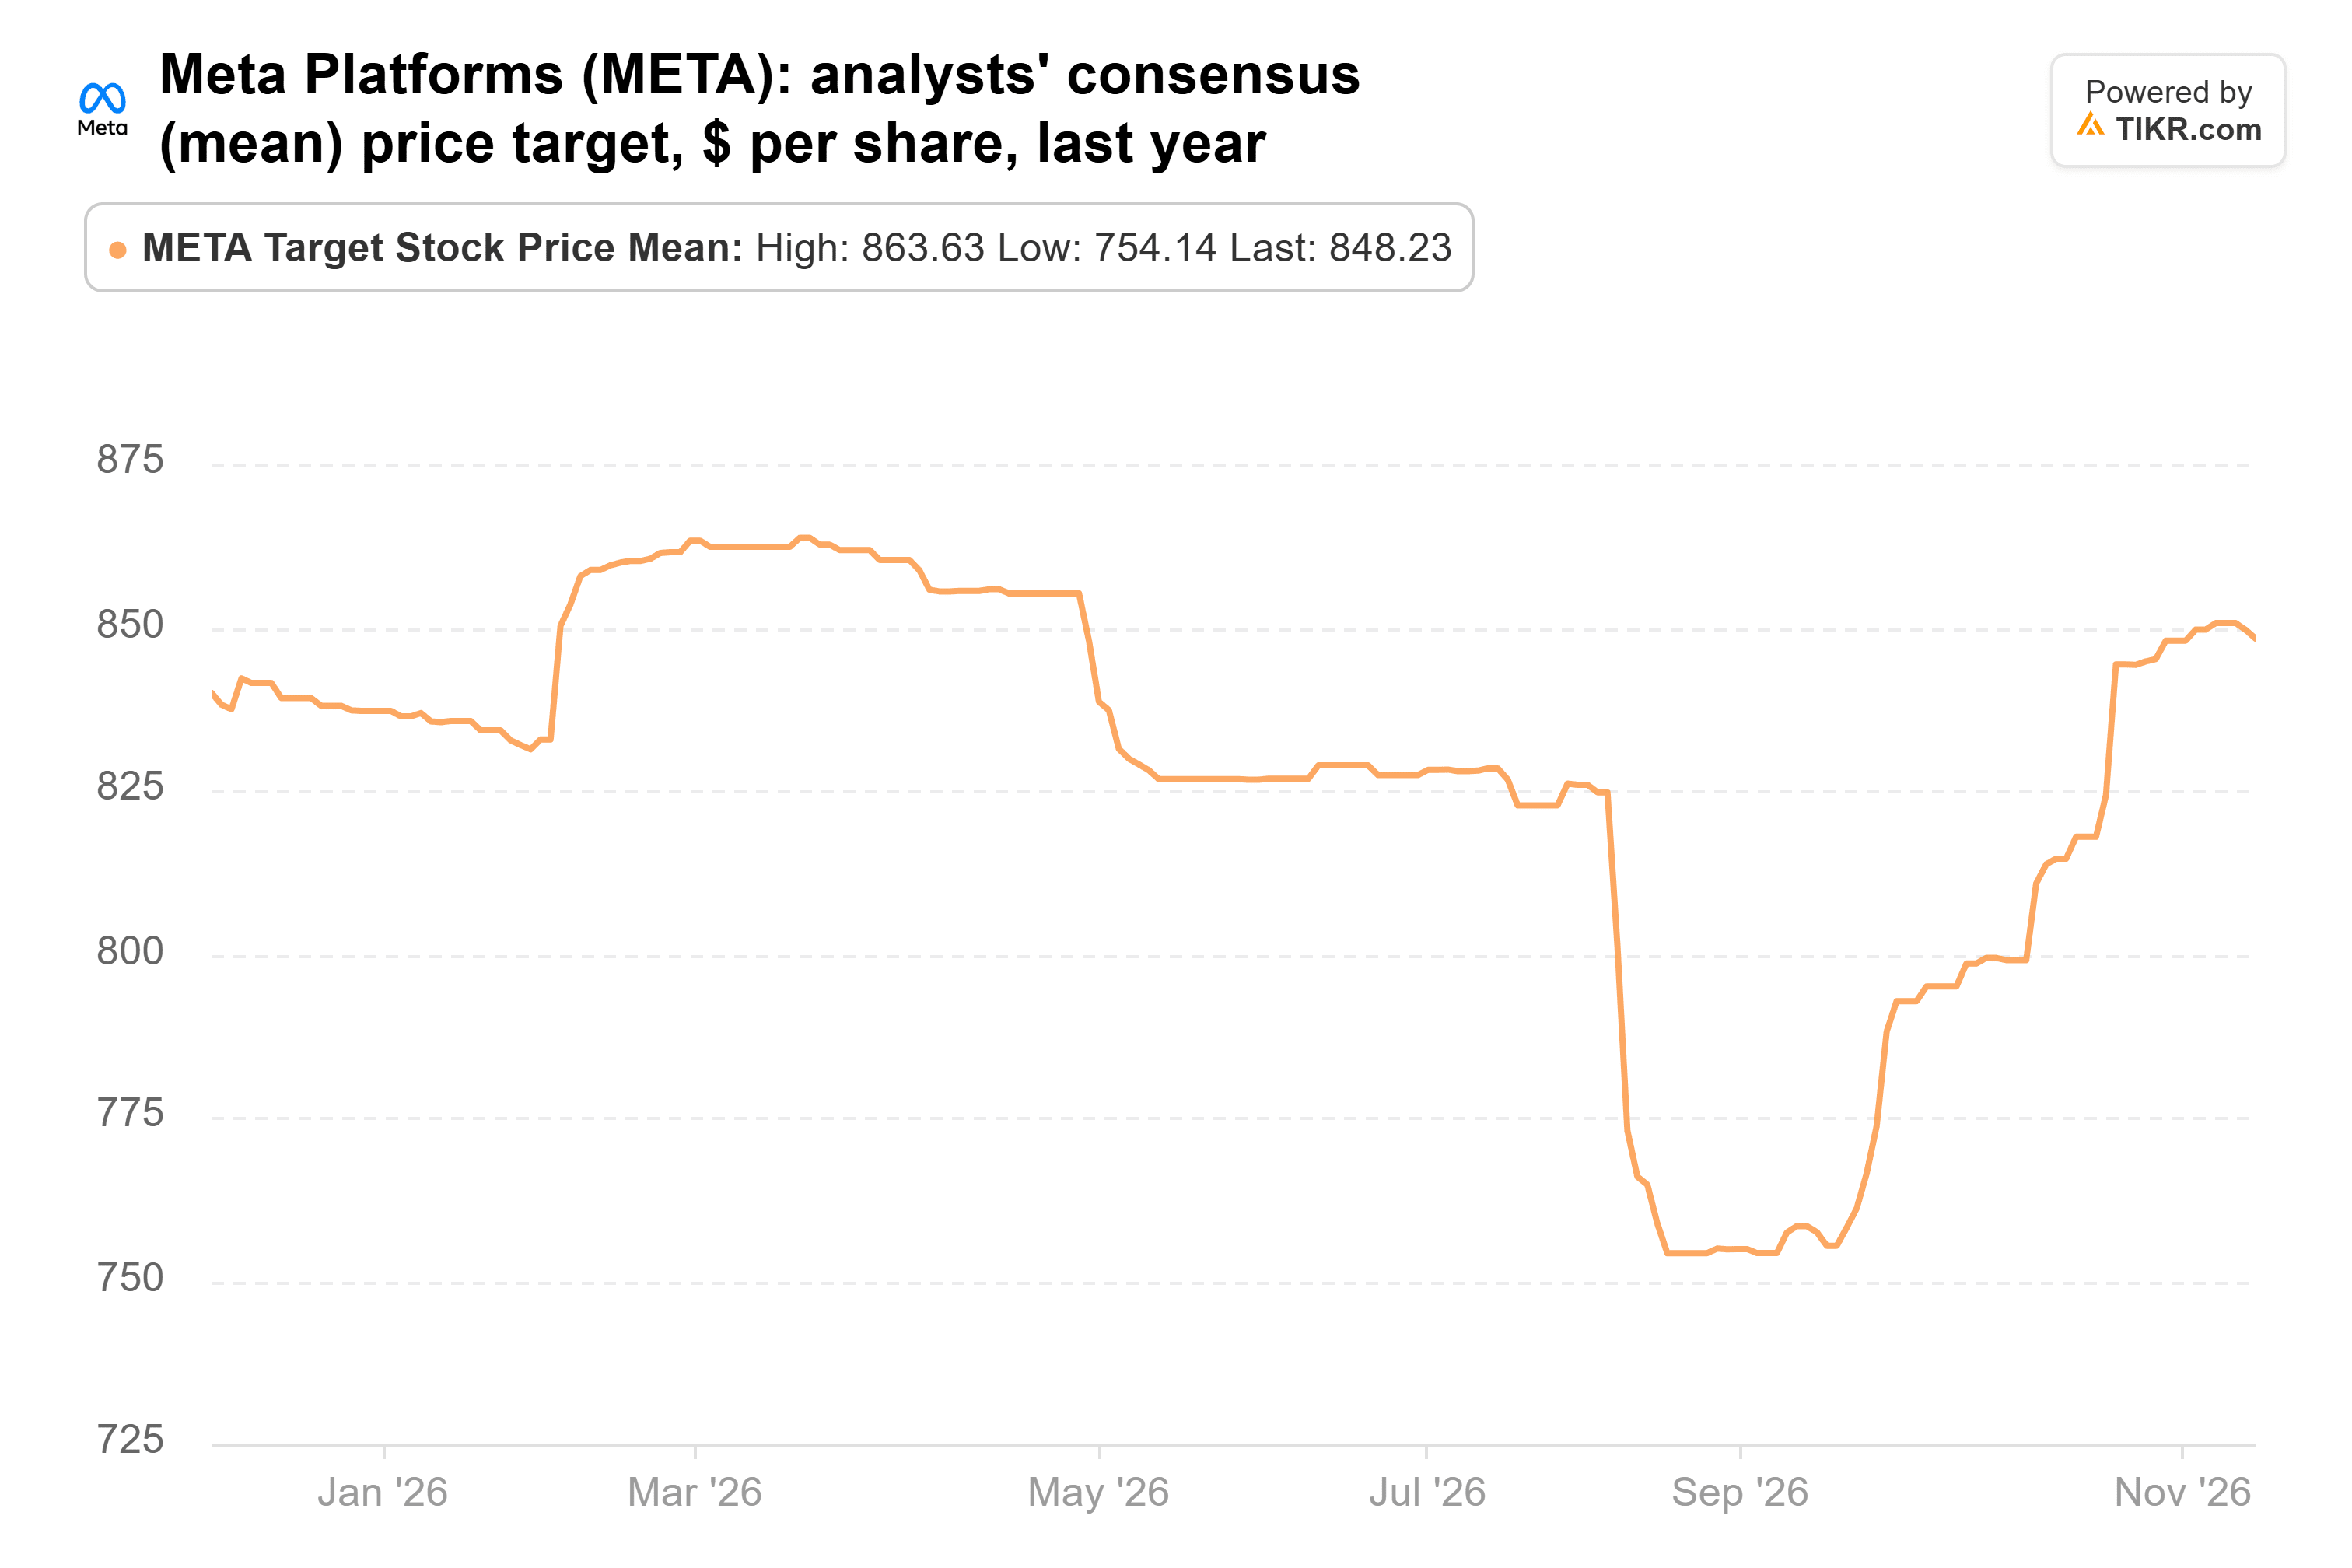
That’s 51% above the stock, with targets running from $650 to $1,050.
TIKR tracks 62 analysts on Meta Platforms. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Meta Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Meta Platforms’ Analyst Ratings
US Foods keeps winning independent restaurants
US Foods got the biggest add of the three. The fund raised its share count 533% in the third quarter, to 1.90 million shares worth $175 million by Sept. 30, or 6.1% of its 13F stocks. The stock is up 16% since then.
The business has earned that. In its fiscal third quarter, case volume from independent restaurants rose 5.0% while chain volume fell 1.5%, and adjusted EPS jumped 17.8% to $1.26. US Foods also bought back $191 million of stock in the quarter and now guides adjusted EPS growth of 18% to 20% for the year.
Analysts have been chasing it. Their average target climbed from $91 a year ago to $119, its high for the year:

Even so, that’s just 11% above the stock, which trades at about 20x forward earnings and 5% below its 52-week high. US Foods is executing well, and investors have already paid up for it.
Burlington has a lot riding on its next report
The fund added 20% to its Burlington stake, ending the quarter with 600,000 shares worth $160 million, or 5.6% of its 13F stocks. The stock is down 8% since Sept. 30 and sits 35% below its 52-week high.
Burlington’s second quarter, ended Aug. 1, was strong on profit: sales rose 11% to $3.0 billion, adjusted EPS jumped 38% to $2.37, and management raised its full-year adjusted EPS guidance to $11.77-$11.97 from $11.45-$11.80. But comparable store sales rose just 2%, and its third-quarter guidance for adjusted EPS of $1.60-$1.70 came in below what analysts expected. Burlington also plans to spend $55 million of tariff refunds on lower prices for shoppers.
The average target peaked at $387 on Aug. 27, and analysts have trimmed it to $350 since:
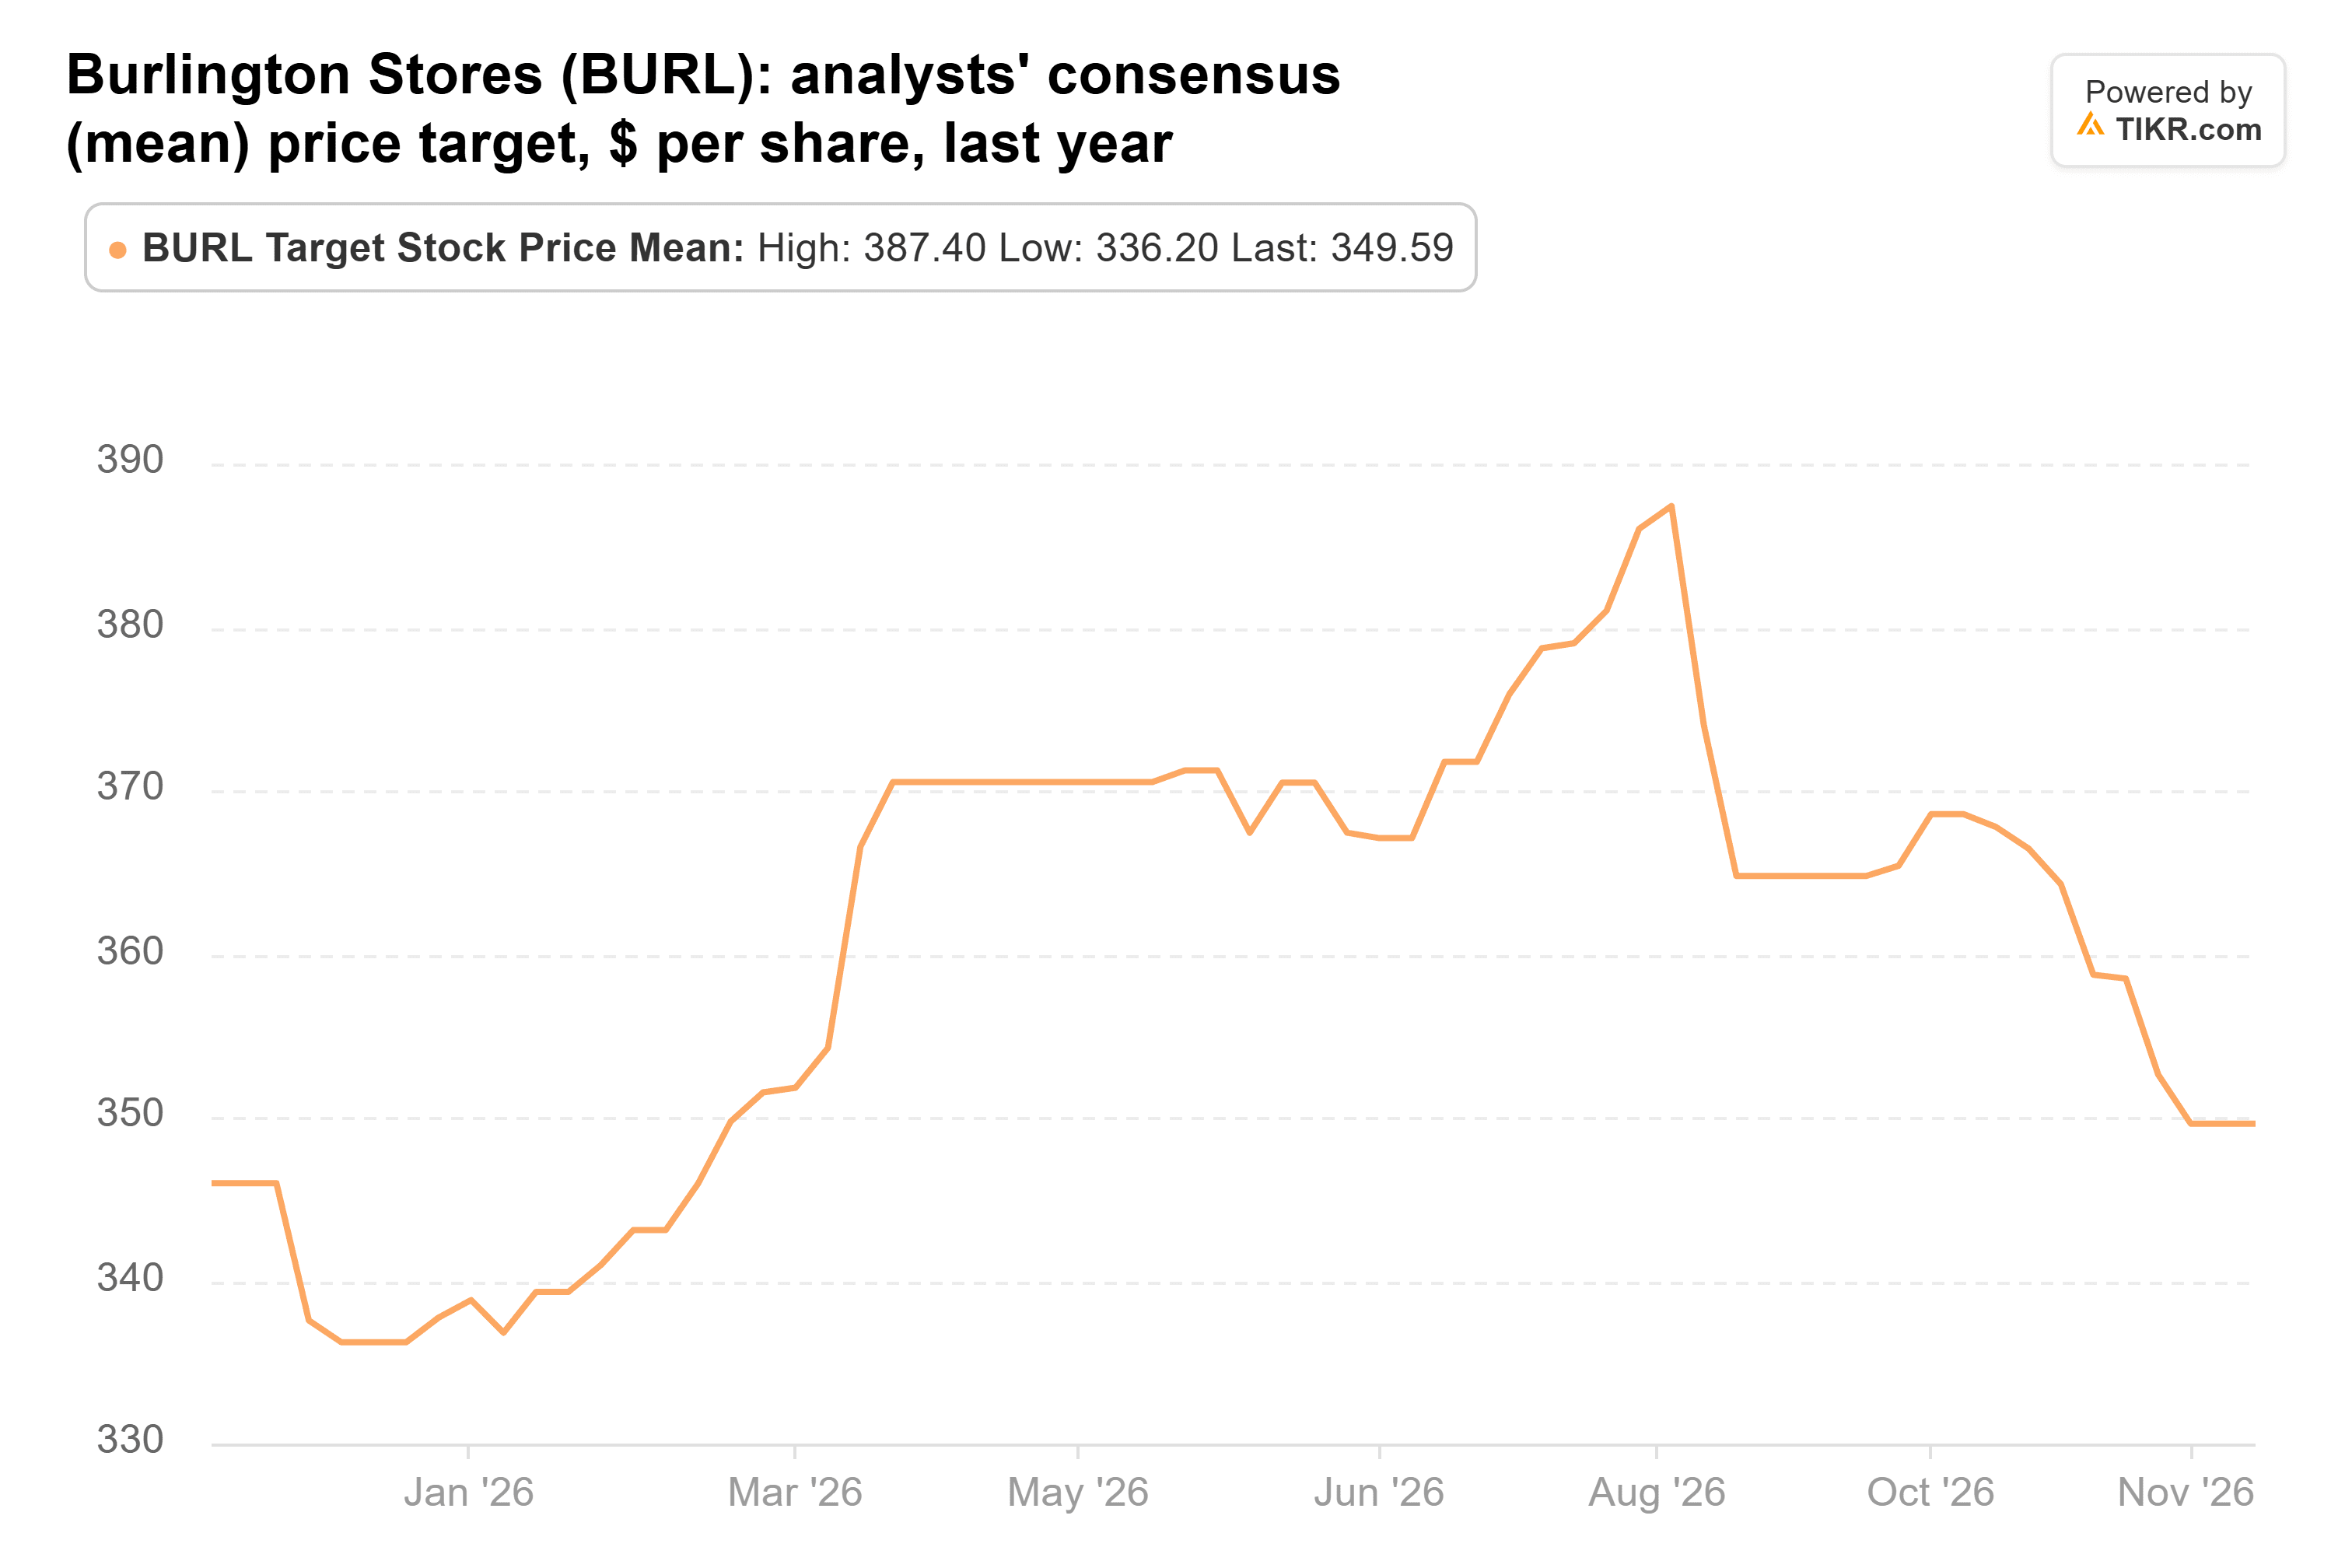
That’s still 42% above the stock, at about 20x forward earnings. But the lowest target on the Street was cut to $240 on Nov. 13, just below where Burlington trades.
Meta is the one I’d buy
If I could only buy one of the three right now, it’d be Meta. On analysts’ 2028 normalized EPS estimate of $40.42, the $848 average target works out to about 21x, right around Meta’s five-year average. So the target needs no re-rating, only for estimates to hold, and you’re paying about 17x forward earnings for an ad business still growing 26%.
The risk is a 2027 capex plan well above the roughly $210 billion analysts expect, which would push free cash flow even further below zero. Meta lays out that plan on its fourth-quarter call in late January, along with revenue against its $73 billion to $76 billion guide. Revenue in the top half of that range, with capex near consensus, would make the fund’s add look smart. Its next 13F, due in mid-February, will show whether it held on.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!




