Key Takeaways
- Clorox yields 4.6% and Kinder Morgan yields 3.8%, so $10,000 pays $460 a year in Clorox today and $380 in Kinder Morgan.
- Clorox’s dividend took a stretched 133% of its free cash flow over the twelve months to Sept. 30, 2026, and analysts expect that to ease to about 74% in fiscal 2027.
- Kinder Morgan’s distributable cash flow covered its dividend a comfortable 2.1x in 2025, and the company has a record $14.4 billion project backlog.
- At their five-year growth rates, $10,000 in Clorox would pay about $1,781 more than Kinder Morgan over 20 years, as long as its dividend keeps growing.
Even after a 24% run in the 10 trading days to Nov. 13, Clorox (CLX) still yields 4.6%. Part of that run came on Nov. 11, from unconfirmed rumors of a takeover offer at $125-$130 a share. That’s a big check from a company whose dividend cost more than its free cash flow over the past year, and whose CEO steps down in January.
Kinder Morgan (KMI) pays less, at 3.8%. But on Oct. 21, it reported record third-quarter results and its largest natural gas project backlog ever.
So if I could only own one of these dividends for the next 20 years, which one would it be?
| Metric | Clorox (CLX) | Kinder Morgan (KMI) |
|---|---|---|
| Dividend yield | 4.6% | 3.8% |
| Dividend growth, 5 years | 2.0% a year (fiscal 2021-2026) | 2.2% a year (fiscal 2020-2025) |
| Coverage measure | Cash dividend payout ratio | Distributable cash flow coverage |
| Coverage, last reported | 133% (TTM to Sept. 30, 2026) | 2.1x (fiscal 2025) |
| Coverage, forward | 74% (fiscal 2027 consensus) | 2.4x (fiscal 2026 consensus) |
| Net debt / EBITDA | 3.8x | 4.1x |
| Interest coverage | 6.5x | 3.0x |
Source: TIKR. Yields at today’s prices.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Clorox needs its margins back
Clorox’s sales are growing. In the first quarter of fiscal 2027, which ended Sept. 30, net sales rose 33% to $1.91 billion, helped by its GOJO acquisition. But gross margin fell 130 basis points to 40.4% on higher commodity, manufacturing and logistics costs. Clorox now expects a fiscal 2027 gross margin of about 41.5%. On Oct. 29, its board also named Fabian Garcia CEO, effective Jan. 5, 2027, as Linda Rendle steps down for health reasons.
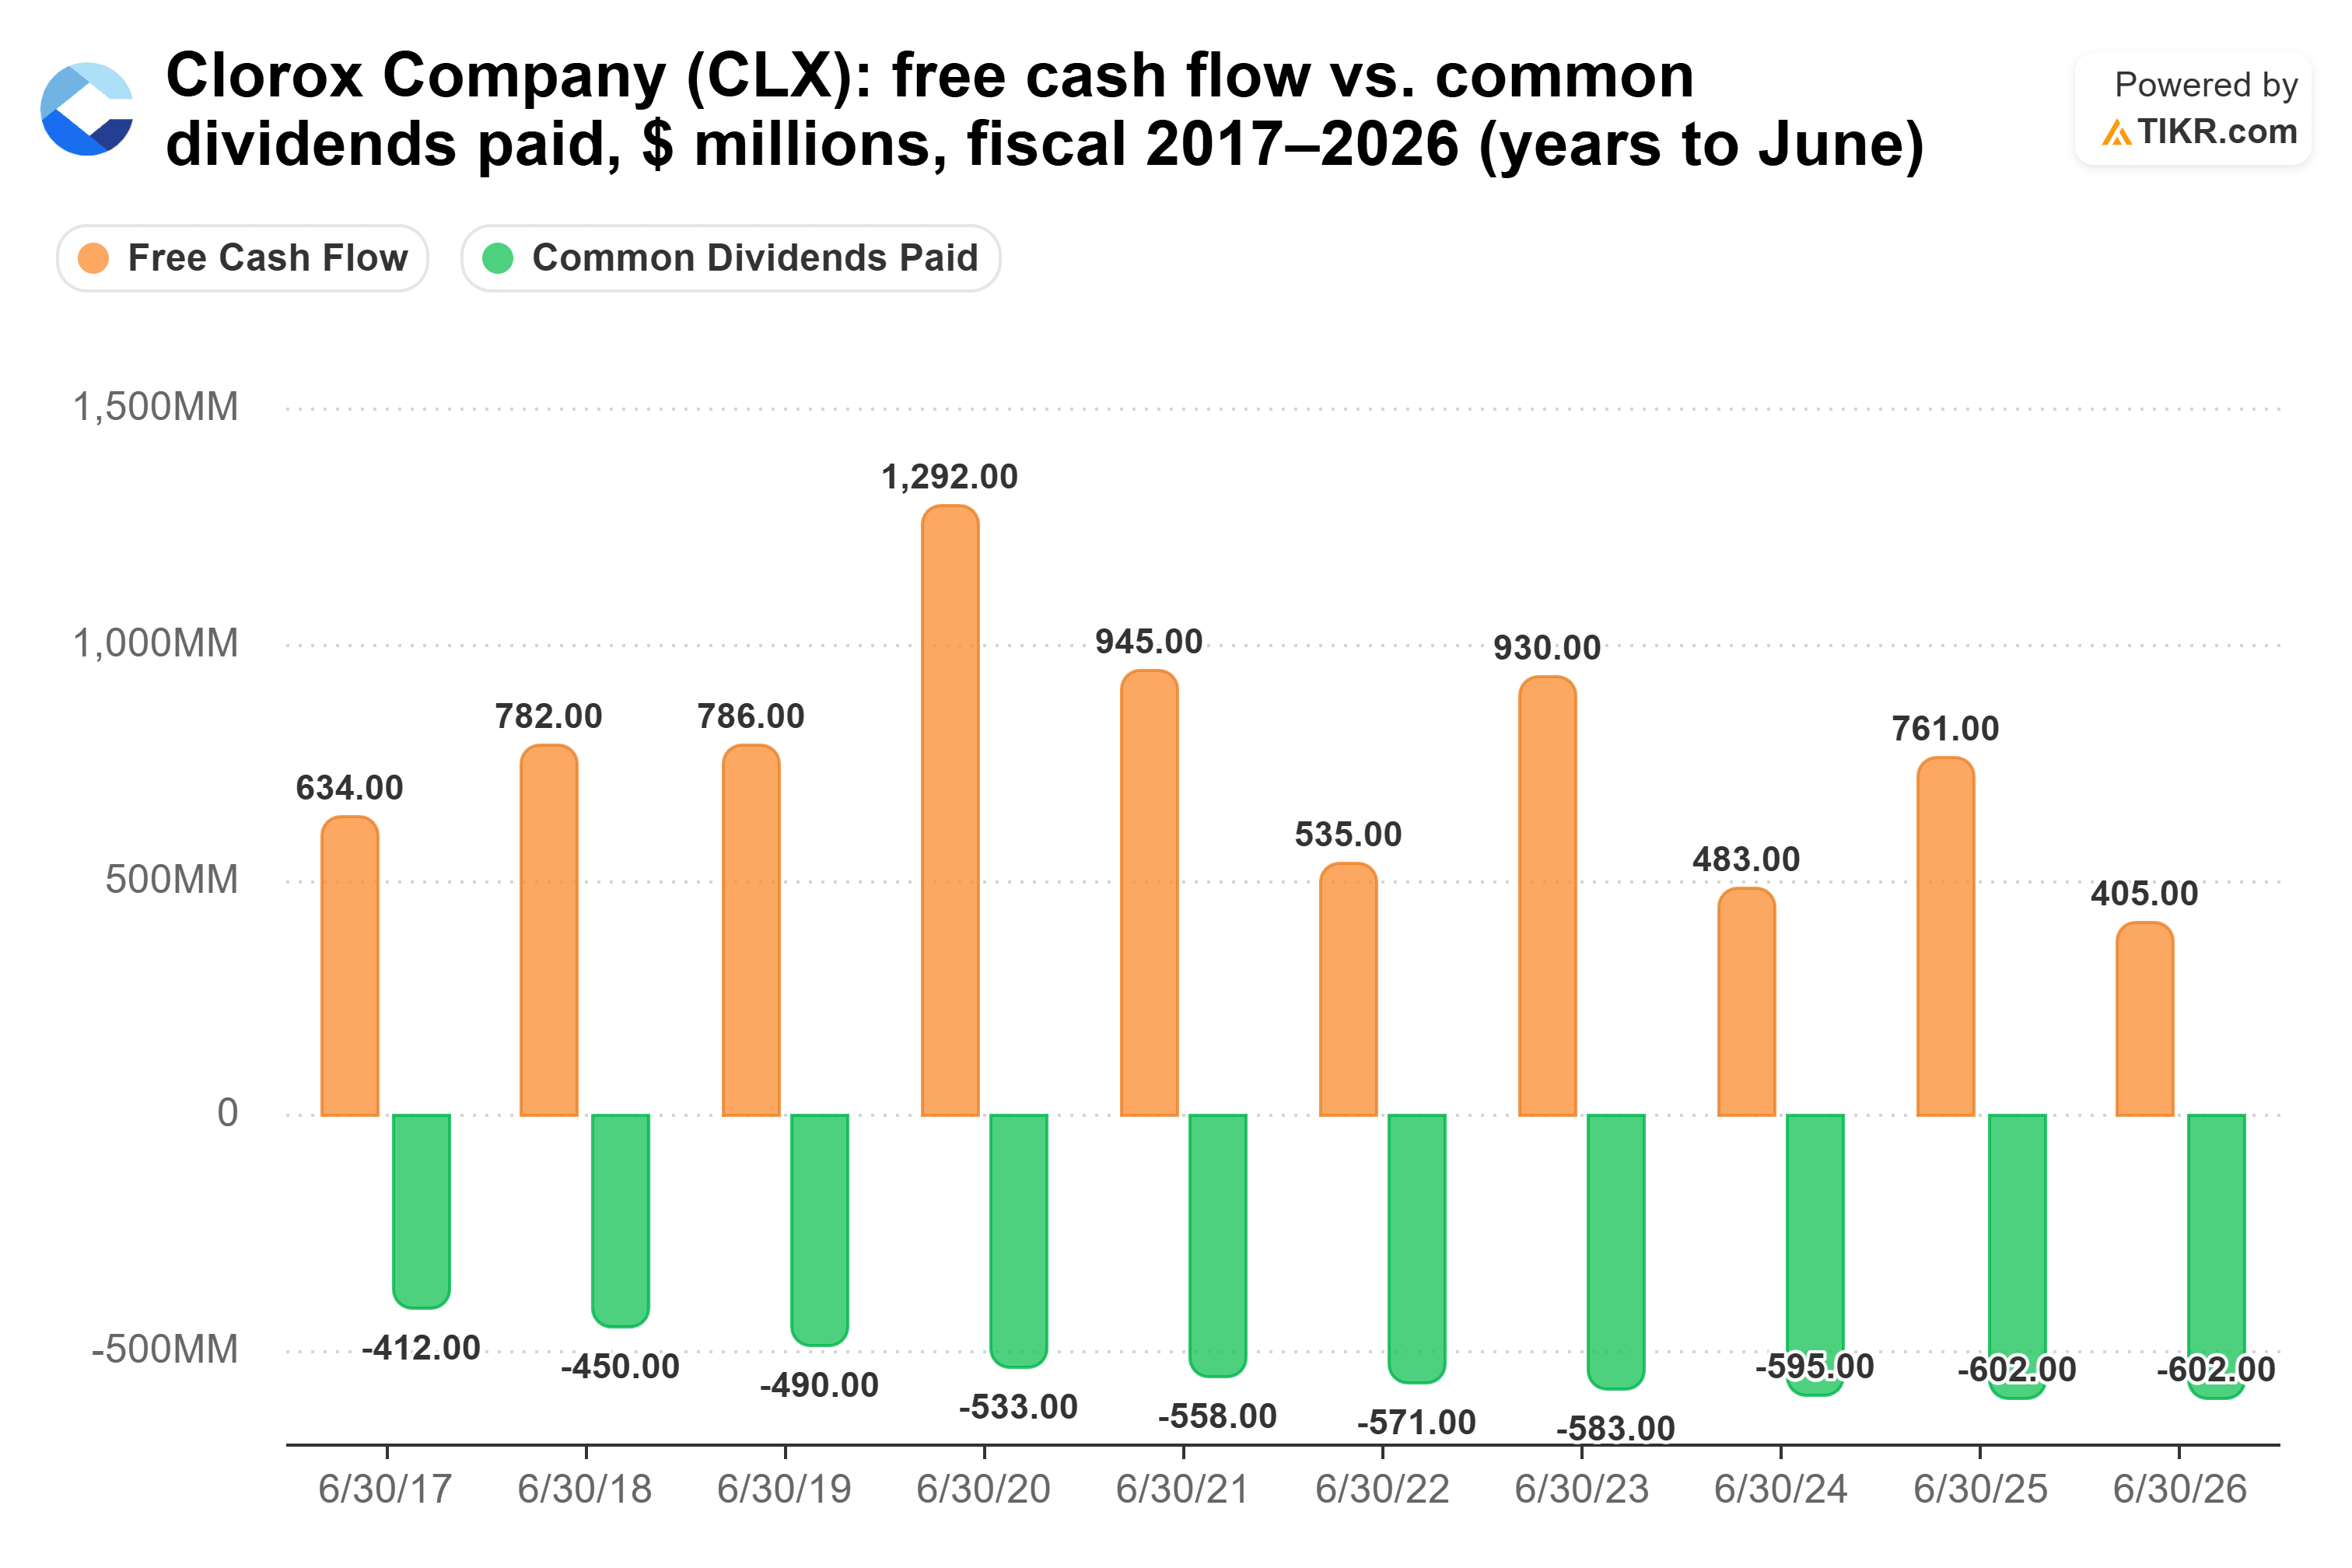
Clorox needs that margin back to cover its dividend. Over the twelve months to Sept. 30, 2026, it paid $602 million in dividends against $453 million of free cash flow. That’s a stretched 133% cash dividend payout ratio. Free cash flow has fallen short of the dividend in three of the last five fiscal years:
On its August call, management said the dividend “has increased annually for a decade. And for now, you should expect this to continue.” It also called the elevated payout “something more transitory as we rebuild our gross margin and not something structural.”
Note the “for now.”
Kinder Morgan has cash to spare
Clorox is trying to rebuild its business. Kinder Morgan is expanding its own. Its third-quarter adjusted EPS rose 21%, and adjusted EBITDA rose 9% to $2.18 billion. Its backlog of expansion projects reached a record $14.4 billion. The same day, it declared a $0.2975 quarterly dividend. That’s the $1.19 a year it budgeted for 2026, after a 2% raise.
Distributable cash flow per share has covered the dividend by more than 1.8x every year since fiscal 2016:
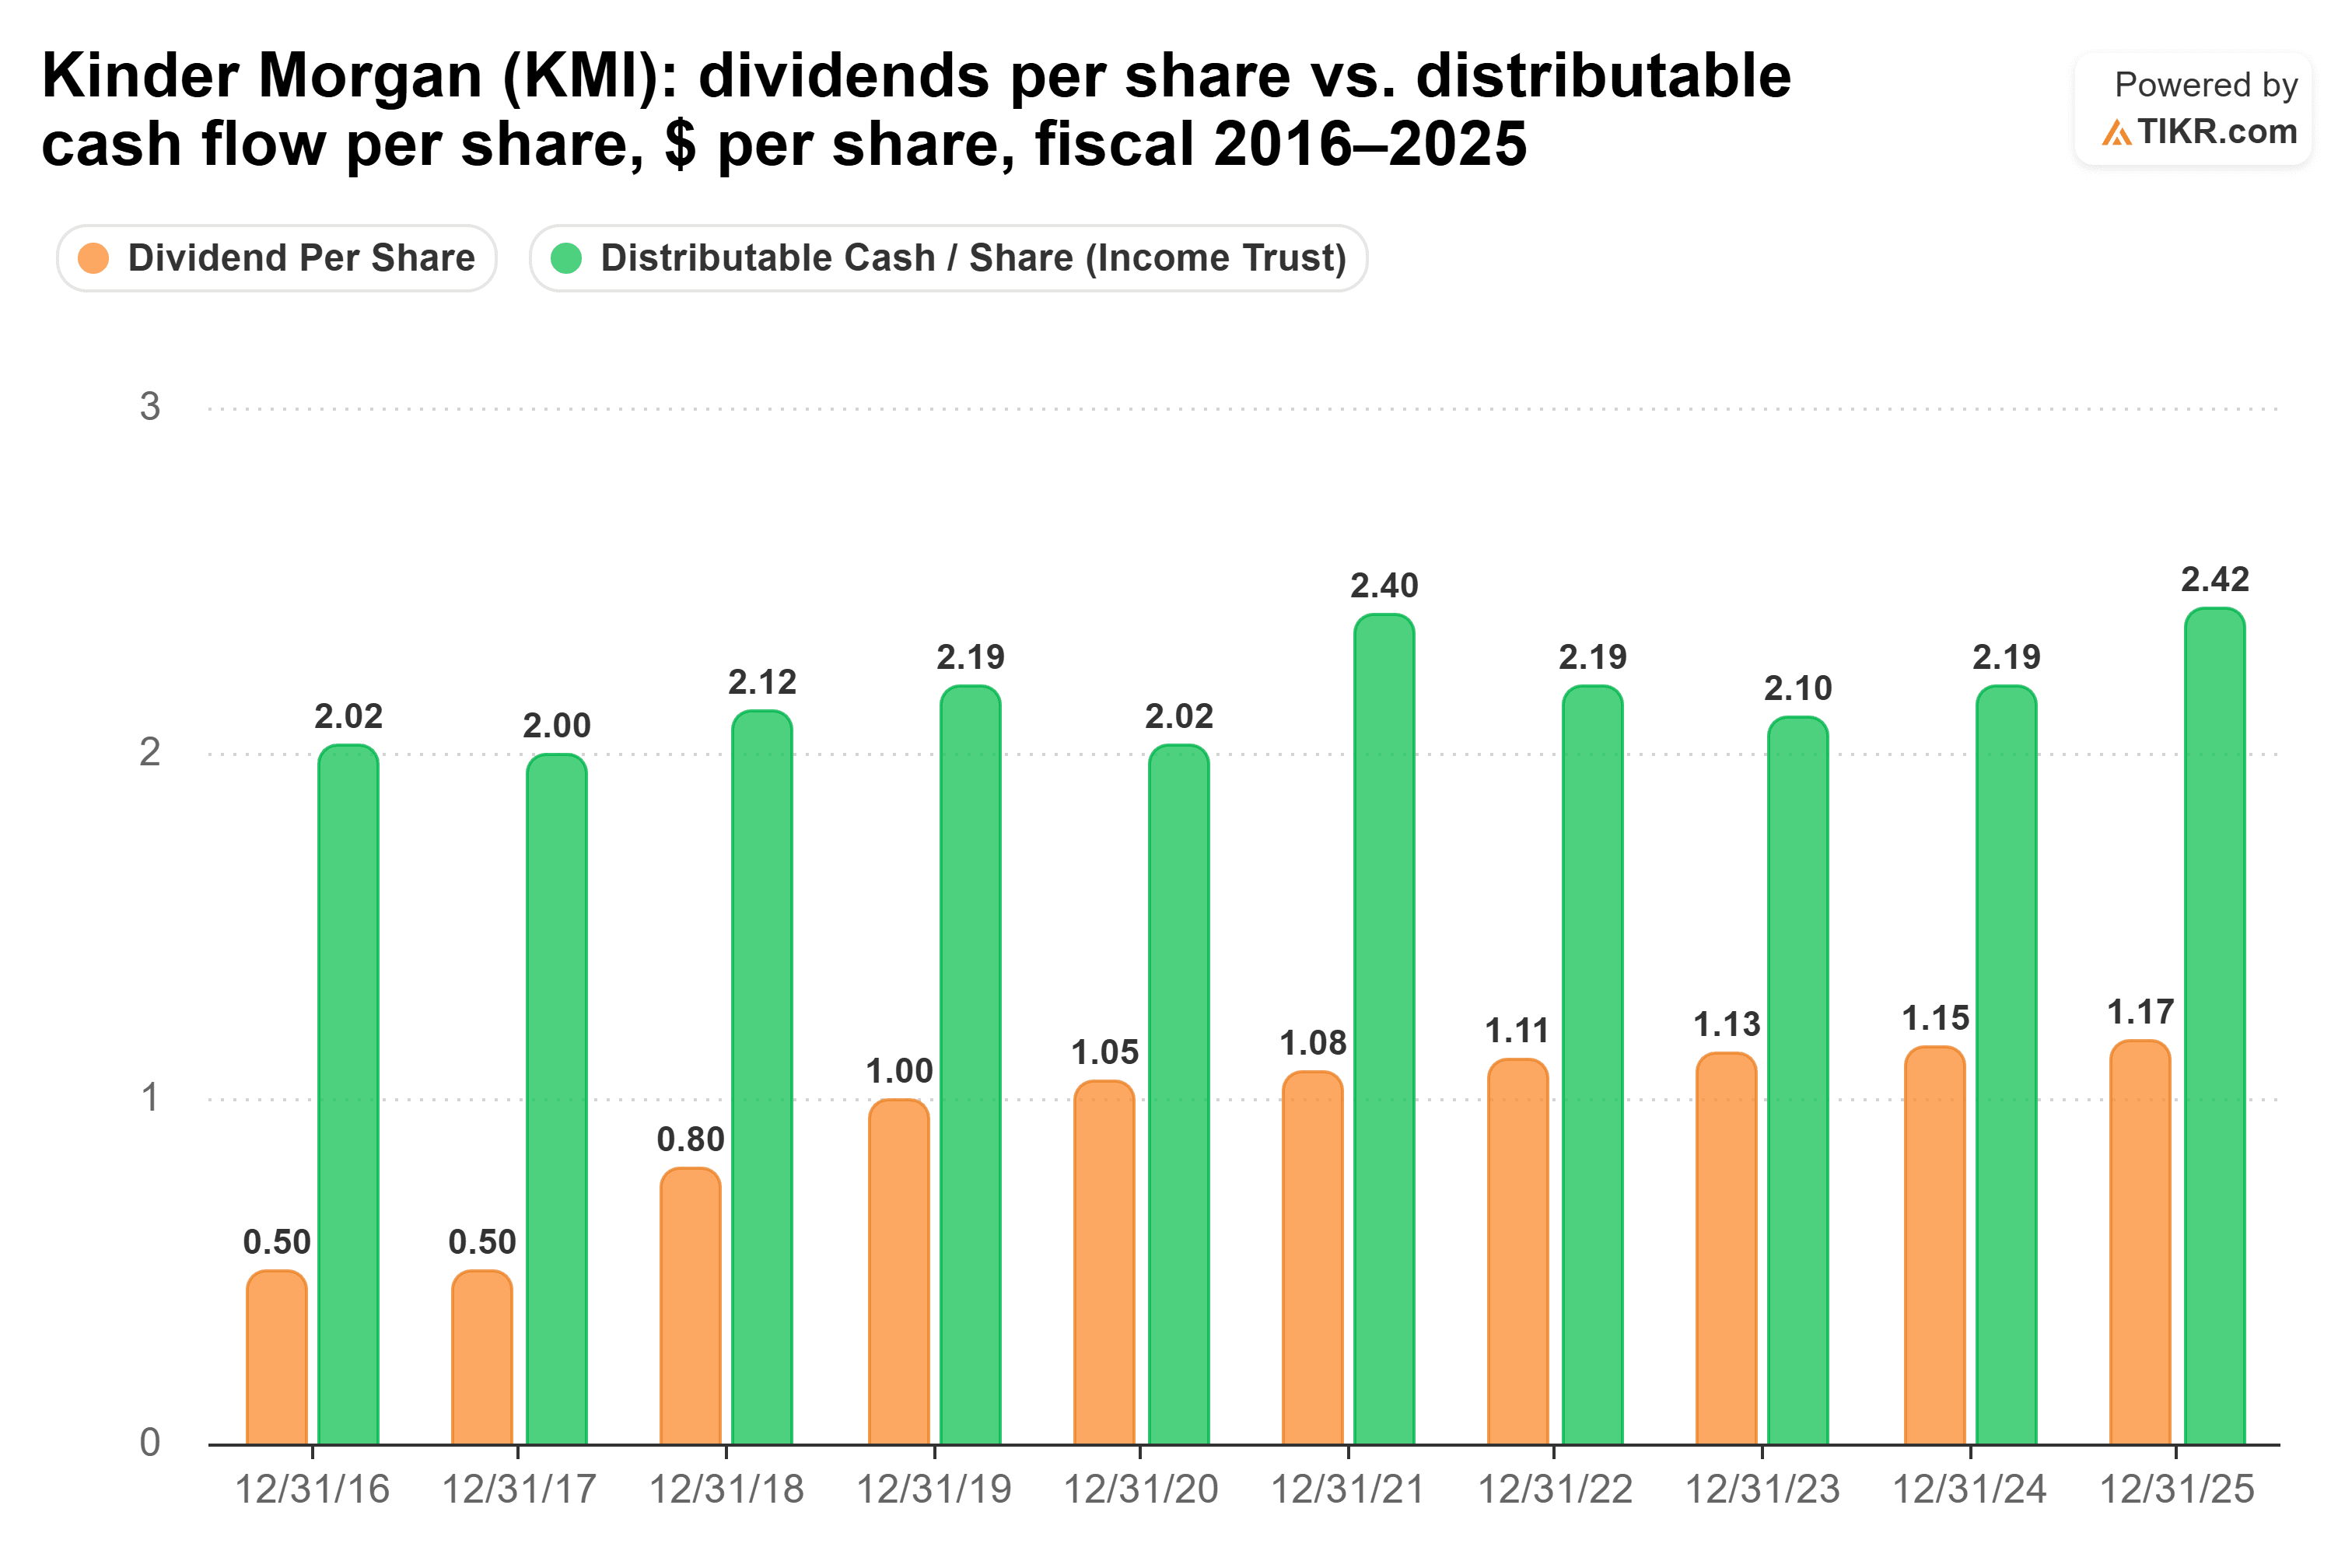
In fiscal 2025, coverage was a comfortable 2.1x: $2.42 a share against a $1.17 dividend. Analysts expect $2.86 for 2026, or 2.4x coverage.
The chart starts just after Kinder Morgan’s dividend cut. It went from $1.60 a share in fiscal 2015 to $0.50 in fiscal 2016, and the dividend is still below where it was before the cut.
So which dividend wins?
If I can only pick one for the next 20 years, I’m picking Kinder Morgan. Over two decades, what I care about most is whether the cash keeps covering the check, and Kinder Morgan’s has done that every year for a decade.
Clorox has a good case, too. Its check is bigger. At each company’s five-year growth rate, $10,000 in Clorox pays about $11,189 over 20 years, against about $9,408 in Kinder Morgan. At those rates, Kinder Morgan wouldn’t catch up for more than 30 years. Clorox also covers its interest 6.5x, more than twice Kinder Morgan’s 3.0x.
But that extra $1,781 assumes Clorox keeps raising a dividend that its free cash flow didn’t cover over the past year. Kinder Morgan’s dividend takes less than half of its distributable cash flow, and over 20 years I’d rather have that cushion.
What would change my answer is Clorox’s cash coming back. Analysts expect its free cash flow to reach $828 million in fiscal 2027 and $843 million in fiscal 2028:

Up from fiscal 2026’s $405 million, that would bring the cash dividend payout ratio back to about 74%. But last year’s final consensus missed by 18%, and a new CEO takes over while costs are still rising. If he pulls off the rebuild, Clorox’s bigger check gets a lot safer.
Forget Kinder Morgan: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Kinder Morgan isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!