

Key Takeaways
- Lumentum guided fiscal Q1 revenue to $1.225 billion to $1.275 billion, about 23% above Q4’s $1.01 billion, with non-GAAP operating margin near 40%.
- CEO Michael Hurlston told Bloomberg Television that Lumentum’s AI optical components are “completely sold out” through early 2029.
- At 39.1x forward earnings, Lumentum is the priciest major AI optics name, and new laser capacity takes about three years to reach customers.
- The November 5 report will test whether supply additions can keep pace with demand and support that steep revenue ramp.
Few companies can say they have nothing left to sell for three years. Lumentum (LITE) can.
CEO Michael Hurlston told Bloomberg Television in Tokyo that the company’s optical components are “completely sold out” through early 2029. Six months earlier, he had pointed to 2028.
The stock rose 3.4% to $851 on October 21 and is up 120% this year. Still, shares sit 26% below their $1,143 high as AI hardware stocks cooled through October.
The tension is simple. Lumentum has more demand than it can serve, so every quarter now depends on how fast its fabs can grow.
A doubled quarter and a bigger guide
Fiscal Q4 revenue rose 109% to $1.01 billion, up from $480.7 million a year earlier. Non-GAAP EPS of $3.23 beat the $2.97 consensus.
The guide was even louder:
- Q1 fiscal 2027 revenue of $1.225 billion to $1.275 billion, about 23% sequential growth at the midpoint.
- Non-GAAP operating margin of 39.5% to 40.5%, up from 36.6% in Q4.
- Non-GAAP EPS of $4.05 to $4.35.
That trajectory looks like this.

Revenue more than doubled in a year, and the guide implies another big step. For comparison, Coherent (COHR) guided to a $2.3 billion Q1 midpoint, about 12% sequential growth from a much bigger base.
One accounting note: Lumentum posted a $7.2 billion GAAP net loss in Q4 because equitizing convertible notes triggered a one-time, non-cash $7.8 billion loss. It did not touch operations, but it explains the negative trailing P/E.
Scarcity is doing the margin work
When customers cannot get enough product, pricing tilts toward the seller. Hurlston said Lumentum cannot meet roughly 70% of demand for some products through next year and about 30% for certain others through 2028. Customers are already placing orders for 2030.
Lumentum added a fab in Greensboro, North Carolina, and is expanding a second fab in Japan. Its Tokyo-area output has grown twelvefold in two years.
Where does that pricing power show up?
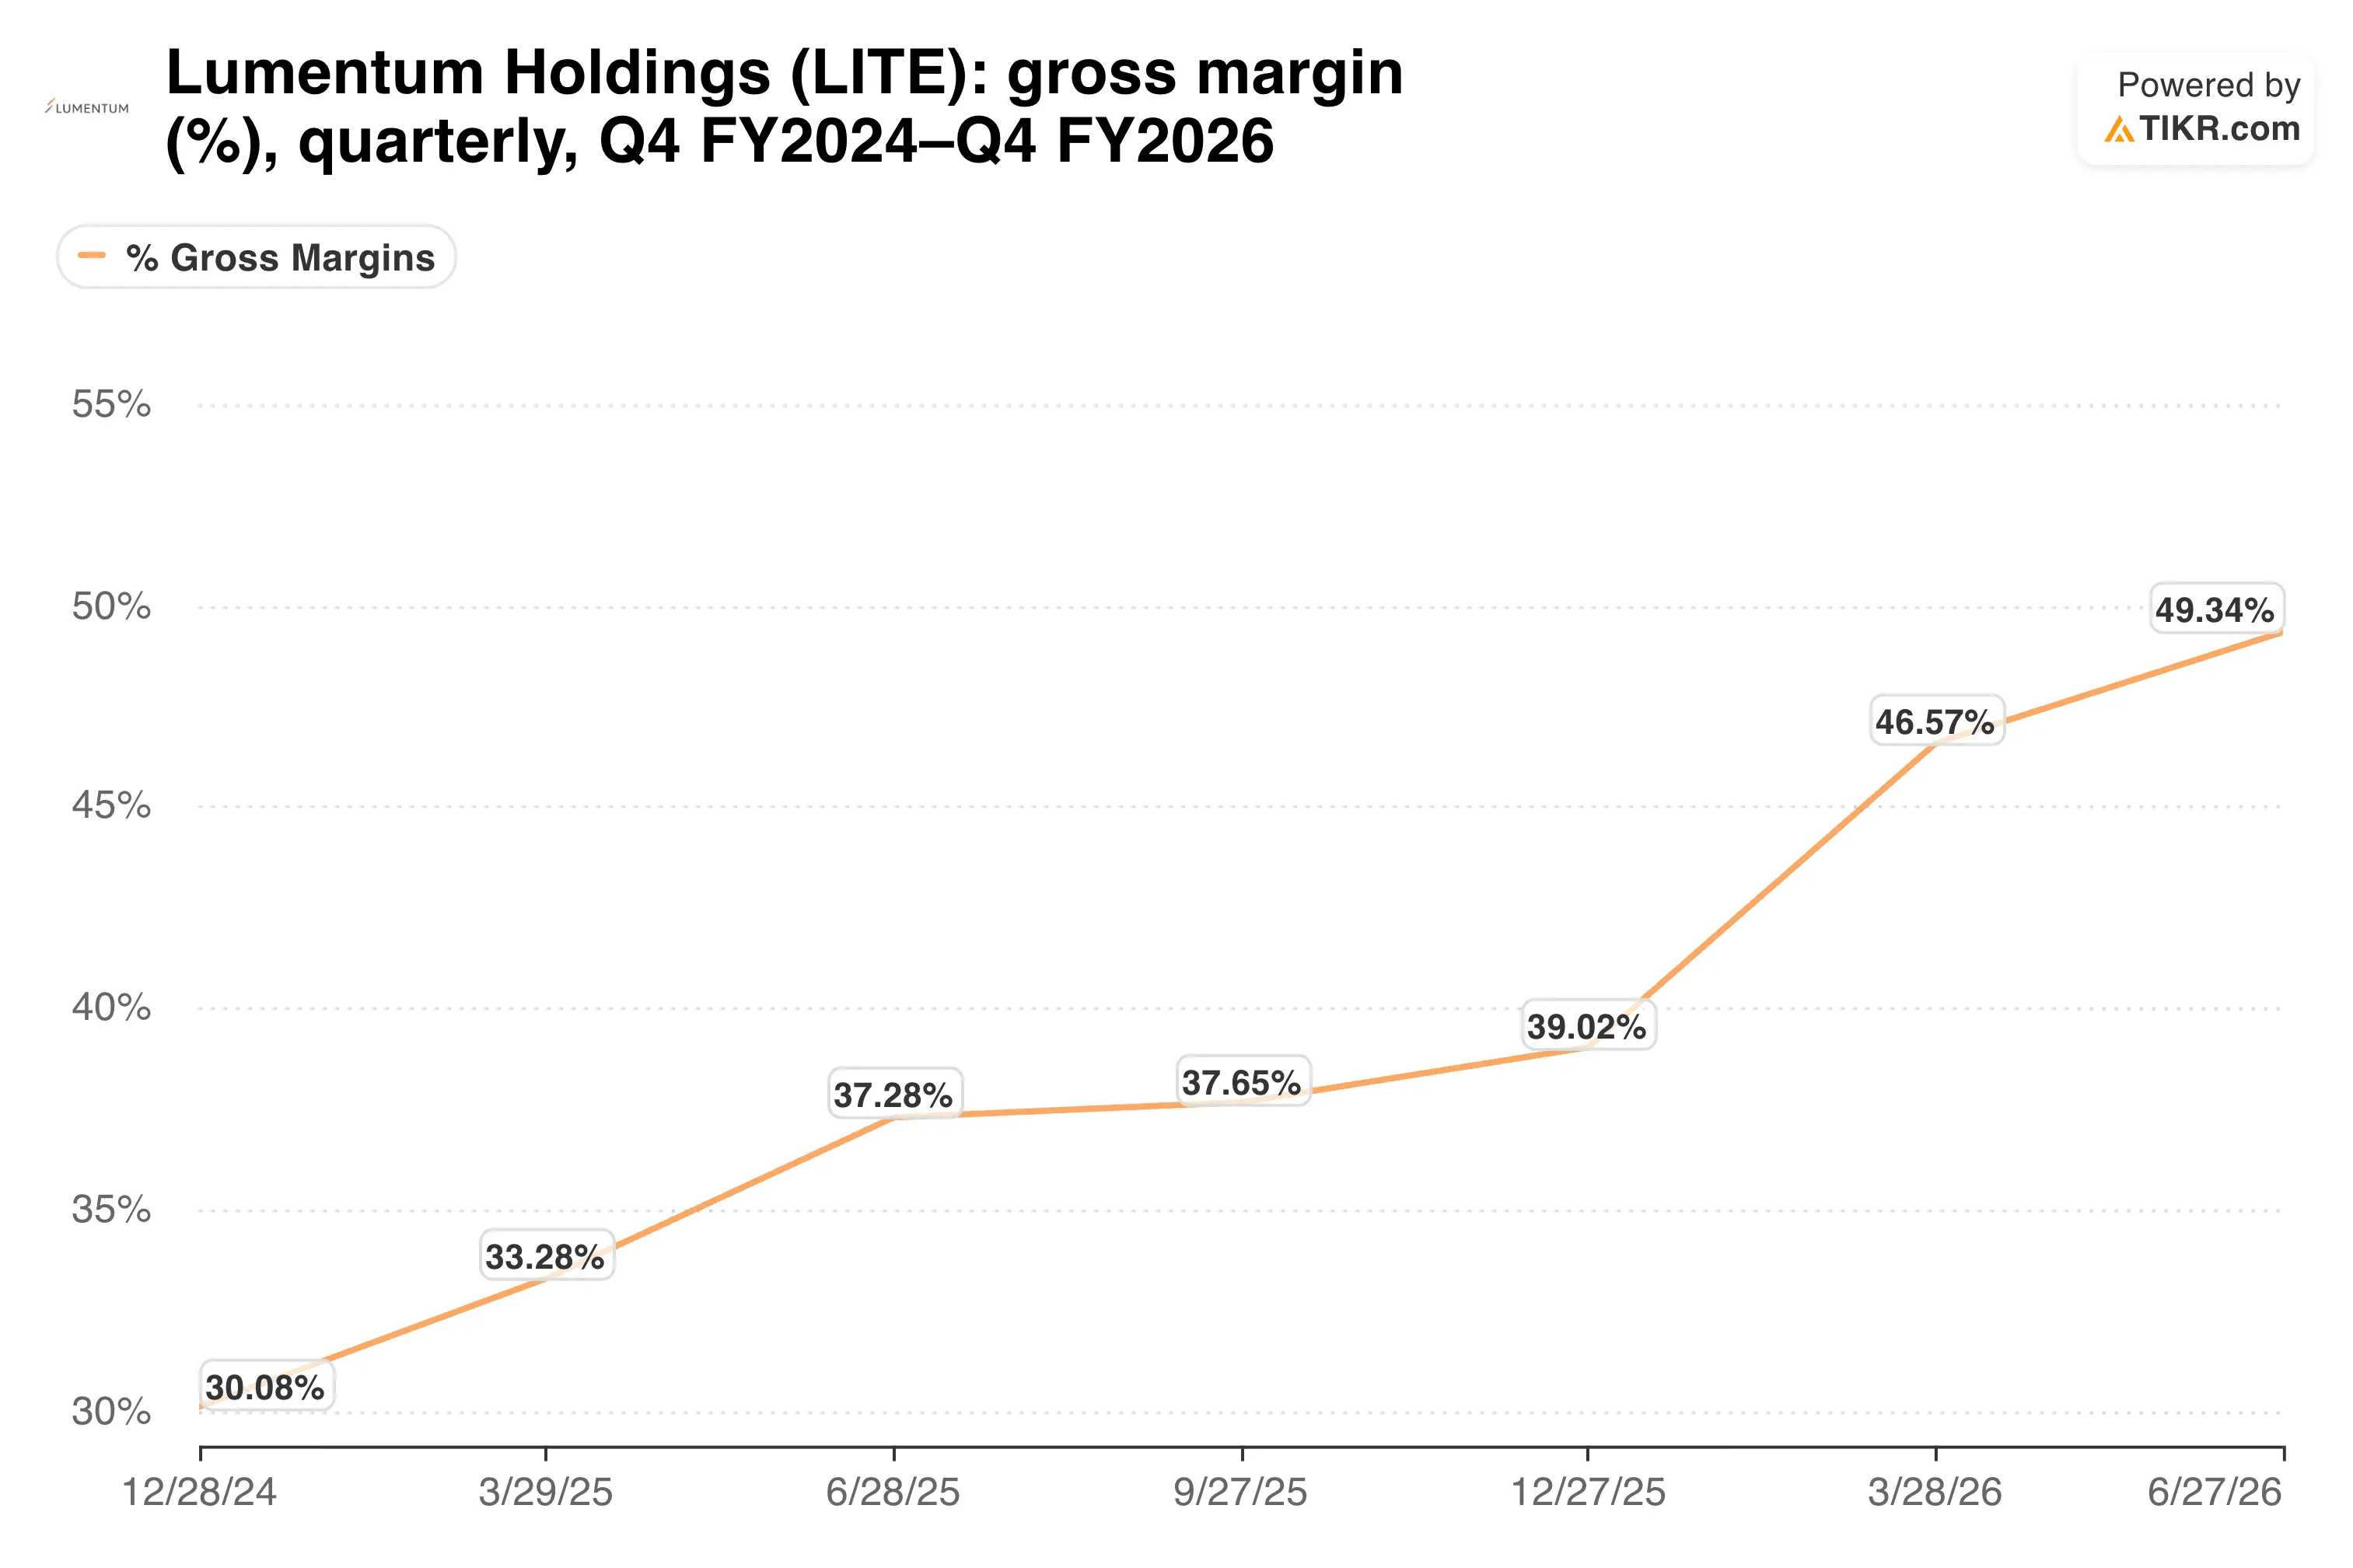
Non-GAAP gross margin hit 50.4% in Q4, and the Q1 guide suggests operating leverage is still building.
The product mix helps too. Record 800G transceiver shipments, early 1.6T production and optical circuit switches are driving cloud revenue. At the OCP Global Summit, Lumentum also demonstrated PCIe-over-optics rack connectivity with Astera Labs (ALAB) and Corning (GLW).
TIKR tracks 26 analysts on Lumentum. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Lumentum, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Lumentum’s Analyst Ratings
The price of being sold out
Scarcity cuts both ways. Hurlston warned that new laser capacity takes about three years to reach customers, so relief may not arrive until 2029 or 2030. Any yield stumble now hits revenue directly.
Investors are paying up for that visibility, and the multiple stands apart from peers.

Lumentum trades at 39.1x forward earnings, versus 25.3x for Coherent and 25.0x for Credo (CRDO). Its 82.4% forward two-year revenue CAGR is the fastest of the three, so the premium has a basis.
Insider selling adds a wrinkle. CFO Ali Wajid sold 24,542 shares for about $25.7 million in early October.
My take: Lumentum has the cleanest demand story in AI optics, and a 40% operating margin guide shows it is turning scarcity into profit. But a 39x multiple leaves little room for a capacity delay or a hyperscaler pause. I would rather own it on execution proof than on the sold-out headline.
The November 5 report is the test. Watch whether revenue clears $1.25 billion and whether management pulls new capacity forward.
So what is Lumentum stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Lumentum could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


