

Key Takeaways
- Coherent shares have fallen 25.1% over three months and sit 46% below their $440 high, despite record fiscal 2026 revenue of $7.12 billion.
- Datacenter & Communications revenue jumped 58.6% to $1.62 billion in Q4, making up 79% of total sales.
- Free cash flow remains negative as Coherent pours money into capacity, and the stock still trades at 25.3x forward earnings.
- The November 4 report will show whether Q1 revenue lands in the guided $2.2 billion to $2.4 billion range with margins intact.
Coherent (COHR) just finished the best year in its history. The stock is acting like it had a bad one.
Shares closed at $238 on October 21, up 2.5% on the day but down 25.1% over three months. That leaves the stock 46% below its 52-week high of $440.
The business story has barely changed. Revenue hit $7.12 billion in fiscal 2026, up 22.5%, and AI data center demand carried almost all of the growth.
So what did change? Mostly the mood around AI hardware. Optics names sold off in mid-October on worries about AI returns, and Goldman Sachs (GS) strategists argued the momentum trade had run its course.
Coherent reports fiscal Q1 on November 4, and that print now carries a lot of weight.
The data center engine kept accelerating
Q4 revenue reached $2.05 billion, up 34% year over year and 42% on a pro forma basis. Non-GAAP EPS came in at $1.74, ahead of the $1.61 consensus.
The segment mix tells the real story:
- Datacenter & Communications revenue rose 58.6% to $1.62 billion, or 79% of total sales.
- Data center revenue alone grew 66% year over year and 24% sequentially.
- Non-GAAP gross margin climbed to 40.2%, up 215 basis points from a year earlier.
Here is how lopsided the growth has become…

The industrial side barely matters to the thesis anymore. Coherent is now an AI optics company with a laser business attached.
CEO Jim Anderson said in the Q4 release that Coherent enters fiscal 2027 with “exceptional customer demand, expanding production capacity, and multiple new growth platforms beginning to ramp.”
Nvidia and PhotonLink widen the runway
Two developments explain why analysts still see room to run.
First, Nvidia (NVDA) signed a multiyear, nonexclusive agreement in March that includes a multibillion-dollar purchase commitment and a $2 billion equity investment. Nvidia announced a similar partnership with Lumentum (LITE) the same day, so Coherent holds no exclusive claim on the business.
Second, the new PhotonLink platform packages Coherent’s lasers, silicon photonics, fibers and detectors into one offering. Management counts more than 10 co-packaged optics engagements, more than 10 near-packaged engagements and five-plus chip-to-chip projects. It expects PhotonLink revenue to start ramping in calendar Q4 2026.
Street estimates already assume much of that comes through.
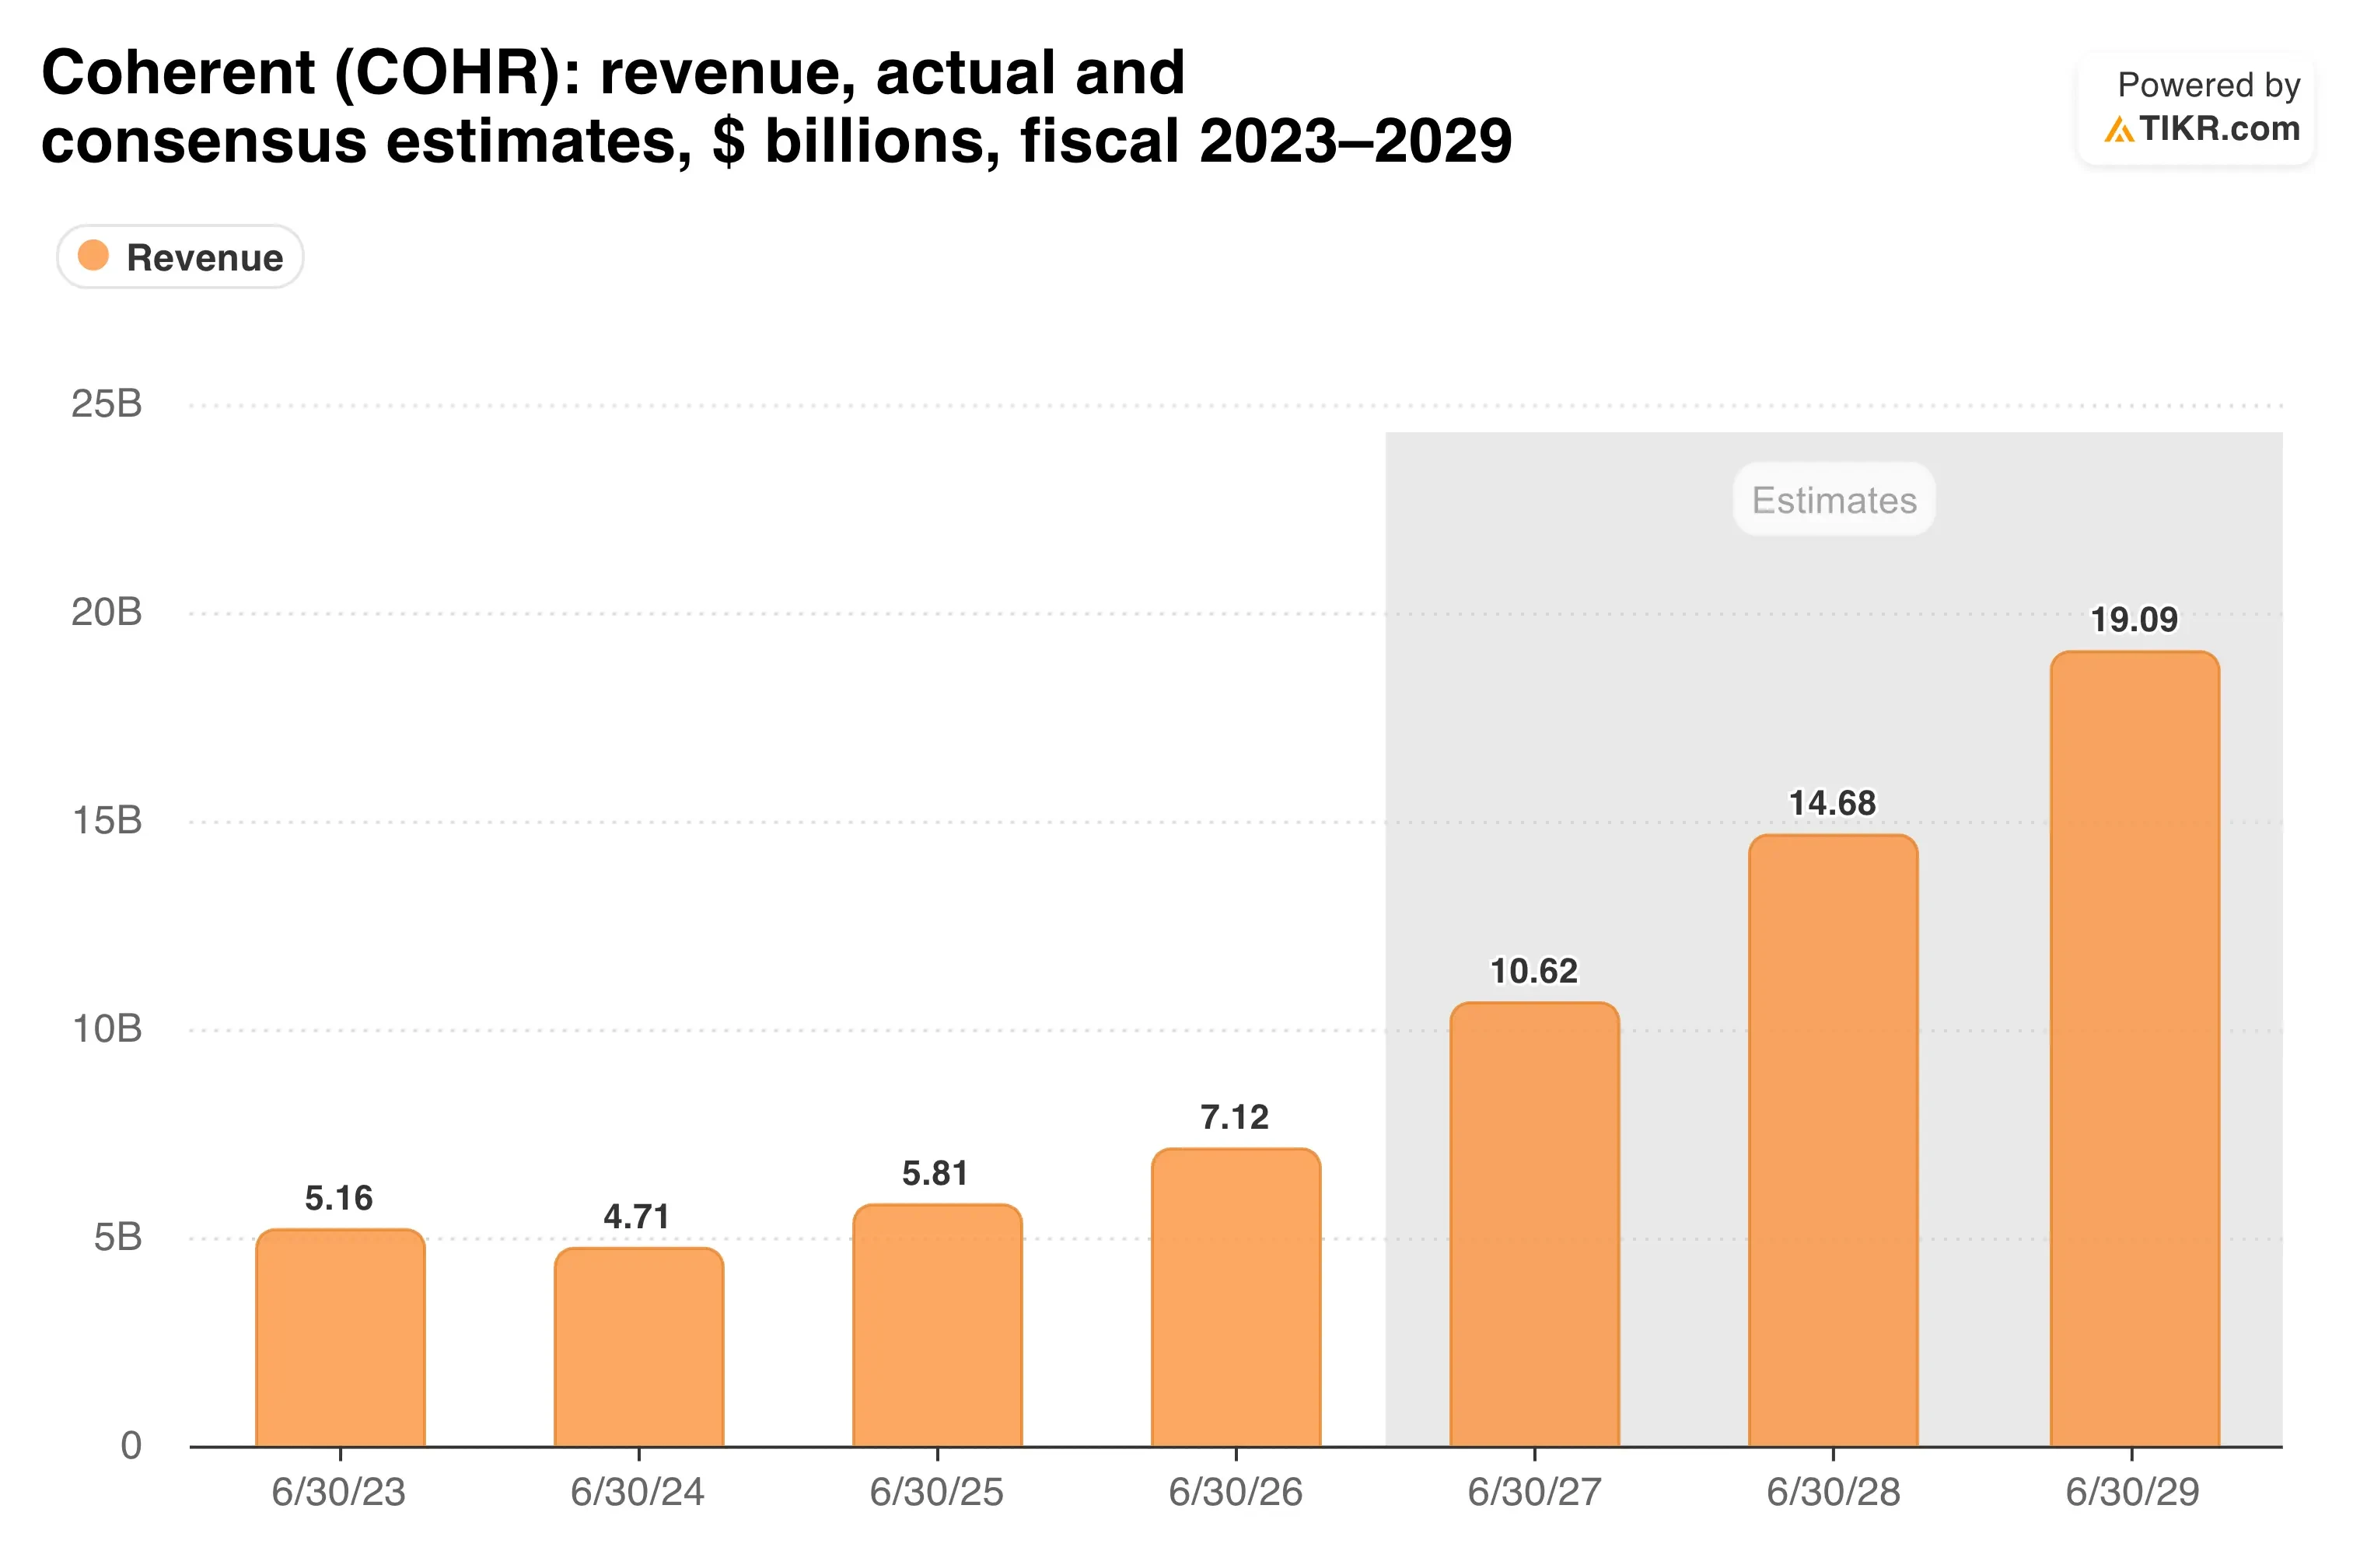
Consensus implies a 43.6% forward two-year revenue CAGR. That is fast, yet it trails Lumentum at 82.4%, which partly explains why Lumentum commands the richer multiple.
TIKR tracks 24 analysts on Coherent. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Coherent, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Coherent’s Analyst Ratings
Growth is expensive to build
Coherent is spending heavily to meet demand, and cash flow shows it. The stock’s market cap to forward free cash flow ratio is negative, so analysts expect another year of cash burn.
Let’s look at the trend:
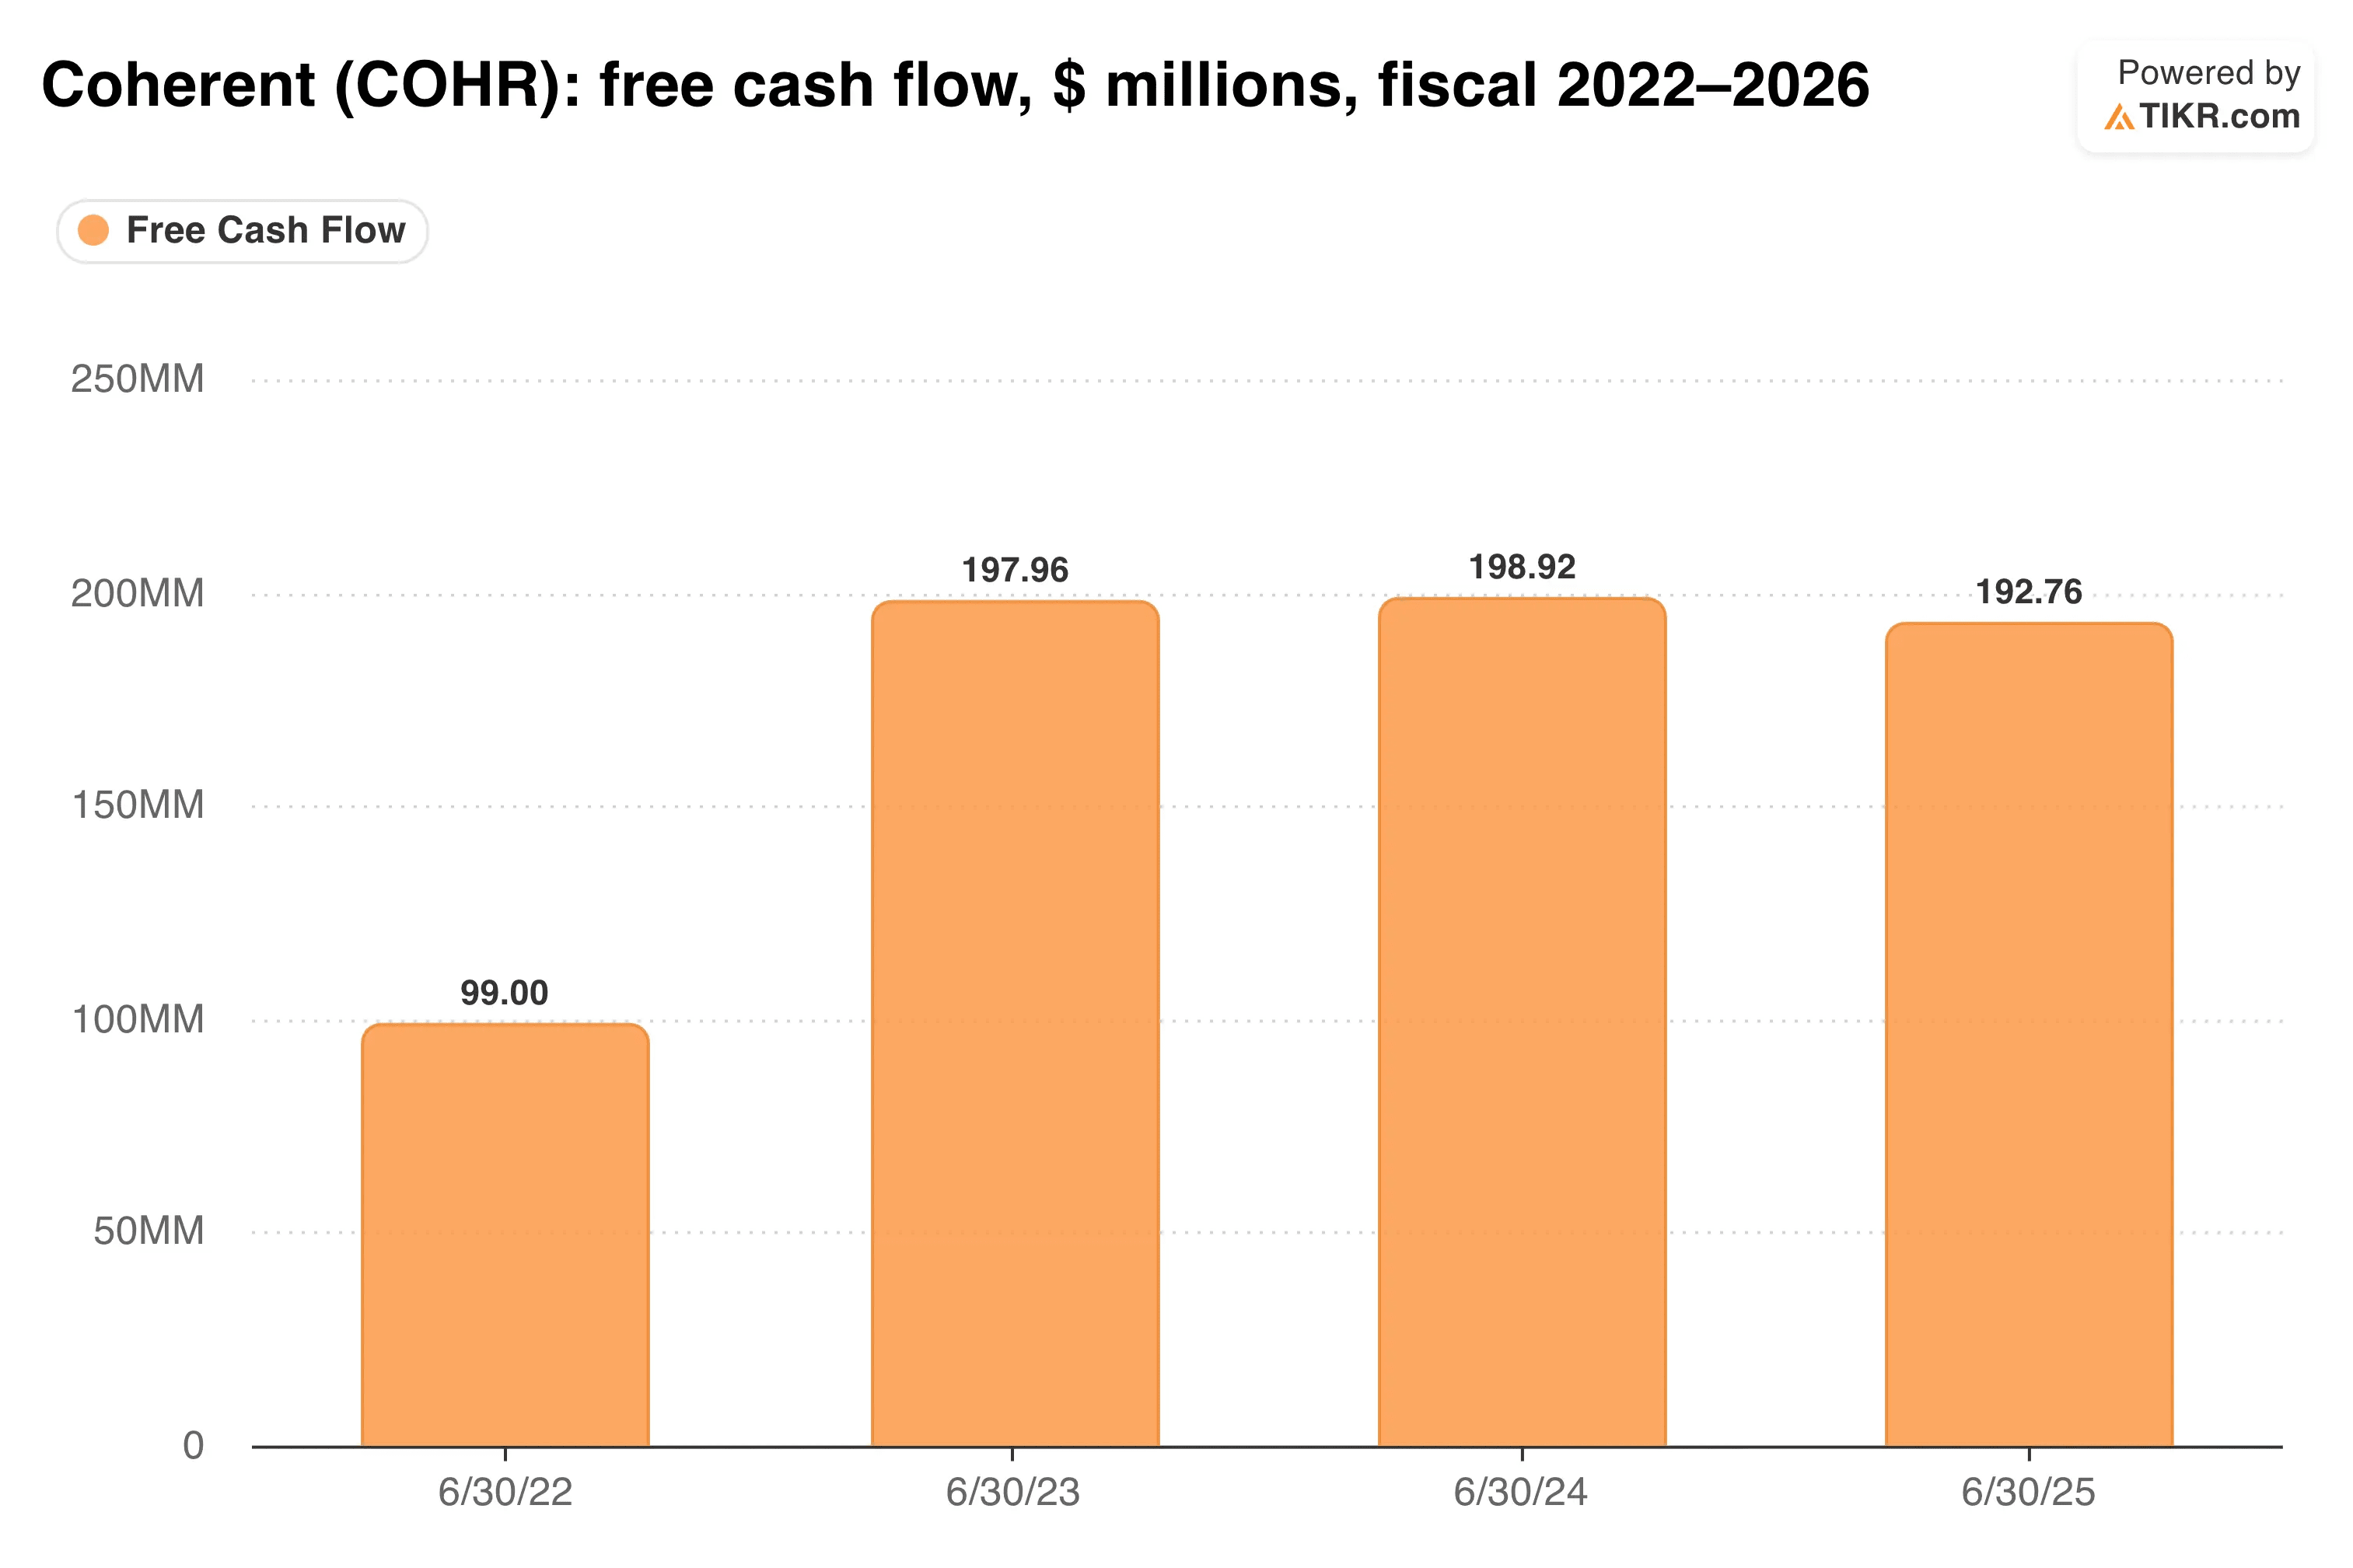
Capacity spending makes sense when customers are lining up. However, it leaves Coherent with $1.56 billion of net debt and little room for a demand hiccup.
Valuation looks more reasonable after the drawdown. At 25.3x forward earnings, Coherent trades well below Lumentum’s 39.1x, and the $395 average analyst target sits about 66% above the current price.
Insiders have been sellers, though. The CTO disposed of $3.6 million of stock in early September, and a director sold about $590,000 the same week.
My take: The selloff squeezed out a lot of froth, and the core data center business is growing faster than ever. Still, Coherent is the lower-margin, cash-burning name in AI optics, so it needs clean execution to earn a re-rating. I want proof that gross margin keeps climbing toward the top of its 39.5% to 41.5% Q1 guide.
November 4 is the next checkpoint. Watch Q1 revenue against the $2.2 billion to $2.4 billion range, any early PhotonLink revenue commentary, and updates on 1.6T transceiver volumes.
So what is Coherent stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coherent could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


