Key Takeaways
- Marvell stock is up 75% in 2026. The run took off after Jensen Huang, then Nvidia’s CEO, called it the “next trillion-dollar company” in June.
- Marvell’s $115 billion all-stock deal for Lumentum and an AI chip selloff have left the stock 55% below its June high, even as revenue growth speeds up.
- The deal adds about 49% to Marvell’s share count, and regulators, including China’s, still have to approve it before the expected close in the first half of 2028.
- Marvell trades below its five-year average multiple, which makes it a buy if its Dec. 1 report holds up.
Marvell Technology (MRVL) is up 75% in 2026, even after falling 55% from its June high. Jensen Huang, then CEO of Nvidia (NVDA), called Marvell the “next trillion-dollar company” on June 2, as CNBC reported. Then Marvell agreed to buy Lumentum (LITE) in an all-stock deal investors hated.
Nvidia has skin in the game: it holds $2 billion of Marvell preferred stock and put $2 billion into Lumentum in March.
The business earned the run
On Aug. 19, Marvell deepened its custom-chip work with Google. Google got a warrant on 58.97 million Marvell shares at $206.58. Revenue for the quarter to Aug. 1 rose 37% to a record $2.74 billion. At its Oct. 6 Investor Day, Marvell raised its fiscal 2028 revenue outlook to about $20 billion, from about $18 billion in August. On Nov. 2, it said third-quarter revenue would land within 2% of its $3.15 billion midpoint. That’s about 52% growth from a year earlier.
TIKR tracks 46 analysts on Marvell. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Marvell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Marvell’s Analyst Ratings
The deal investors hated
Bloomberg reported after the Oct. 28 close that Marvell was in advanced talks to buy Lumentum. On Nov. 2 the two signed: Lumentum holders get 4.5 Marvell shares for each Lumentum share, an implied enterprise value of $115 billion. Lumentum’s holders would own about 33% of the combined company. That adds about 49% to Marvell’s share count, on top of Google’s warrant. Regulators, including China’s, have to approve the deal before the expected close in the first half of 2028. If they block it, Marvell owes Lumentum $3.2 billion.
Lumentum is up 52% in 2026, and its September-quarter revenue rose 136.5% to $1.26 billion. But its non-GAAP gross margin was 53.2% that quarter, below the 57.5% to 58.5% range Marvell guided for its October quarter. Marvell CEO Matt Murphy conceded on Fox Business that “you take more risk when you do it, and sometimes being unorthodox is what you have to do in order to get the outsized return.” On Nov. 10, TD Cowen and Bank of America downgraded the stock.
The selloff wasn’t all about the deal
Marvell had no news of its own on Nov. 4 and 5, when the AI chip group sold off after Democrats won both houses of Congress on promises to be tougher on data-center construction. Huang’s Nov. 12 resignation from Nvidia and a 10-year Treasury yield above 5% hit the group again. Marvell was still up 82% for the year on Nov. 10, so a good part of the latest drop came from the whole group, not just the deal.
Cheaper than its usual multiple
Analysts still expect Marvell’s normalized EPS to climb from $2.84 in fiscal 2026 to $12.76 in fiscal 2029:

Investors are paying less for those earnings than they usually do:

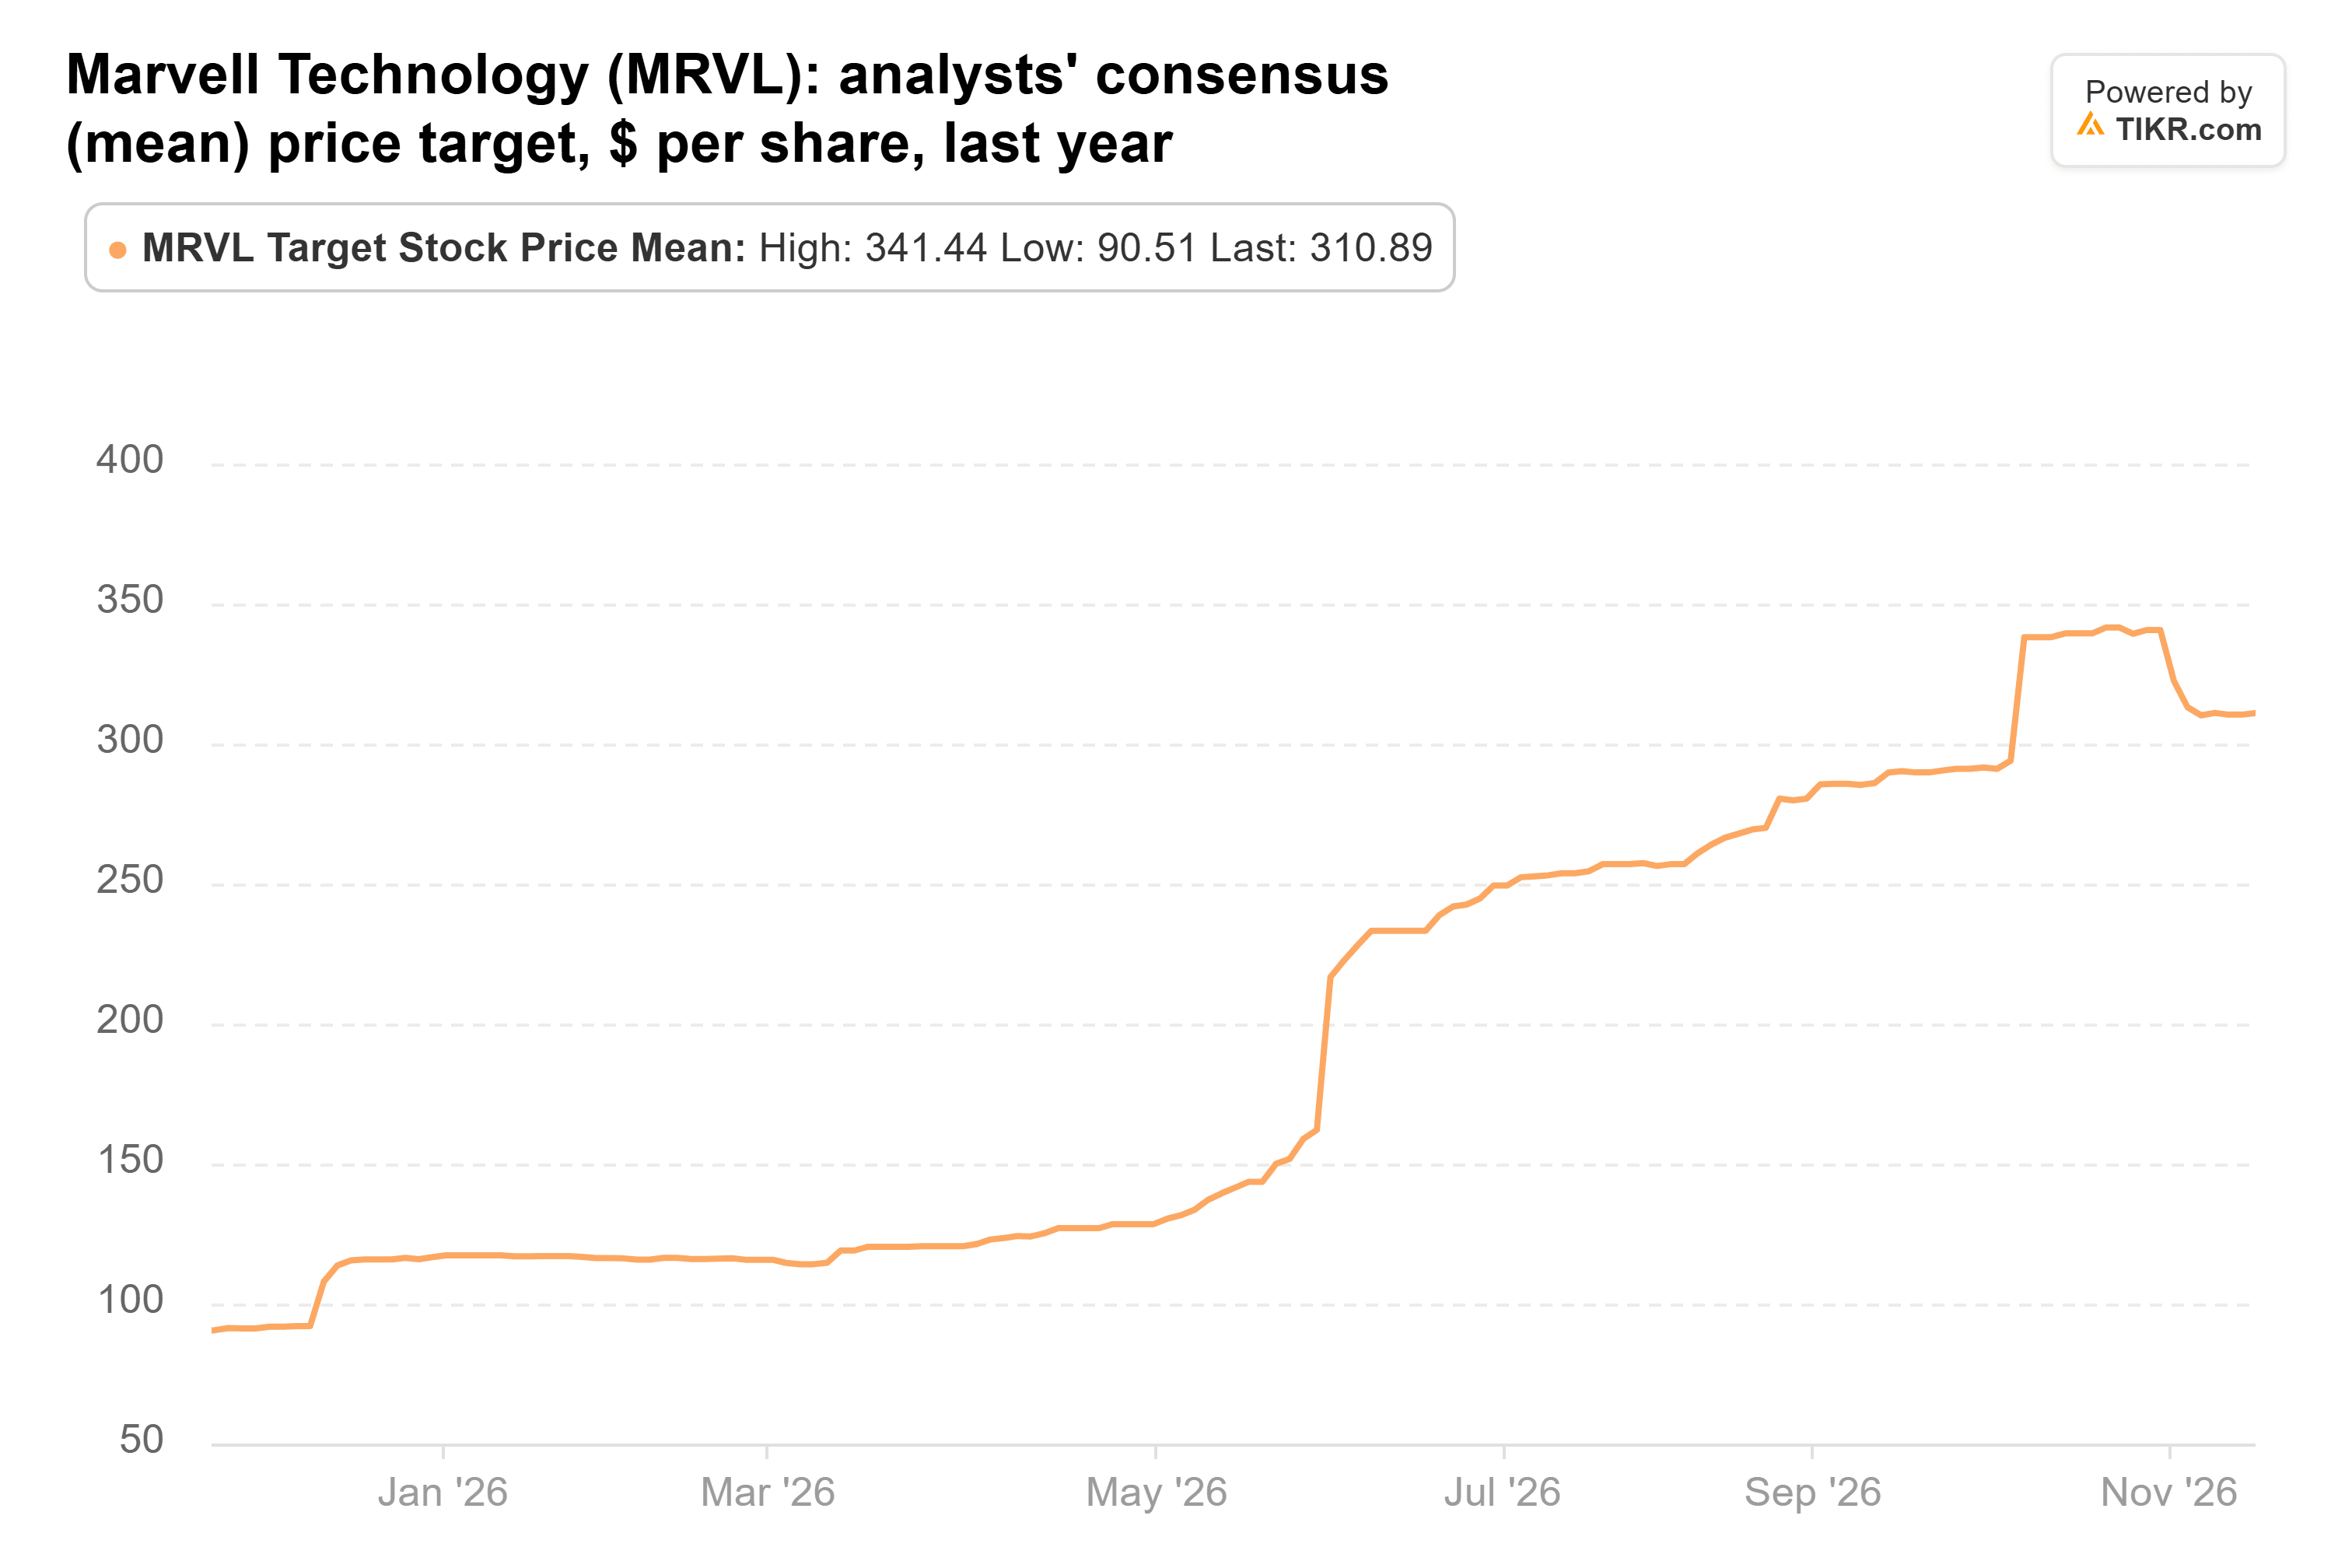
Marvell trades at about 26x forward earnings. That’s under its five-year average of about 32x and far below the 70x it reached in June. The Street’s average target has slipped to $311 from $341 in late October, still more than double the stock’s price:
What has to hold on Dec. 1
On Dec. 1, third-quarter revenue near the midpoint, with gross margin inside its guide, would show the business is on track. Management’s fiscal 2027 outlook of about $12 billion implies fourth-quarter revenue of roughly $3.7 billion, so that’s the guide to beat. Any cut to the $20 billion fiscal 2028 outlook would break the case.
I’d rather buy Marvell here than at June’s high. At that multiple, with EPS expected to triple from this fiscal year to fiscal 2029, investors have already priced in much of the deal’s risk, as long as the quarter holds up. Dilution is the cost to watch. Meanwhile, Nvidia’s Nov. 17 report beat its own forecast, with revenue up 103% to $115.8 billion.
So what is Marvell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!