

Key Takeaways
- ServiceNow shares fell 35% in the past month, most of it after the company guided fourth-quarter cRPO growth down to 18.5%.
- Management blames renewals pulled into the third quarter, and two AI-driven software selloffs, which also hit Salesforce, did most of the rest.
- At about 22x forward earnings, less than half its five-year average, the stock looks like a buy if cRPO growth holds 18.5%.
ServiceNow (NOW) stock is down 35% in the past month. It fell 27% on Oct. 29, after its third-quarter report. Then two software selloffs over AI took it lower still, and hit Salesforce (CRM) too.
Wedbush analyst Dan Ives called the post-earnings drops “violent air pockets” on the Nov. 3 episode of the RiskReversal Pod. Given CEO Bill McDermott’s leadership and the valuation, he said, “you own it.”
I agree.
The backlog guide investors hated
Subscription revenue rose 21% to $3.99 billion. But ServiceNow guided fourth-quarter cRPO growth to 18.5%, down from the third quarter’s 20.5% and below the roughly 19.8% analysts expected.
CFO Gina Mastantuono called the AI-disruption narrative “false.” She tied the guide to a July 1 pricing change that pulled renewals into the third quarter, plus more on-premises public-sector deals. Total RPO grew 22% to $29.7 billion, faster than cRPO, which fits that explanation.
Analysts still see normalized EPS rising from $3.51 in 2025 to $5.89 in 2028:

Then software sold off on AI fears
There was no ServiceNow news on Nov. 5, when software stocks slid again, or on Nov. 17, when Salesforce led a software selloff ahead of Anthropic’s expected IPO.
Salesforce, down 19% on the same AI fear, trades at about 13x forward earnings, roughly half its 27x five-year average. Its Dec. 2 report will show whether its AI agents are adding to growth.
TIKR tracks 49 analysts on ServiceNow. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on ServiceNow, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See ServiceNow’s Analyst Ratings
Is it a buy at 22x?
ServiceNow’s forward P/E is about 22x, less than half its 52x five-year average:

At today’s price, it’s even lower, near April’s low of 20x. The consensus target has fallen to $156 from $231 a year ago:
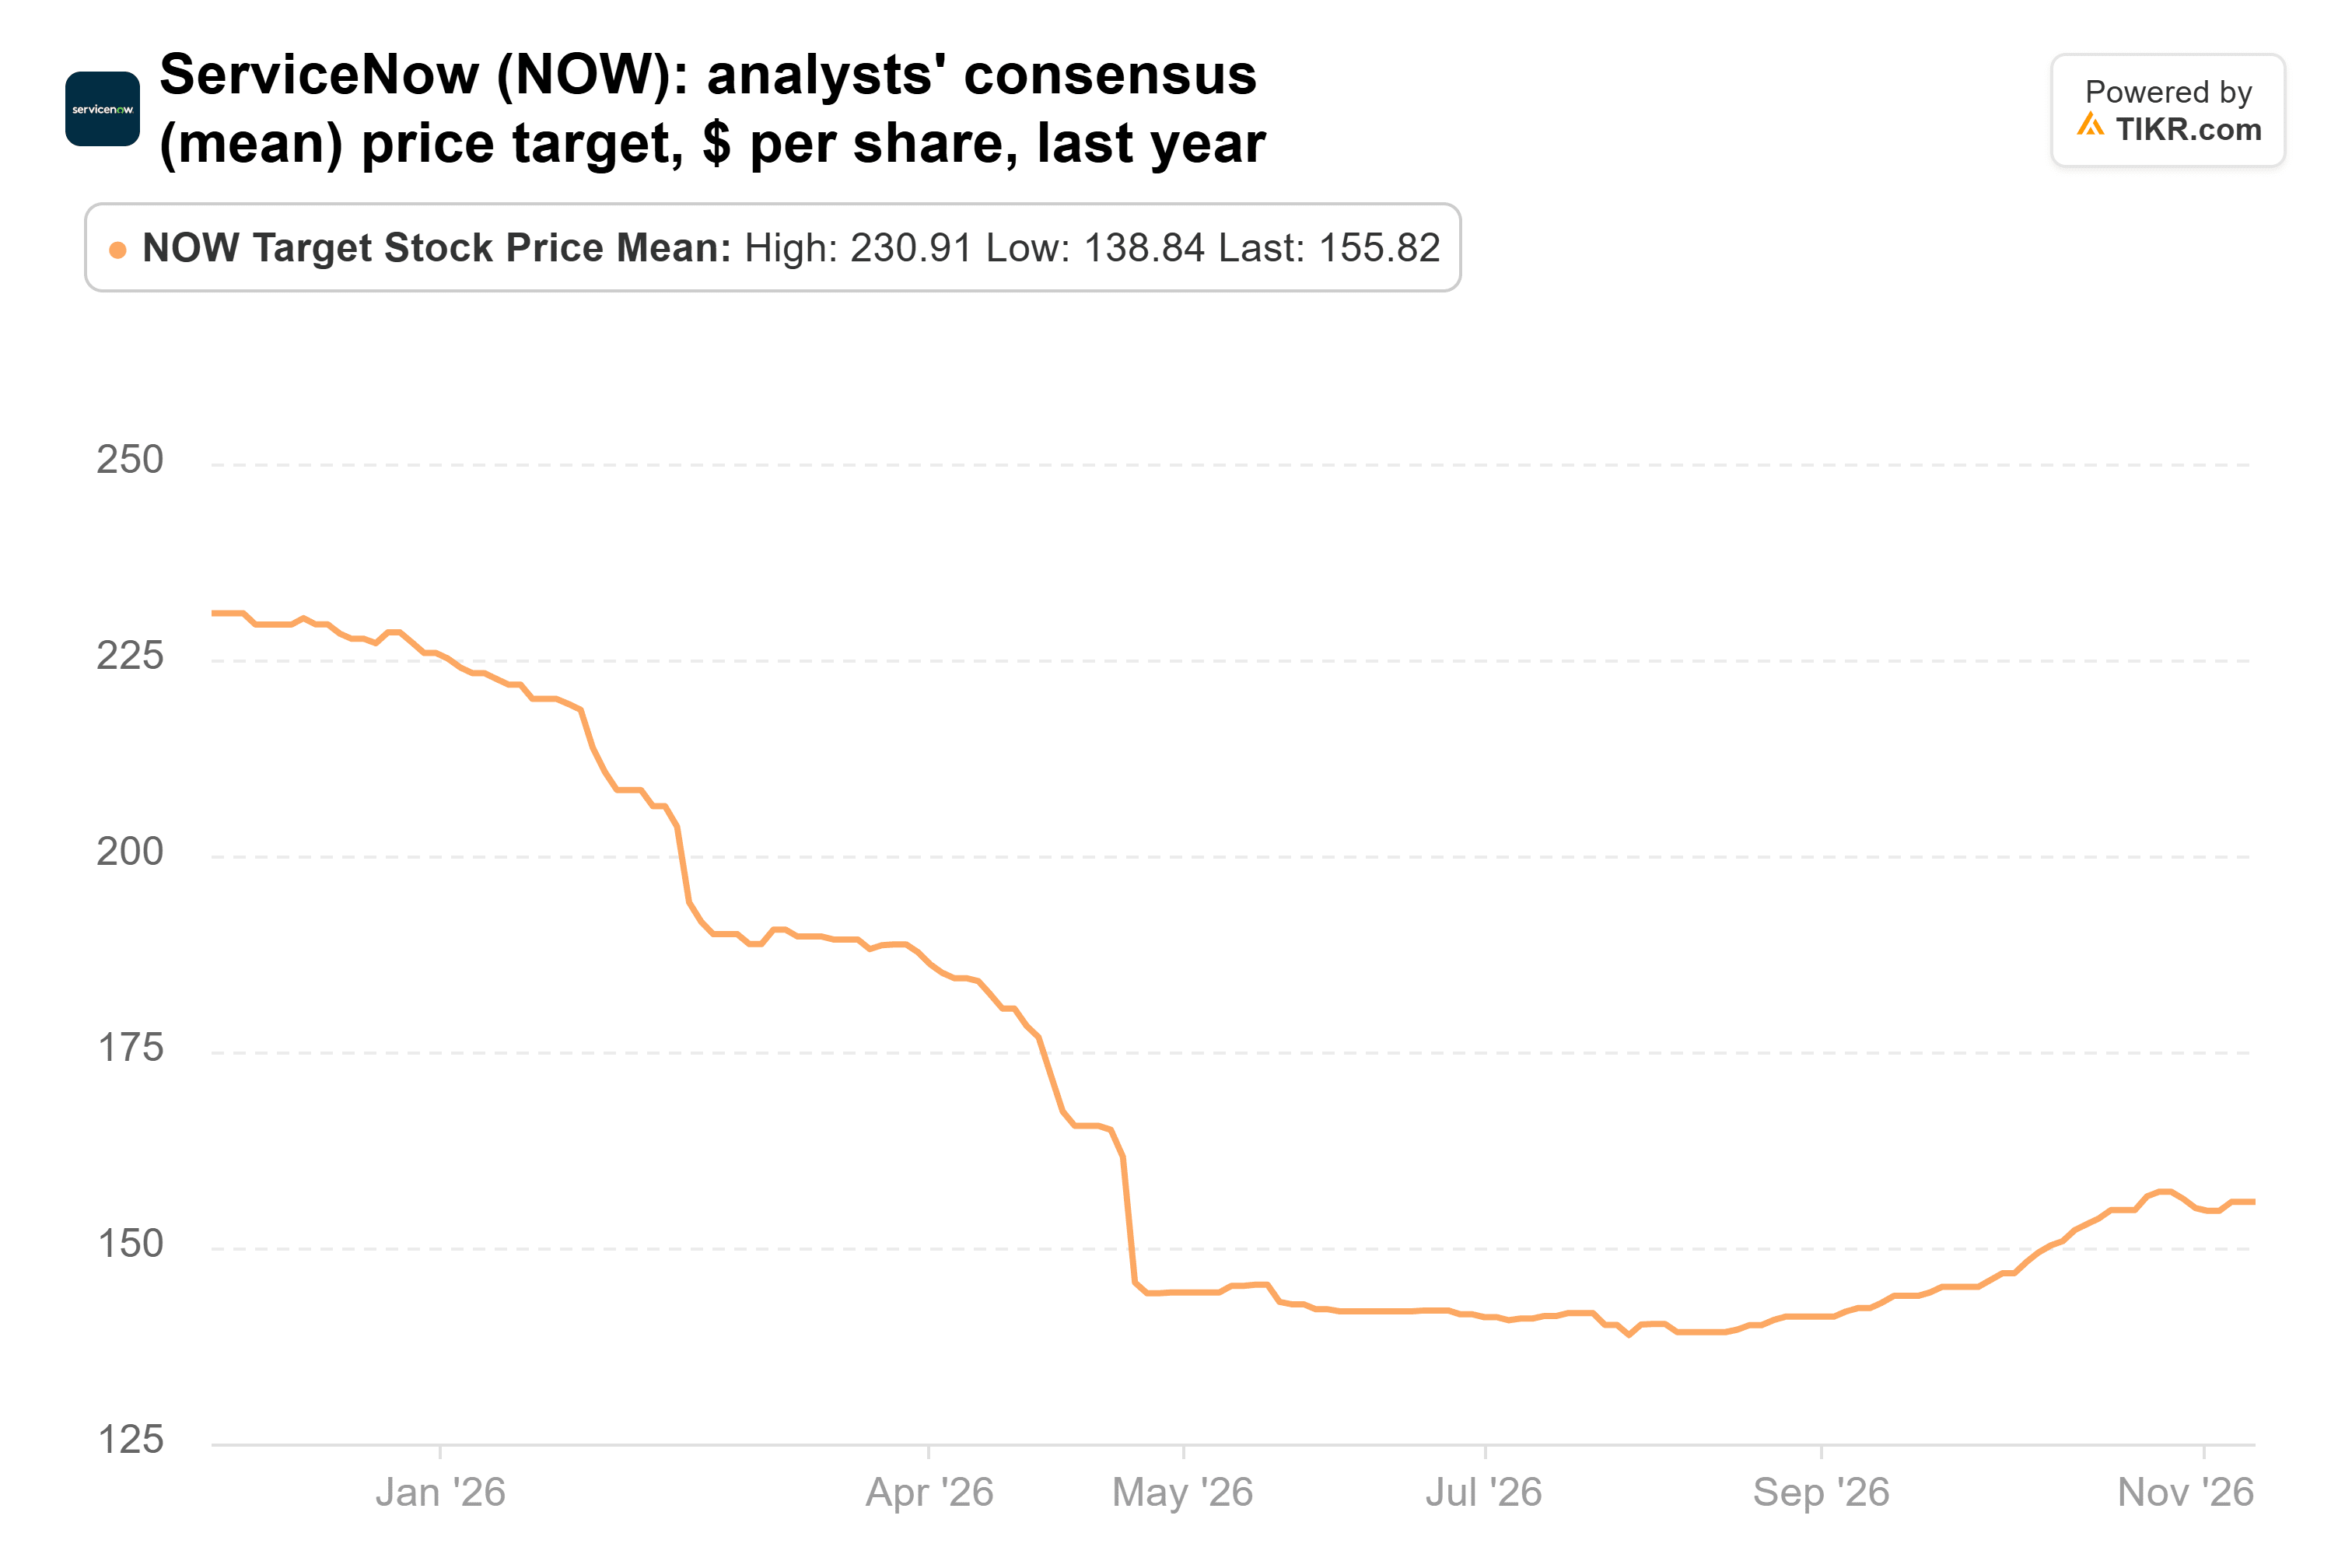
That’s still more than 60% above the stock.
The risk is that AI agents shrink seat counts, and a slower backlog would be the first sign. But a two-point slowdown with a pricing change behind it doesn’t justify losing a third of its value. I’d buy here. The late-January report is the test: cRPO growth needs to come in at or above 18.5%, and the first 2027 subscription guide needs to land near 20%.
So what is ServiceNow stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ServiceNow could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



