Key Takeaways
- Freedom Capital Markets downgraded Qualcomm to Hold from Buy on Nov. 9 and cut its price target to $185 from $200, the same as the consensus target.
- The downgrade came after a fiscal fourth quarter in which handset chip revenue fell 26%. Qualcomm’s earnings guidance for the December quarter was also well below a year earlier.
- Analysts have cut their fiscal 2027 estimate to $9.59 a share from $10.17 on Nov. 5, below the $10.54 Qualcomm earned in fiscal 2026.
- Freedom’s caution looks justified: a $185 target already asks for about 19x fiscal 2027 earnings, well above Qualcomm’s five-year average of 14x, on estimates that are still falling.
Qualcomm (QCOM) is down 29% from its May 29 closing high, and Freedom Capital Markets just stepped back. On Nov. 9, the firm downgraded the stock to Hold from Buy and cut its price target to $185 from $200, 4% above the Nov. 12 close of $177.14.
Handsets did the damage
Qualcomm’s fiscal fourth quarter, reported Nov. 4, pulled in two directions. Handset chip revenue fell 26% from a year earlier to $5.1 billion, while automotive revenue jumped 89% to a record $1.99 billion. The chip unit’s pretax margin slipped to 24% from 29%.
The outlook hurt more. Qualcomm guided December-quarter non-GAAP EPS of $2.15 to $2.35, against $3.50 a year earlier, and management said December will no longer be its biggest quarter as Apple sales wind down. It also said the price increases meant to cover higher wafer, packaging and memory costs won’t fully reach chip margins until the second half of fiscal 2027. The stock fell 9.5% on Nov. 5, the day after the report.
CEO Cristiano Amon reiterated the $5 billion data center target for fiscal 2027, and has since said that ramp is limited by supply.
Freedom thinks the surprises are over
Freedom analyst Egor Tolmachev said the fourth quarter removed “most of the uncertainties that have weighed on Qualcomm.” But the answers were mostly bad ones. Tolmachev expects the push into new growth markets to cost more margin, for longer, than Freedom had assumed. The firm raised its revenue forecasts but cut its non-GAAP EPS estimates by about 3% for fiscal 2027 and 8% for fiscal 2028.
TIKR tracks 37 analysts on Qualcomm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
Does $185 add up?
Freedom’s target sits right on the Street’s. The consensus target is $185, down from $196 as recently as Nov. 2 and $190 a year ago, after a peak near $223 in mid-July:
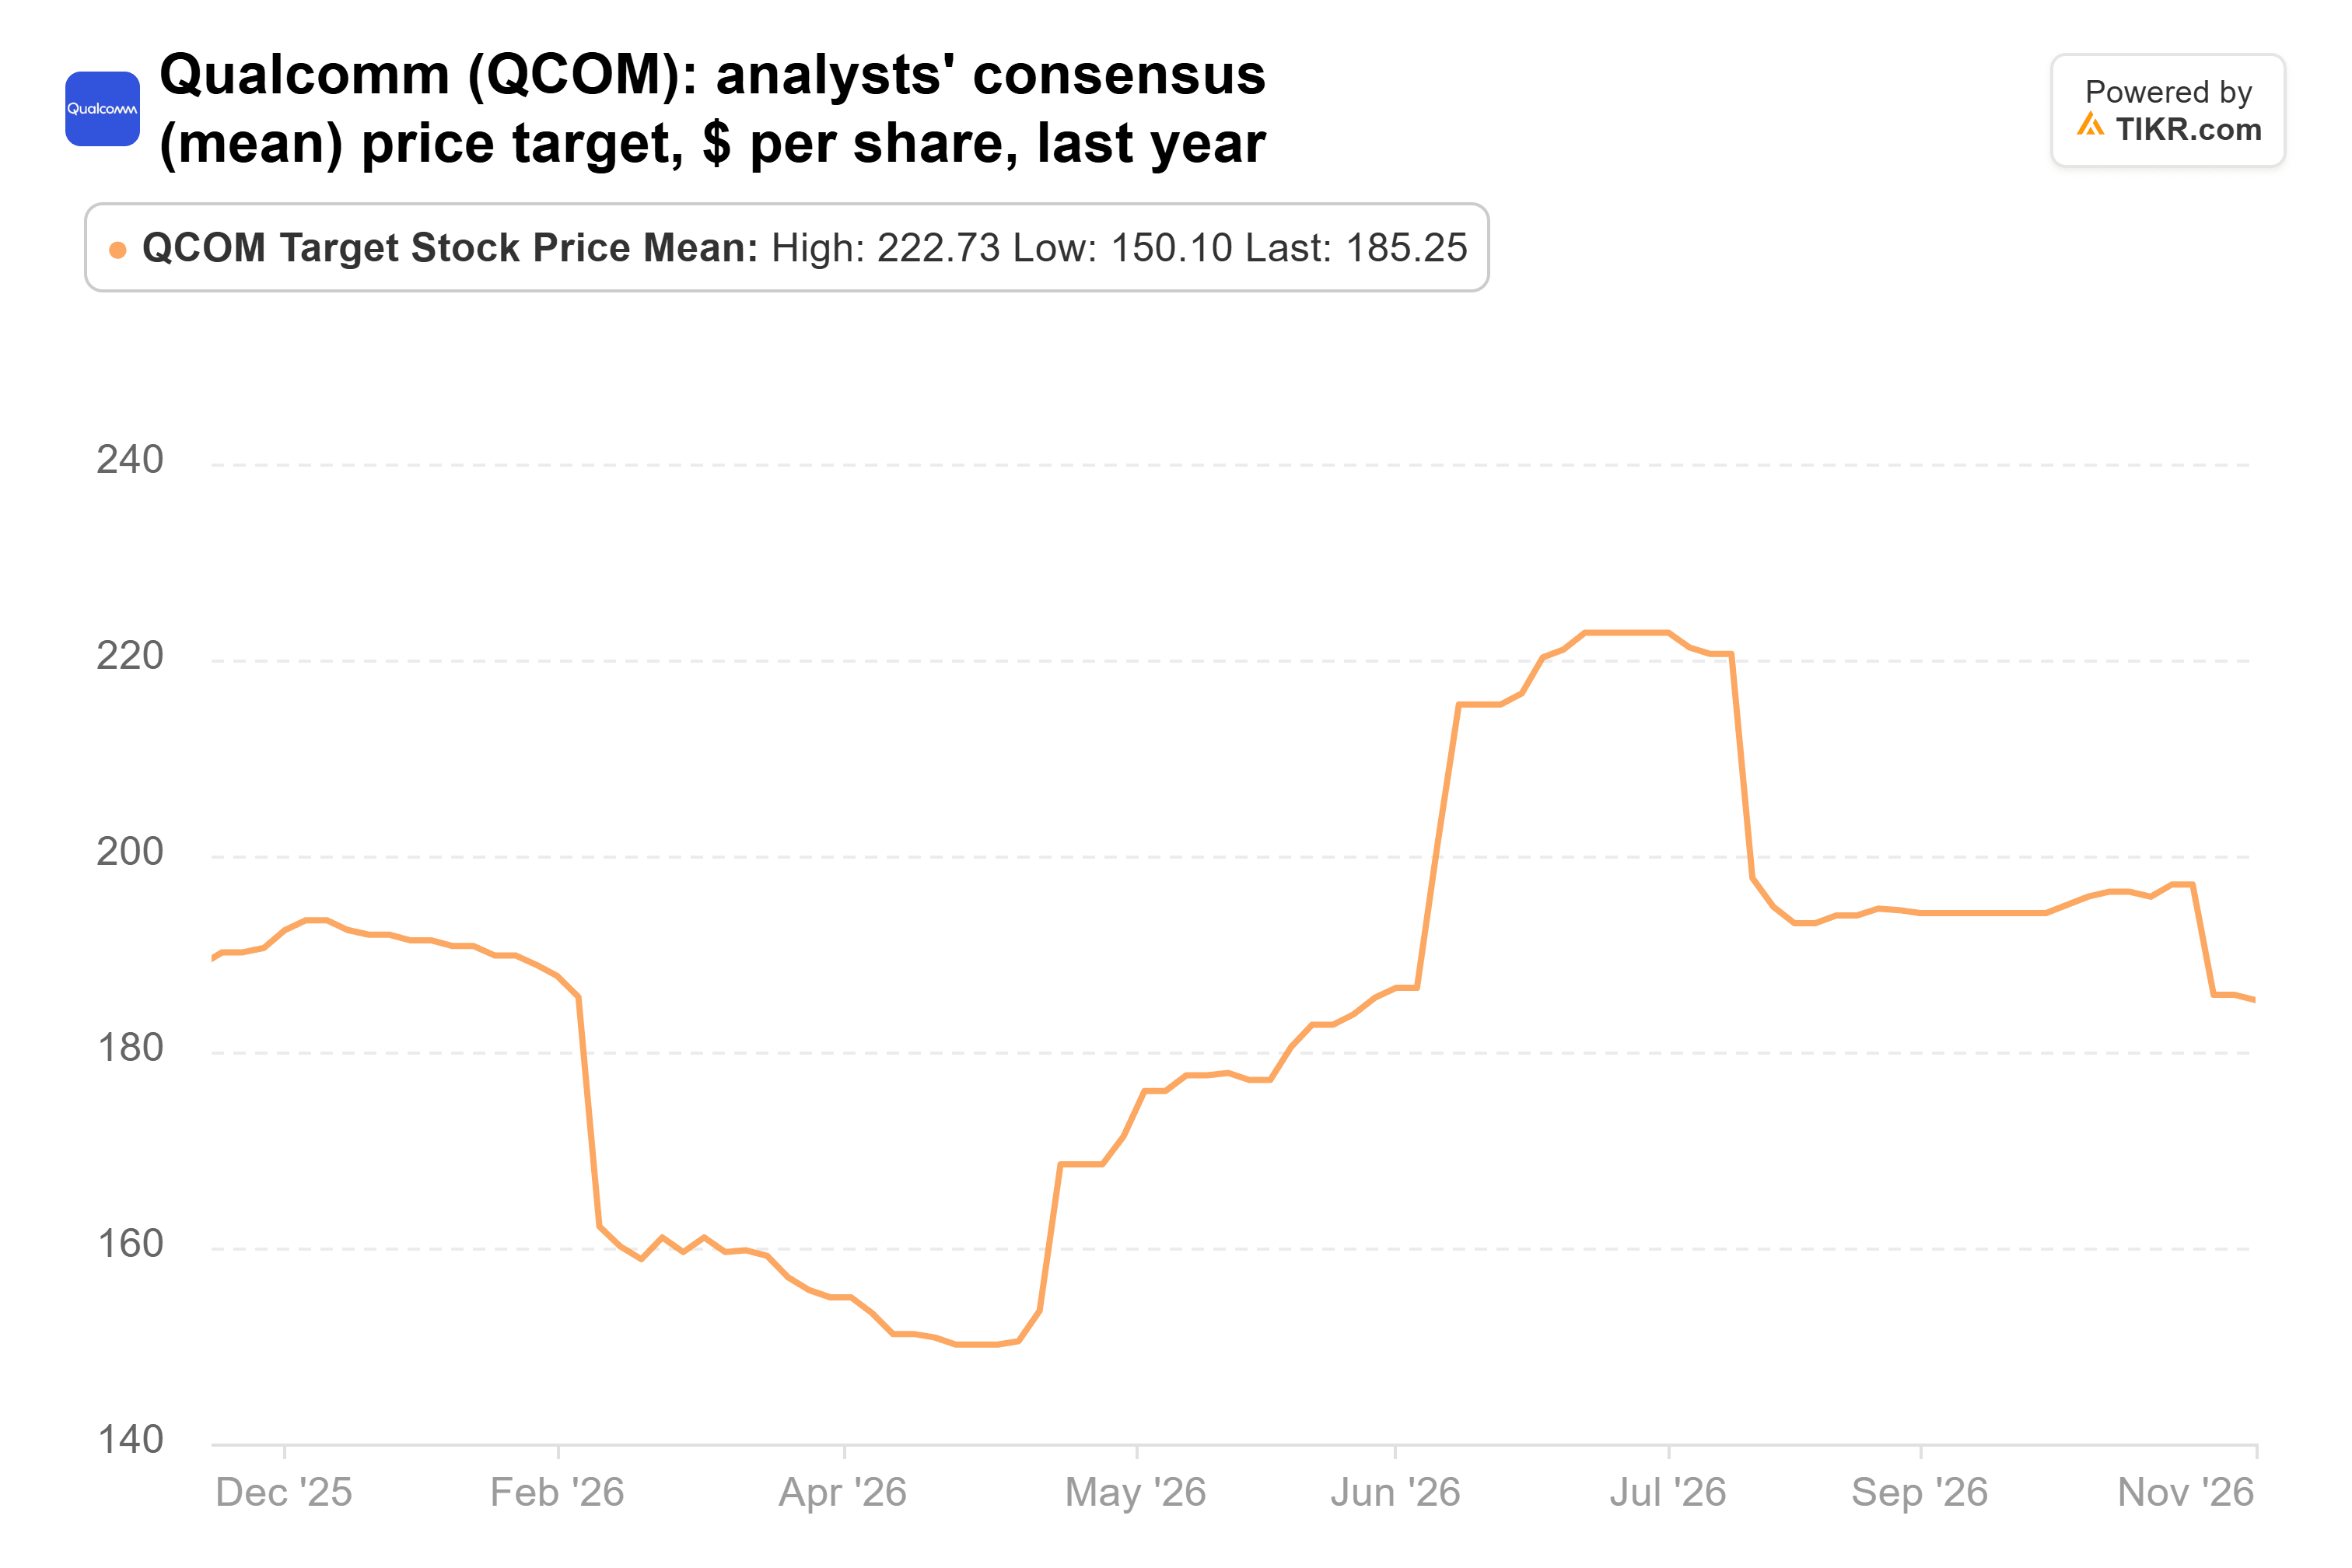
Analysts’ individual targets run from $100 to $320.
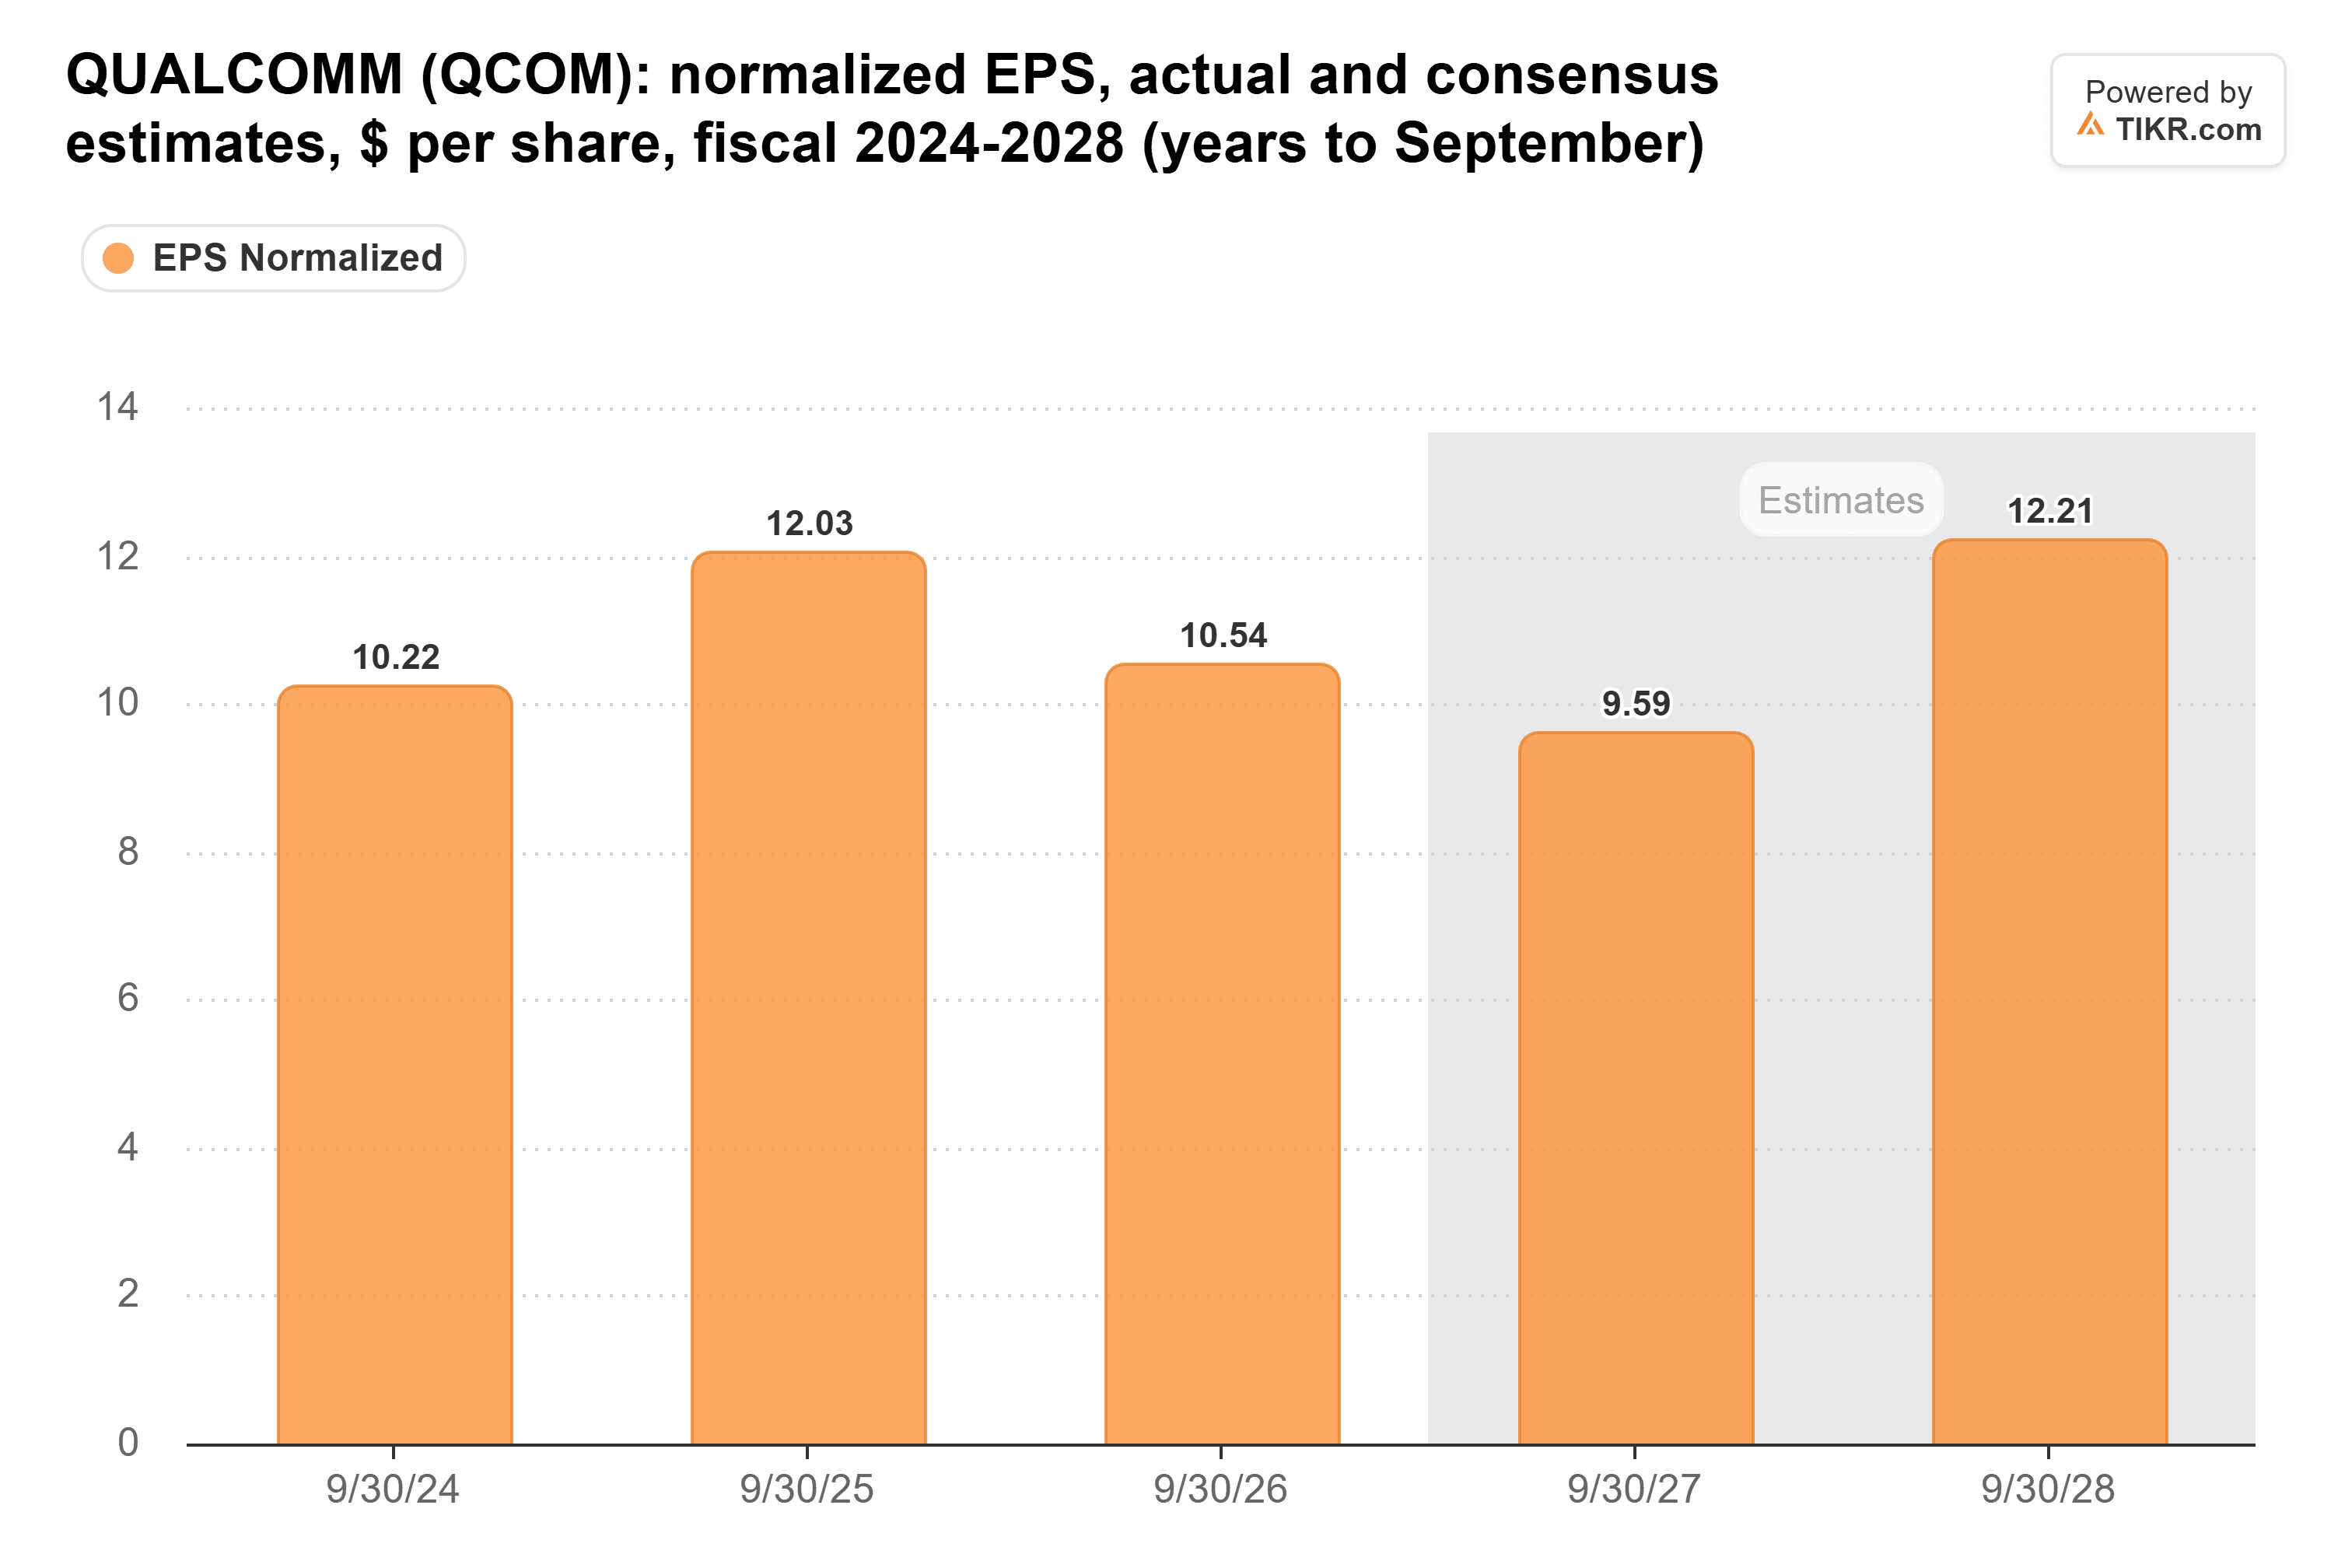
The estimates are moving the wrong way. Analysts now expect $9.59 a share in fiscal 2027, down from $10.17 on Nov. 5 and below the $10.54 Qualcomm earned in fiscal 2026. The fiscal 2028 estimate slipped to $12.21 from $12.89 over the same stretch. This chart tracks Qualcomm’s normalized EPS from fiscal 2024 through fiscal 2028:
Qualcomm trades at about 18x forward earnings, well above its five-year average of 14x:
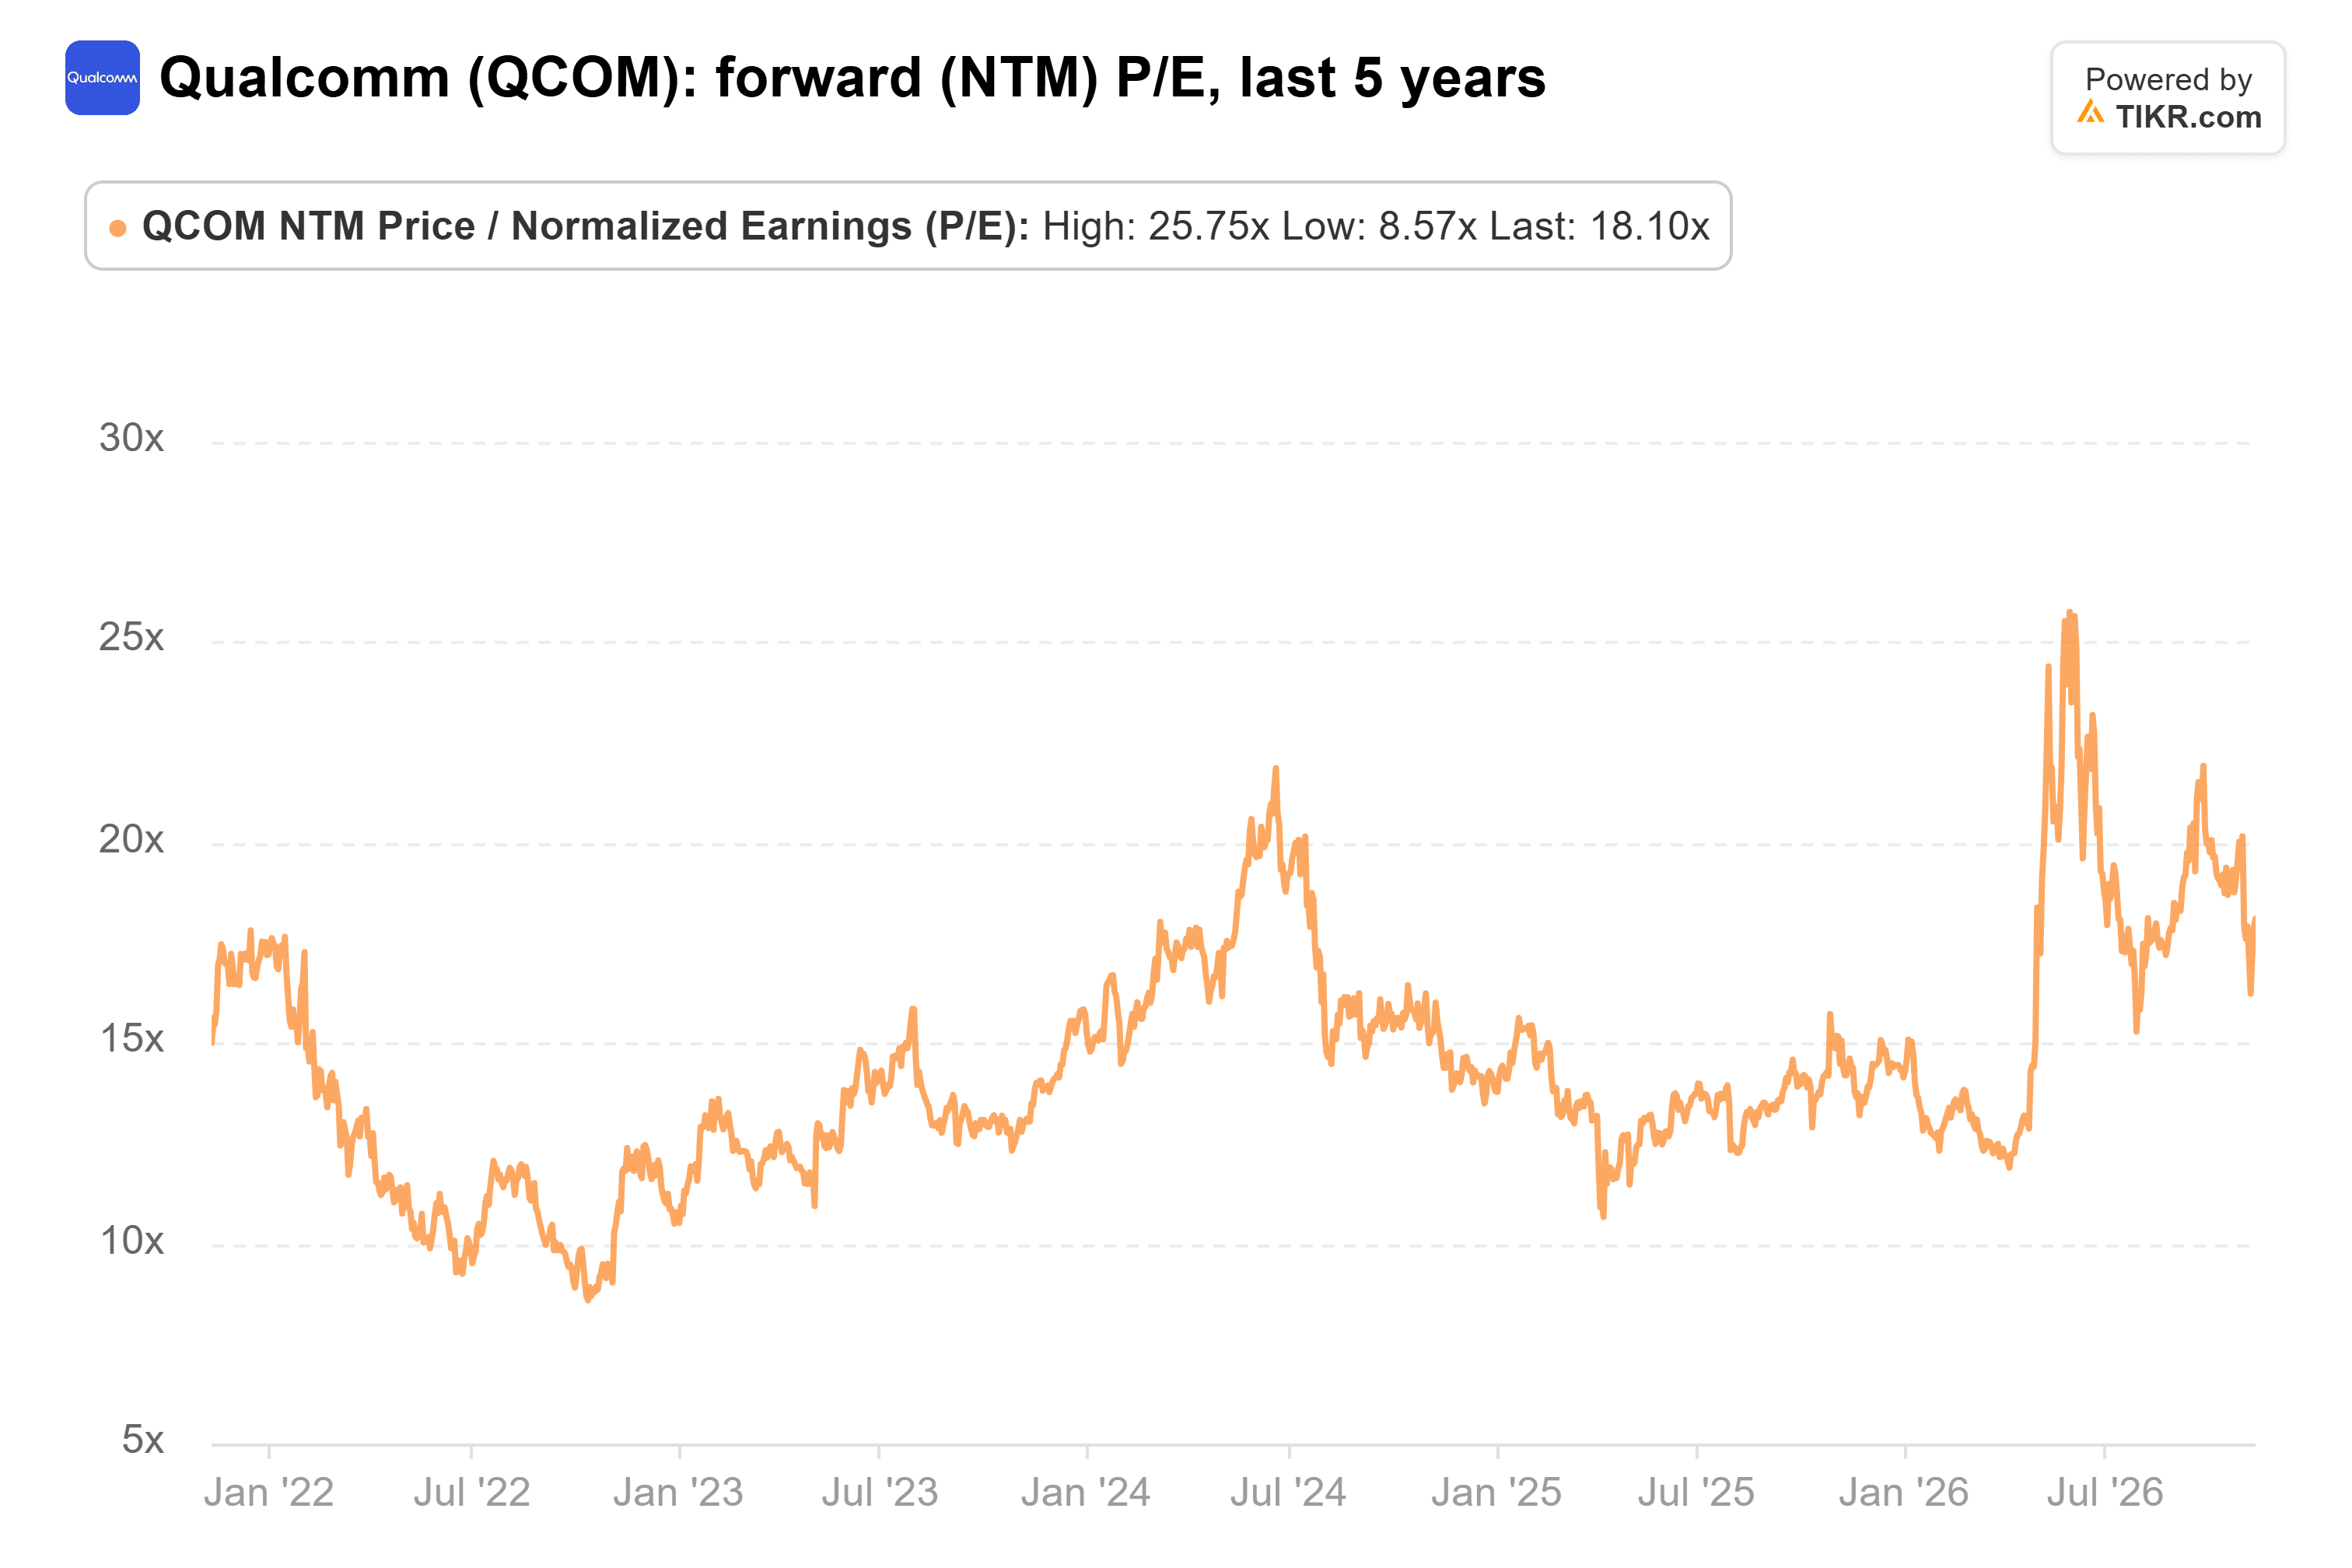
Divide Freedom’s $185 by that $9.59, and the target implies about 19x fiscal 2027 earnings. That’s below May’s peak near 26x, but still above average for earnings that analysts expect to shrink in fiscal 2027.
$185 already asks a lot
The risk to Freedom’s call is data centers. Qualcomm expects more than $650 million in data center revenue in the December quarter as custom chips for two hyperscalers start shipping. If supply allows a faster ramp, $5 billion could prove conservative.
Still, Freedom’s $185, like the Street’s, prices Qualcomm above its usual multiple on estimates that are still falling, which makes the downgrade look reasonable rather than early. The December-quarter report, due in early February, will show whether price increases are landing in chip margins and how much data center revenue has arrived.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!