Key Stats for Qualcomm Stock
- Current Price: $184.87
- Target Price (Mid): ~$388
- Street Target: ~$194
- Potential Total Return: ~110%
- Annualized IRR: ~20% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Huawei has paid Qualcomm (QCOM) for patents since 2001. On October 5, 2026, Huawei said that flow is reversing: Qualcomm agreed to pay to license and acquire Huawei patents for the first time. The deal is a multi-year cross license covering 5G, compute, AI, and networking.
Terms were not disclosed, and the patent purchase closes only after regulatory approval. Shares traded higher overnight before the October 5 open, after closing at $184.87 on October 2.
Huawei Is Now the One Getting Paid
Qualcomm’s fiscal 2025 annual report says licensing revenue stopped including Huawei royalties in the second quarter of fiscal 2025, after the license expired. The new deal adds no disclosed royalty income to replace them. Huawei said the agreement, its first with Qualcomm covering 5G, should lift its own licensing contract value above $6.9 billion. In 2020, the money moved the other way, when Huawei paid Qualcomm $1.8 billion in back licensing fees.
John Han, Executive Vice President and General Manager of Qualcomm Technology Licensing, said the deal “reaffirms industry recognition of Qualcomm’s 5G technology leadership” and “likewise reflects Qualcomm’s recognition of Huawei’s continued innovation and intellectual property in 5G and other technology fields.” The patents Qualcomm is buying cover compute, AI, and networking, the same fields as its data center push, though Qualcomm has not said how it will use them.
The Same Day, Qualcomm Took Arm to Court Over Its Royalty Bill
Qualcomm’s trial against Arm Holdings (ARM) opened in Delaware federal court on October 5, with Qualcomm seeking to stop paying Arm royalties for up to five years. The allegations remain unproven.
The outcome matters most for Qualcomm’s data center plans. At Goldman Sachs’ Communacopia + Technology Conference on September 8, CFO and COO Akash Palkhiwala put the CPU market at over $200 billion a year, with “about half of that market transitioning over to Arm architecture.” CPUs are one of the four parts of Qualcomm’s data center strategy, so Arm’s royalty terms shape that business’s costs.
See historical and forward estimates for Qualcomm stock (It’s free!) >>>
The Margin Target Now Has Two New Variables
Palkhiwala said OpEx should trail revenue growth, supporting a 30% operating margin target about three years out. TIKR consensus EBIT margin rises from around 28% in fiscal 2027 to around 32% in fiscal 2029. Neither the Huawei payments nor the Arm outcome has a public figure that analysts could model yet.
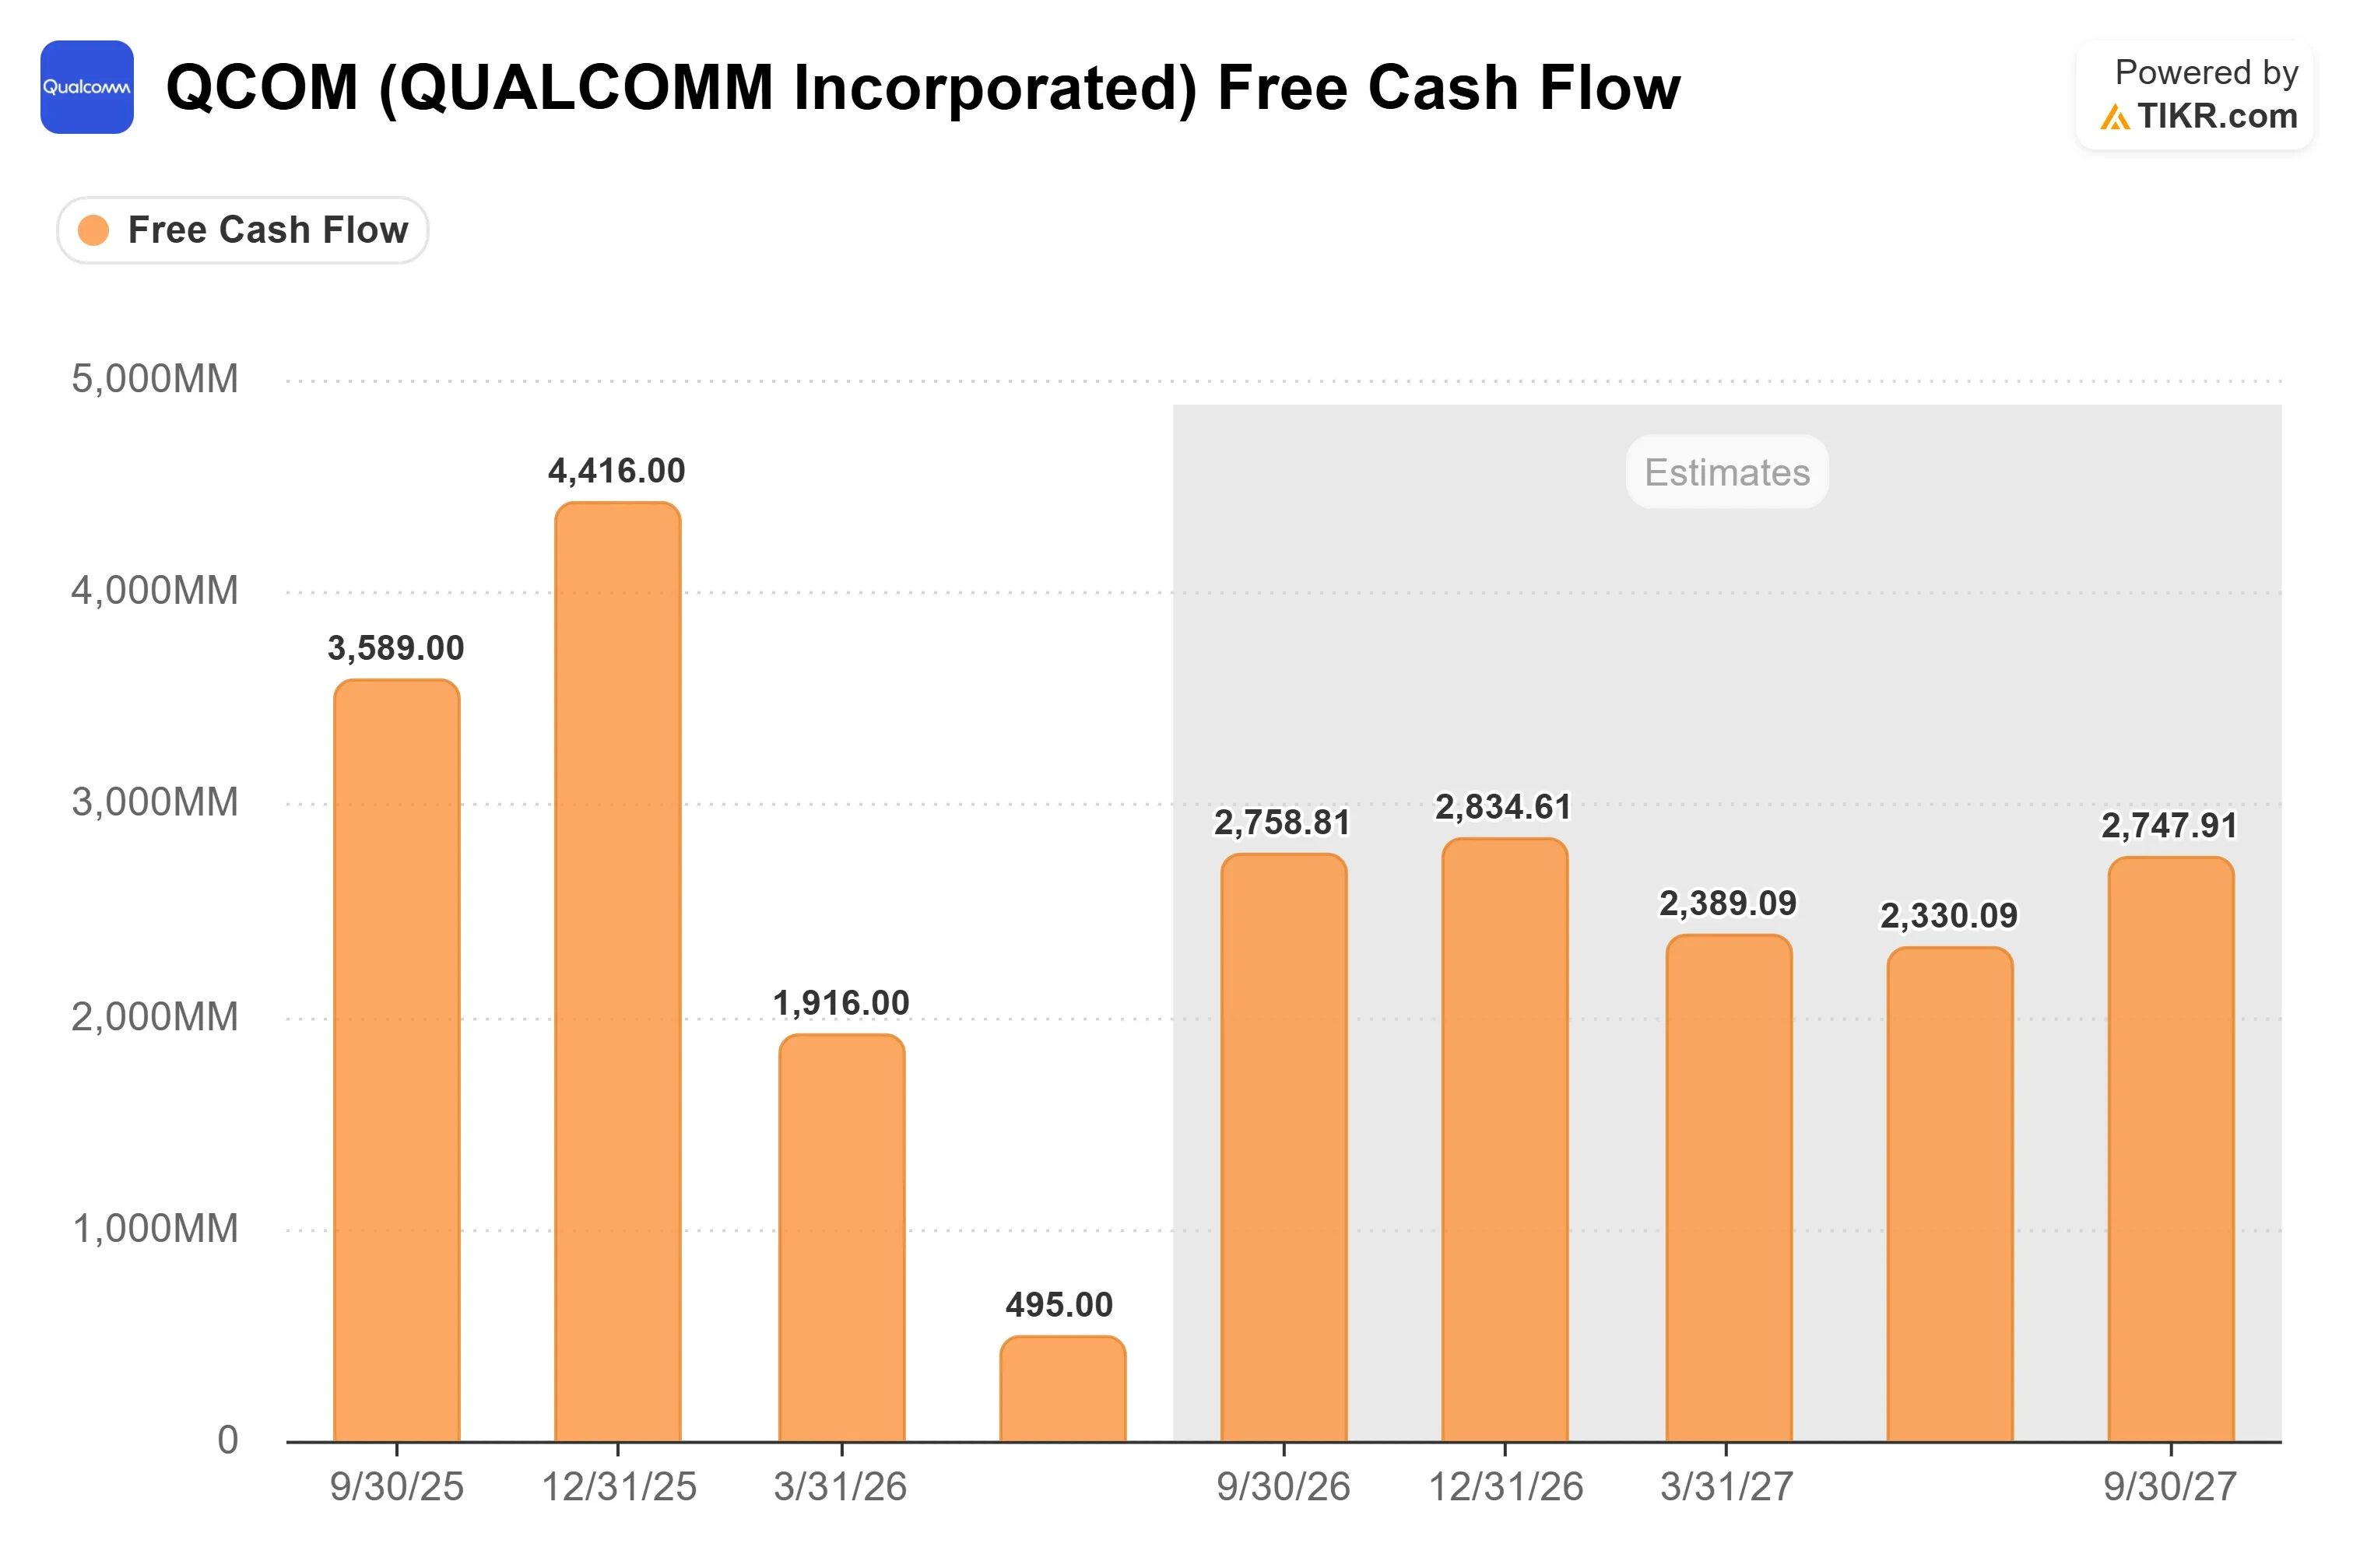
Cash conversion is the near-term risk. Free cash flow missed Street estimates in three of the last five quarters, including $495 million against $2.43 billion in fiscal Q3 2026.

See how Qualcomm performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $184.87
- Target Price (Mid): ~$388
- Potential Total Return: ~110%
- Annualized IRR: ~20% / year

See analysts’ growth forecasts and price targets for Qualcomm stock (It’s free!) >>>
TIKR’s mid-case values Qualcomm at around $388 by September 30, 2030, about 110% above the October 2 close, or around 20% a year over four years. Two items with no public figures could move that path. A ruling that cuts ARM royalties would help margins, while Huawei licensing costs, once disclosed, would work the other way.
Conclusion
The Delaware verdict and fiscal fourth-quarter results in early November, on a date Qualcomm has not yet announced, are the next tests. Adjusted EPS at or above the ~$2.16 consensus, inside Qualcomm’s $2.05 to $2.25 guide, would show the core business holding while these costs get sorted out. Any first disclosure of Huawei licensing costs will show how much the reversal weighs on the margin target.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Qualcomm on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!