

Key Takeaways
- At today’s prices, about 2,703 shares of Altria, or roughly $210,600, pay $1,000 a month in dividends. Philip Morris International takes about 1,875 shares, or roughly $368,700.
- Altria’s 5.7% yield gets a retiree to that income for about $158,100 less than Philip Morris’s 3.3%.
- Altria’s dividend is the less covered of the two, using 78% of free cash flow over the twelve months to Sept. 30, against 68% at Philip Morris.
- Philip Morris’s business is growing faster, but Altria’s steady payout and lower cost make its check the better deal for a retiree.
If you want $1,000 a month in dividends from one stock, two of the best-known income names in the market get you there at very different prices.
Let’s take a hypothetical retiree who wants that $1,000 a month, or $12,000 a year, from a single tobacco stock. Altria needs about 2,703 shares of Altria Group (MO), roughly $210,600 at a 5.7% yield. Philip Morris needs about 1,875 shares of Philip Morris International (PM), roughly $368,700 at a 3.3% yield.
So Altria gets you the same income for about $158,100 less. The real question is which dividend check a retiree can count on.
| Stock | Dividend a share, per year | Shares | Cost | Yield | Income a month | Cash dividend payout ratio (TTM to Sept. 30) |
|---|---|---|---|---|---|---|
| Altria Group (MO) | $4.44 | 2,703 | $210,618 | 5.7% | $1,000 | 78% |
| Philip Morris International (PM) | $6.40 | 1,875 | $368,738 | 3.3% | $1,000 | 68% |
Source: TIKR and company figures, at today’s prices.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Altria pays a lot from a business that’s barely growing
Altria’s net revenue rose just 1.0% to $6.1 billion in the third quarter from a year before. Fewer cigarettes shipped, and Copenhagen and Skoal kept losing users to nicotine pouches. Its profits are still inching up, though. Adjusted EPS grew 4.8% to $1.52, and on Oct. 29 management raised its full-year forecast to $5.66 to $5.74, or 4.5% to 6.0% growth from 2025’s $5.42.
Part of that comes from holding on to Marlboro smokers who are feeling the pinch. On the third-quarter call, CEO Salvatore Mancuso said Marlboro’s Cowboy Cut “provides a premium Marlboro option at the right price to retain value-sensitive smokers within that franchise.” Pouches are the harder part. On! shipments rose 13.3% in the quarter, but adjusted operating income in Altria’s oral tobacco segment fell 3.7% to $443 million.
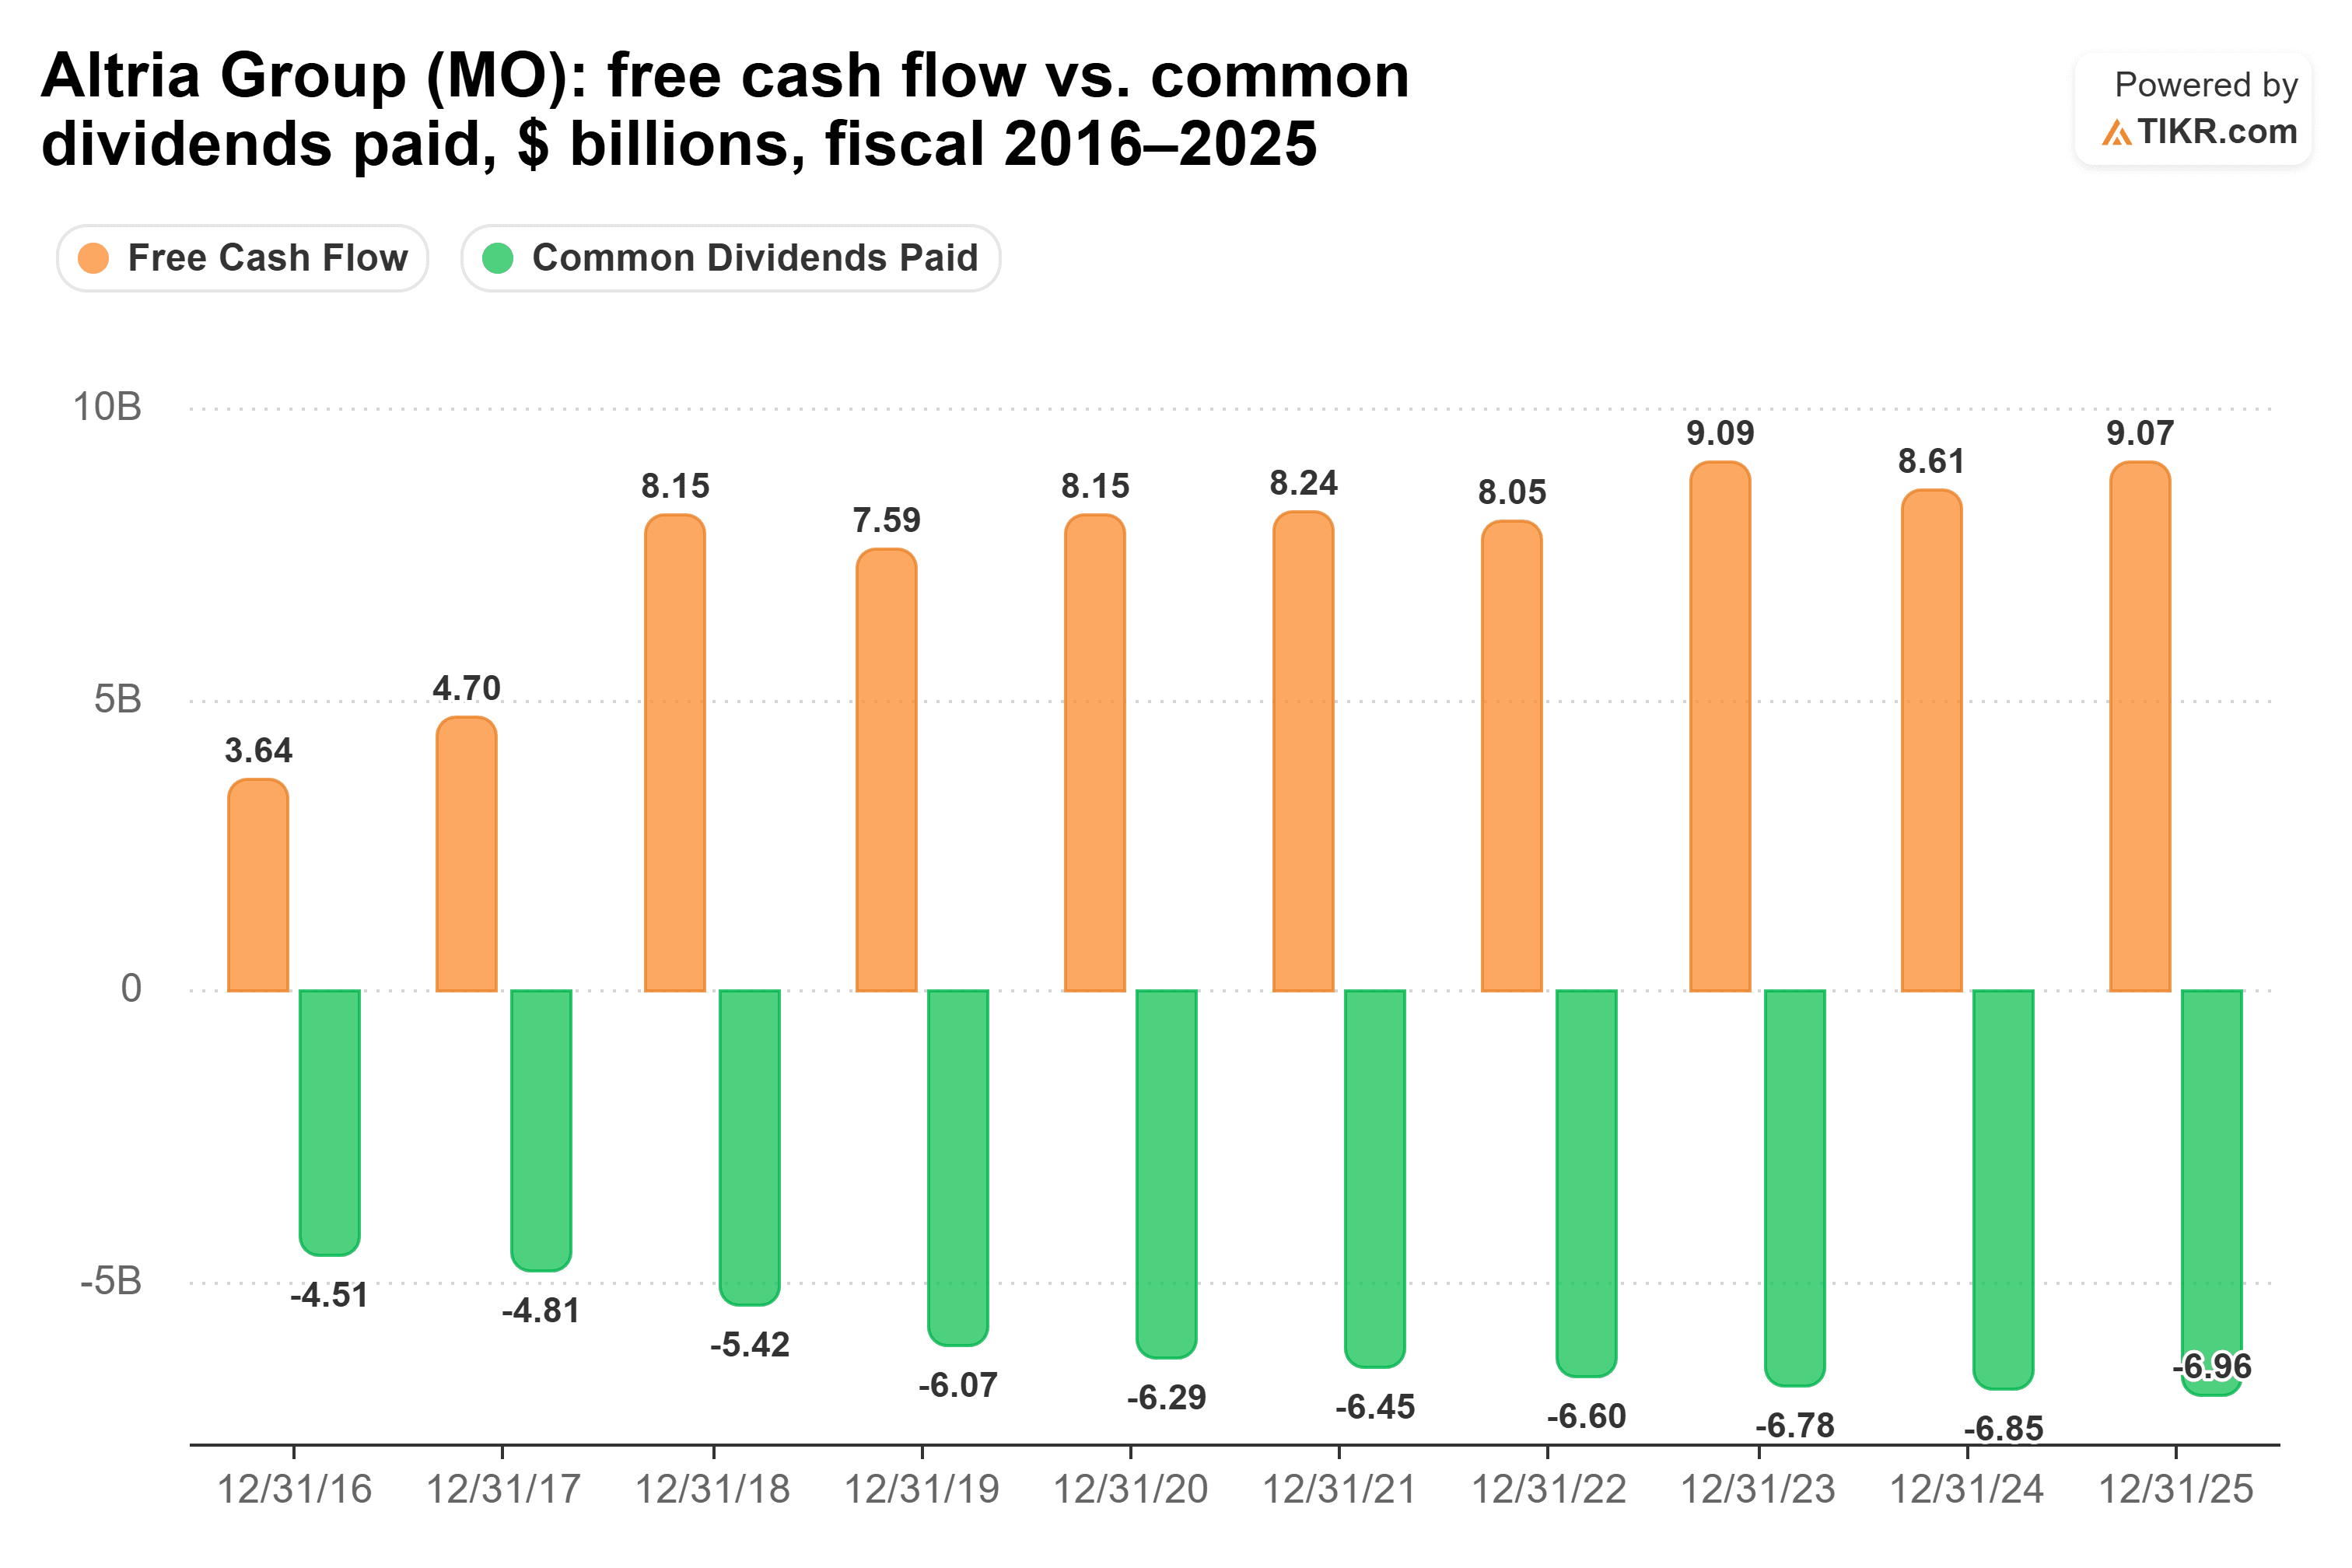
In August, the board raised the quarterly dividend 4.7% to $1.11 a share. That was Altria’s 61st increase in 57 years, and it fits the company’s goal of mid-single-digit dividend growth every year through 2028. Over the twelve months to Sept. 30, the dividend ate up 78% of free cash flow, and the payout ratio has stayed between 75% and 82% every fiscal year since 2021. Free cash flow has covered the dividend every year since fiscal 2018, after falling short in fiscal 2016 and 2017.
With Philip Morris, you’re paying for growth
Philip Morris’s check costs far more, and what that buys is a business that’s still growing. Its net revenue rose 5.5% (7.1% organically) to $11.4 billion in the third quarter from a year before, and adjusted EPS grew 5.4% to $2.36. Smoke-free products like IQOS, ZYN and VEEV made up more than 40% of net revenue in the quarter.
That growth costs money, though. When it reported on Oct. 21, Philip Morris updated its full-year adjusted EPS forecast for currency, to $8.29 to $8.44, or 9.9% to 11.9% growth. Management also pointed to rising energy costs, geopolitical tension and heavier spending behind ZYN in the US. It expects its US segment’s adjusted operating income to land around zero, or slightly negative, in the fourth quarter as it spends to expand ZYN’s range.
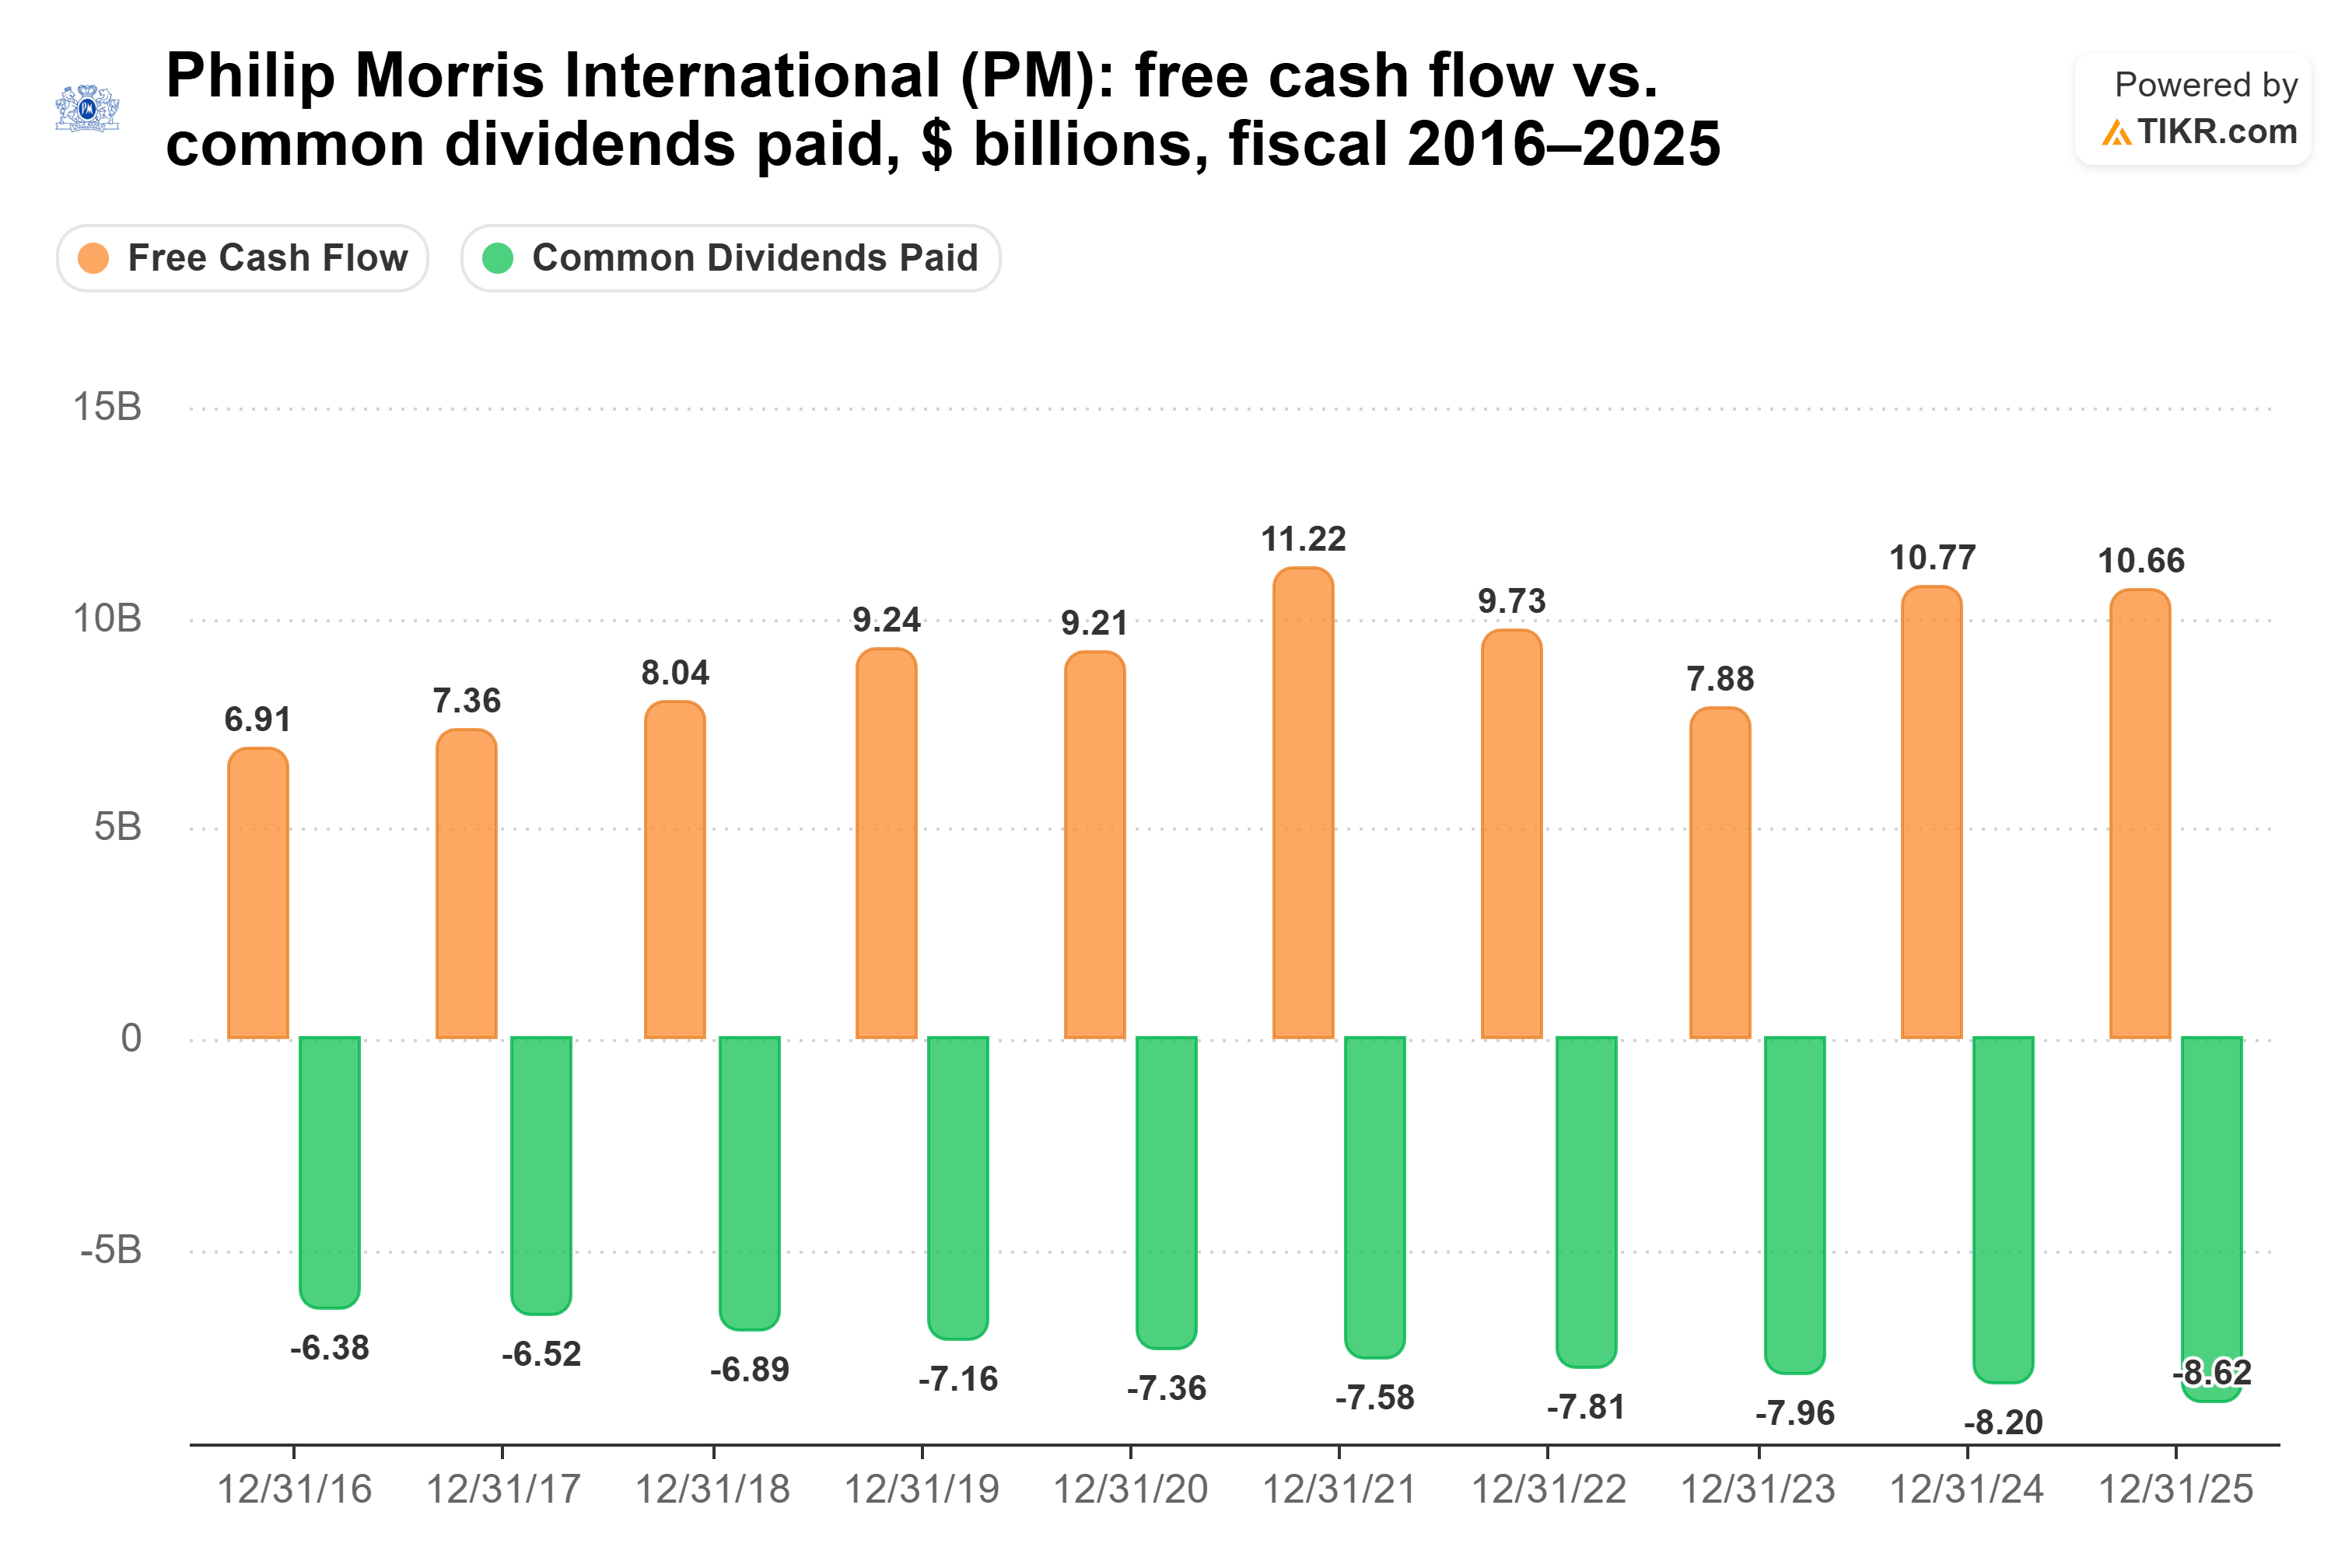
On Sept. 18, Philip Morris raised its quarterly dividend 8.8% to $1.60 a share, which the company counts as its 19th straight yearly raise. Over the twelve months to Sept. 30, the dividend ate up a more comfortable 68% of free cash flow. Its record is lumpier than Altria’s, though. The payout ratio was 81% in fiscal 2025, and fiscal 2023 was the one year in the last ten when the dividend outran free cash flow.
It’s also carrying a bit more debt, at 2.0x net debt to EBITDA against Altria’s 1.7x, and it isn’t buying back any stock this year.
I’d take the cheaper check
I’d go with Altria. Getting to $1,000 a month for that much less leaves a retiree a lot of money for the rest of a portfolio. Altria’s dividend has also grown faster: 4.1% a year from fiscal 2020 to fiscal 2025, against 3.5% at Philip Morris. At those rates, Altria’s shares would pay about $17,300 a year in year 10, and Philip Morris’s about $16,400.
Altria’s is the less covered of the two checks, so it’s the one most at risk of a cut. Being the most at risk of these two doesn’t mean it’s truly risky, though. A payout ratio that has held in that range for five years supports it, as do interest coverage of 10.9x over the last twelve months and an earnings forecast that went up in October. The risk is the slow one: fewer cigarettes every year, and pouch profits that slipped in the third quarter.
Philip Morris has a strong case of its own. Its business is growing, its dividend eats up a smaller share of its free cash flow today, and its 8.8% raise was nearly twice Altria’s 4.7%. If raises that size keep coming, its check will grow faster than Altria’s. It’s just that, at today’s prices, I’d rather keep the savings.
Of course, Altria’s next raise should come around August. If it falls short of that mid-single-digit goal, I’d take it as a sign its cash is getting tighter.
Forget Altria Group: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Altria Group isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





