

Key Takeaways
- Hornbeck Offshore CEO Todd Hornbeck bought $1.5 million of stock on Nov. 10 and 11, with shares now 48% below their September high.
- The day before, he called off a planned sale of more than a million shares, which makes the buy a strong vote of confidence.
- The stock has slid through a third-quarter miss and a soft fourth-quarter outlook, while new five-year agreements with Shell add to a $1.9 billion backlog.
- The numbers back his buy at about 10x forward earnings, though only two analysts cover the stock and their estimates dip in 2027.
Hornbeck Offshore Services (HOS) has had a rough start as a public company. The stock hit $11.13 intraday on Sept. 2, its first day of trading after its all-stock merger with Helix Energy Solutions closed. It closed at $5.83 on Nov. 12, down 48% since.
Todd Hornbeck, its president and CEO, just bought more: 280,866 shares at an average $5.34 on Nov. 10 and 11, or $1.5 million in all, according to a Form 4 filed Nov. 12.
A messy first quarter as one company
Most of the bad news since then has been about timing. Third-quarter results on Nov. 4 missed estimates. With only one month of Helix in the quarter, Hornbeck posted an $85.7 million net loss on $119.8 million of merger costs, accelerated stock pay and terminated offering costs. Excluding those, it earned $0.13 a share, short of the $0.20 FactSet consensus, according to MT Newswires.
The outlook looks soft, too: $90-$100 million of fourth-quarter adjusted EBITDA, against $155 million in the third with both companies counted for the full quarter. CFO Potter Adams put much of the gap down to 223 days of regulatory drydock downtime, against 50 in the third quarter, and said the range “should not be annualized from September.” The company guided to 500-550 million for 2027, a heavy drydock year.
Meanwhile, Hornbeck keeps winning work. On Nov. 2, it announced five-year integrated services agreements with Shell (SHEL) in the U.S. Gulf of America, starting in 2027. Todd Hornbeck called it “the first 5-year agreement for a Q vessel in over a decade.” Backlog stood at $1.9 billion on Sept. 30.
See analyst ratings on Hornbeck Offshore Services (it’s free):
See the full breakdown of Buy, Hold, and Sell ratings on Hornbeck Offshore Services, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Hornbeck Offshore Services’ Analyst Ratings
A small add, but a loud signal
The buy lifts his holding to 5,950,514 shares, 5% more than he owned before, worth about $35 million at the Nov. 12 close of $5.83. That’s a modest add. But he did something more telling the day before: on Nov. 9, he terminated a 10b5-1 plan he’d set up on Sept. 1 to sell 1,170,405 shares, with none sold under it. For investors who track what insiders are buying, calling off a sale and buying instead is about as clear a signal as a Form 4 gives.
Do the numbers back him at $5.34?
Analyst estimates for Hornbeck’s normalized earnings average $0.72 a share this year, slipping to $0.54 in 2027 and $0.53 in 2028:
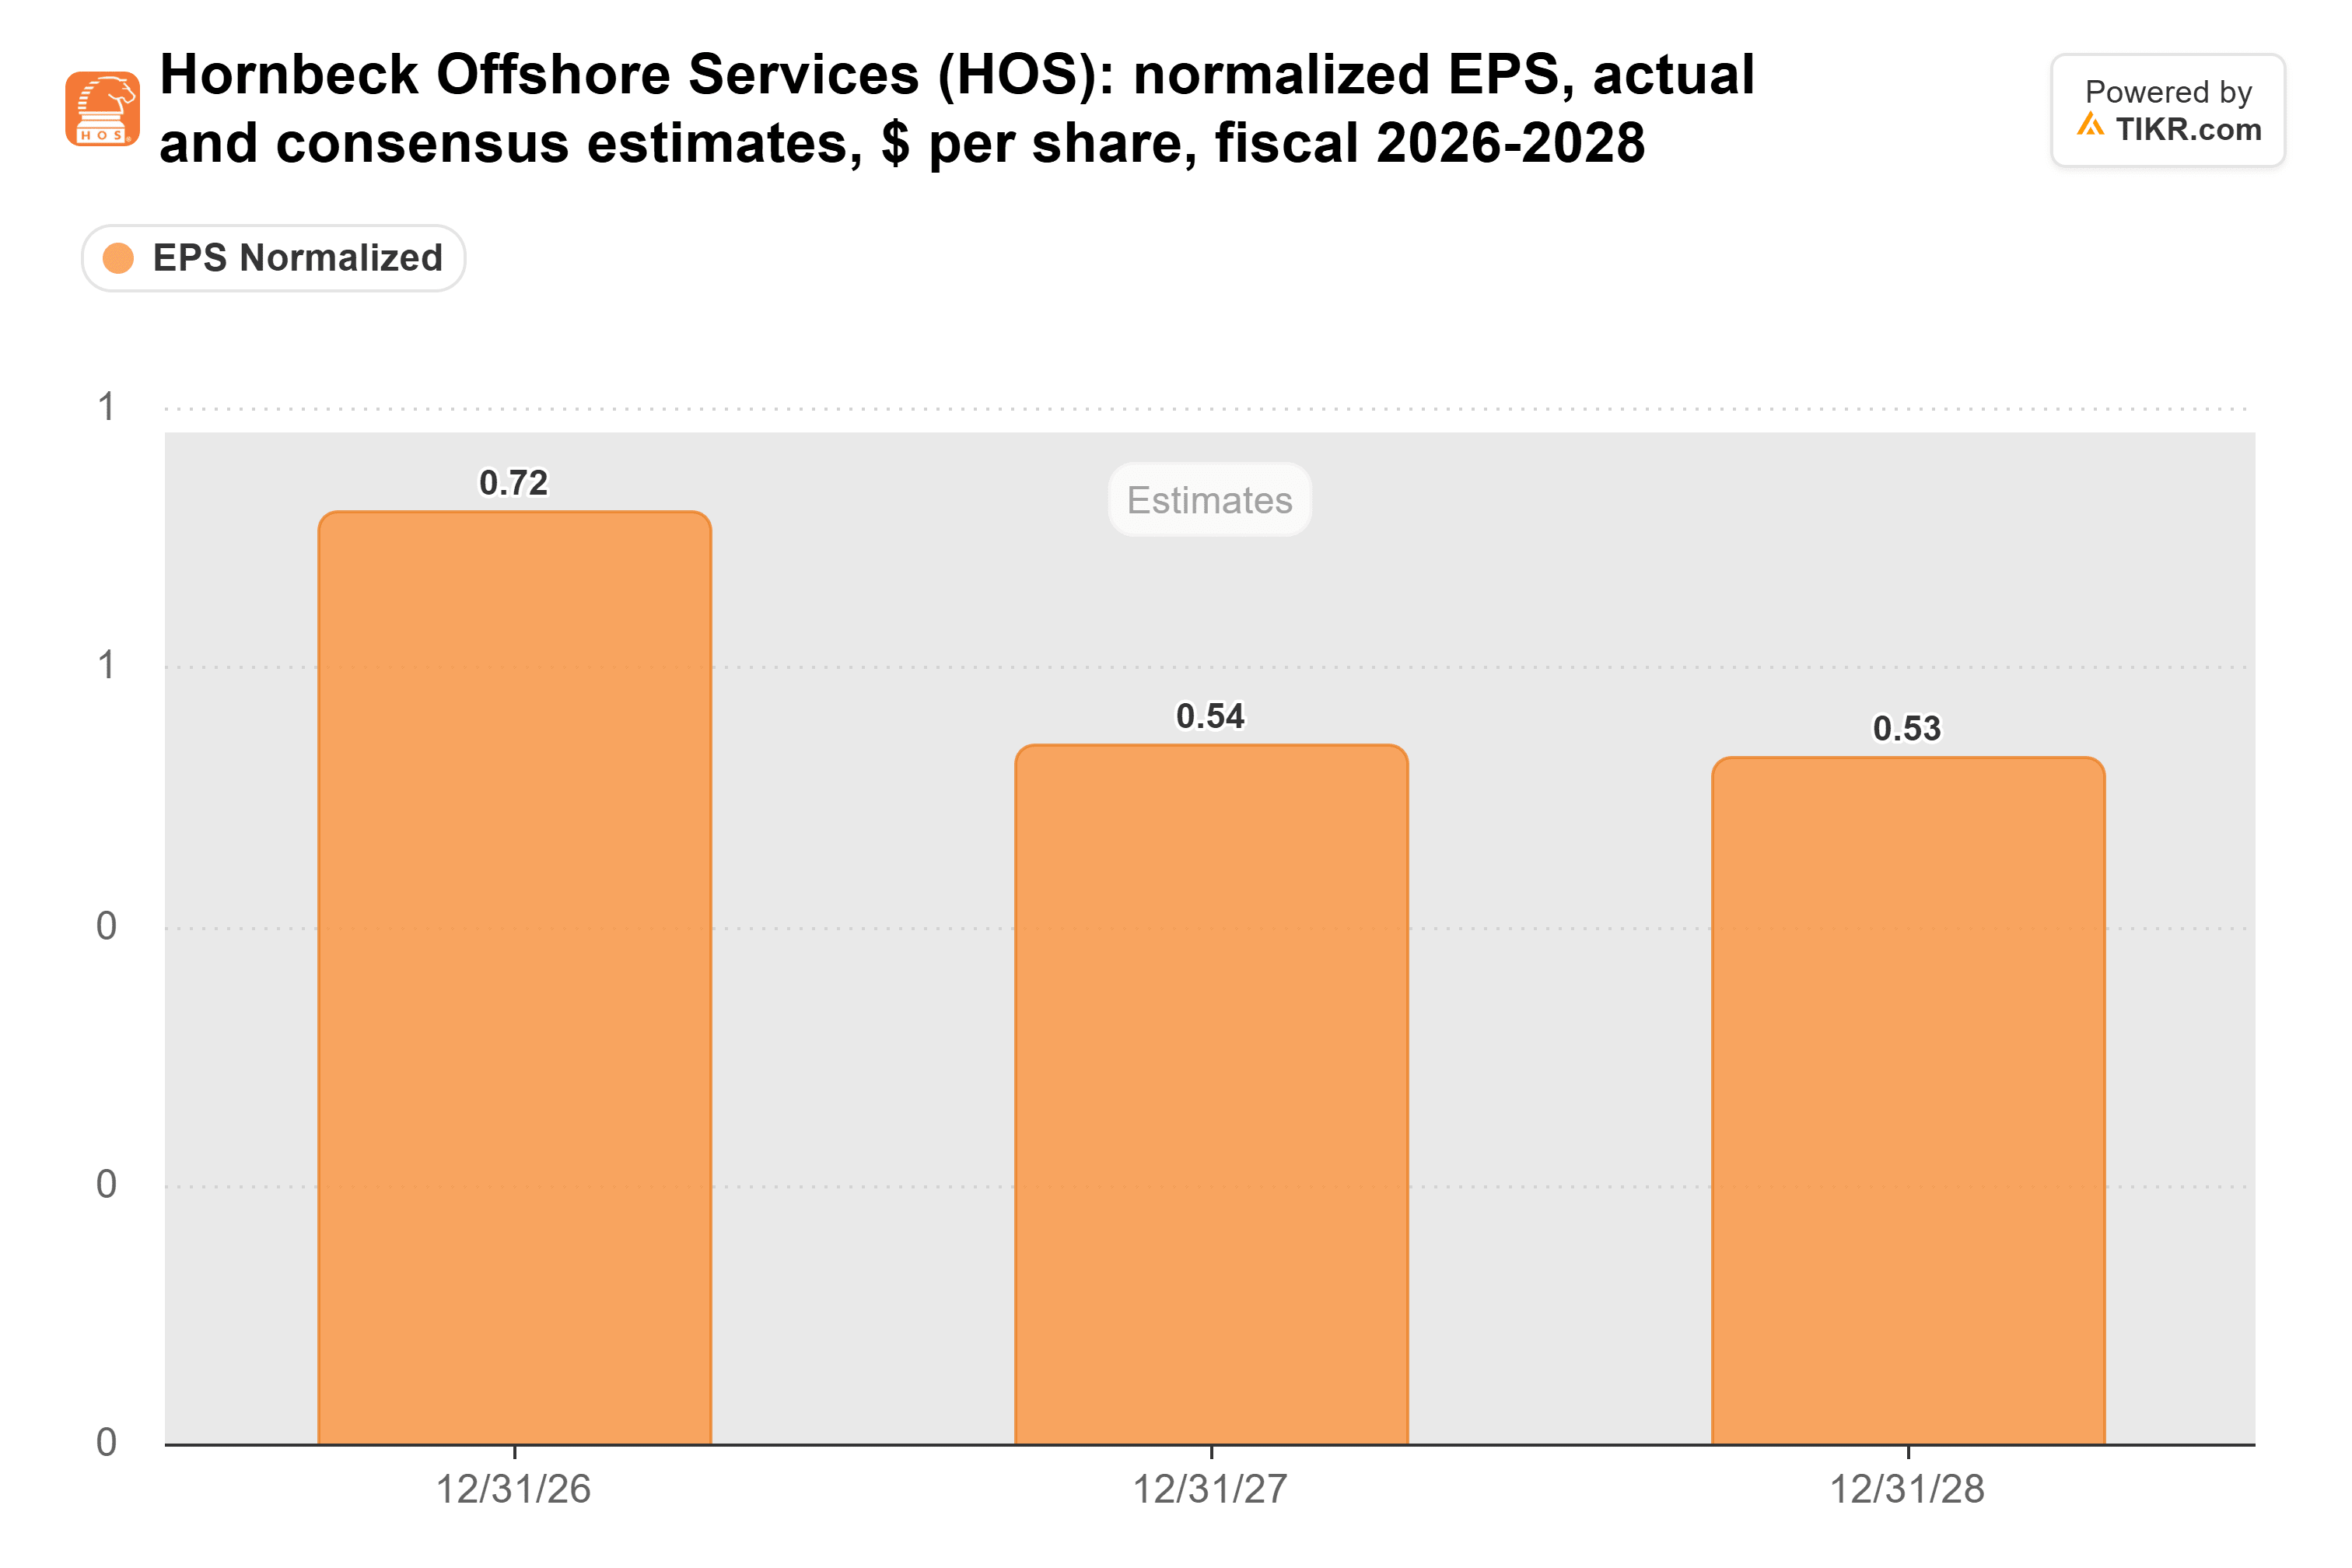
The 2026 average hides a wide split between the two estimates, from $0.28 to $1.16 a share on Yahoo Finance’s tally, so 2027 is the steadier figure. Its dip lines up with the heavy drydock year management laid out.
On those estimates, the stock trades at 11x forward earnings, below its 12x average since it listed in September:
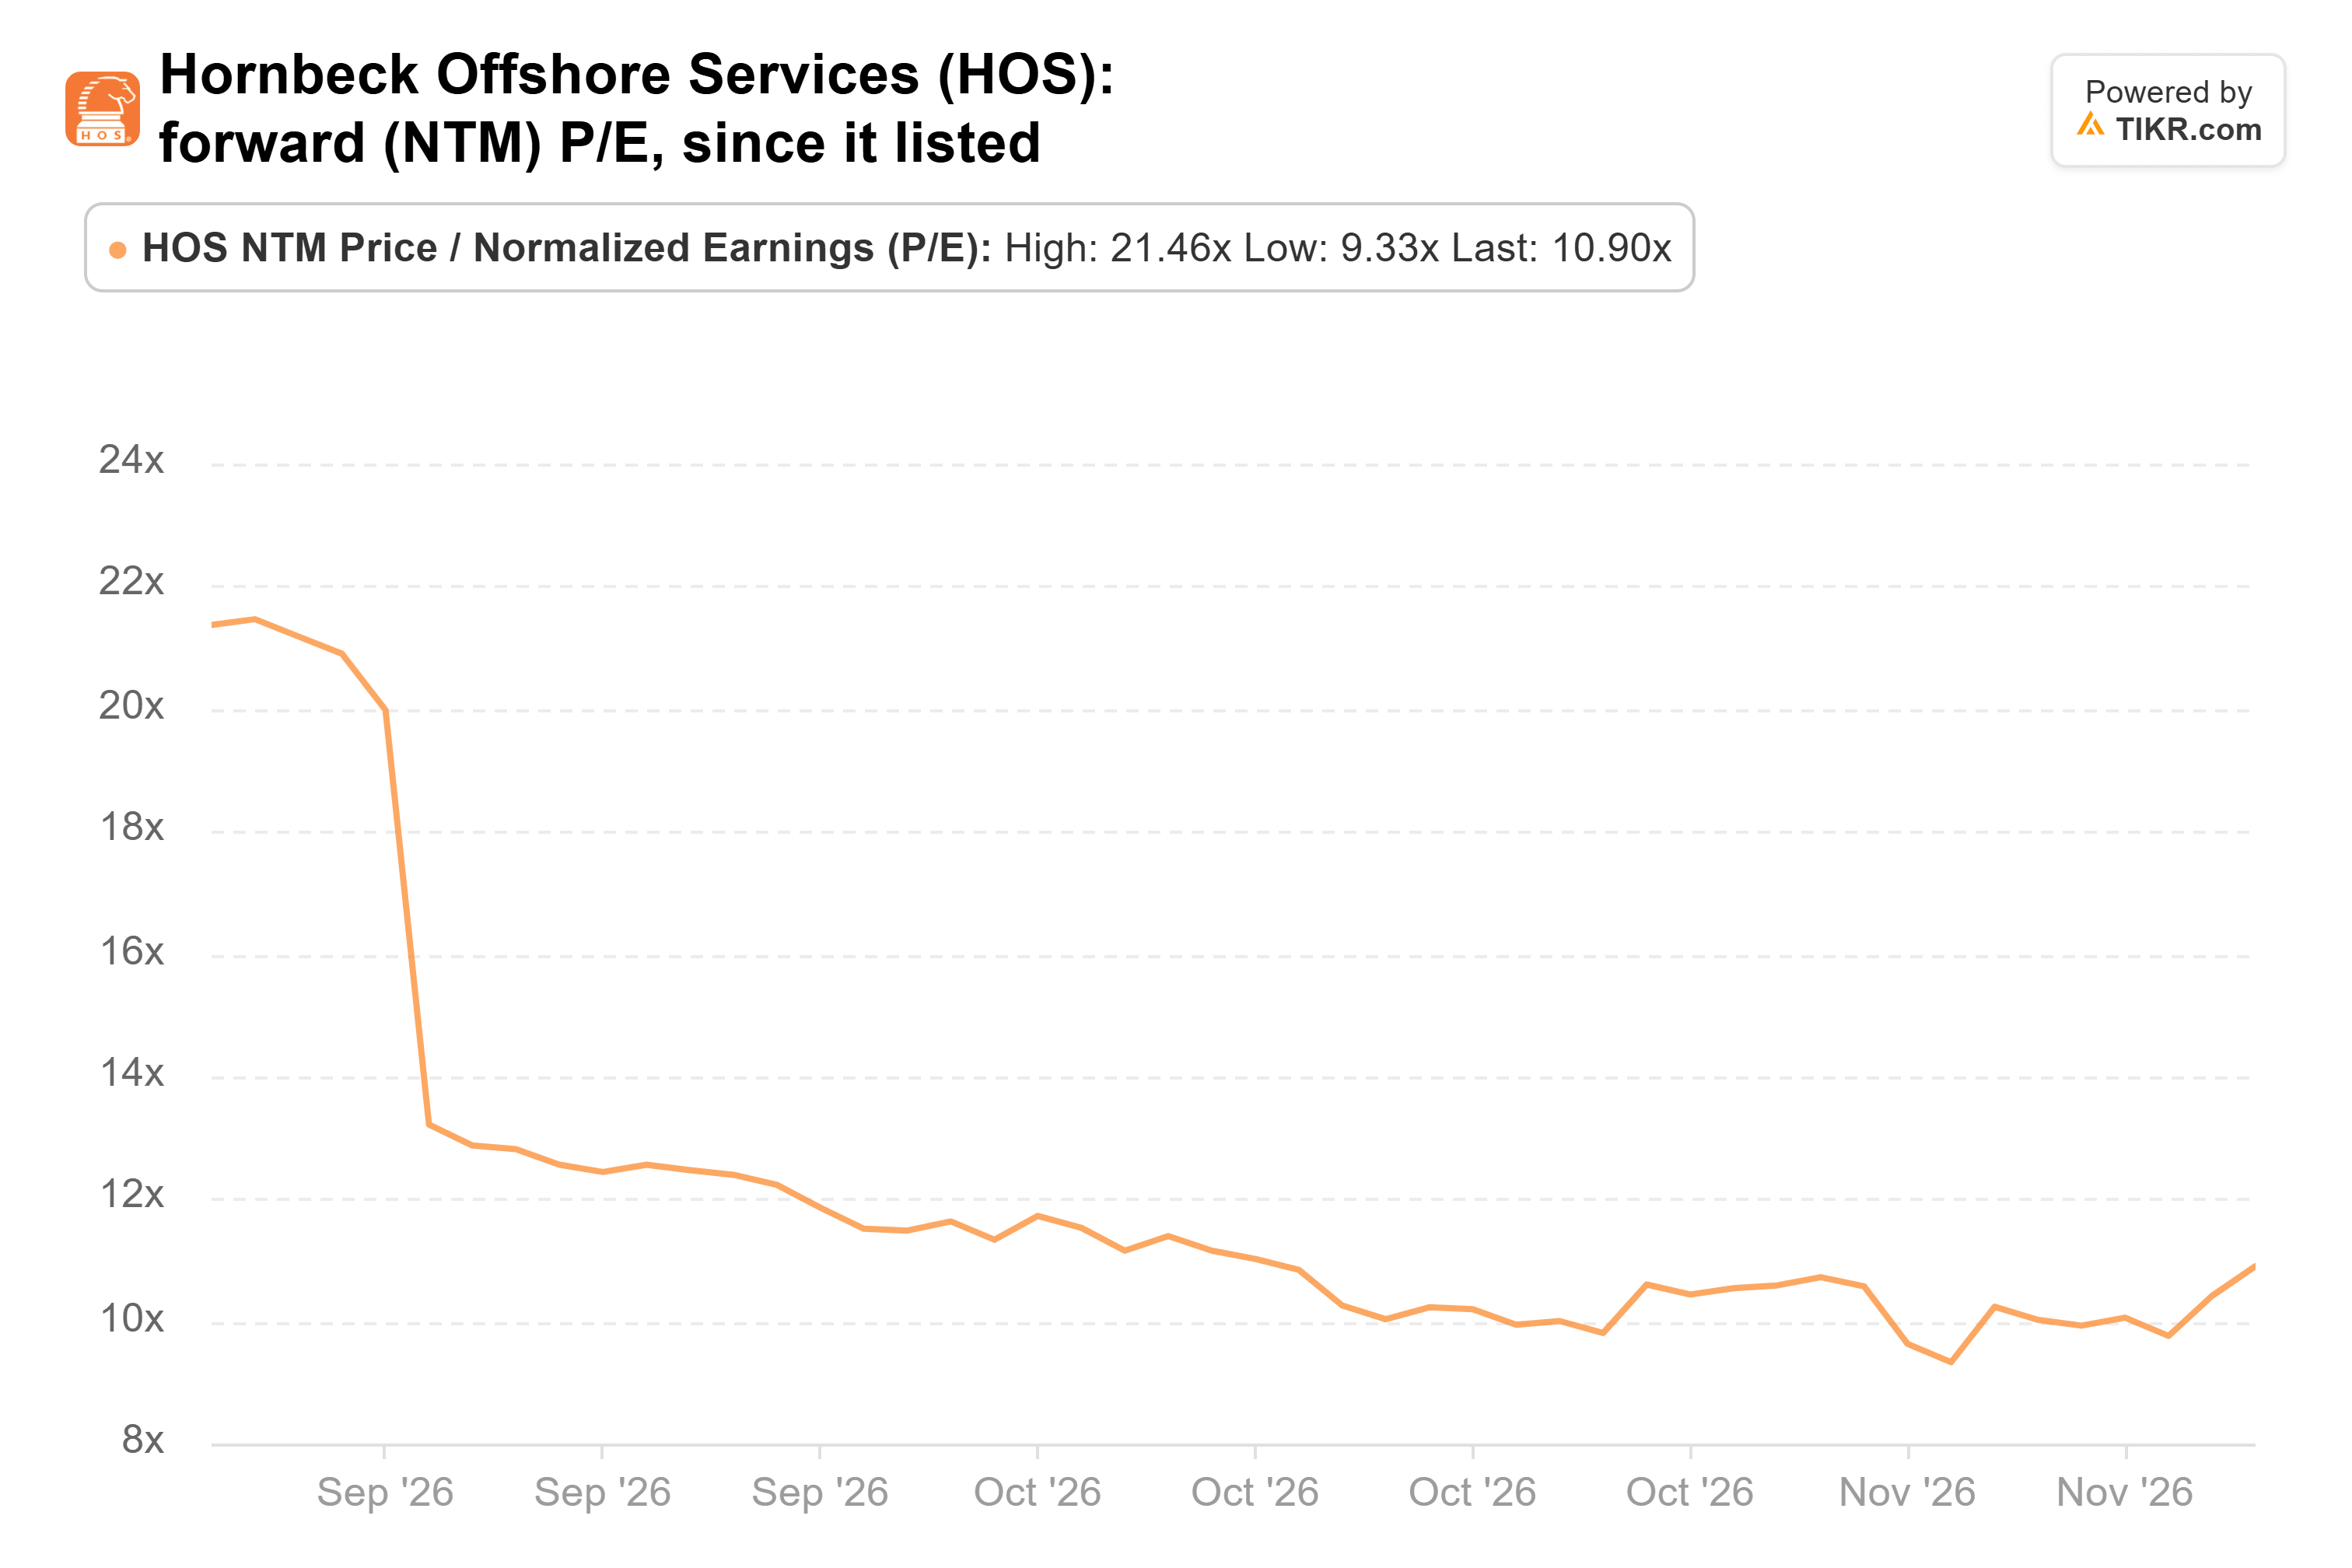
His $5.34 works out to roughly 10x, close to the 9.3x low the stock hit on Nov. 3. The analysts’ price targets of $12 and $14 make a $13 consensus, more than double the Nov. 12 close, though that consensus hasn’t moved since September, before the third-quarter miss.
The risk is the integration: the company is counting on at least $75 million of yearly revenue and cost synergies within three years, and Adams said activity in the Gulf “remains measured.”
Bottom line: the numbers back Todd Hornbeck’s buy. Net debt of $259 million is about half of the $536 million of adjusted EBITDA the two companies earned over the past 12 months, which gives the company room to get through its drydocks. Still, one insider’s buy is only a signal. The next real check is the fourth-quarter report, expected in February.
So what is Hornbeck Offshore stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Hornbeck Offshore could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Hornbeck Offshore for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!








