Key Takeaways
- DraftKings fell 21.3% after third-quarter revenue of $1.33 billion missed estimates and it cut 2026 adjusted EBITDA guidance to $175 million to $275 million.
- Predictions investment will reach $650 million to $700 million this year, well above the $400 million Guggenheim had assumed.
- CEO Jason Robins says DraftKings is “set up for an exceptional 2027,” with adjusted EBITDA guided to $800 million to $1.0 billion.
- At 11.6x 2027 EBITDA, the Feb. 18 report must show that guidance holds.
DraftKings (DKNG) lost 21.3% on Friday, closing at $19, just above its 52-week low of $17. The company had promised investors a pivotal quarter, and it delivered one, just in the wrong direction.
Third-quarter revenue rose 16% to $1.33 billion but missed the $1.40 billion estimate. Then management cut 2026 adjusted EBITDA guidance to $175 million to $275 million, from $700 million to $900 million.
The culprit is Predictions, DraftKings’ answer to Kalshi and Polymarket. It will now consume $650 million to $700 million of investment this year.
Even so, CEO Jason Robins sounded upbeat. “We believe we are set up for an exceptional 2027,” he said in the release.
The quarter Predictions ate
The losses got much bigger:
- Net loss: $468.7 million, up 83% from $256.8 million a year earlier
- Adjusted EBITDA: a loss of $317 million, against a loss of $126.5 million
- Monthly unique payers: up 13% to 4.1 million
More than 1.6 million customers have engaged with Predictions this year. But promotions offset most of its gross revenue, so the product adds almost nothing to the top line in 2026.
Revenue guidance came down too, to $6.35 billion to $6.55 billion from $6.5 billion to $6.9 billion. That’s a 3.7% cut at the midpoint.
The swing shows up starkly in EBITDA…
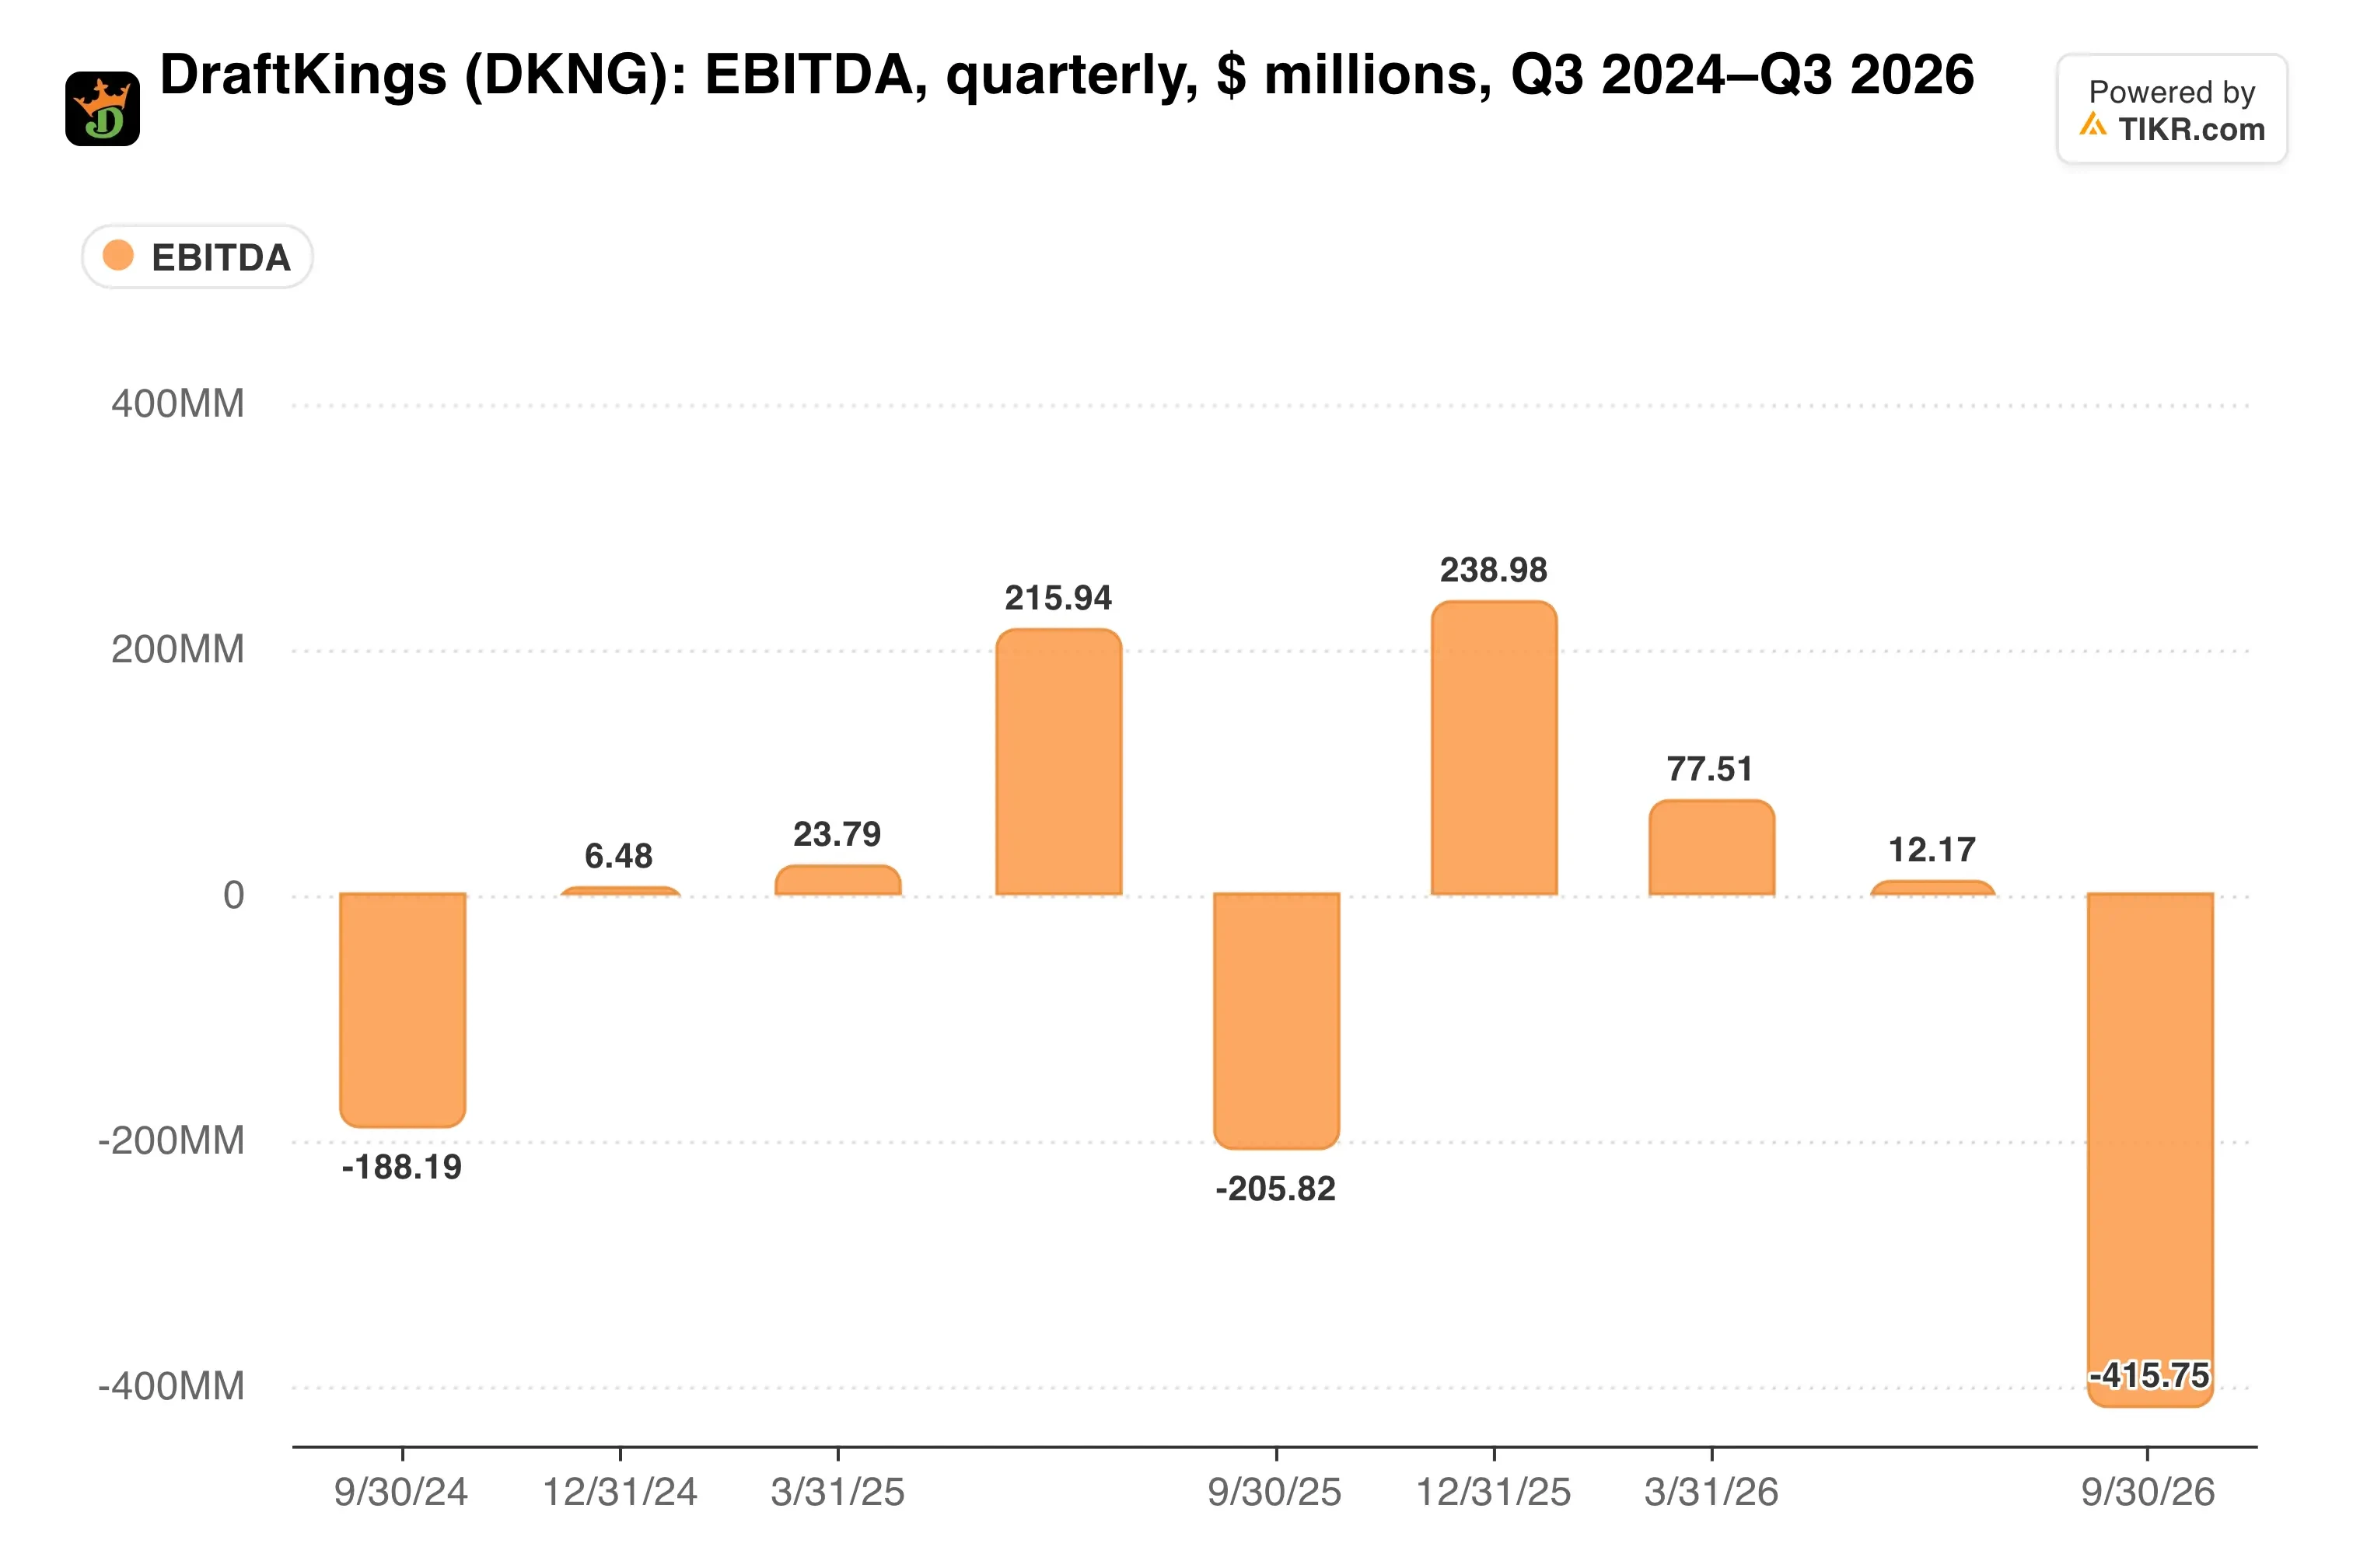
This year’s guidance midpoint of $225 million sits far below the $700 million to $900 million DraftKings first promised in February.
The 2027 bet
So everything rides on next year. DraftKings guided 2027 revenue to $7.35 billion to $7.75 billion, up 17% at the midpoint, and adjusted EBITDA to $800 million to $1.0 billion.
That still includes about $300 million of Predictions spending at the midpoint. Strip it out, and the core business earns about $1.2 billion.
CFO Alan Ellingson framed it as reinvestment. “Our core business continues to generate significant free cash flow,” he said, adding that DraftKings is funding Predictions “at attractive payback periods.”
Analysts had already been bracing for more. In October, Guggenheim assumed about $400 million of Predictions spending this year, and the actual figure is now well above that.
Will Wall Street’s forecasts follow the guidance?
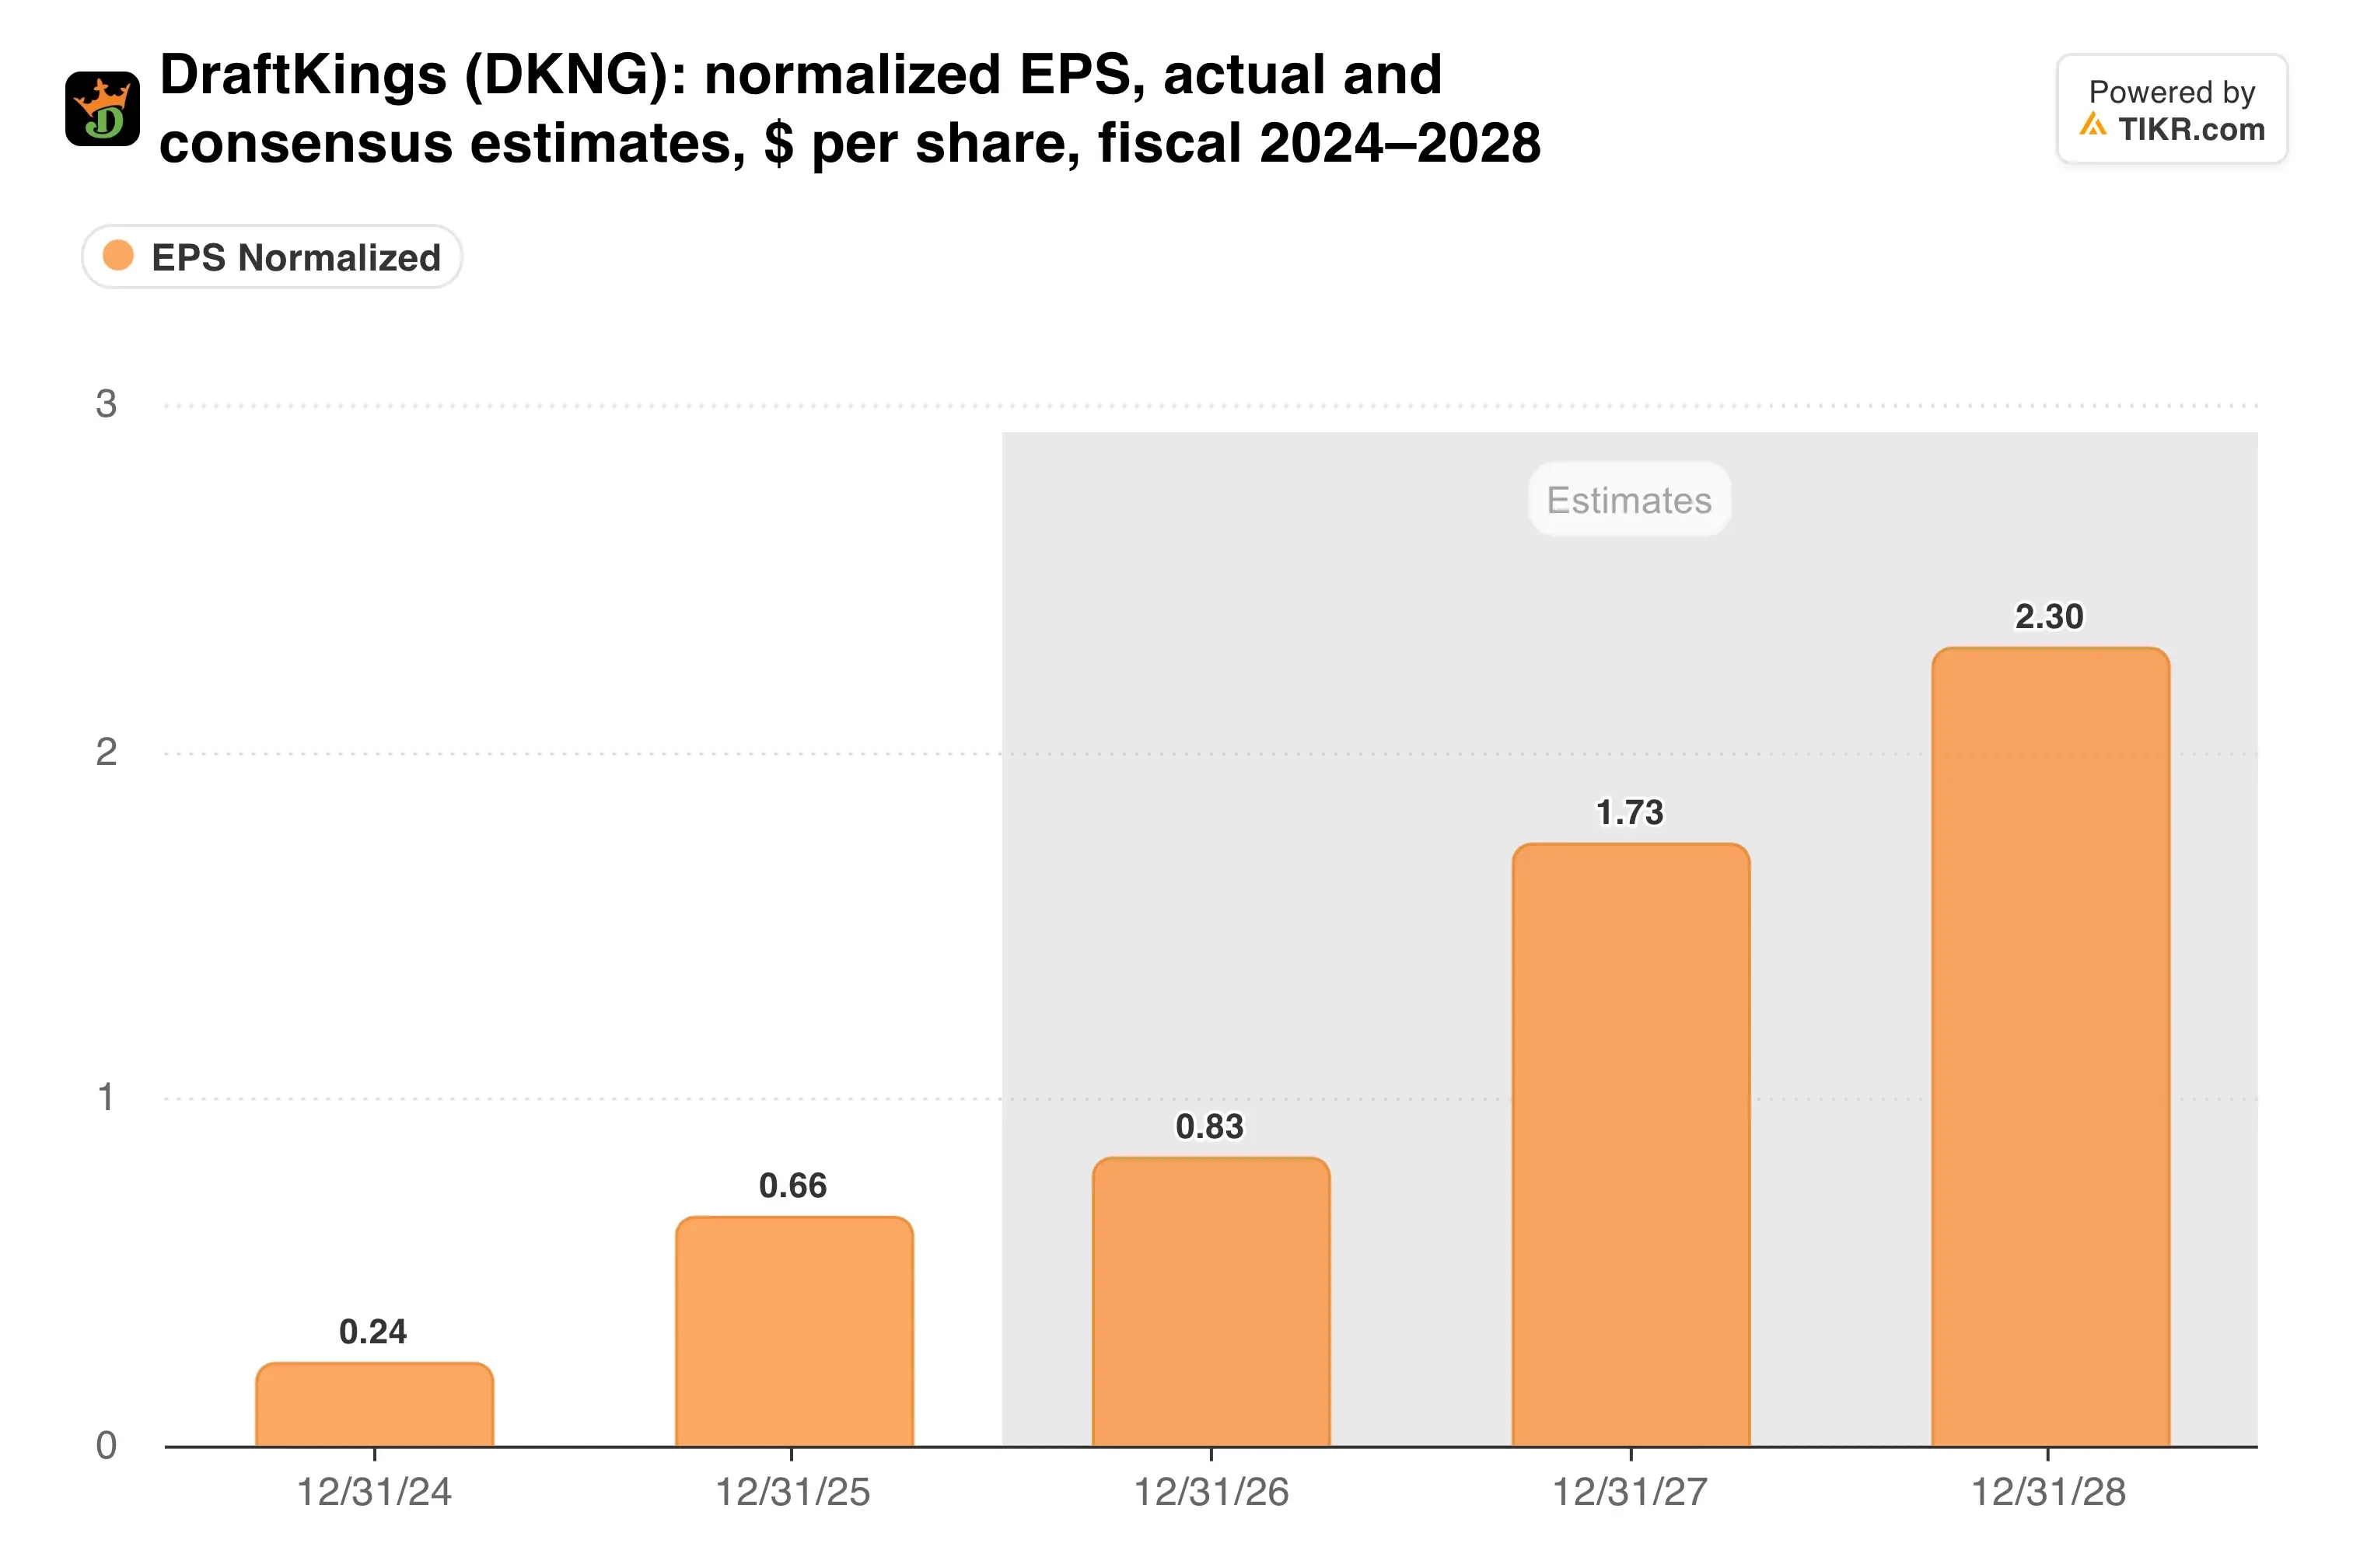
If they do, 2027 has to deliver almost all of the profit growth on its own.
TIKR tracks 37 analysts on DraftKings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on DraftKings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See DraftKings’ Analyst Ratings
Cheap, if 2027 shows up
At Friday’s close, DraftKings had a $9.2 billion market value and a $10.4 billion enterprise value. That’s about 11.6x the 2027 EBITDA midpoint, and 12.4x forward earnings.
For a business guiding to 17% revenue growth, that’s a modest price. Yet DraftKings has now cut guidance two years running, and credibility is the real discount here.
The stock’s slide makes that obvious:
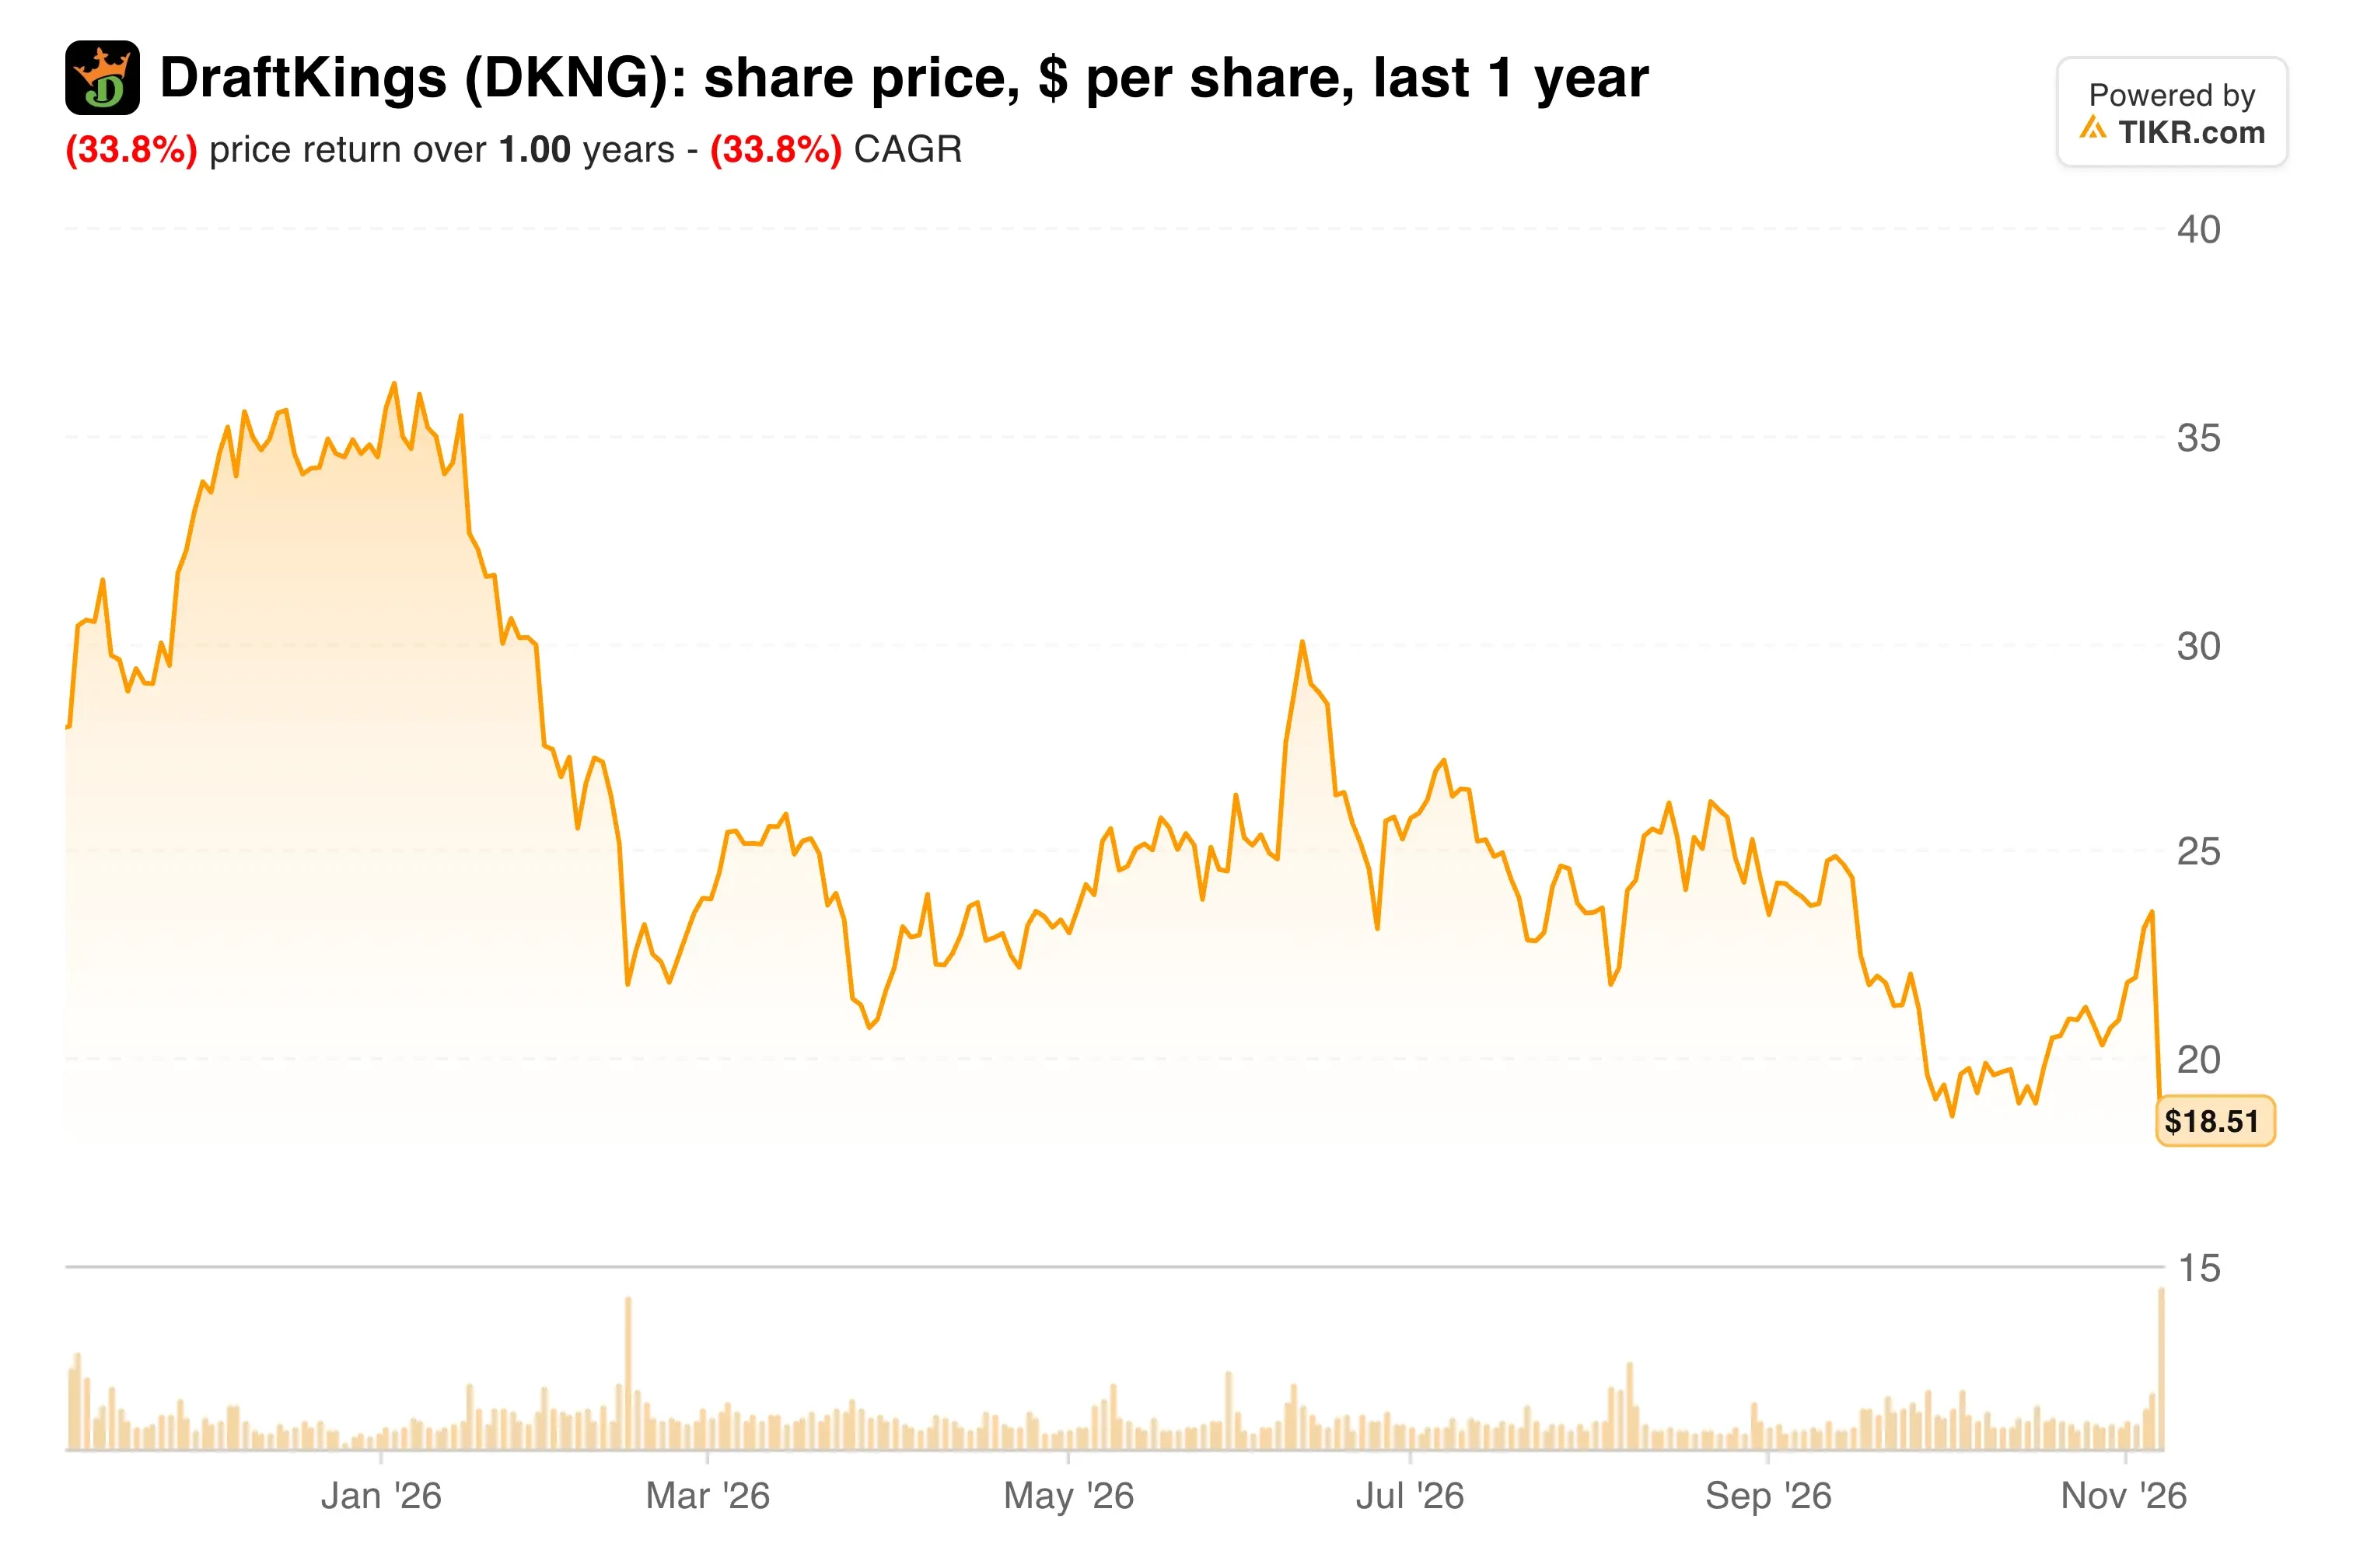
Shares are down about half from their 52-week high of $37.
My take: The core sportsbook and casino business looks healthy, and 11.6x 2027 EBITDA prices in a lot of doubt. But DraftKings keeps raising the cost of Predictions while Kalshi sets the pace, so I’d wait for proof that spending peaks. Buying at a 52-week low is tempting, yet the guidance has moved too often to trust yet.
The Feb. 18 fiscal-year report is the next checkpoint. It will show whether 2027 guidance survived the first weeks of the new year.
So what is DraftKings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DraftKings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!