Key Takeaways
- Goldman Sachs reiterated its $1,250 target on Micron, 70% above the Nov. 9 close, while Bank of America dropped Micron from its US 1 list of top picks.
- The banks are closer than they look: Goldman rates Micron Neutral, and Bank of America kept its Buy rating.
- At 4.2x forward earnings, Micron is priced for a peak, and about $33.5 billion of its disclosed contract obligations should become revenue within 12 months.
Micron Technology (MU) fell 29% in the month to Nov. 9 as Wall Street argued over whether its record profits are a new floor or a peak. Then two banks weighed in.
Goldman Sachs analyst James Schneider reiterated his $1,250 price target, 70% above Monday’s $733.15 close, citing “the high probability of strong free cash flow in the coming quarters.” Yahoo Finance’s headline called Micron “a screaming buy at current valuation levels.”
On Tuesday, Bank of America pulled Micron, Nvidia and Lam Research off its US 1 list of top picks without saying why.
The Banks Agree More Than It Seems
Goldman still rates Micron Neutral. Schneider said its risk/reward is “becoming more attractive,” which is a long way from screaming. Bank of America kept Buy ratings on all three stocks.
The real split is over how long Micron’s earnings last. Democrats’ midterm sweep stoked fears of limits on new data centers, and UBS analysts say construction pauses could threaten around 30% of expected US data-center capacity additions in 2028.
Micron Is Priced for a Peak
Consensus has normalized EPS more than doubling, from fiscal 2026’s record $75.52 to $176.50 in fiscal 2027, then $207.76 in fiscal 2028. The fiscal 2027 figure is up 18% since the end of June, and fiscal 2028’s is up 27%.
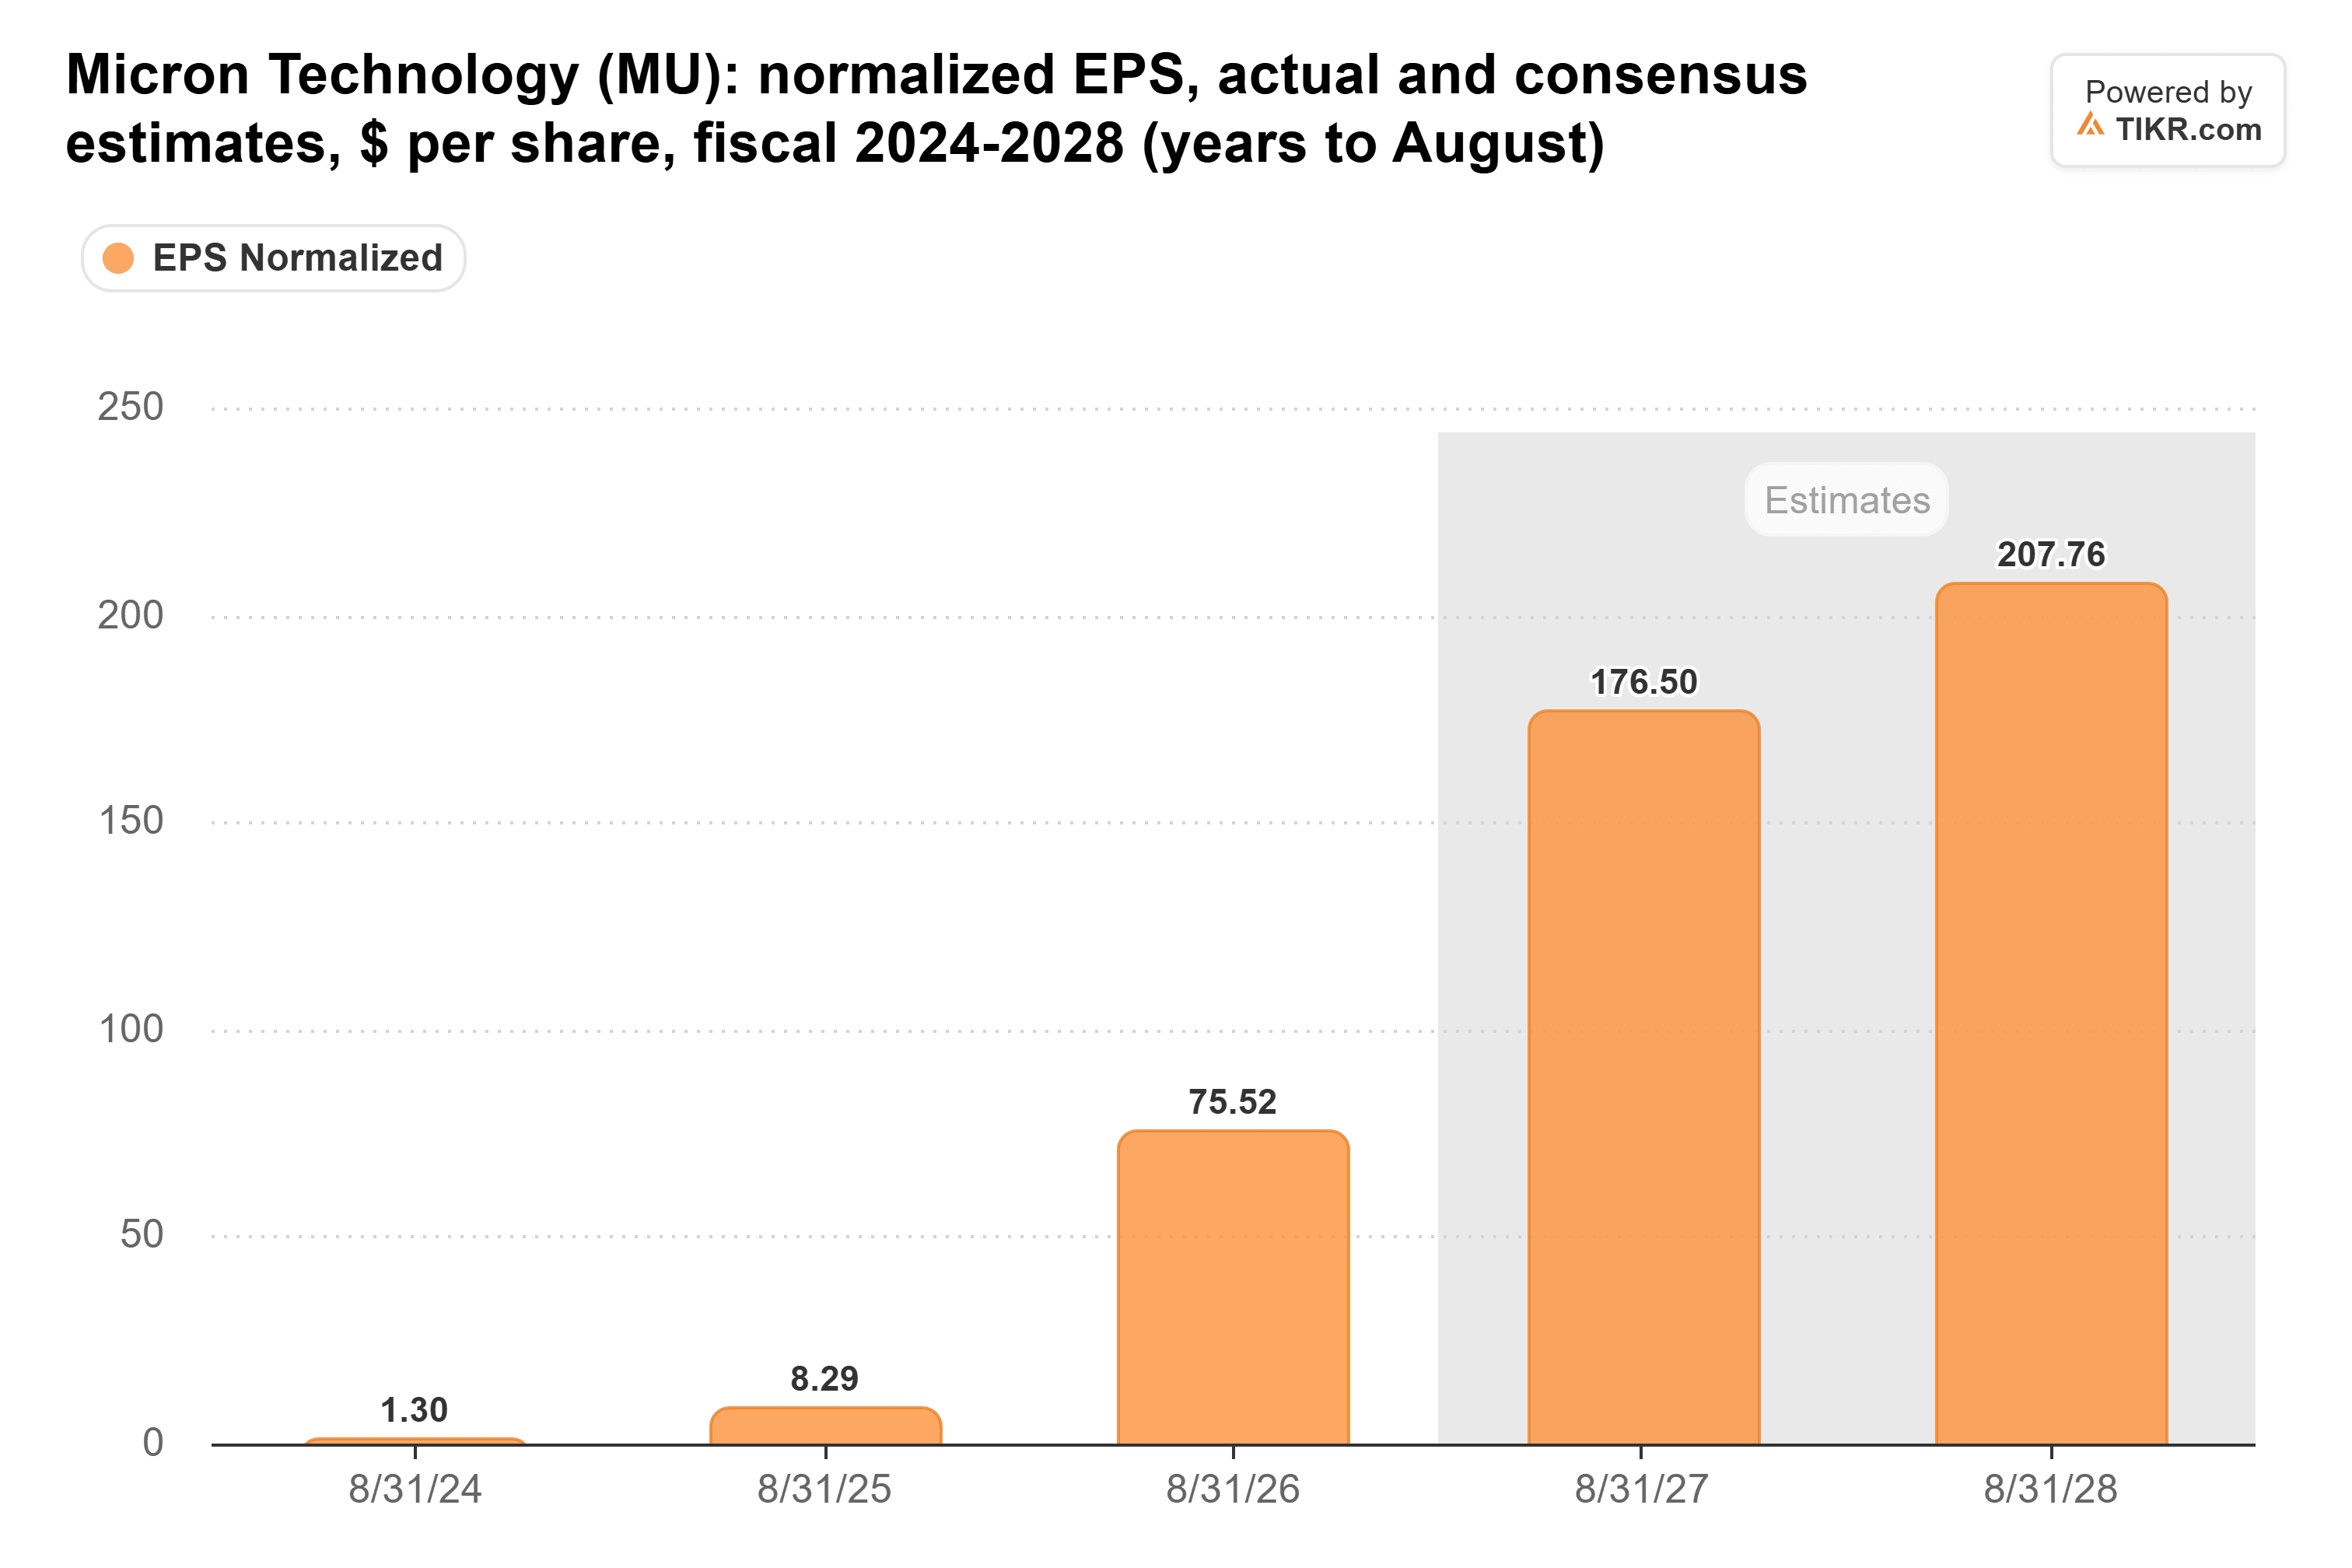
On Nov. 9, the stock traded at 4.2x forward earnings, below every quarter-end reading of the past five years and close to its 2017 and 2018 levels, when the last memory cycle peaked. After that peak, GAAP EPS fell 79% in two years, from $11.51 in fiscal 2018 to $2.37 in fiscal 2020.
TIKR Tracks 49 Analysts on Micron. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
Micron Has Been Here Before
Revenue nearly halved in fiscal 2023, to $15.5 billion from $30.8 billion, and GAAP gross margin swung from 45% to negative 9%. Revenue then soared to a record $133.2 billion in fiscal 2026.
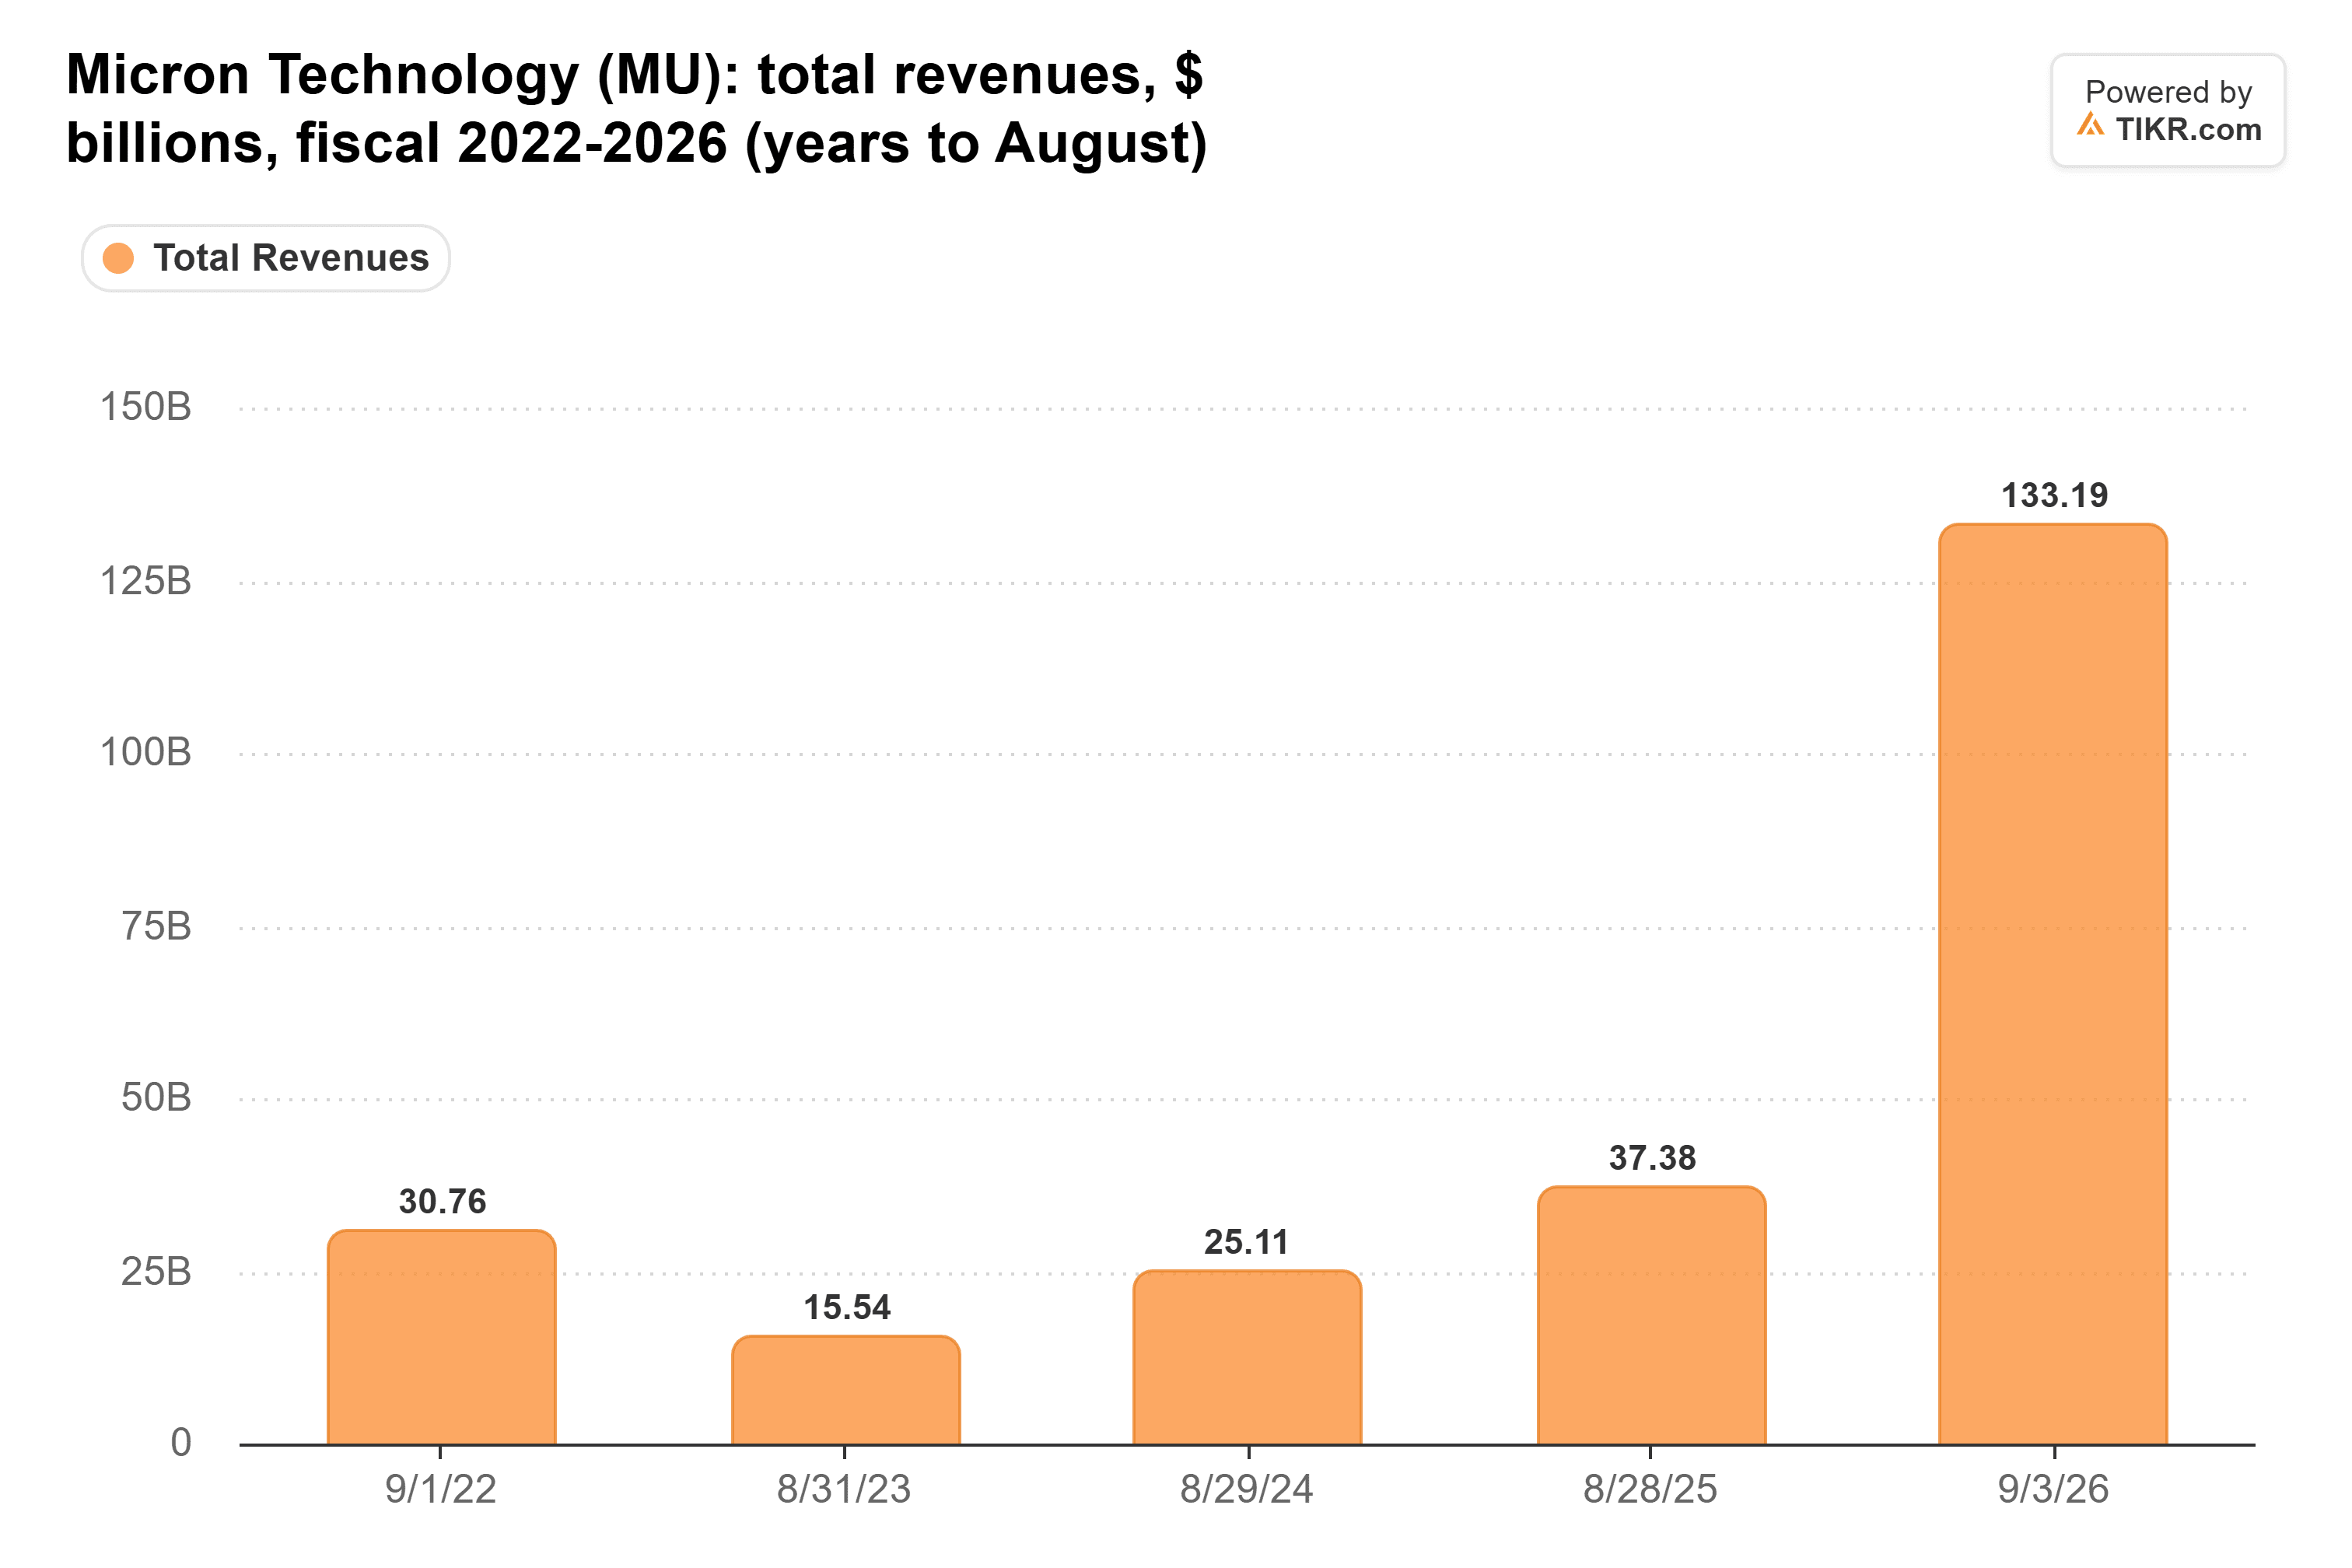
Management says this cycle is different because of 26 take-or-pay agreements with customers. But at Sept. 3, Micron expected about a quarter of its roughly $134 billion of remaining performance obligations to become revenue in the next 12 months. That’s about $33.5 billion, against the $275.5 billion analysts expect in fiscal 2027. That figure values committed volumes at minimum prices and excludes agreements without fixed pricing or price bands, as well as contracts with an original term of one year or less.
Such deals have given way before. Jukan, a semiconductor account on X, pointed out that other chipmakers let customers push out committed volumes once demand fell.
Goldman Has the Better Side of This
At 4.2x, the price already assumes those estimates won’t last. Even Goldman’s $1,250 target is only about 6x estimated fiscal 2028 EPS.
Free cash flow was $59.0 billion in fiscal 2026, against $16.7 billion over the previous nine years combined. It held $73.5 billion of cash and investments at fiscal year-end, about $12.7 billion of it customer deposits due back between 2029 and 2031, and it can start buying back up to $35.16 billion of stock on Dec. 9.
Bank of America’s caution makes sense too. New capacity arrives in 2027 and 2028, including Micron’s Idaho fab, and analysts expect gross margin to fall from 87.0% in fiscal 2027 to 65.5% by fiscal 2030.
At this price, Micron doesn’t need record earnings to last. It needs them to fall less than they did after 2018, and the cash and buyback cushion the wait.
Micron’s December Report Is the Next Test
Micron reports fiscal first-quarter results in December. Management guided to $61.5 billion of revenue, plus or minus $1.5 billion, at a non-GAAP gross margin of about 86.25%. A beat with margins holding would back Goldman’s side; any customer pushing out contracted volumes would back the bears.
So What Is Micron Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!