Key Takeaways
- McDonald’s shares rose 6% on Nov. 4 after a third-quarter earnings beat, even as U.S. comparable sales slipped 0.2% on fewer guests.
- Investor Daniel Mahncke calls GLP-1 drugs the biggest threat McDonald’s has faced in decades, though he puts the hit at about 1% of sales today.
- Franchisees absorb most of a lost sale, and Mahncke says their cash flow is already down about 10% from its peak.
- At 20x forward earnings the stock sits below its five-year average, but a 10% hit would pull estimates down too.
McDonald’s (MCD) shares jumped 6% on Nov. 4 after a third-quarter earnings beat. But U.S. comparable salesslipped 0.2% as fewer guests came in, and one investor sees a bigger worry.
On this week’s episode of We Study Billionaires, Daniel Mahncke focused on GLP-1 weight-loss drugs like Zepbound from Eli Lilly (LLY): “I think that’s probably the most powerful threat that we have had McDonald’s seeing in probably decades, if not ever.”
Small Today, and Growing
Mahncke cites research showing GLP-1 households “tend to spend about 8% less at fast food chains, coffee shops, and basically all similar places within six months.” He figures “the impact right now should be about 1% of sales, which doesn’t sound massive.”
At McDonald’s Sept. 23 Investor Day, U.S. President Skye Anderson put GLP-1 users at about 30 million Americans and said 84% of their households visit McDonald’s.
Lilly’s numbers show how fast that could grow. U.S. Zepbound revenue rose 48% to $5.3 billion in the third quarter, its release says, and the FDA approved Foundayo, Lilly’s once-daily GLP-1 pill, on April 1.
So Mahncke frames it as “whether this will be an impact of 1% or 10% on sales,” and says he’s grown less sure it stays near 1%.
The Estimates Look Like the 1% Case
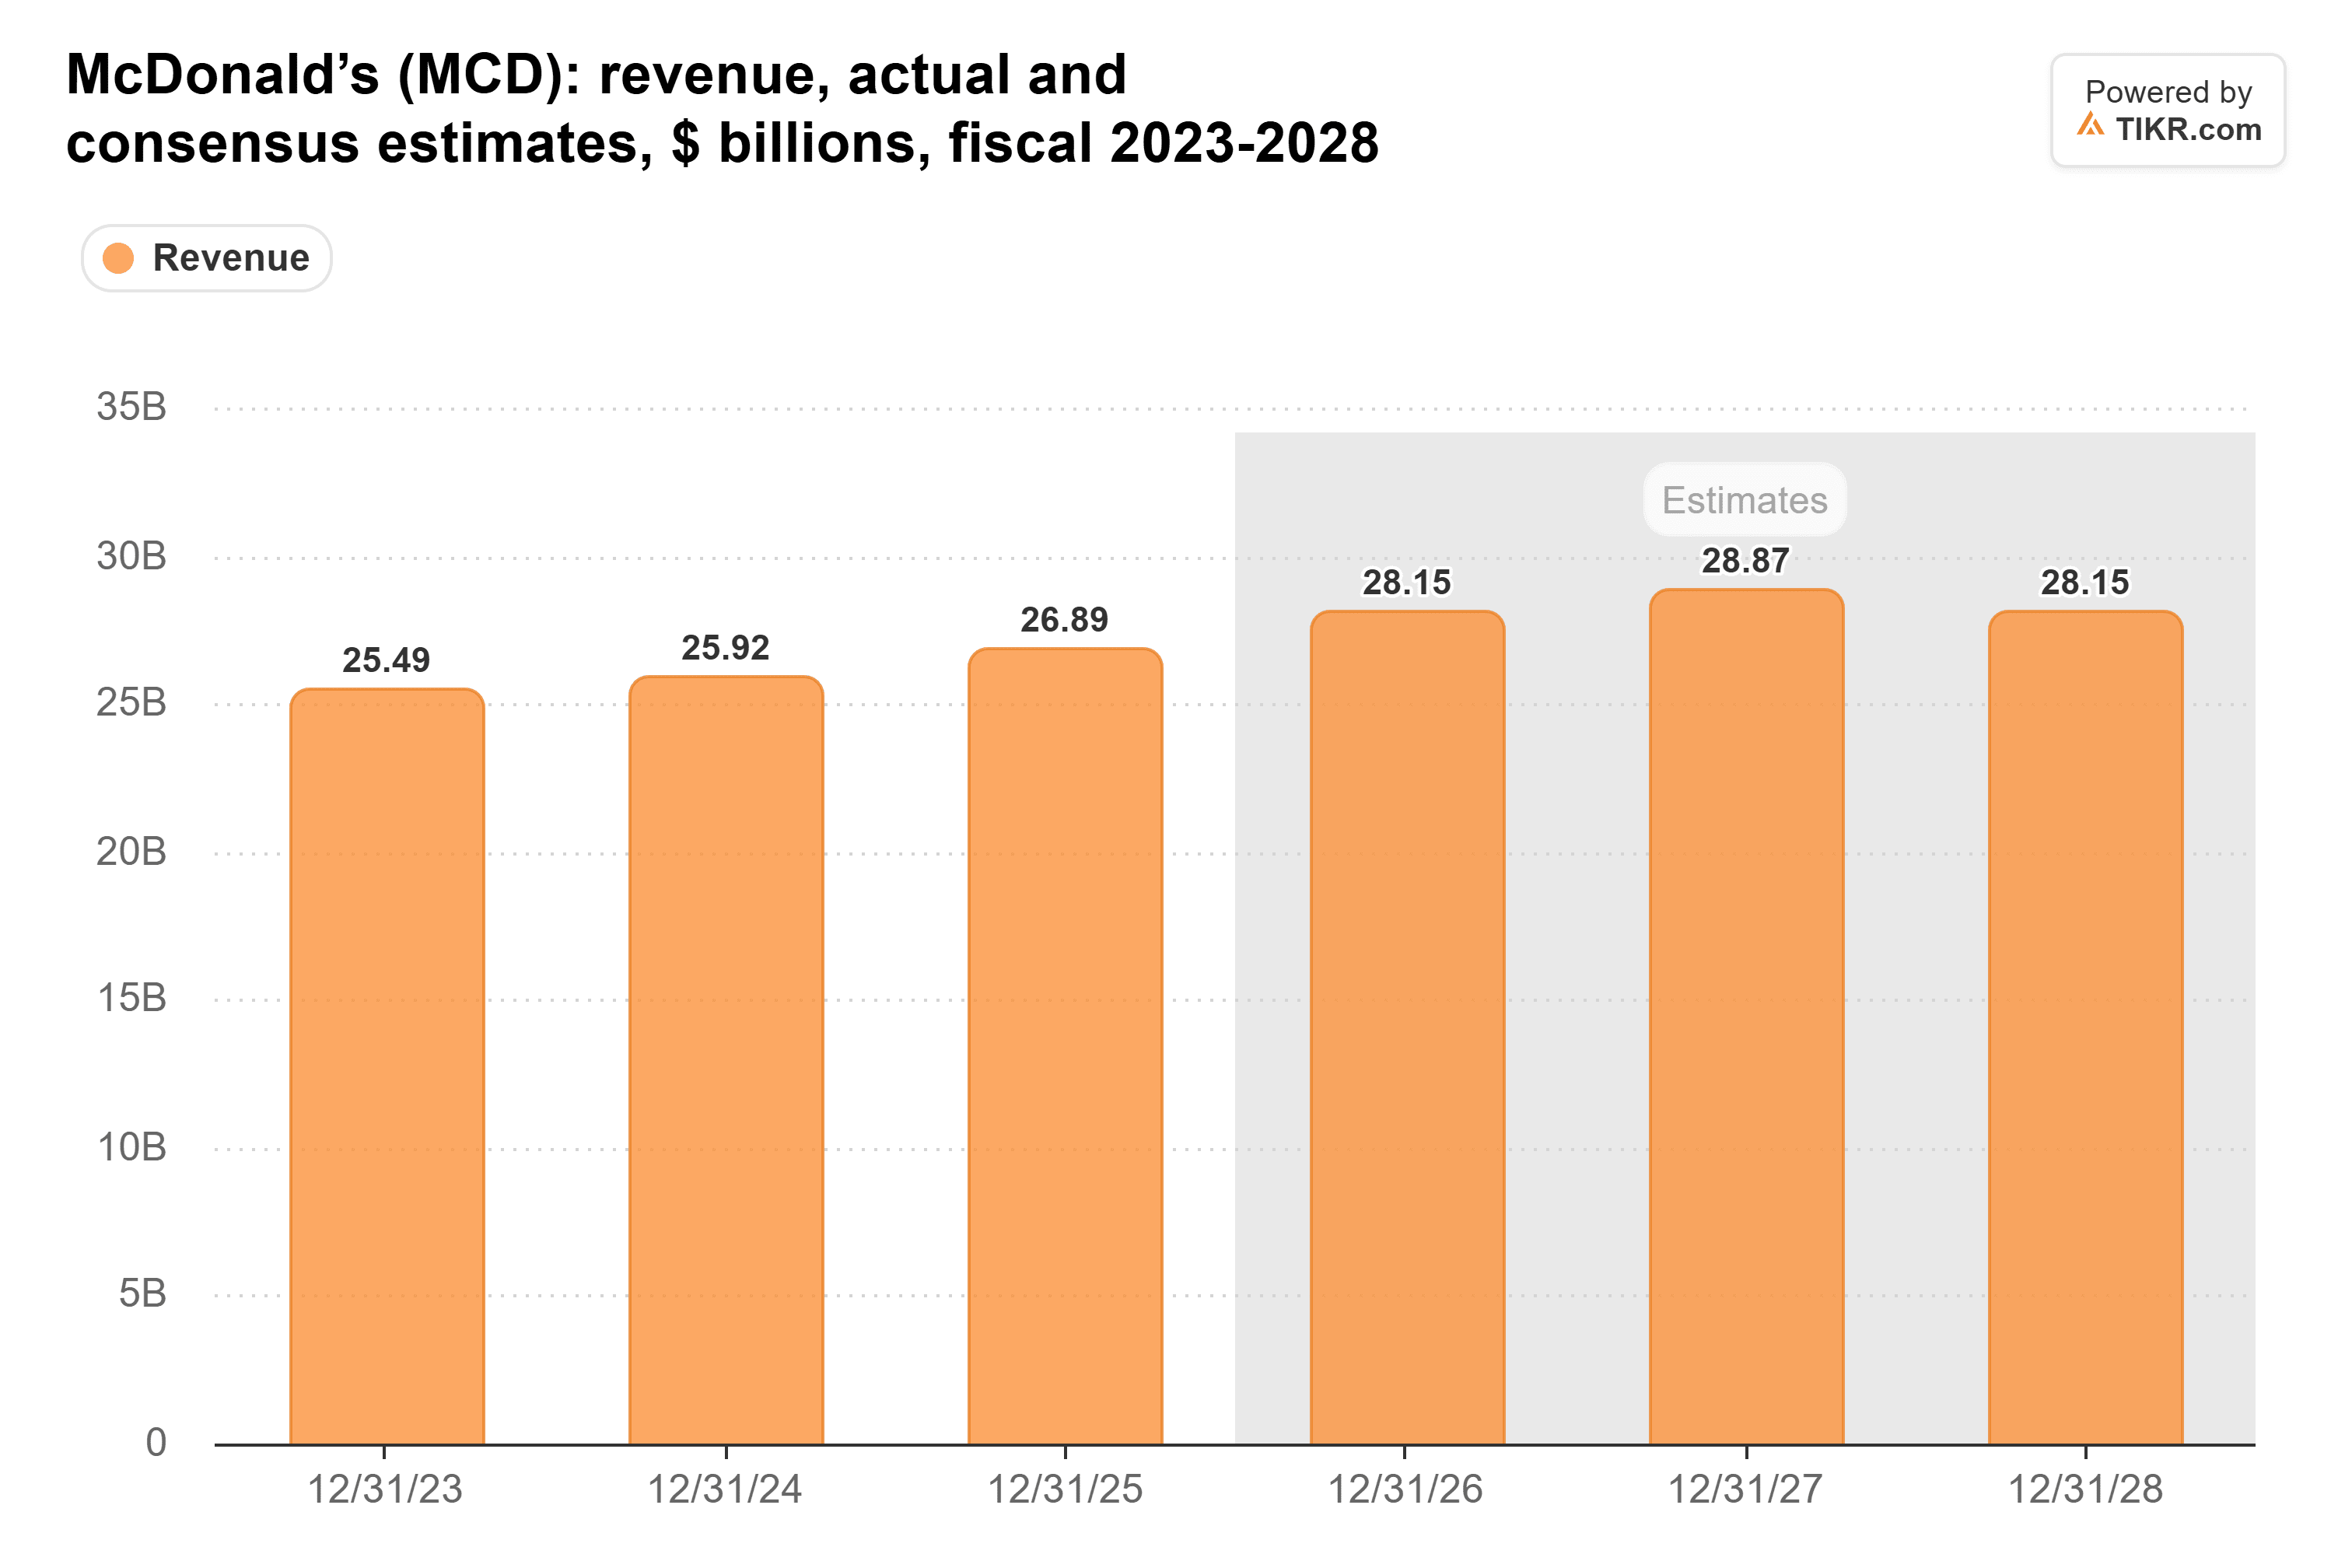
Analysts expect revenue to climb from $26.9 billion in 2025 to $28.9 billion in 2027, before dipping as McDonald’s moves toward its target of about 98% franchised by the end of 2028.
As of Oct. 23, analysts had cut their EPS estimates for 2026 through 2028 by 3.5% to 7.6% over the past year.
McDonald’s Gets Paid First
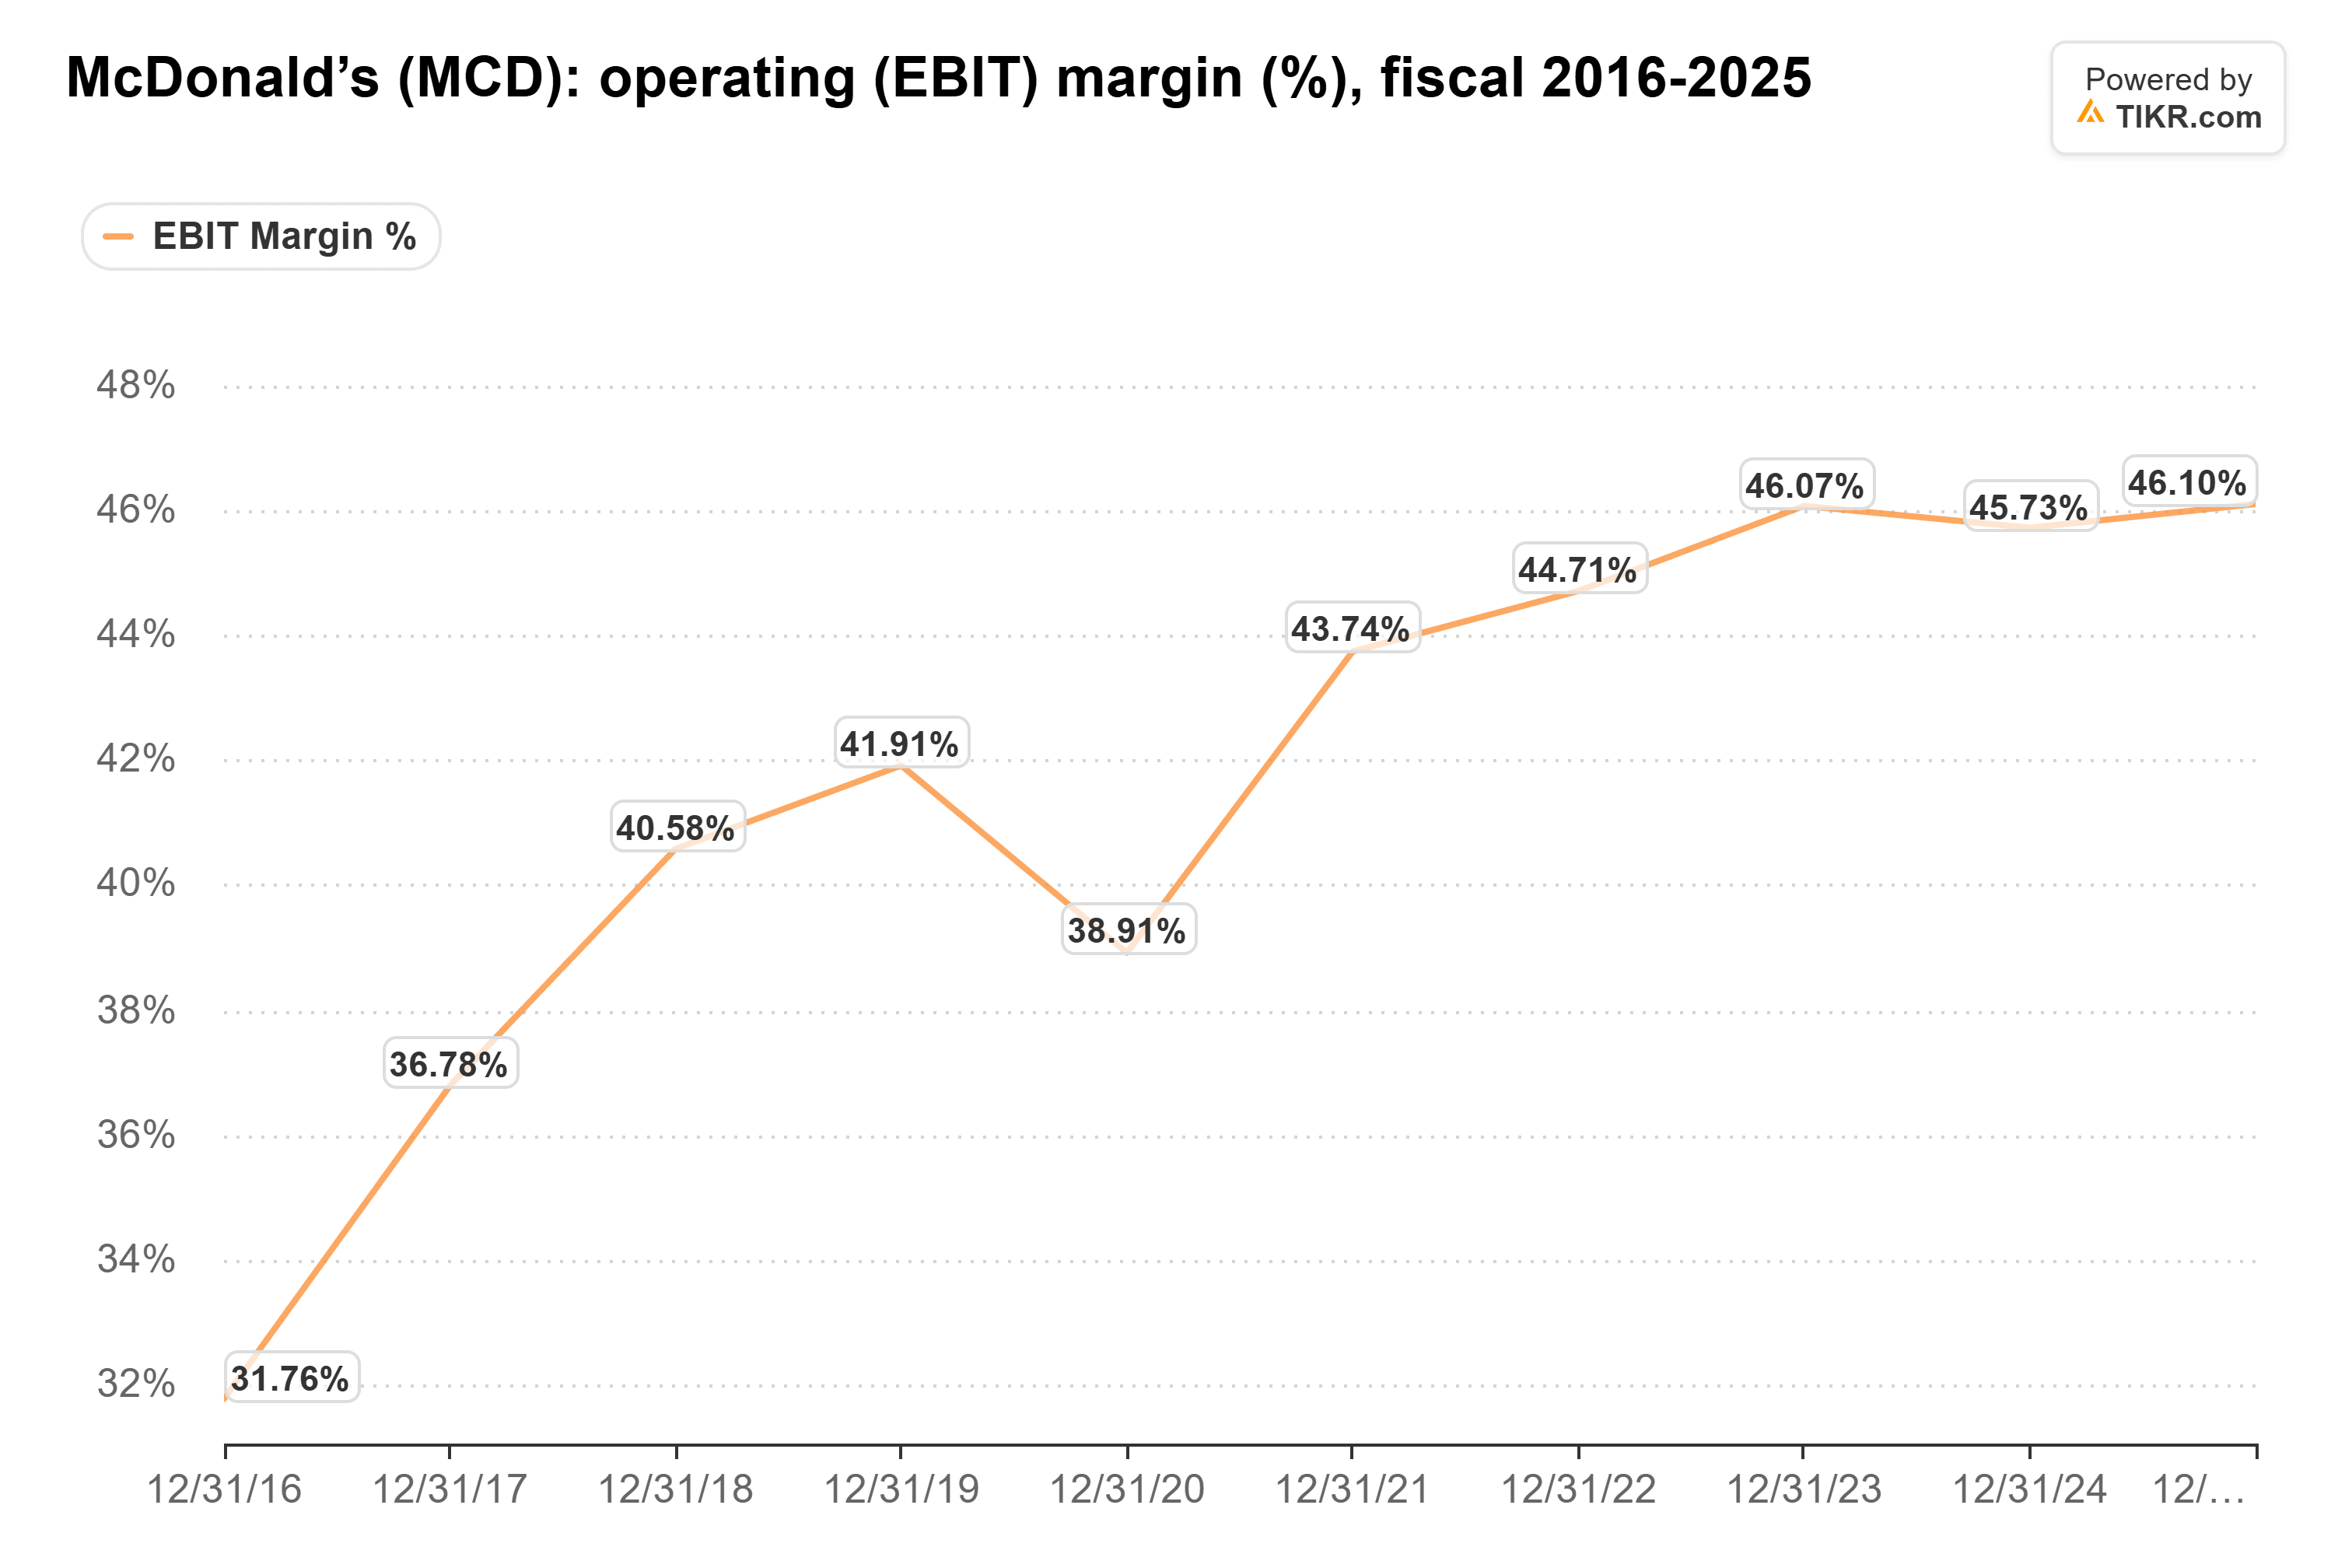
About 95% of McDonald’s restaurants are franchised, and owners pay royalties and rent based on sales, with minimum rent payments. A lost sale costs McDonald’s only its cut. That model helped lift its operating margin from 31.8% in 2016 to 46.1% in 2025 and held there.
Franchisees carry the risk. McDonald’s says the average U.S. restaurant sells more than $4 million a year and earns its owner about $500,000 of cash flow. Mahncke says “franchisee cash flow is actually down about 10% from those post-pandemic peaks.”
For that restaurant, a 10% sales hit is $400,000 of lost sales against $500,000 of cash flow. Food costs and royalties shrink with sales, but minimum rent limits how far rent falls. It’s a big bite.
TIKR Tracks 33 Analysts on McDonald’s. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on McDonald’s, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See McDonald’s Analyst Ratings
McDonald’s Is Already Paying for It
McDonald’s NEXT plan adds about $800,000 per U.S. restaurant on top of a standard $400,000-$450,000 remodel, backed by about $8.5 billion of rent relief and capital support through 2036.
The rent relief comes out of franchised margins, McDonald’s richest line at 84.2% of franchised revenue in 2025. If the hit runs closer to 10%, I’d expect McDonald’s to give back more rent or wait longer for the upgrades meant to win guests back.
At 20x, McDonald’s Needs a Bigger Discount
McDonald’s traded at 20.2x forward earnings on Nov. 2, below its five-year average of 23.9x, after touching 17.5x on Sept. 30.
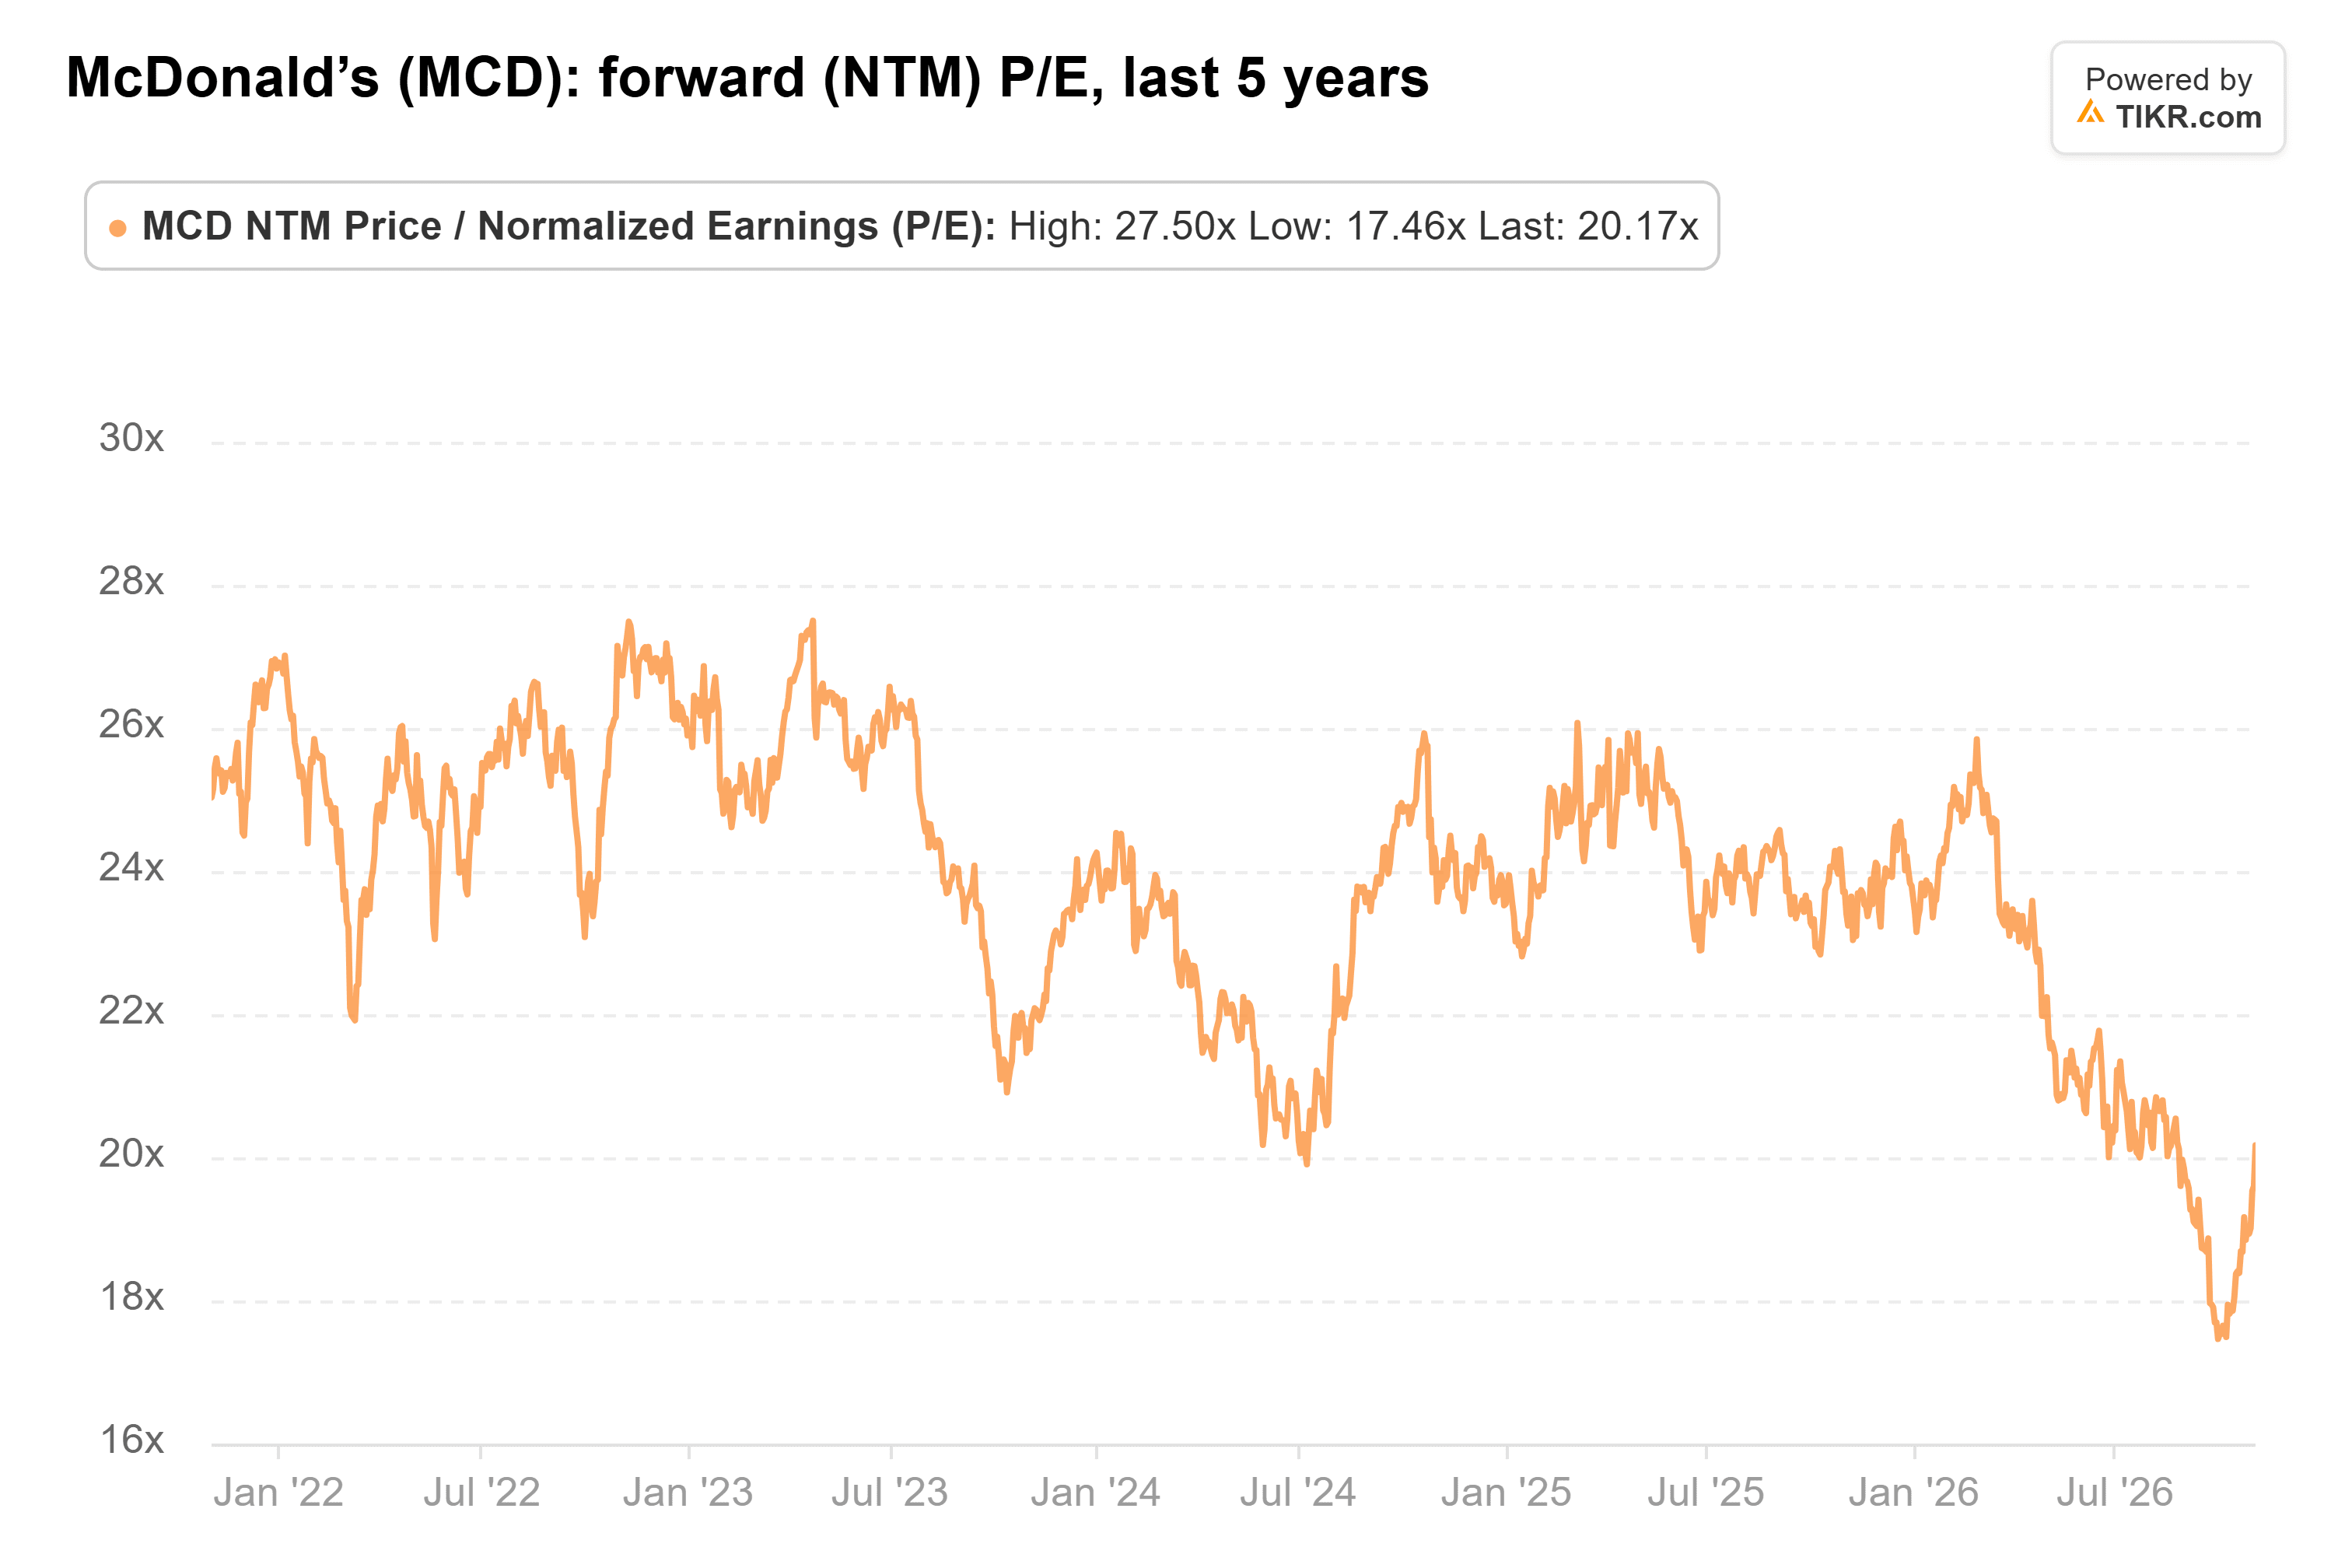
To me, that discount fits the 1% case; a 10% case would drag the estimates behind it lower. I take Mahncke’s warning seriously, and I’d wait for U.S. guest counts to turn before buying.
McDonald’s plans a national entry-level value menu in early 2027. If guests come back while GLP-1 use keeps growing, McDonald’s can offset at least some of the pressure.
So What Is McDonald’s Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what McDonald’s could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!