Key Takeaways
- Arm fell 13% and Qualcomm 9.5% on Thursday as pricier memory hit their phone businesses.
- Memory makers like Micron win from the AI-driven shortage, and phone-chip designers pick up the bill.
- Qualcomm’s gross margin fell to 50.8% from 55.3% a year earlier, and its price increases won’t fully pay off until the second half of fiscal 2027.
- Arm has data center growth to lean on. Qualcomm’s next margin is the test.
Chip stocks sold off on Nov. 5, and the two phone-chip names in the middle had the same problem: memory.
Qualcomm (QCOM) fell 9.5% after guiding December-quarter earnings below what analysts expected, as rising chip and memory costs outran its own price increases. Arm Holdings (ARM) dropped 13% after saying memory pricing in smartphones weighed on its royalties. Both bounced on Friday.
Micron Technology (MU) fell 17% in the same selloff. But Micron is the one selling the memory.
On Thursday’s Decoder, The Verge editor-in-chief Nilay Patel listed the shocks the supply chain has absorbed, from COVID to tariffs, then said:
“It feels like the only thing the system isn’t resilient to is the AI industry wanting every scrap of RAM that the whole world can produce.”
PCs are hit too: Intel expects industry PC shipments to fall about 12% this year. Qualcomm and Arm have warned on phones since February.
Qualcomm Pays Twice
Pricier memory means fewer, pricier phones, and Qualcomm’s own inputs cost more too.
Its handset revenue fell 26% to $5.14 billion in the September quarter. Automotive jumped 89% to a record $1.99 billion, but cars and IoT together added only about $1 billion against $1.8 billion lost in handsets.
For the December quarter, Qualcomm guided non-GAAP EPS to $2.15 to $2.35. Even the top of that range is 33% below the $3.50 it earned a year earlier.
TIKR Tracks 37 Analysts on Qualcomm. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
Analysts had earnings dipping in fiscal 2027, then climbing past fiscal 2025’s $12.03 a share in fiscal 2028:
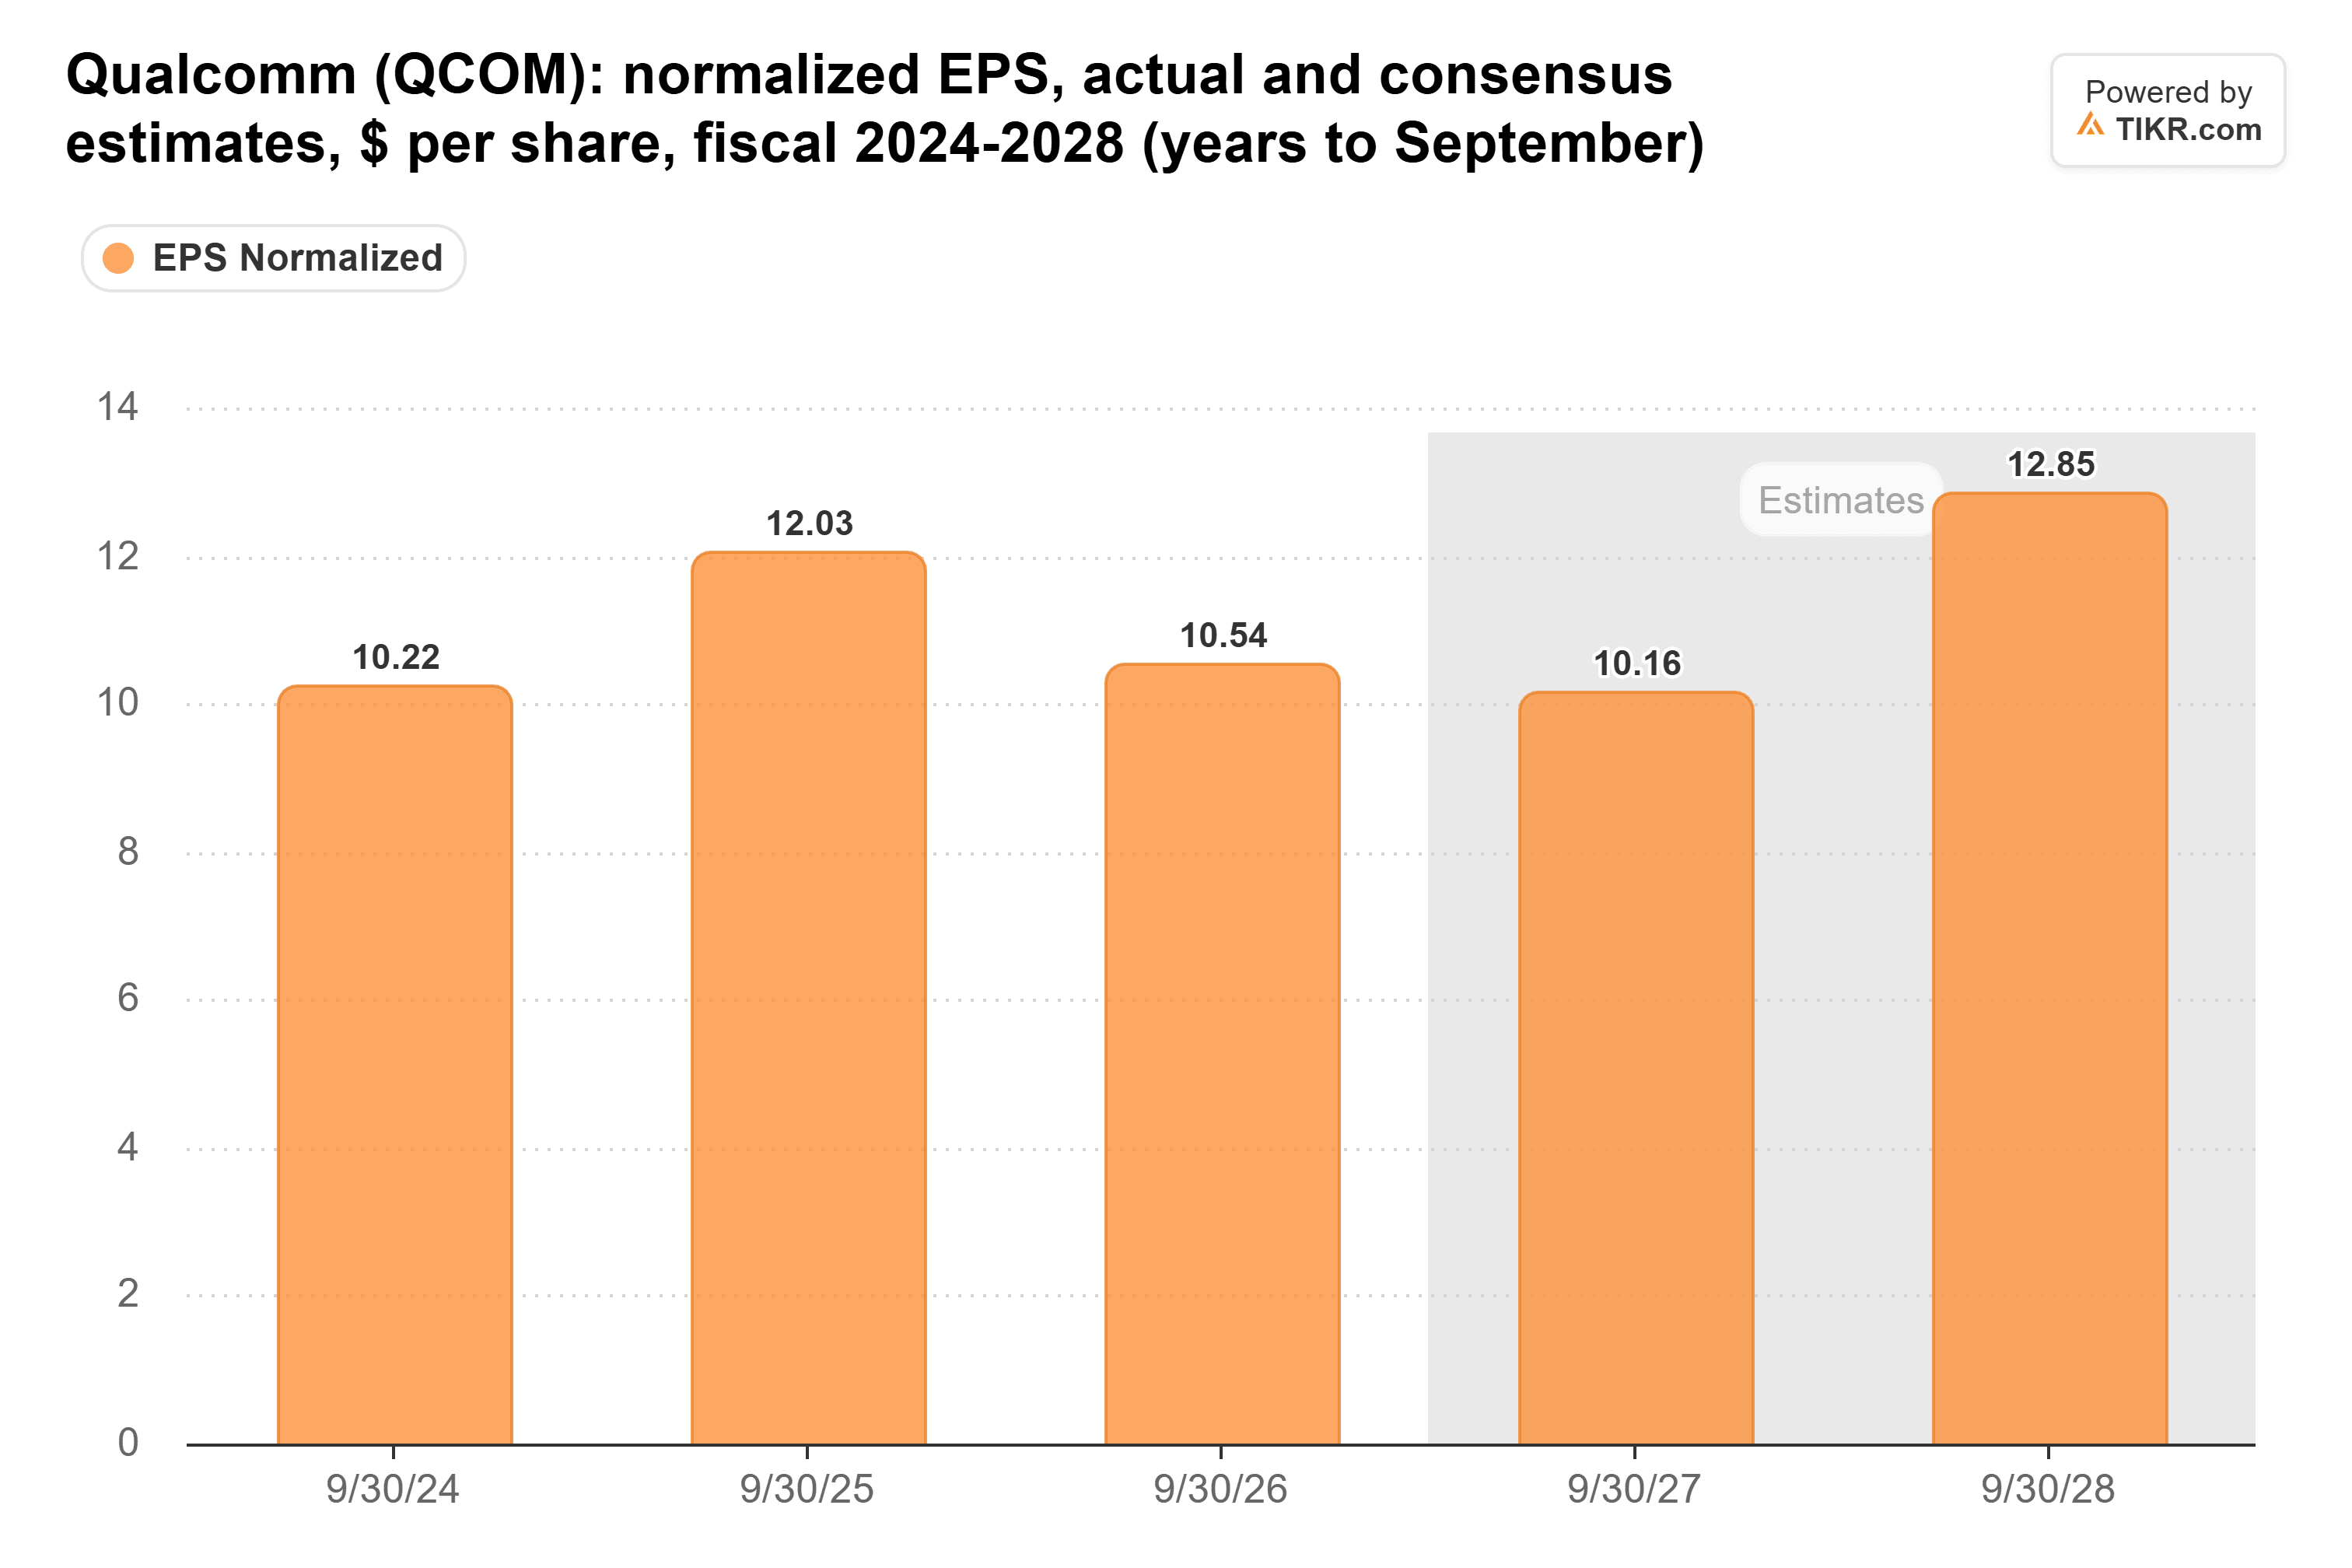
Lasting memory pressure would put that at risk. After this guide, I’d expect fiscal 2027 to come down.
Qualcomm’s Price Increases Come Late
Qualcomm said input costs are rising from wafer fabrication to memory, and its price increases won’t fully reach its chip unit’s gross margin until the second half of fiscal 2027.
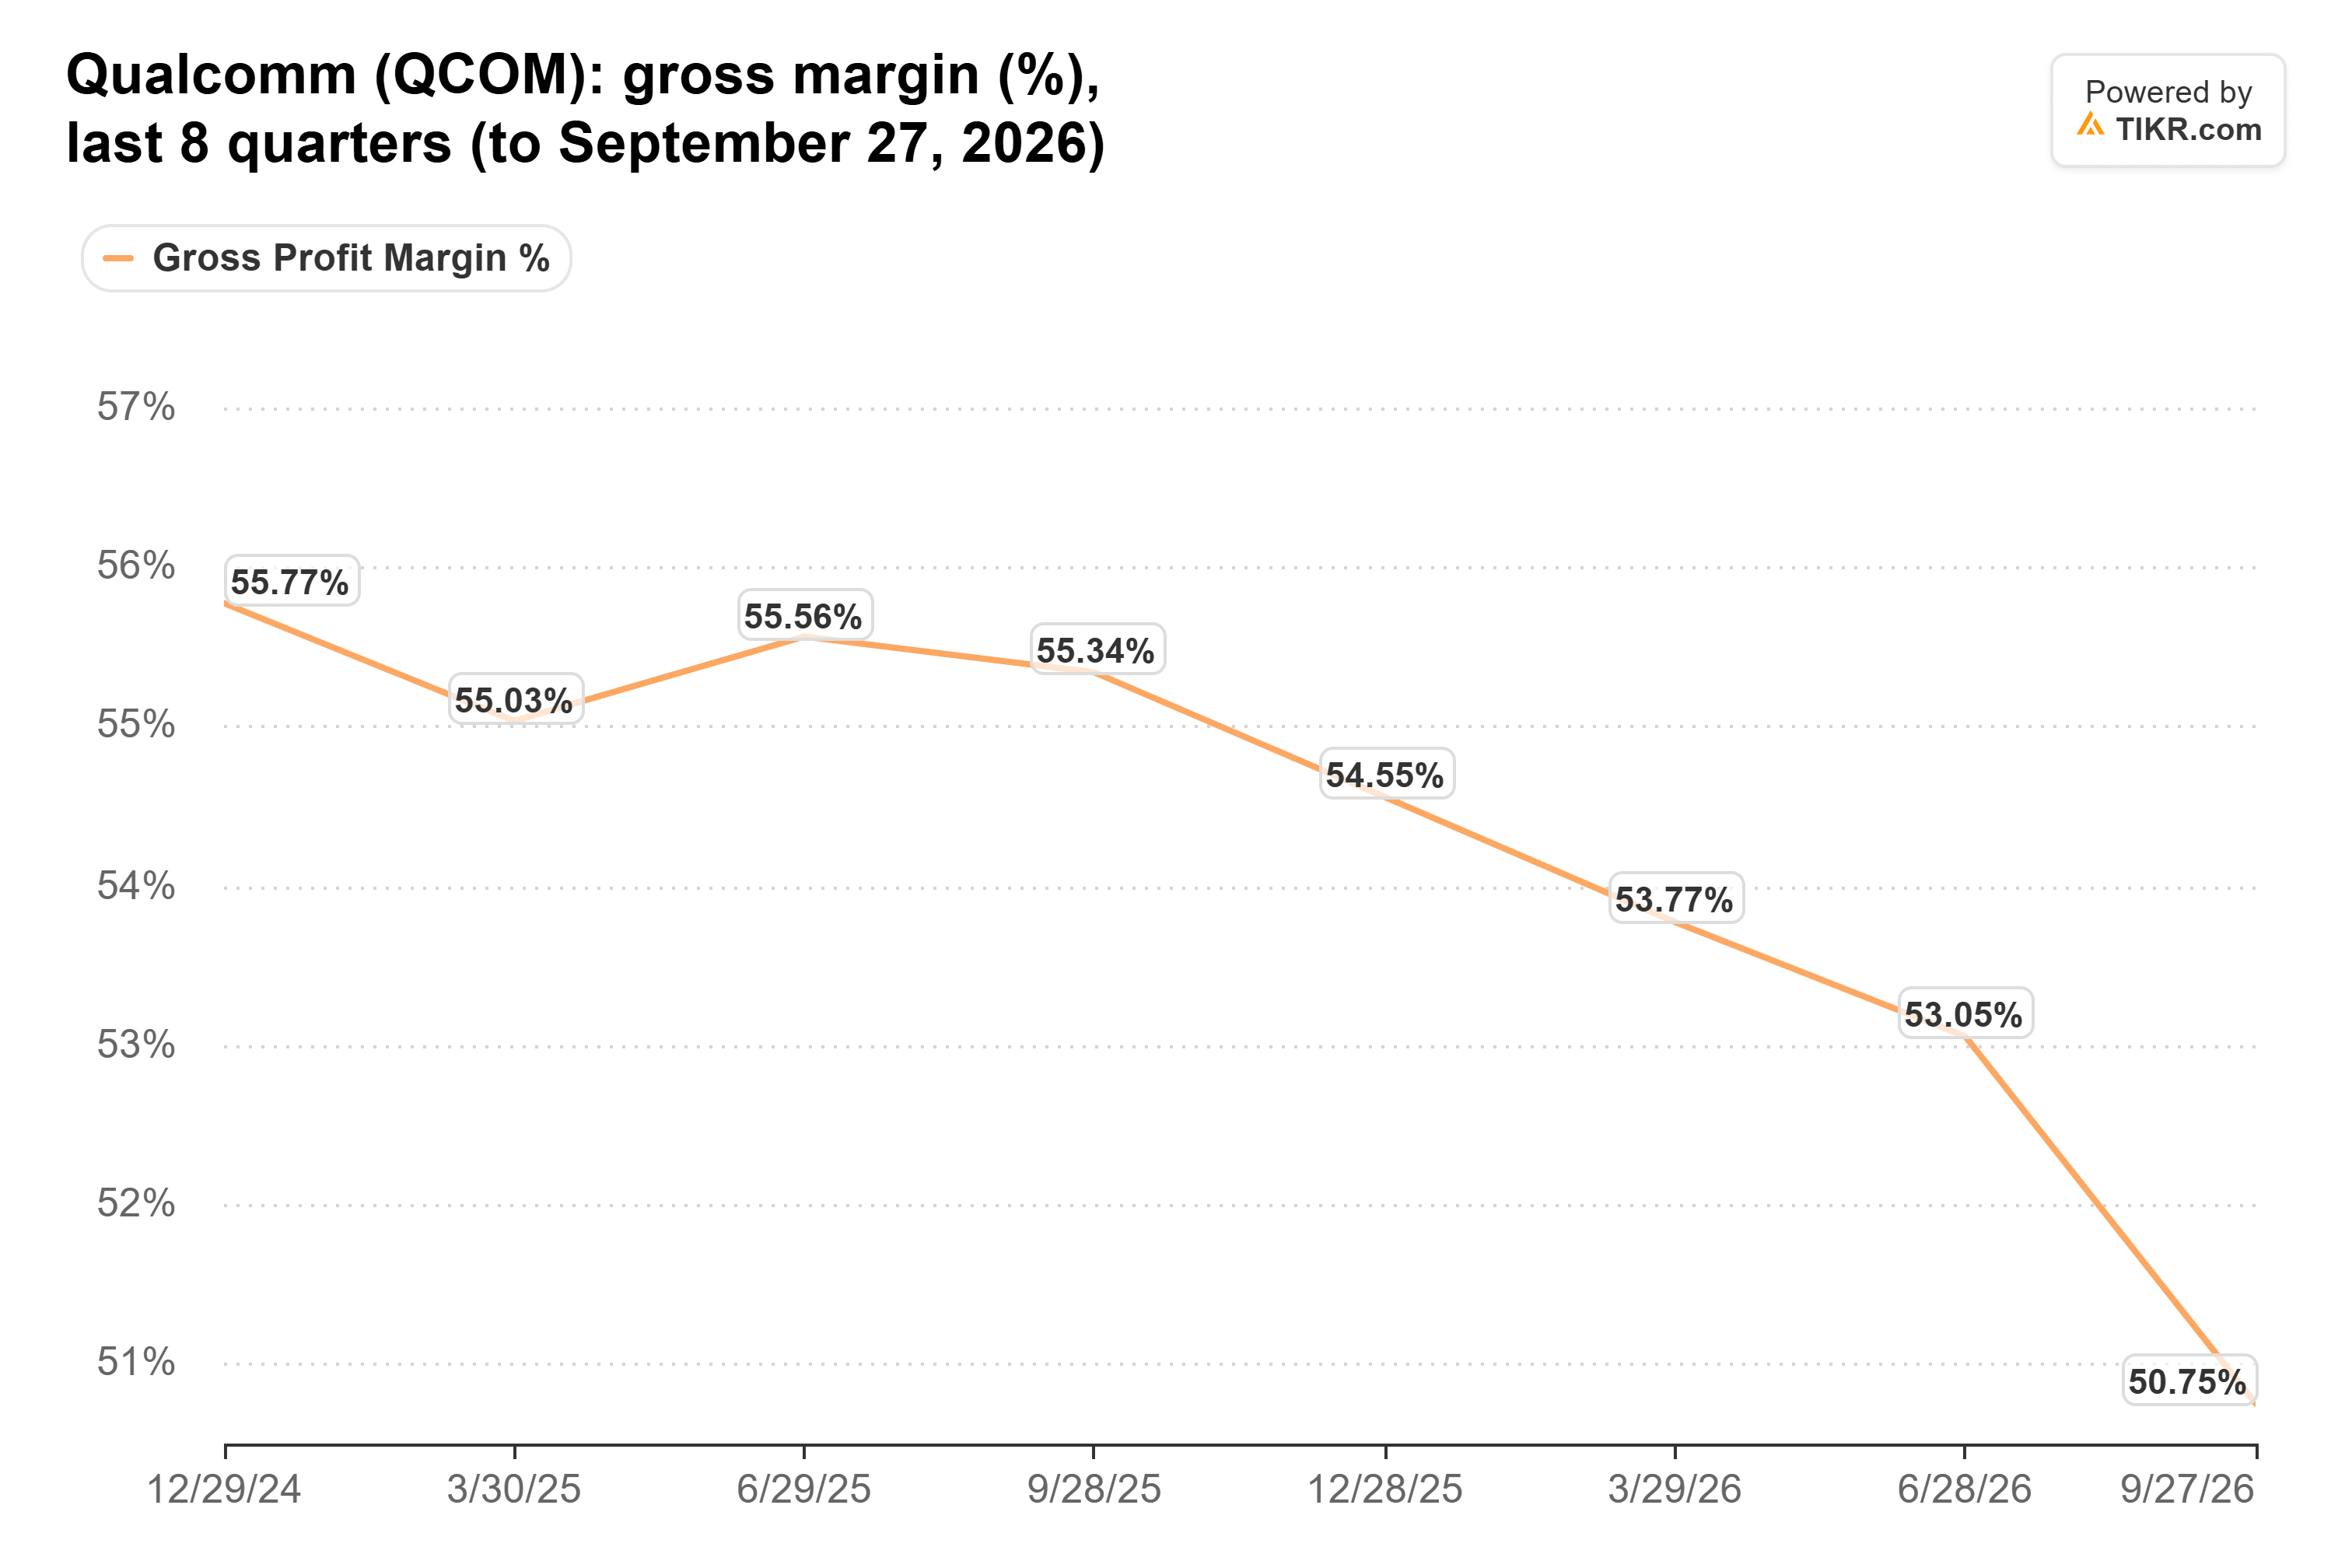
Its gross margin has fallen four quarters straight, to 50.8% from 55.3% a year earlier, and the latest drop was the steepest:
It also guided its chip unit’s pretax margin to 20% to 22% for December, from 24%, about 3 points of that from folding in data center.
Arm Feels It in Its Royalties
Arm collects royalties on chips built on its designs, Qualcomm’s included.
Its revenue rose 27% to $1.44 billion in the September quarter, but royalty revenue grew just 8% to $670 million. Arm said memory pricing in smartphones partly offset higher royalty rates and data center growth.
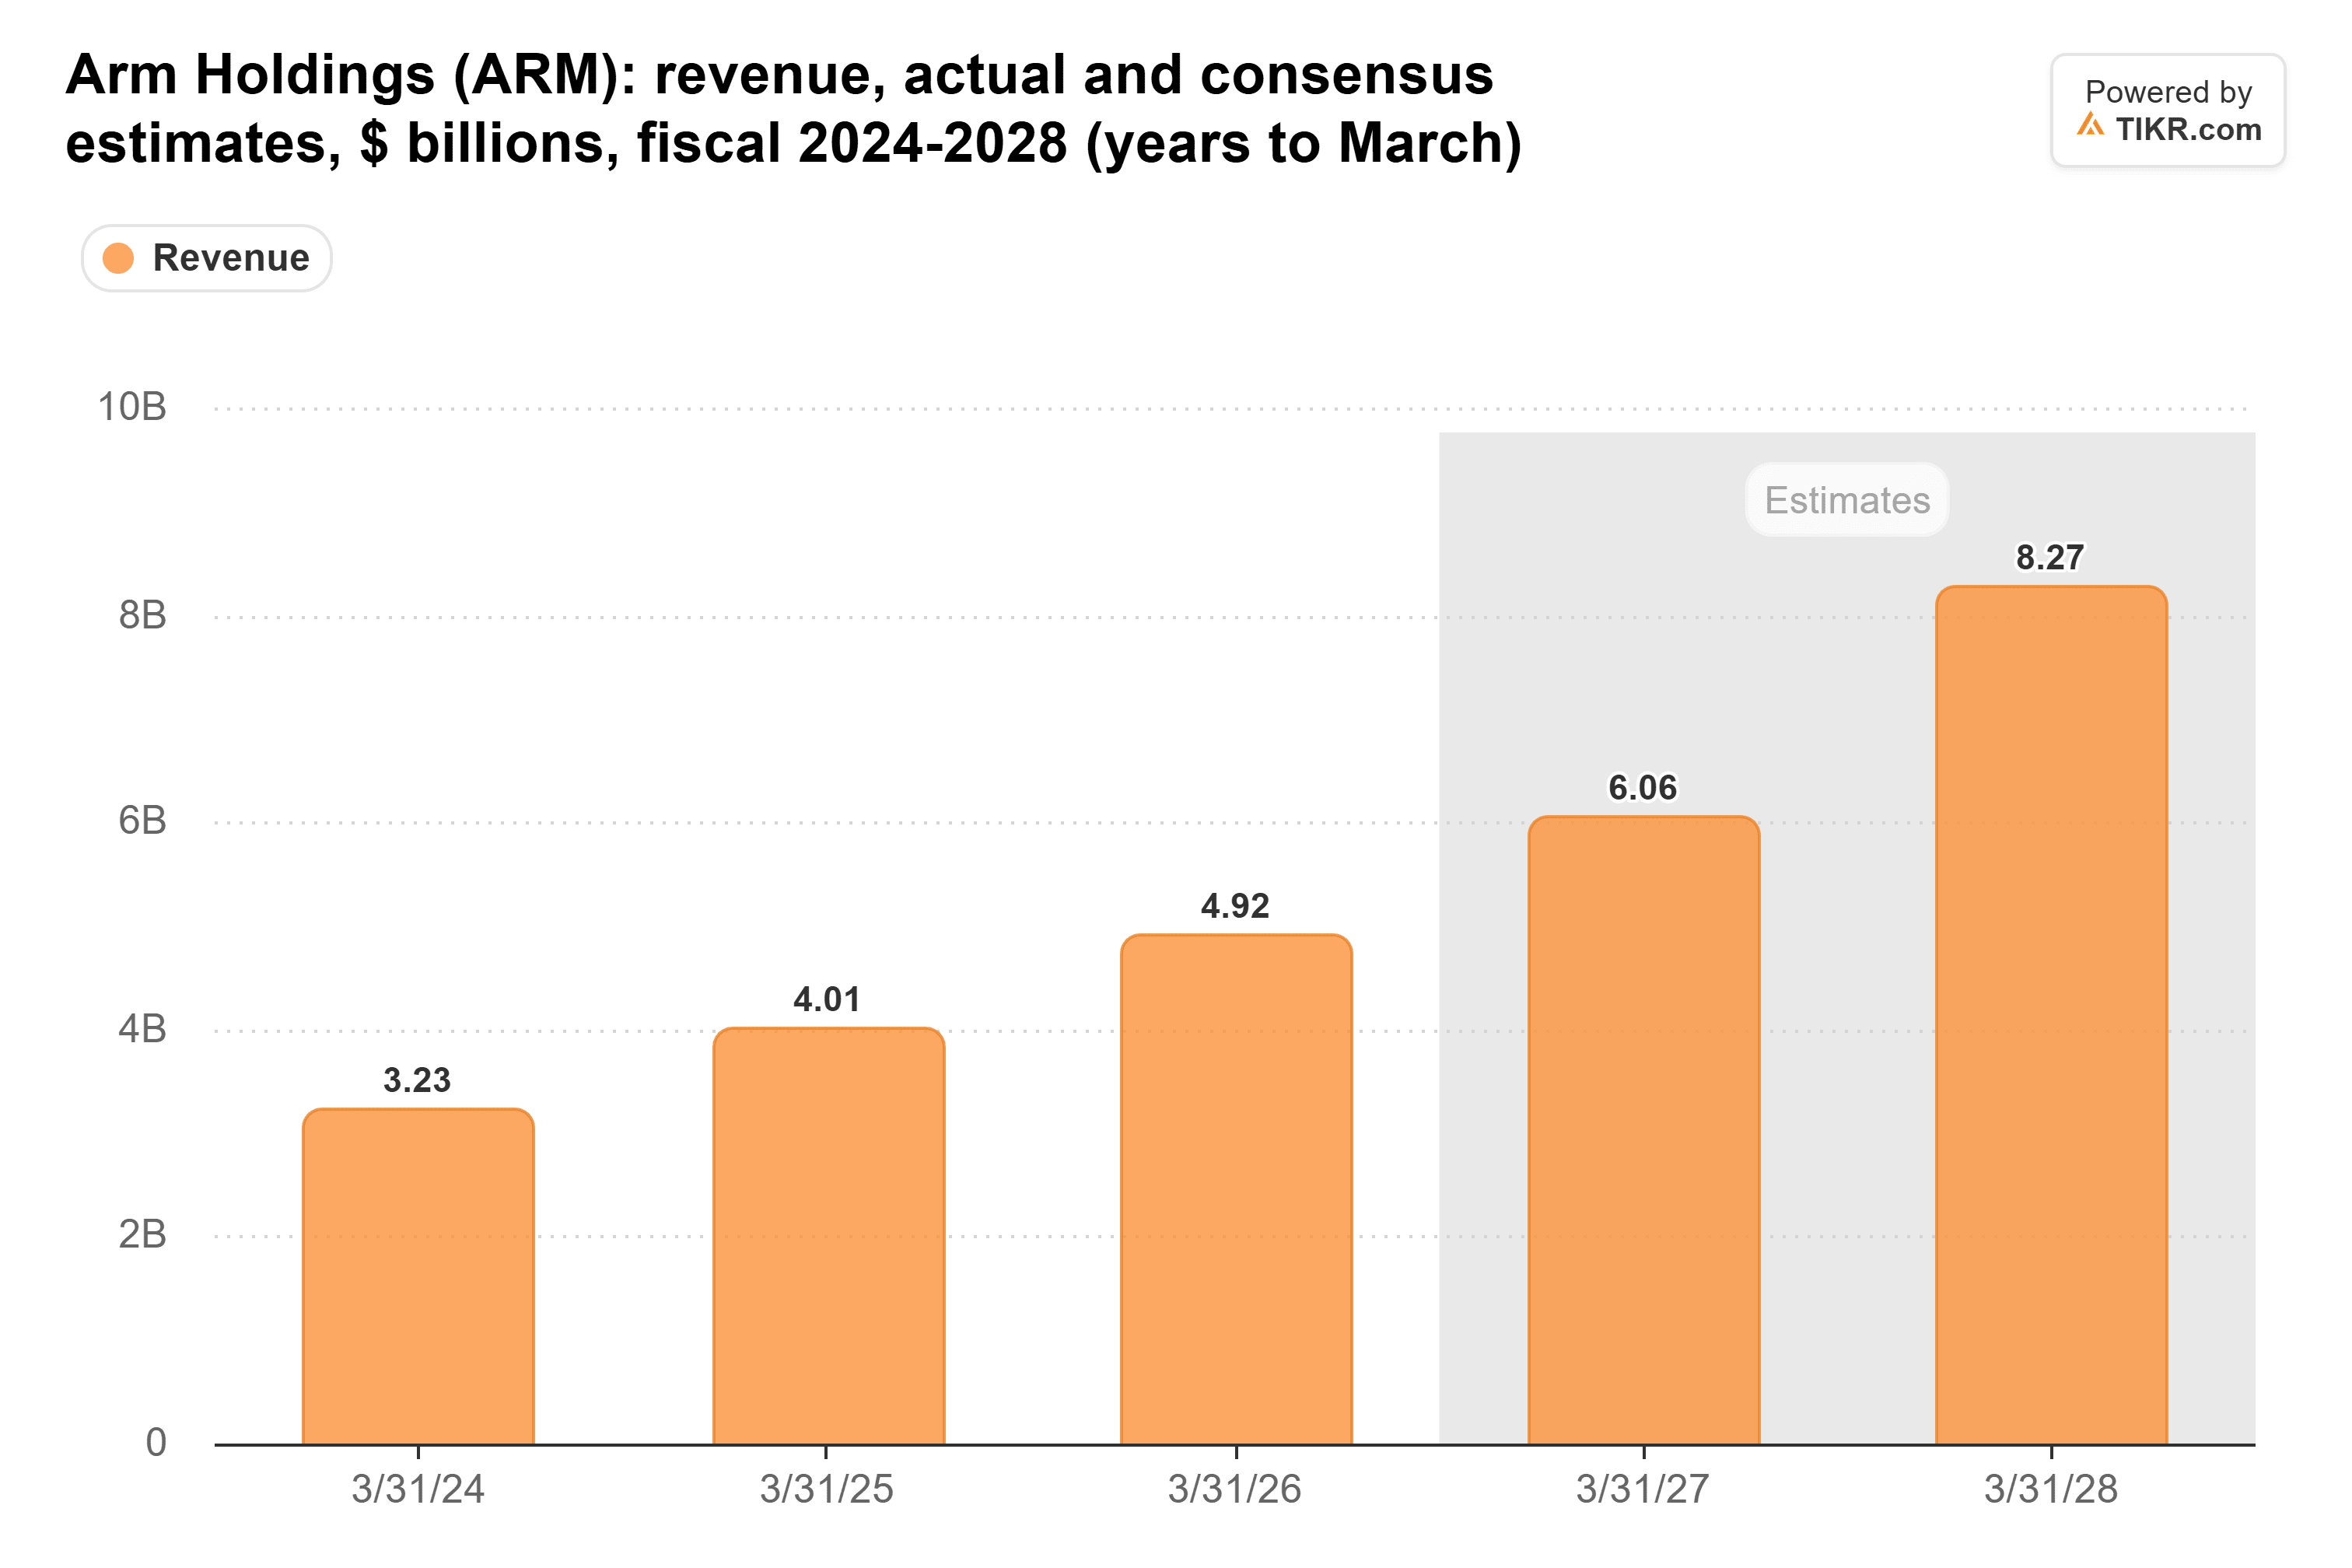
Analysts expected Arm’s revenue to climb from $4.92 billion in fiscal 2026 to $8.27 billion in fiscal 2028:
Arm has more to lean on. Its data center royalties doubled, and it’s more confident of up to $2 billion of AGI CPU revenue across fiscal 2027 and 2028. Qualcomm is chasing $5 billion of data center revenue in fiscal 2027, but handsets were $27.8 billion of its $38.4 billion of chip revenue in fiscal 2025.
Micron Sends the Bill
In its September report, Micron posted fiscal fourth-quarter revenue of $54.2 billion, against $11.3 billion a year earlier, at an 86.8% gross margin. CEO Sanjay Mehrotra said Micron expects “an even stronger fiscal 2027.”
Qualcomm Is Footing Most of the Bill
Arm has enough growth outside phones to ride this out. Qualcomm doesn’t yet, and I’d want to see its gross margin turn back up before betting the squeeze is over.
Memory prices can fall fast once new supply arrives, though, and that could lift Qualcomm’s margin sooner than guided. Its December-quarter report will show which comes first.
So What Is Qualcomm Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!