


Key Takeaways
- First Solar has fallen [43%] from its June 3 closing high. On Oct. 8, Goldman Sachs cut its price target to $272 from $310 and kept its Buy rating, which still points to 51% upside.
- Goldman’s new target is close to the $274 consensus, and even Wall Street’s lowest target, $197, is above the Oct. 7 close.
- Consensus earnings estimates for 2026 and 2027 have barely moved in 90 days, so the stock’s fall has come from a lower multiple.
- Goldman’s call looks plausible but stretched. On today’s estimates, the stock would need to trade at [12.9x] forward earnings, up from [8.5x].
First Solar (FSLR) closed at [$180.13] on Oct. 7, [43%] below its June 3 closing high of $318.25. On the morning of Oct. 8, Goldman Sachs analyst Brian Lee cut his price target to $272 from $310 and kept his Buy rating.
That’s a 12% cut to the target after a 43% drop in the stock, so Goldman’s upside has grown to [51%]. Lee had raised the target to $310 from $300 on May 1.
Waiting on Washington
On July 30, First Solar reported second-quarter earnings of $3.92 a share, up 23% from a year earlier. Sales fell 4% to $1.06 billion, and 2026 guidance stayed where it was.
Policy hung over the call. The Section 232 investigation into polysilicon imports was still pending, and CEO Mark Widmar said “there clearly are customers that are sitting on the sidelines.”
Rates added pressure. On Sept. 24, shares fell about 10% to a new 52-week low as rising Treasury yields hit solar stocks.
Why Goldman Still Says Buy
Lee expects a subdued third-quarter report because of broader macro pressures, according to TheFly’s summary of the note. But he also points to favorable bookings and demand this year, especially in utility-scale solar, and notes the shares trade near their valuation low for the year. If bookings beat muted expectations, he sees room for the stock to rise.
First Solar’s numbers back the demand side. It ended June with 45.1 GW of contracted backlog running through 2030, and Widmar pointed to “somewhat insatiable demand from hyperscalers.”
The rest of the Street agrees. Since March 31, Buy ratings have gone from 12 to 16 and Holds from 14 to 9.
Does $272 Add Up for First Solar Stock?

Goldman isn’t out on a limb. Its $272 is close to the $274 consensus target, and even the lowest of 30 targets, $197, is above the stock. A year ago, the stock and the consensus target were level, near $228. Since then, they’ve gone opposite ways…

Analysts also expect First Solar’s normalized EPS to climb from $14.21 in 2025 to $23.21 in 2027, a 63% gain in two years.
The selloff hasn’t dented those numbers. The 2026 and 2027 consensus estimates are each within 1% of where they stood 90 days ago. Investors are paying less for the same expected earnings.
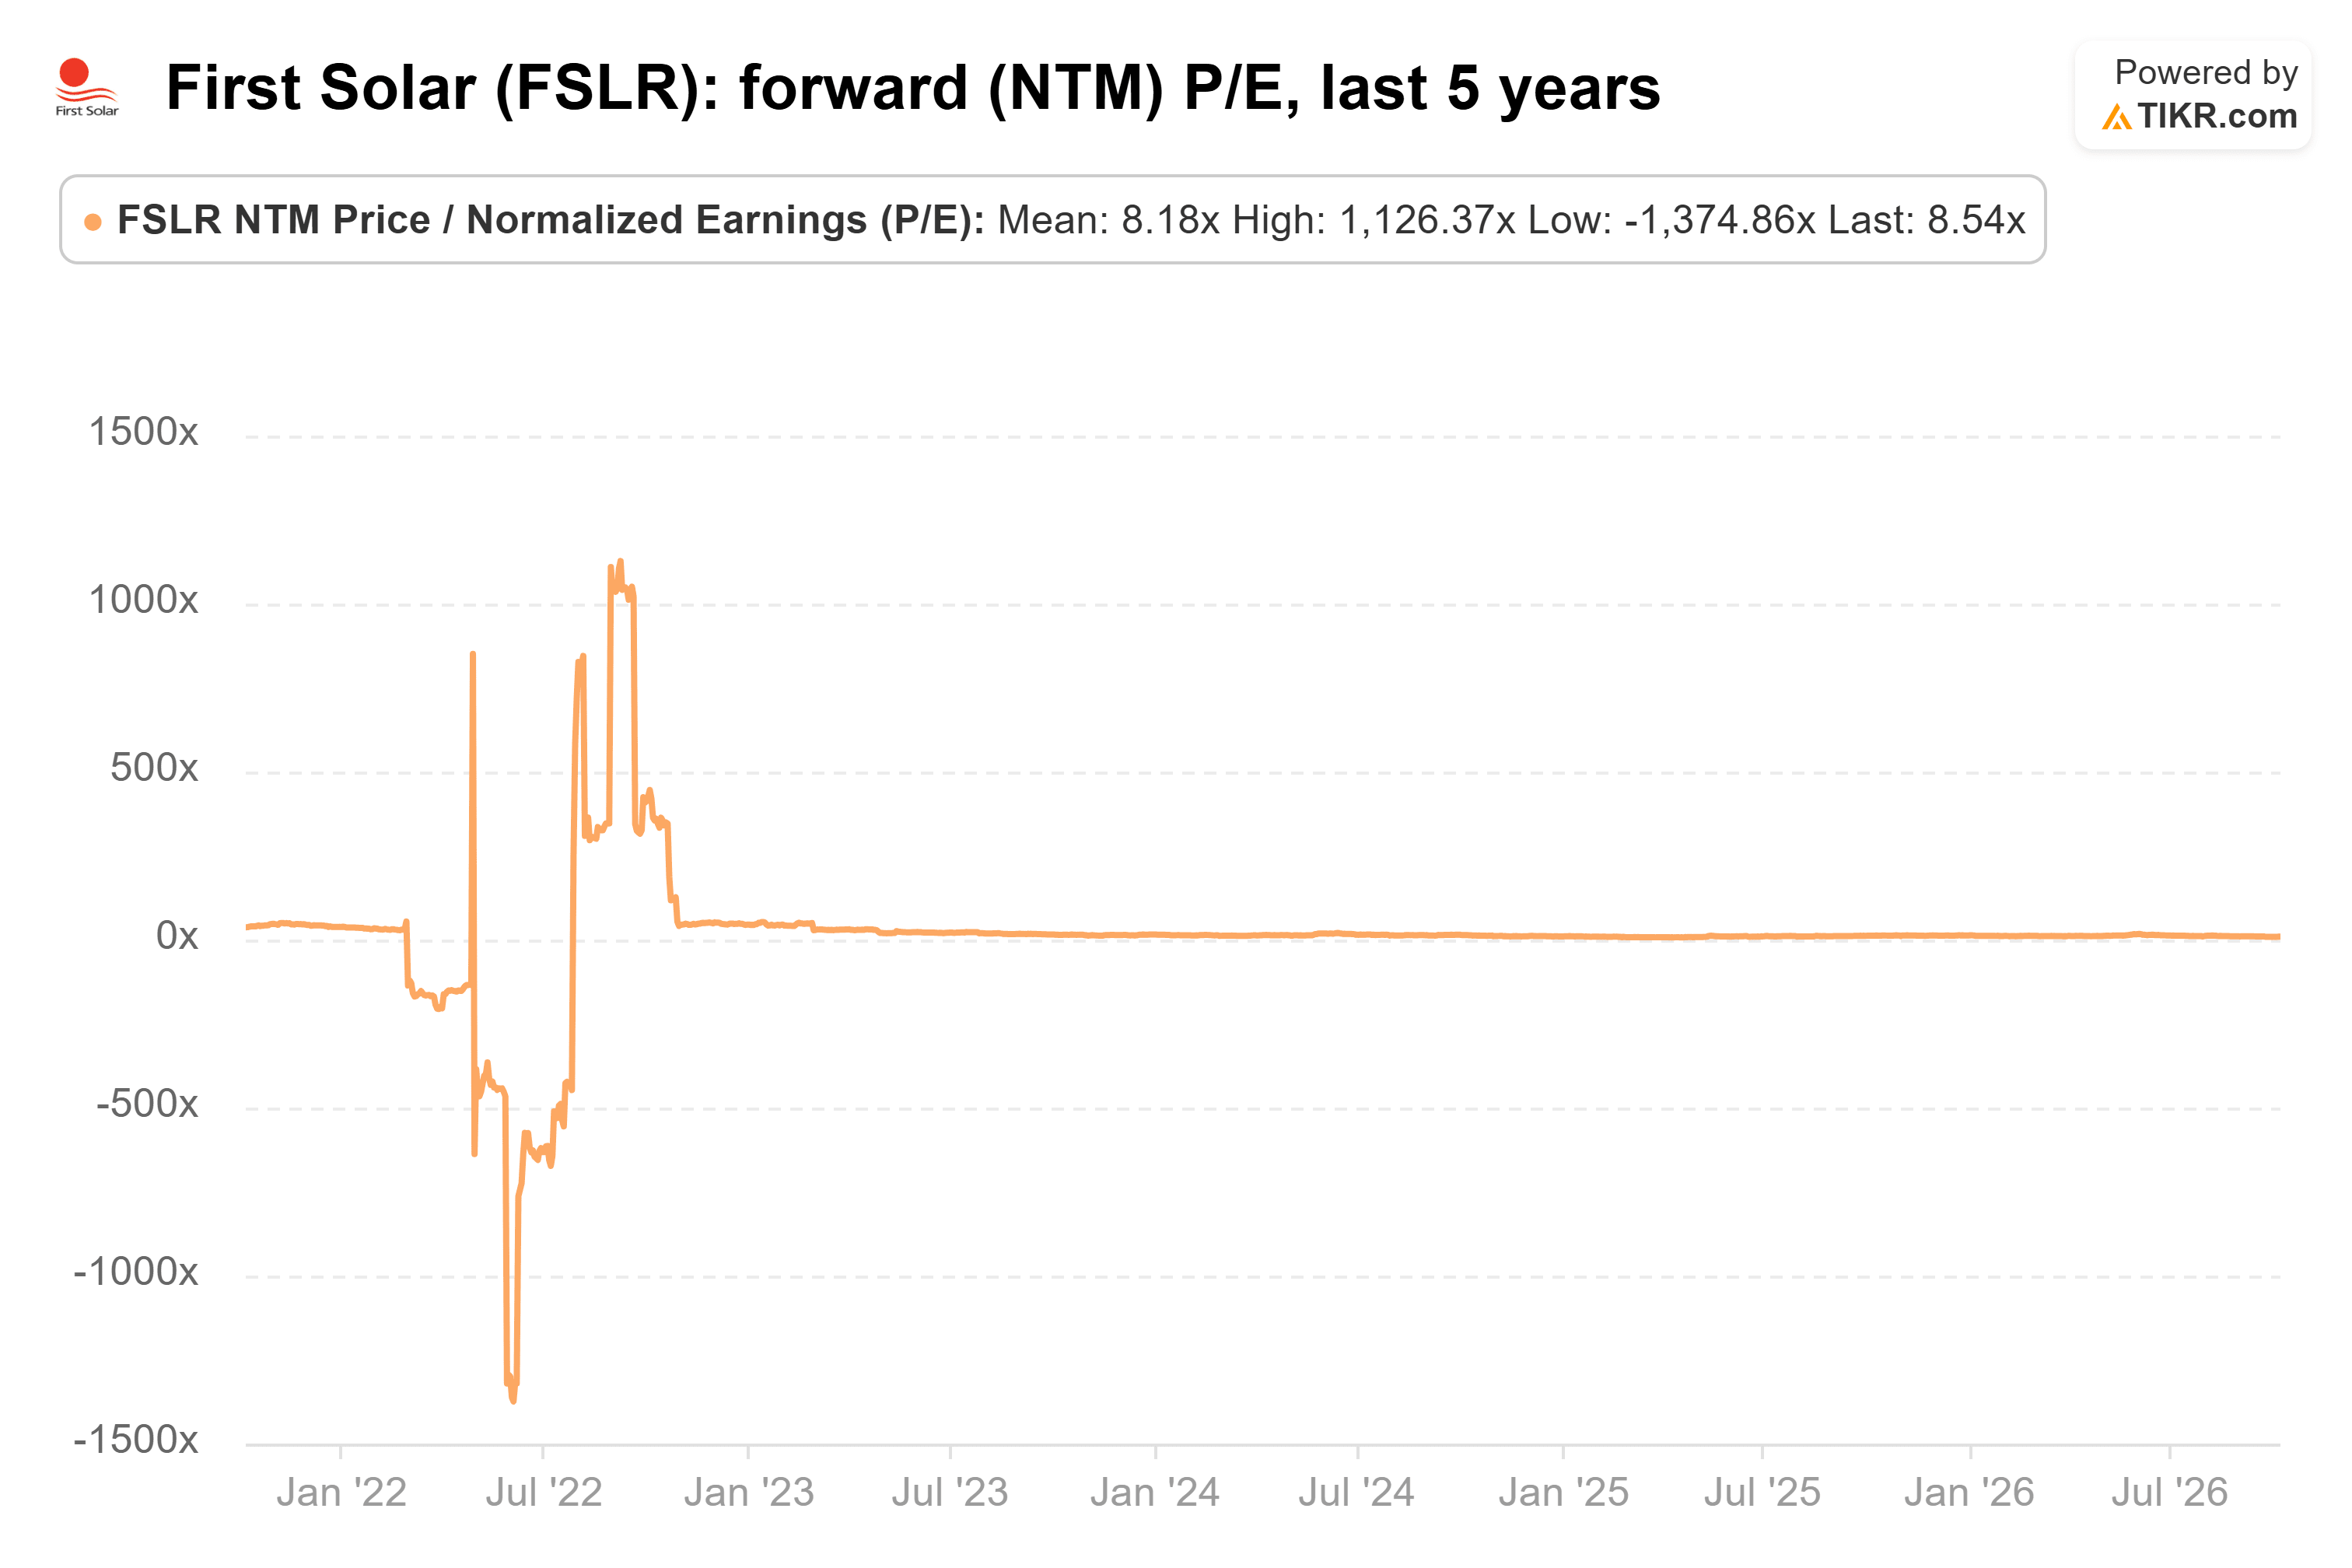
At [$180.13] and [8.5x] forward earnings, First Solar is priced on about [$21] of earnings per share over the next 12 months. Goldman’s $272 works out to [12.9x] those earnings, so on today’s estimates, nearly all of the [51%] upside has to come from a higher multiple.
Time helps a little. A year from now, the next 12 months lean on 2027’s $23.21, and $272 would need about 11.7x.
What Could Keep the Multiple Low
Policy is the main risk. First Solar’s guidance assumes the current US policy environment holds, and the Section 232 outcome could still change what customers are willing to sign.
The P/E history doesn’t settle it either. The stock trades at [8.5x] against a five-year average of 8.2x, but 2022’s wild swings, when expected earnings were near zero, make that average close to meaningless.
The Bottom Line on First Solar Stock
My view is that Goldman’s call is plausible but stretched. The business is holding up, with estimates steady and a backlog to 2030. But $272 needs the stock at [12.9x] forward earnings, up from [8.5x], and Sept. 24 showed how fast rates can knock solar stocks down.
The next test is the third-quarter report, where First Solar guided to $625 million to $775 million of adjusted EBITDA. The company hasn’t set a date yet; last year it reported on Oct. 30. A result inside that range, with 2026 guidance held again, would make $272 easier to reach.
You can pull up the same target history, EPS estimates and forward P/E chart for First Solar on TIKR for free, and check them again after the third-quarter report. Learn more here.
So what is First Solar stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what First Solar could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


