


Key Takeaways
- Barclays raised its ExxonMobil price target to $206 from $200 and kept its Overweight rating. The new target is 23% above the stock price, after a 40% gain in a year.
- ExxonMobil’s third quarter, lifted by refining, produced $19.1 billion of free cash flow, and the company plans $20 billion of buybacks in 2027.
- Analysts expect normalized earnings per share to fall from $13.69 this year to $10.32 in 2028.
- Barclays’ target needs an above-average multiple on earnings that are expected to shrink, which looks too optimistic for a 12-month target.
ExxonMobil (XOM) has gained 40% in a year, and Barclays thinks there’s more to come. On Nov. 13, the firm raised its price target to $206 from $200, 23% above the stock’s $166.87 close on Nov. 16, and kept its Overweight rating.
A big quarter, mostly from refining
Barclays’ raise followed a third quarter lifted by the Middle East conflict. Adjusted earnings rose to $4.23 a share from $3.52 in the second quarter, and free cash flow reached $19.1 billion. The Energy Products segment, mostly refining, more than doubled its adjusted earnings to $9.1 billion from $4.1 billion, while Upstream earnings fell to $7.3 billion from $9.2 billion.
CEO Darren Woods said the gains “are lasting improvements, not simply the result of favorable prices and margins,” pointing to $16.9 billion of structural cost savings since 2019.
ExxonMobil is handing much of that cash back, with $20 billion of buybacks planned for 2027, assuming reasonable market conditions, and a 44th straight year of annual dividend increases. On Nov. 16, it started production at Uaru, its fifth development in Guyana, lifting Guyana’s installed capacity to 1.1 million barrels a day.
TIKR tracks 26 analysts on Exxon Mobil. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Exxon Mobil, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Exxon Mobil’s Analyst Ratings
Barclays is near the top of the Street
Barclays said third-quarter exploration and production results supported its U.S. outlook, which it described as “defined by capital discipline, measured growth and a durable shareholder-return setup,” according to TheFly. Its $206 sits 12% above the $184 consensus target and just under the Street’s $213 high. Bernstein went the other way, cutting its target to $186 from $193 on Nov. 12 while keeping its Outperform rating.
Barclays analyst Betty Jiang used her question on ExxonMobil’s third-quarter call to ask about secondary recovery in the Permian, part of ExxonMobil’s goal of doubling how much oil its wells there recover. Woods said that work would likely show up mostly in the years beyond 2030, well past any 12-month target.
Does $206 add up?
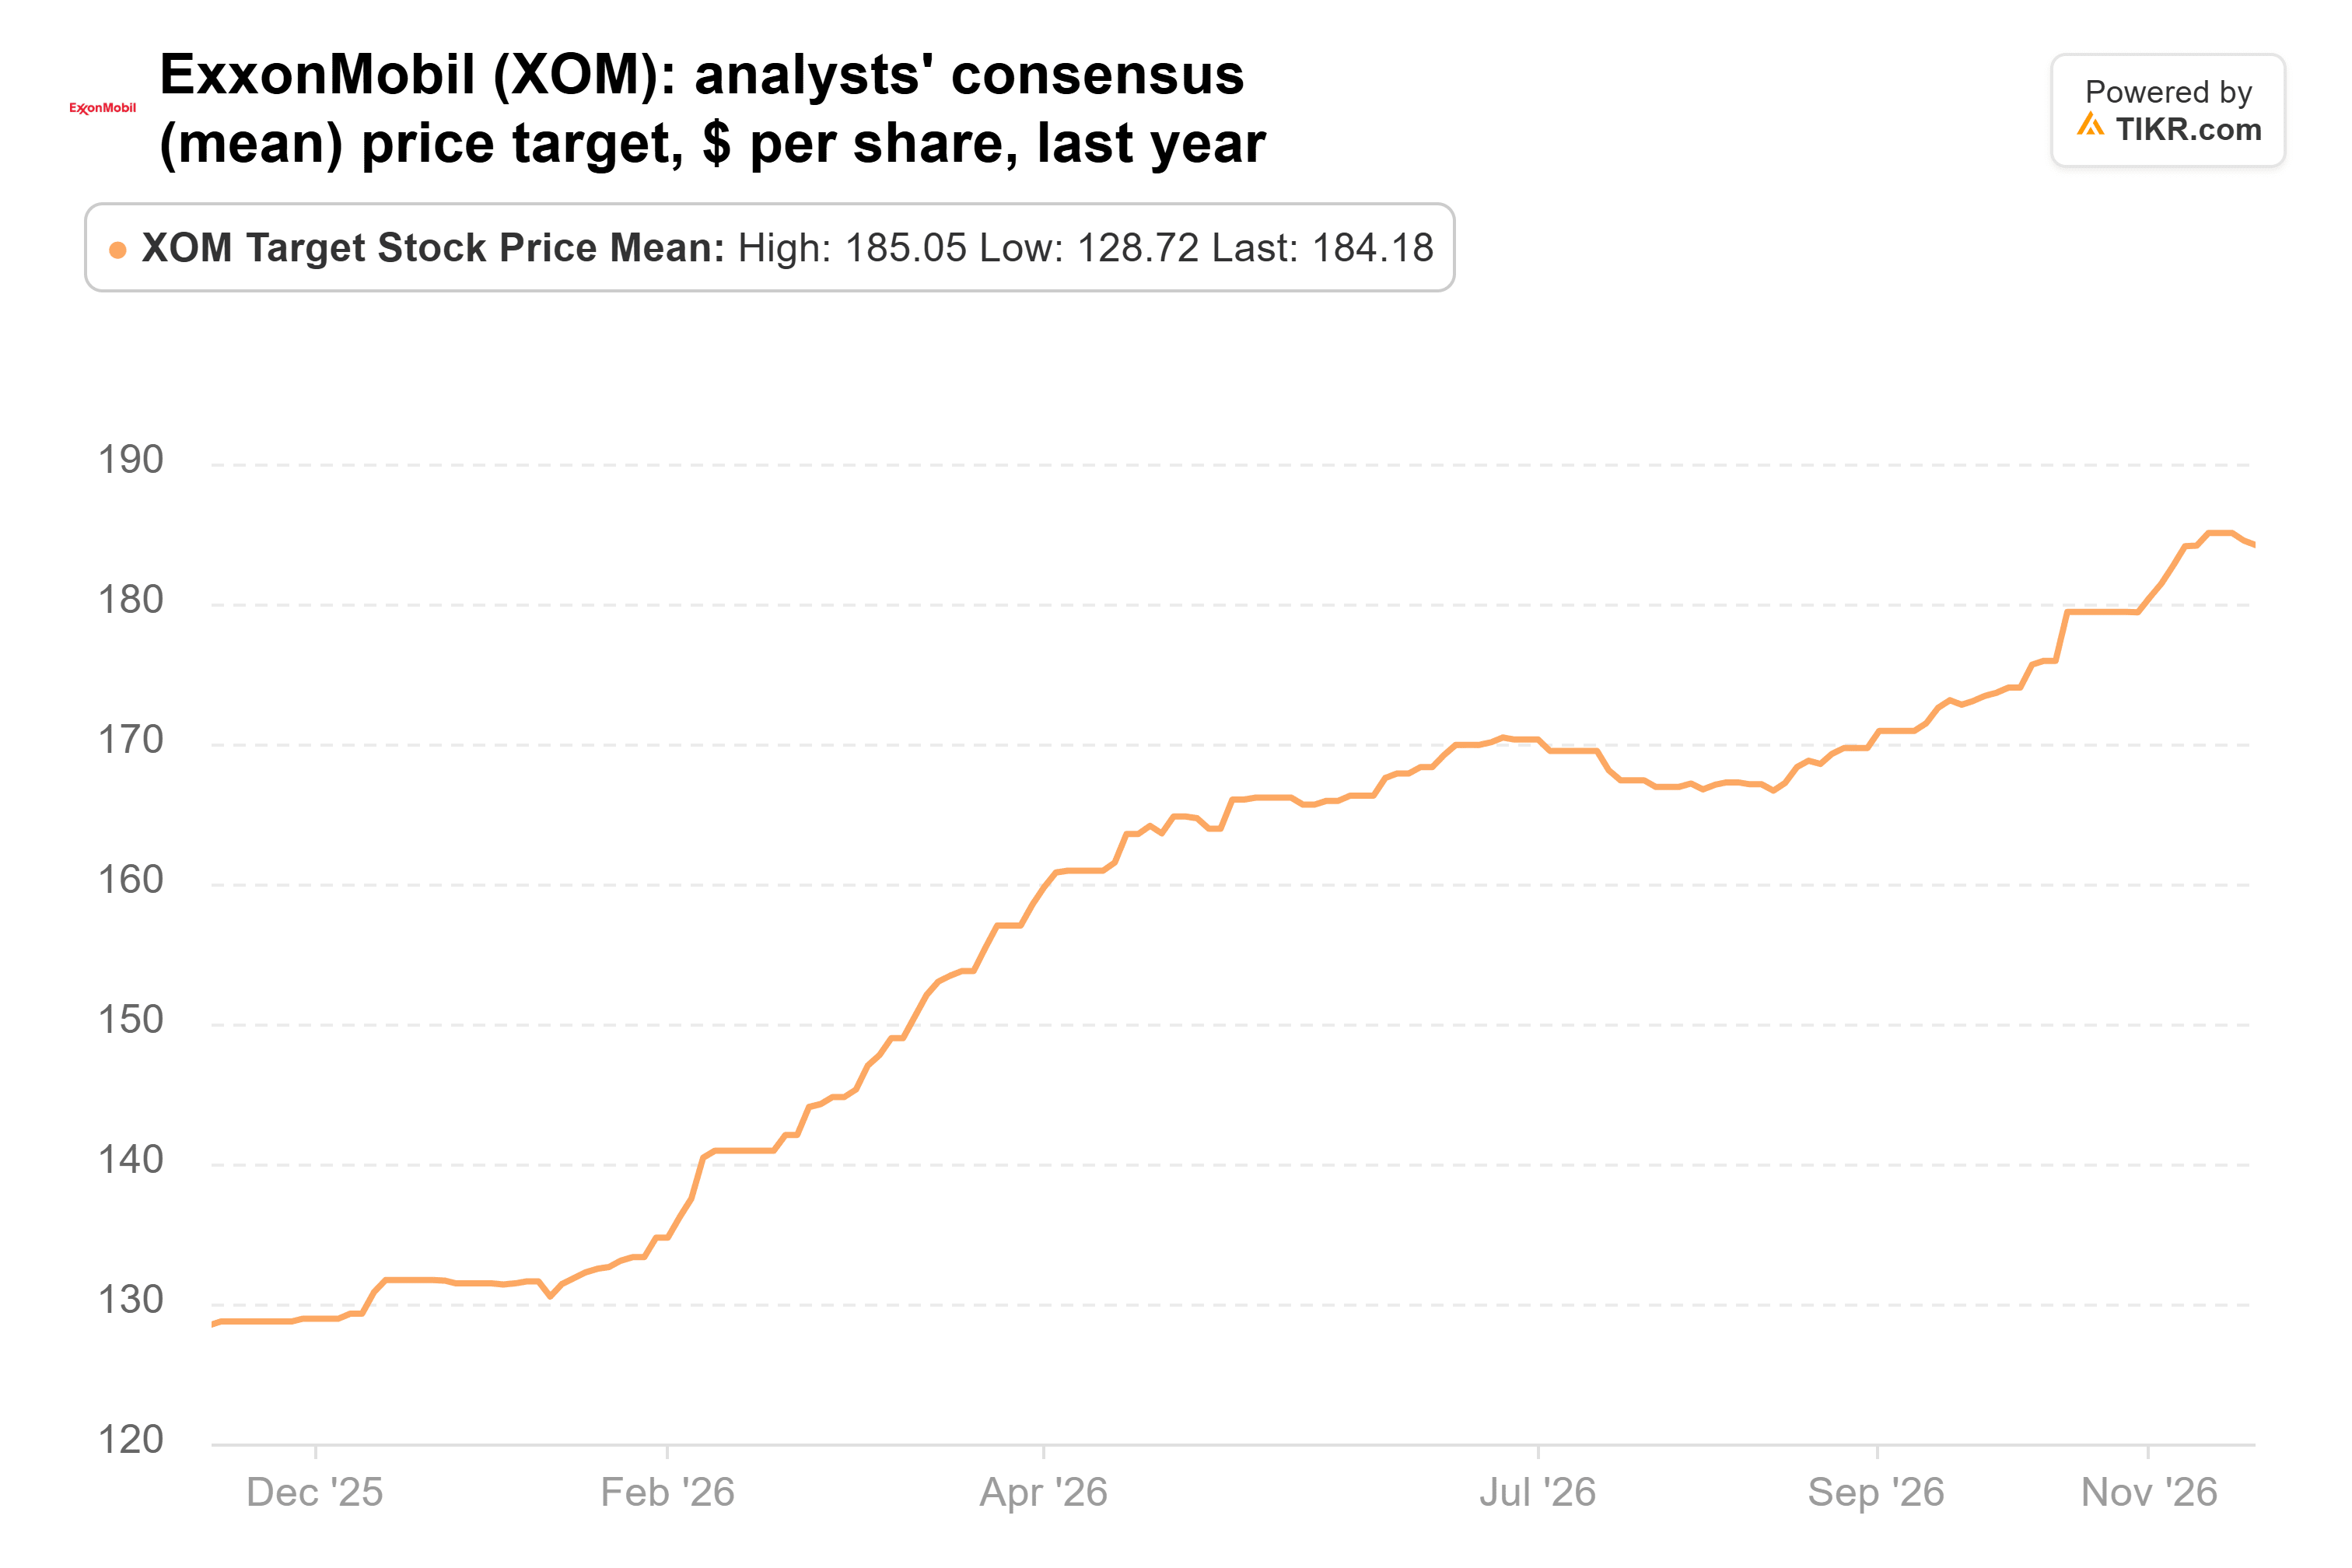
The consensus target has climbed from $129 a year ago to $184, 10% above the price, with the lowest target at $160:
Earnings estimates moved just as fast: analysts now expect $13.69 a share of normalized earnings this year, up from $11.51 90 days ago and almost double 2025’s $6.99. But they see that falling to $12.64 in 2027 and $10.32 in 2028:
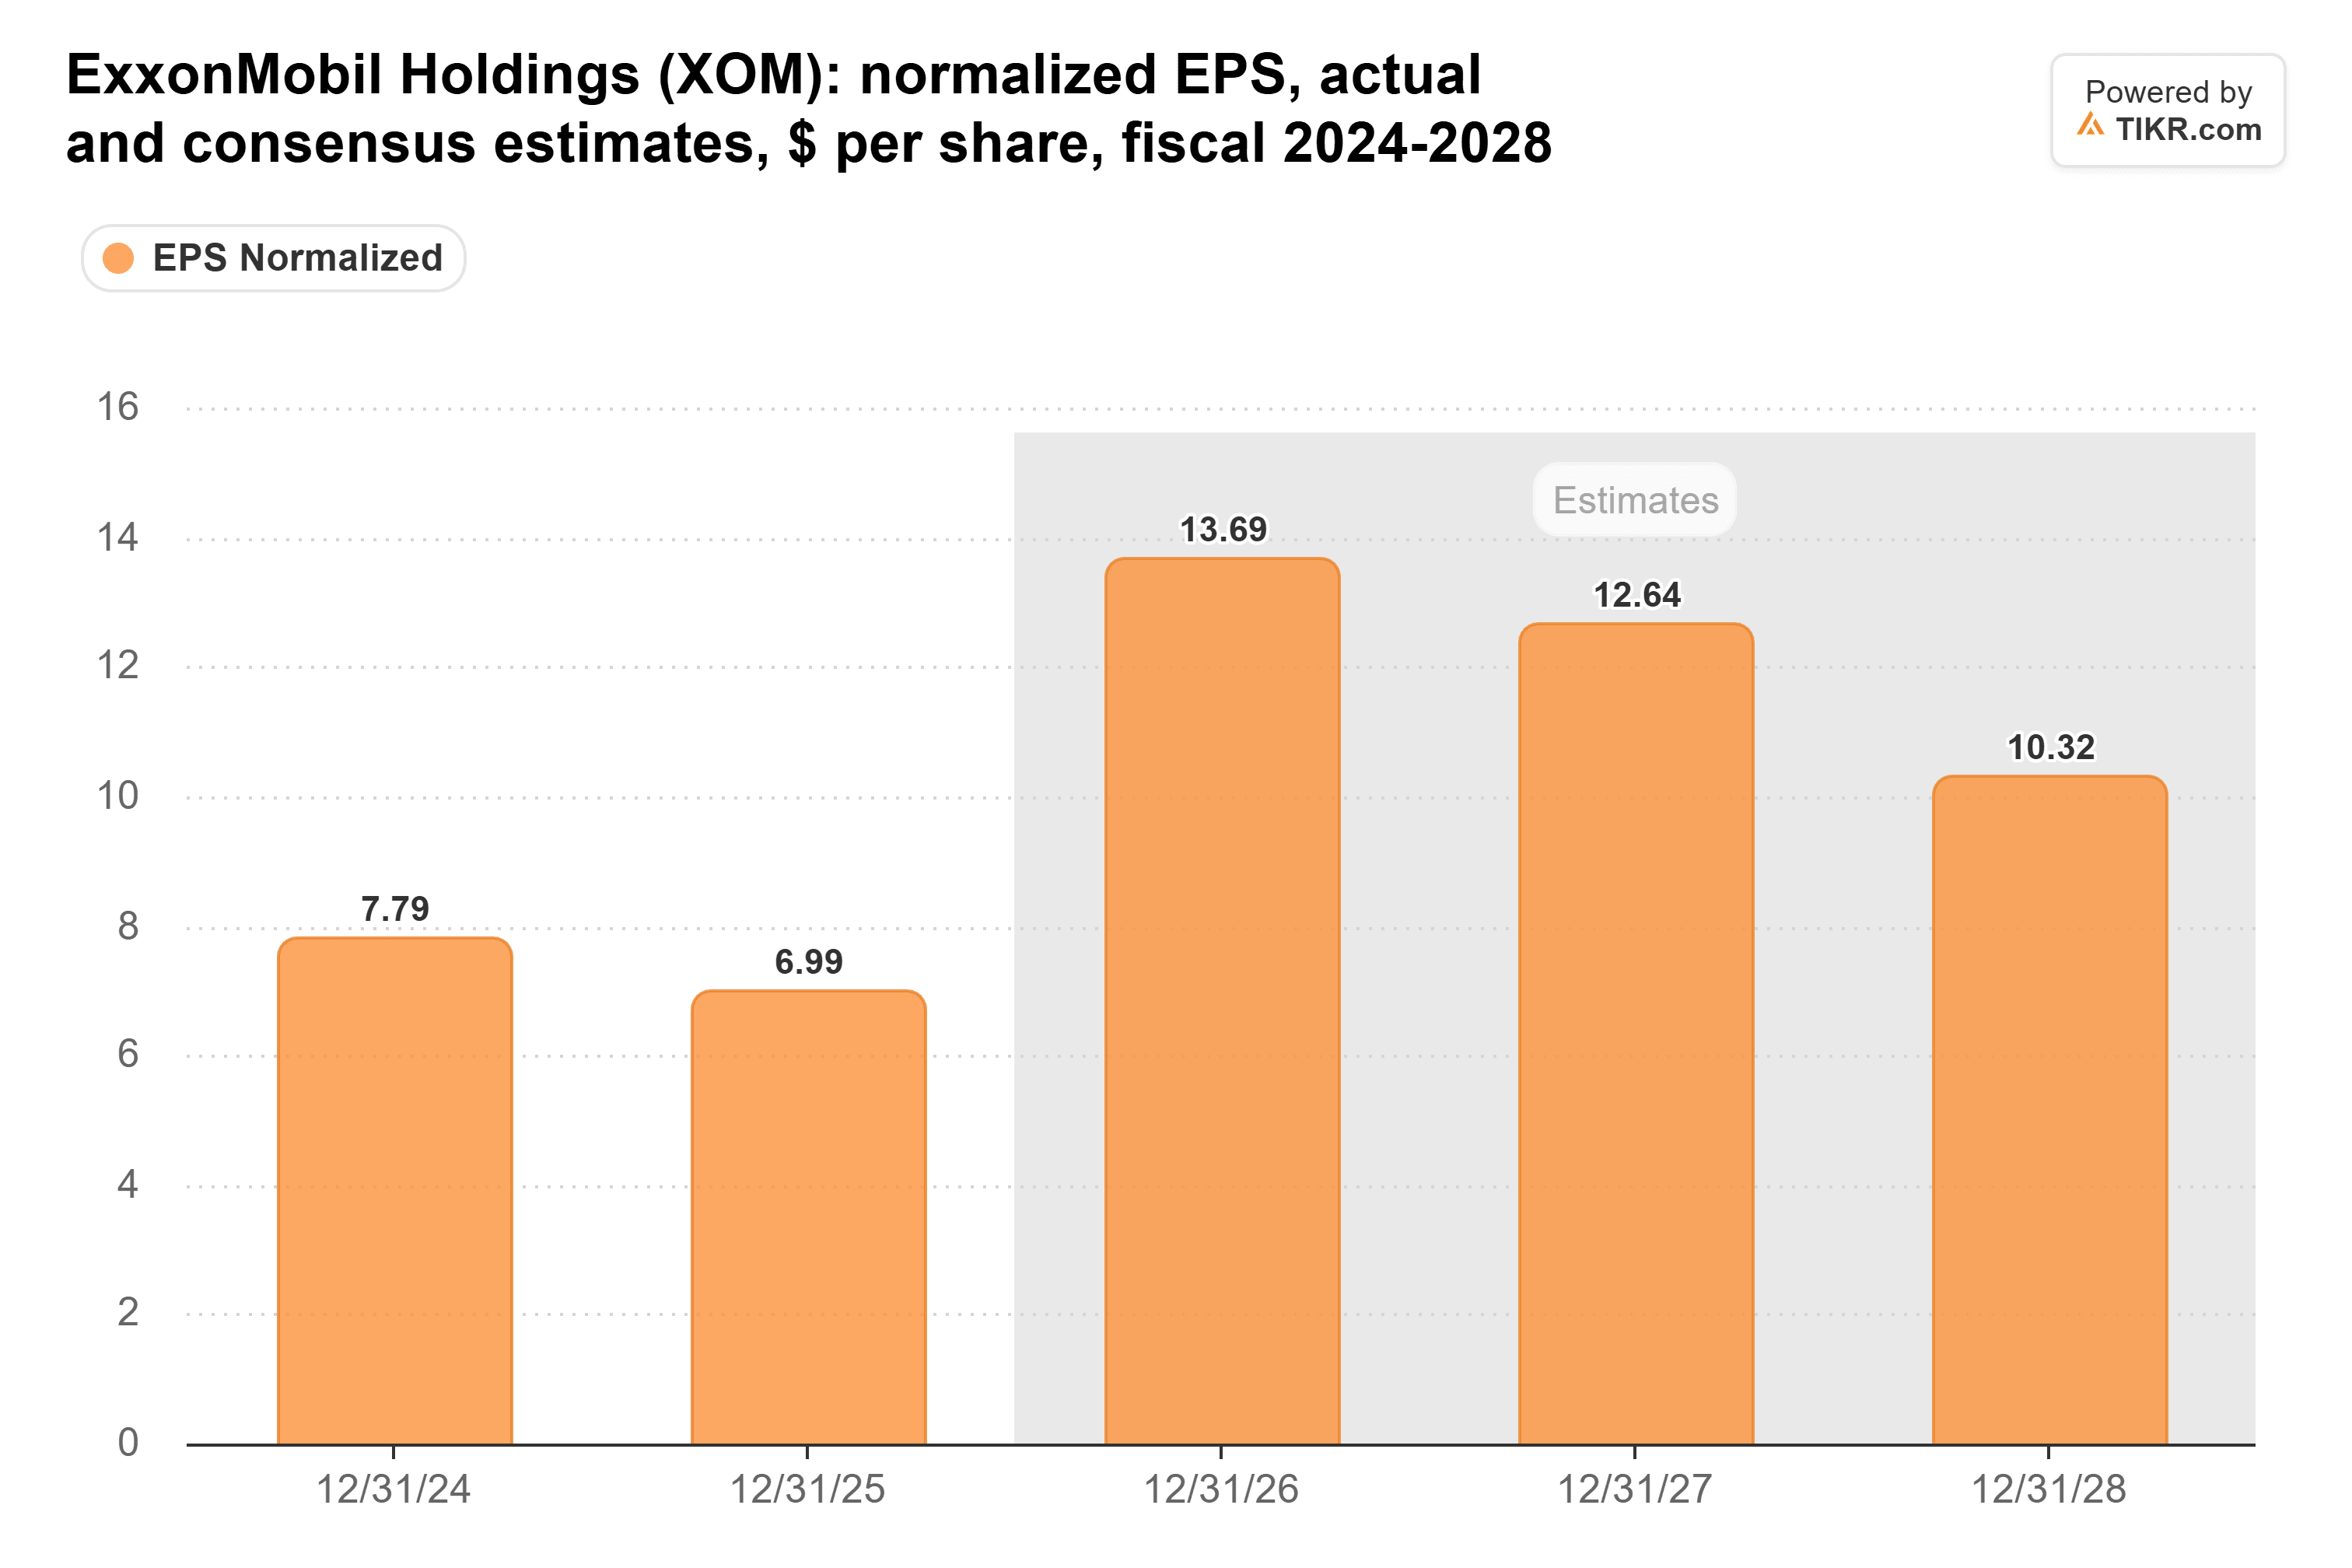
With Brent down from near $117 at the end of October to almost $96 on Nov. 12, those estimates have little room to keep rising.
ExxonMobil trades at about 12x forward earnings, a little below its five-year average of 13x:
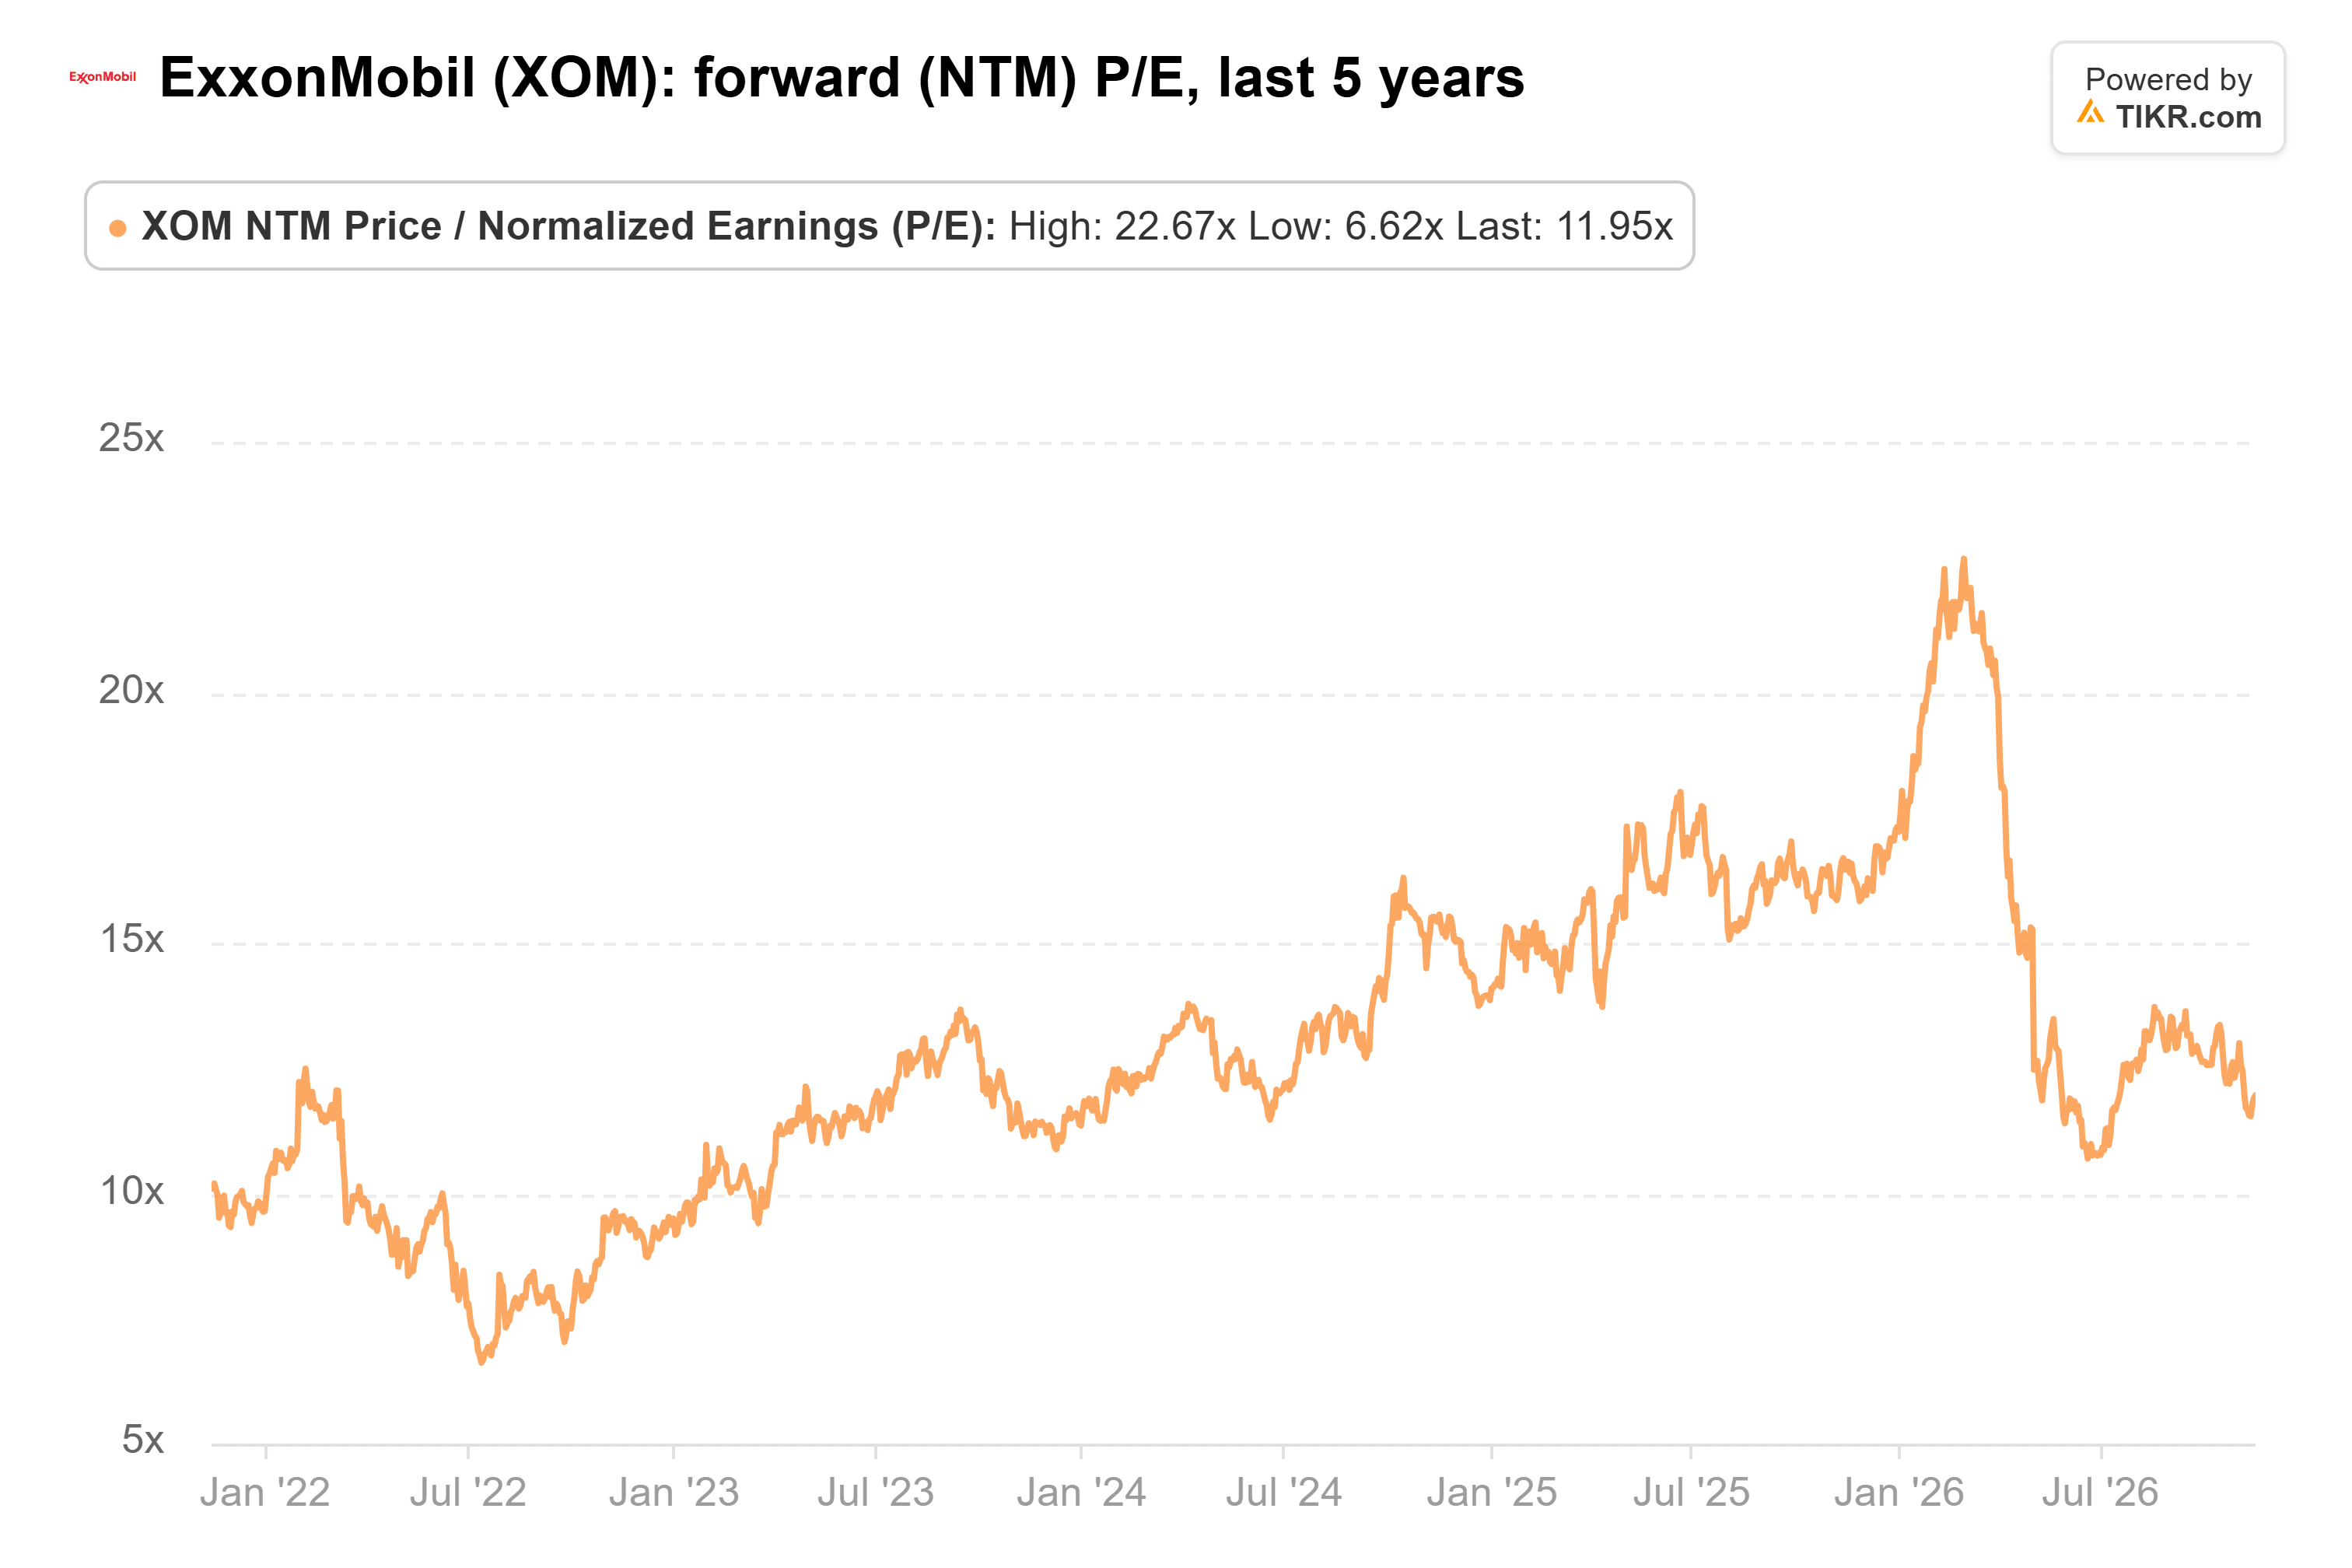
Barclays’ $206 works out to about 14x the next twelve months’ expected earnings, above that average.
Too rich for peak earnings
The biggest risk is one ExxonMobil can’t control: an end to the Iran war would ease the shortages behind this year’s earnings, and analysts would likely cut their estimates. Woods said on the Oct. 30 call that it would likely take “well through next year” for fuel markets to get back closer to normal. But Barclays is asking investors to pay an above-average multiple for earnings that analysts already expect to shrink, which looks too optimistic for a 12-month target. If fourth-quarter results in early 2027 show earnings holding up better than that $10.32 for 2028 implies, Barclays’ case gets a lot stronger.
So what is ExxonMobil stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ExxonMobil could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!




