


Key Takeaways
- Enerflex shares jumped 13% today after it won a contract to build over one gigawatt of natural gas power units for a North American data center.
- The award lifts Enerflex’s behind-the-meter power backlog to over 1.75 gigawatts, with deliveries through 2028, and analysts’ revenue estimates were set before it.
- Enerflex didn’t give the award’s dollar value, and it’s spending about $100 million to expand the Engineered Systems facilities that will build it.
- CIBC upgraded the stock to Outperformer with a $35 target, and the third-quarter report is the next chance to see what the backlog is worth in dollars.
Enerflex (EFXT) shares are up 13% today after the company landed an order for over one gigawatt of natural gas power for a single data center.
Before the open, Enerflex said it will build behind-the-meter, gas-fired power units for “a large-scale North American data center development.” The new award alone is more than twice the roughly 450 megawatts it announced on Oct. 1. Add those and other awards together, and its behind-the-meter power backlog now tops 1.75 gigawatts, with deliveries through 2028.
CEO Paul Mahoney pinned the demand on AI and pointed to the company’s “success securing over 1.75 gigawatts of backlog” (news release).
At 10 a.m., CIBC upgraded the stock to Outperformer from Neutral, with a $35 target.
Gigawatts on a $3.5 billion business
Enerflex’s Engineered Systems backlog stood at $1.5 billion at the end of June, up from $1.1 billion at the end of 2025, and most of the 1.75 gigawatts announced today was booked after that point. The company didn’t put a dollar value on the new award or name the customer.
It’s landing on a business whose revenue has gone sideways, at $3.52 billion in 2025, though analysts see $4.37 billion by 2028…
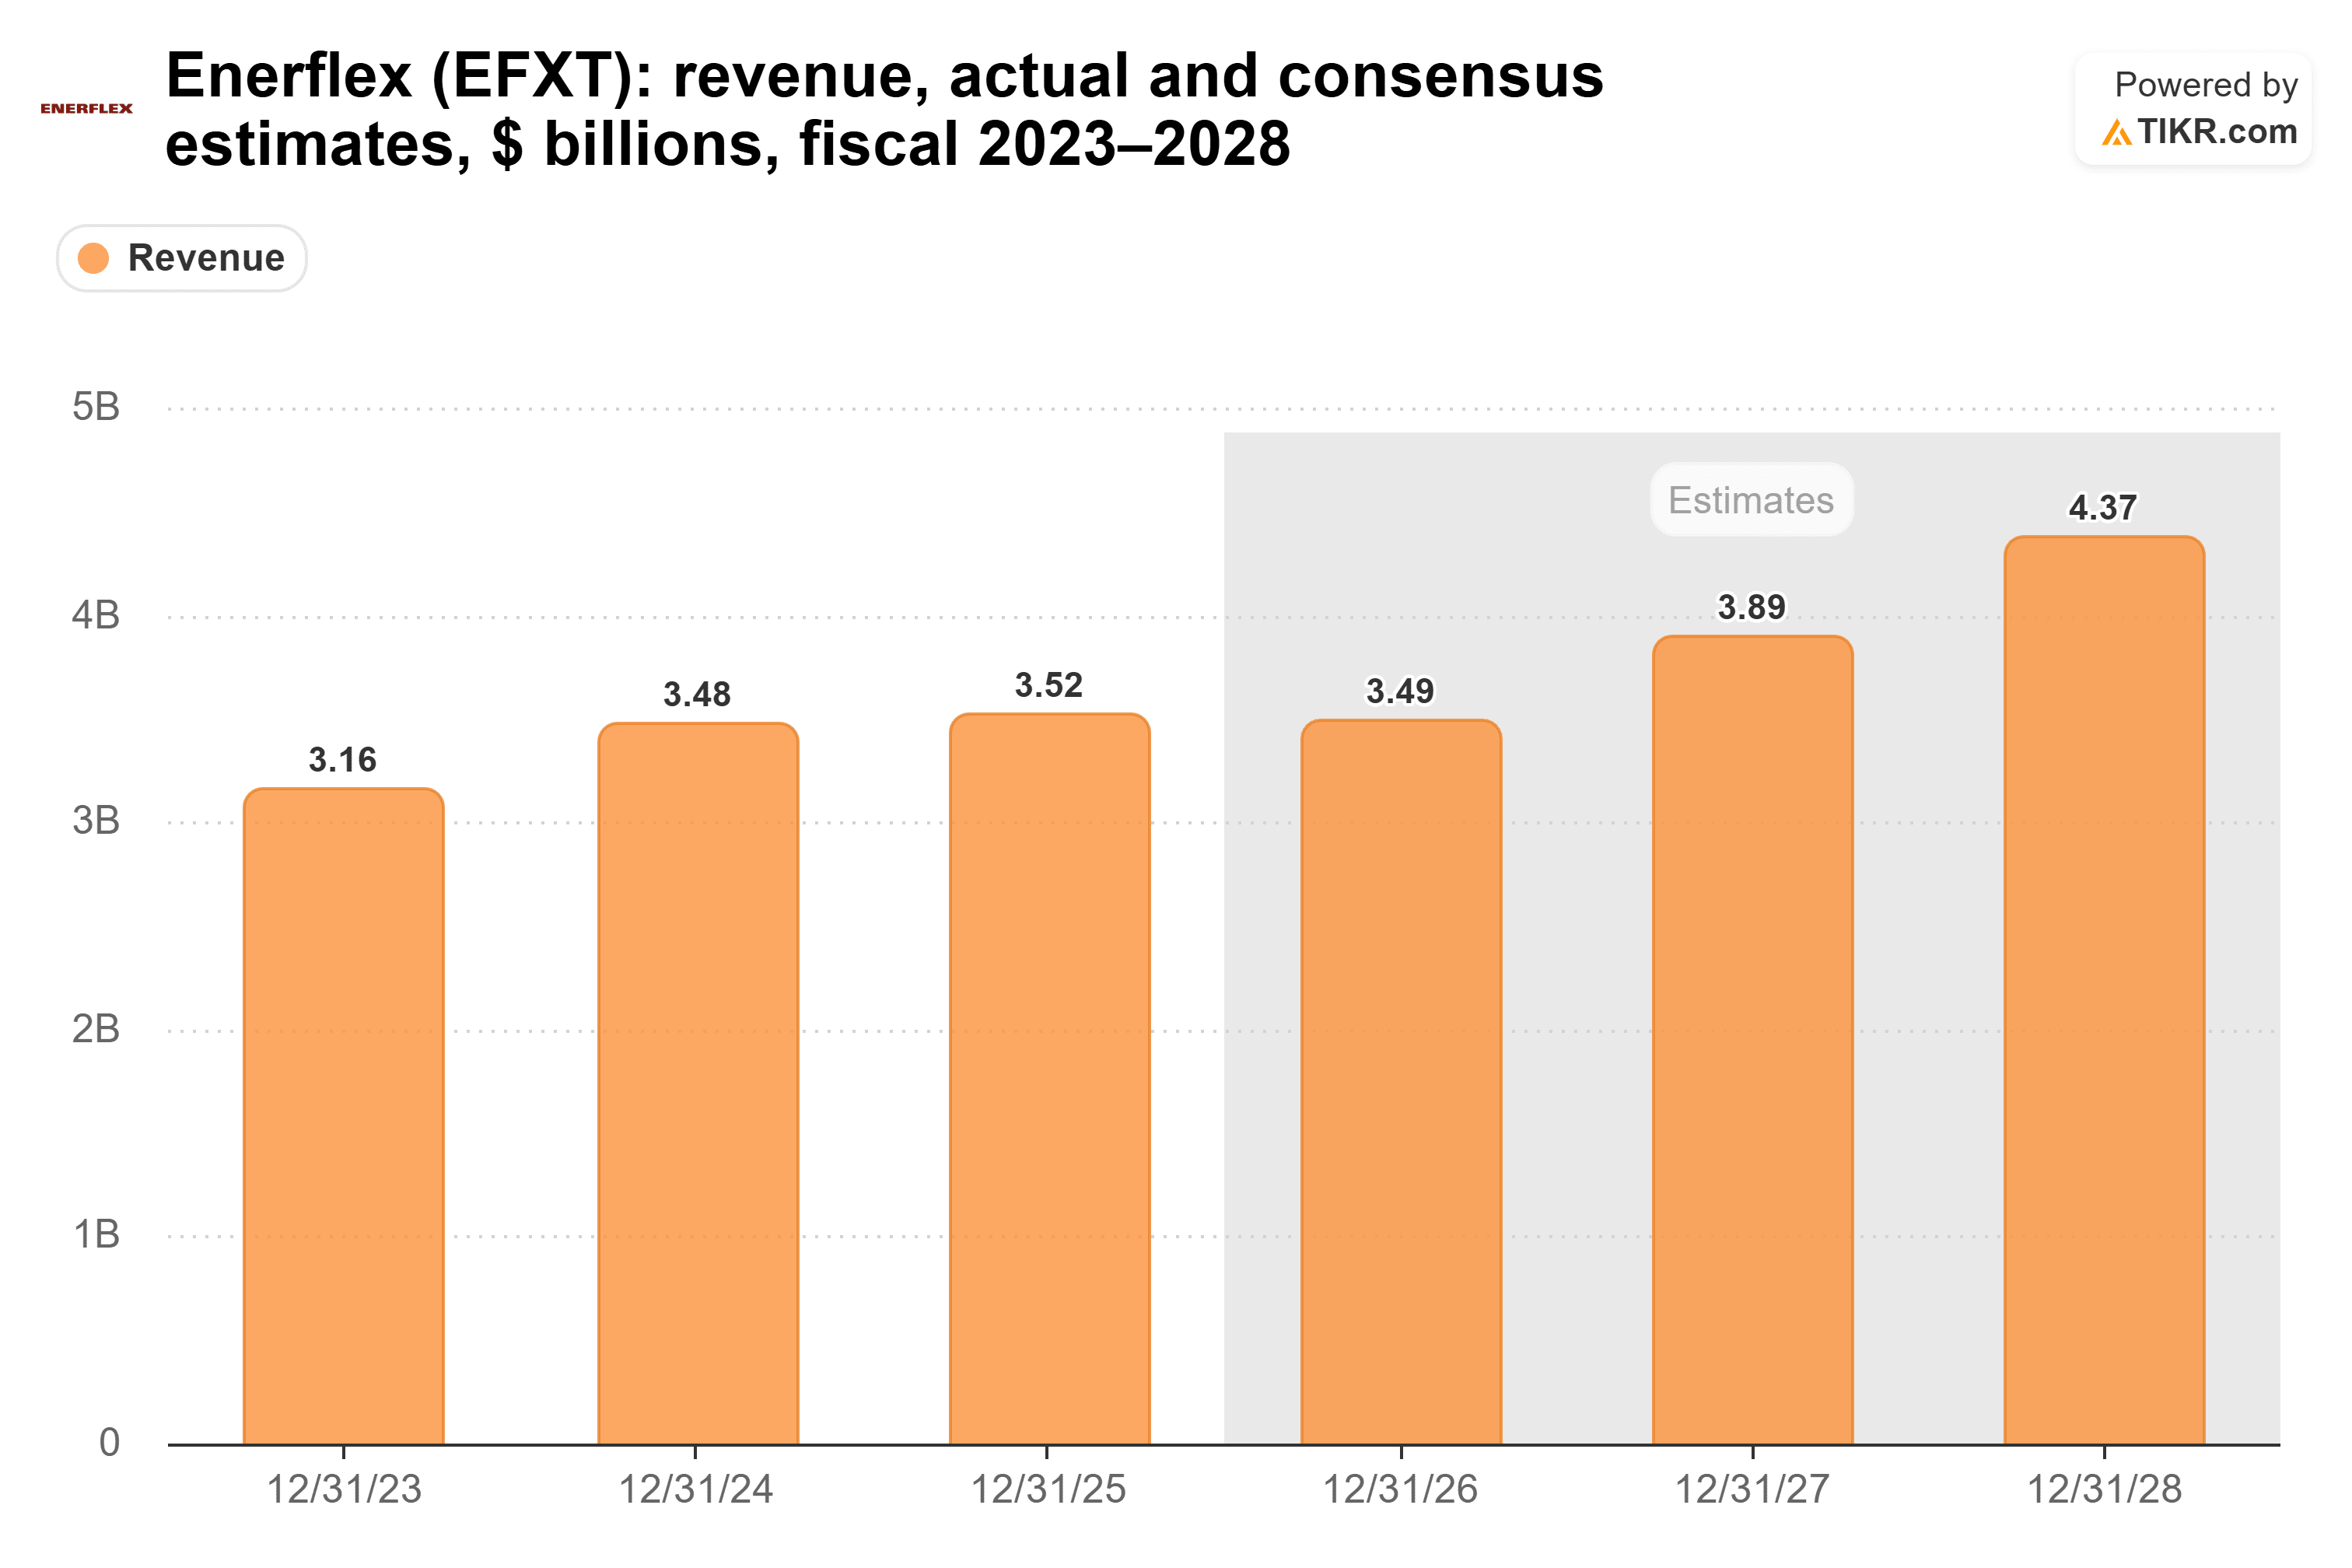
Those estimates date to Oct. 9, before today’s award. With deliveries running through 2028, I’d expect the 2027 and 2028 numbers to move up.
Now Enerflex has to build it
To build it all in its North American plants, Enerflex has authorized about $100 million to expand its Engineered Systems facilities, and only $15 million of it is in this year’s capital spending guidance. Management expects that to significantly increase the business’s revenue capacity.
That’s a lot of new work riding on a schedule that runs through 2028, so a delay or a cost overrun on a gigawatt-scale order would hit hard.
The stock still isn’t stretched
Enerflex already traded at 14x forward earnings at the last close, well above its five-year average of 9.7x…
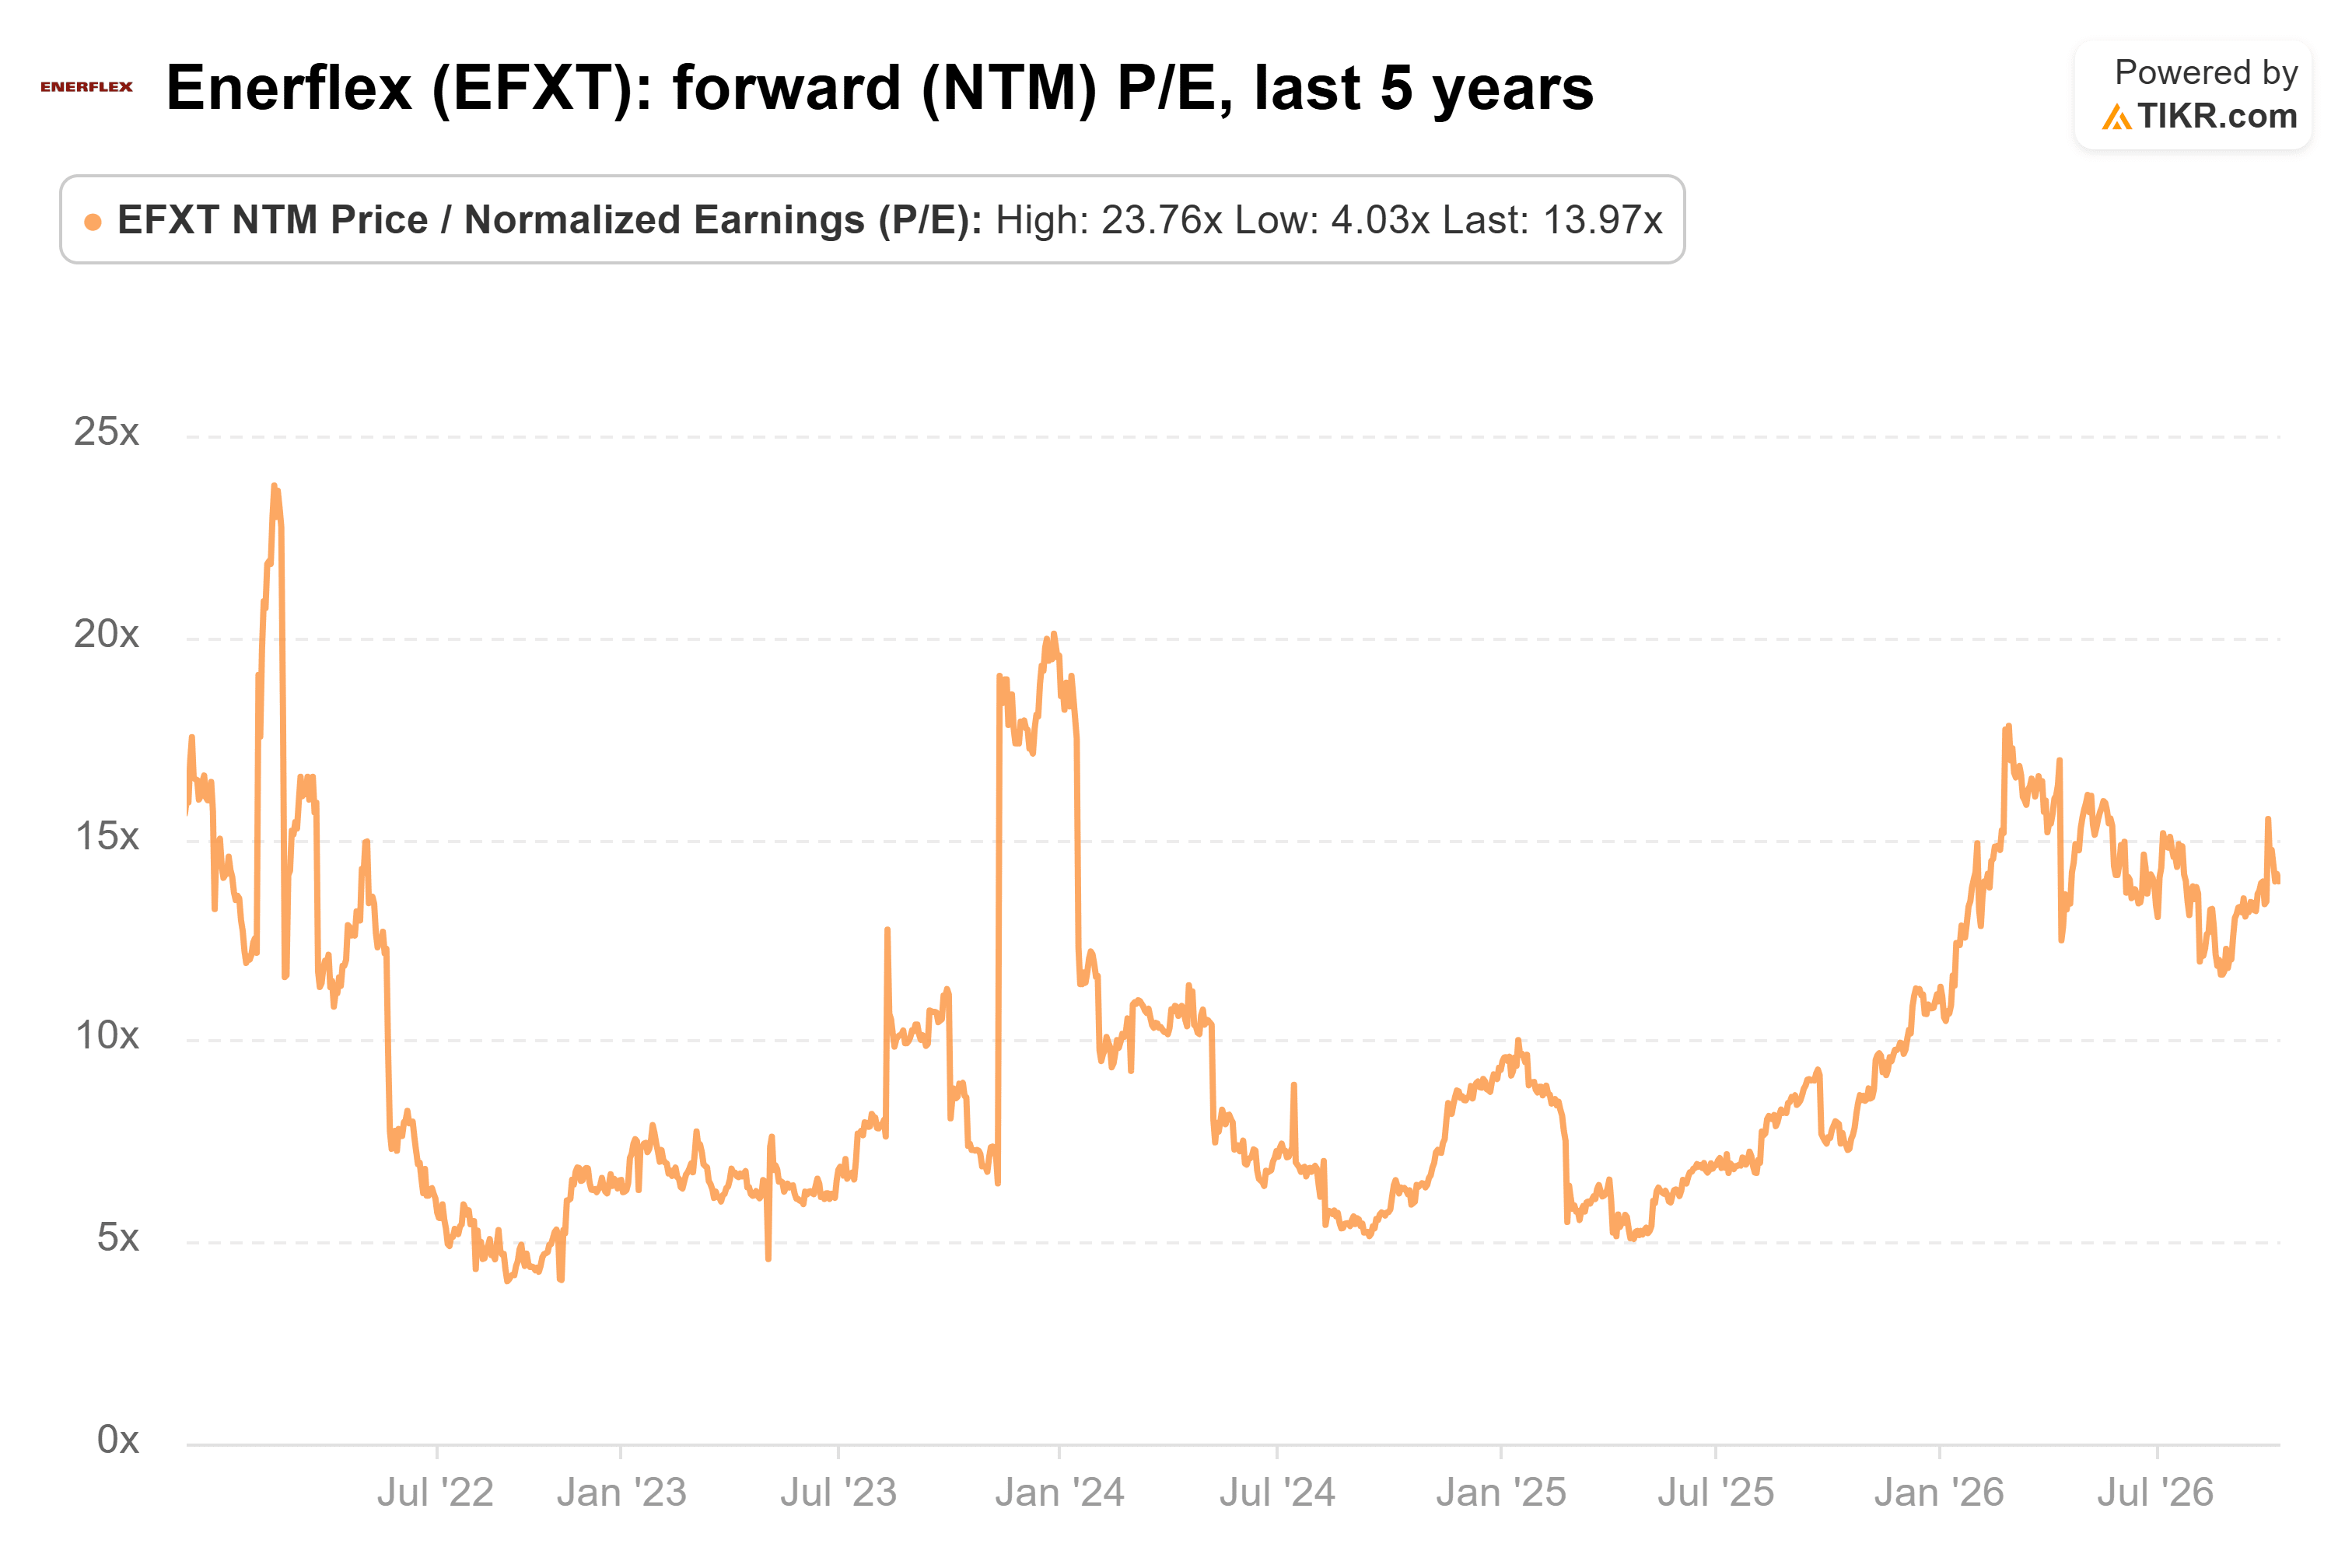
At this morning’s price, it’s closer to 16x, still well below its 23.8x peak in January 2022. And CIBC’s $35 target sits comfortably above even today’s price.
I could see the market’s view of Enerflex shifting further from here. For years it has priced the company as a gas equipment maker, and a gigawatt-scale order is a strong signal that the business is something more than that. Analysts also haven’t folded the award into their estimates yet, which leaves room for the numbers to catch up.
Of course, we still don’t know what any of this is worth in dollars. Enerflex’s third-quarter report is the first chance to find out.
So what is Enerflex stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Enerflex could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


