Key Takeaways
- Eaton stock is down 23% in the past month. Meta Platforms’ spending plans and the Democrats’ midterm sweep hit AI power-equipment stocks across the board, Vertiv and GE Vernova included.
- The selloff erased the gain from a record third quarter, in which Eaton’s Electrical backlog grew 46% and it raised its 2026 organic growth outlook to 13-15%.
- RBC Capital raised its target to $539 after the report, but to get there investors would have to pay a higher forward P/E than at any point in five years.
- At 22x forward earnings, below its 25x five-year average, Eaton looks like a buy, and its fourth-quarter report in February will show whether data-center orders are holding up.
Eaton (ETN) stock is down 23% in the month to Nov. 6, erasing the gain from its best quarter ever.
It went down with the rest of the AI power trade. Vertiv (VRT) lost 28% and GE Vernova (GEV) 25% over the same stretch. They were hit first by spending plans from Meta Platforms (META), then by the Democrats’ midterm sweep. Eaton is still up 7% in 2026.
A record quarter, and a higher outlook
Eaton reported before the open on Nov. 3, Election Day, and set records almost across the board:
- Sales rose 28% to $8.9 billion.
- Adjusted EPS was $3.68, against roughly $3.55 expected.
- Electrical backlog grew 46% from a year earlier, with rolling 12-month organic orders up 39% in Electrical Americas and 51% in Electrical Global.
- Management raised its 2026 organic growth outlook to 13-15%, with adjusted EPS of $13.70-$13.80.
Analysts expect earnings to keep climbing, to $16.28 a share in 2027 from $12.07 in 2025:
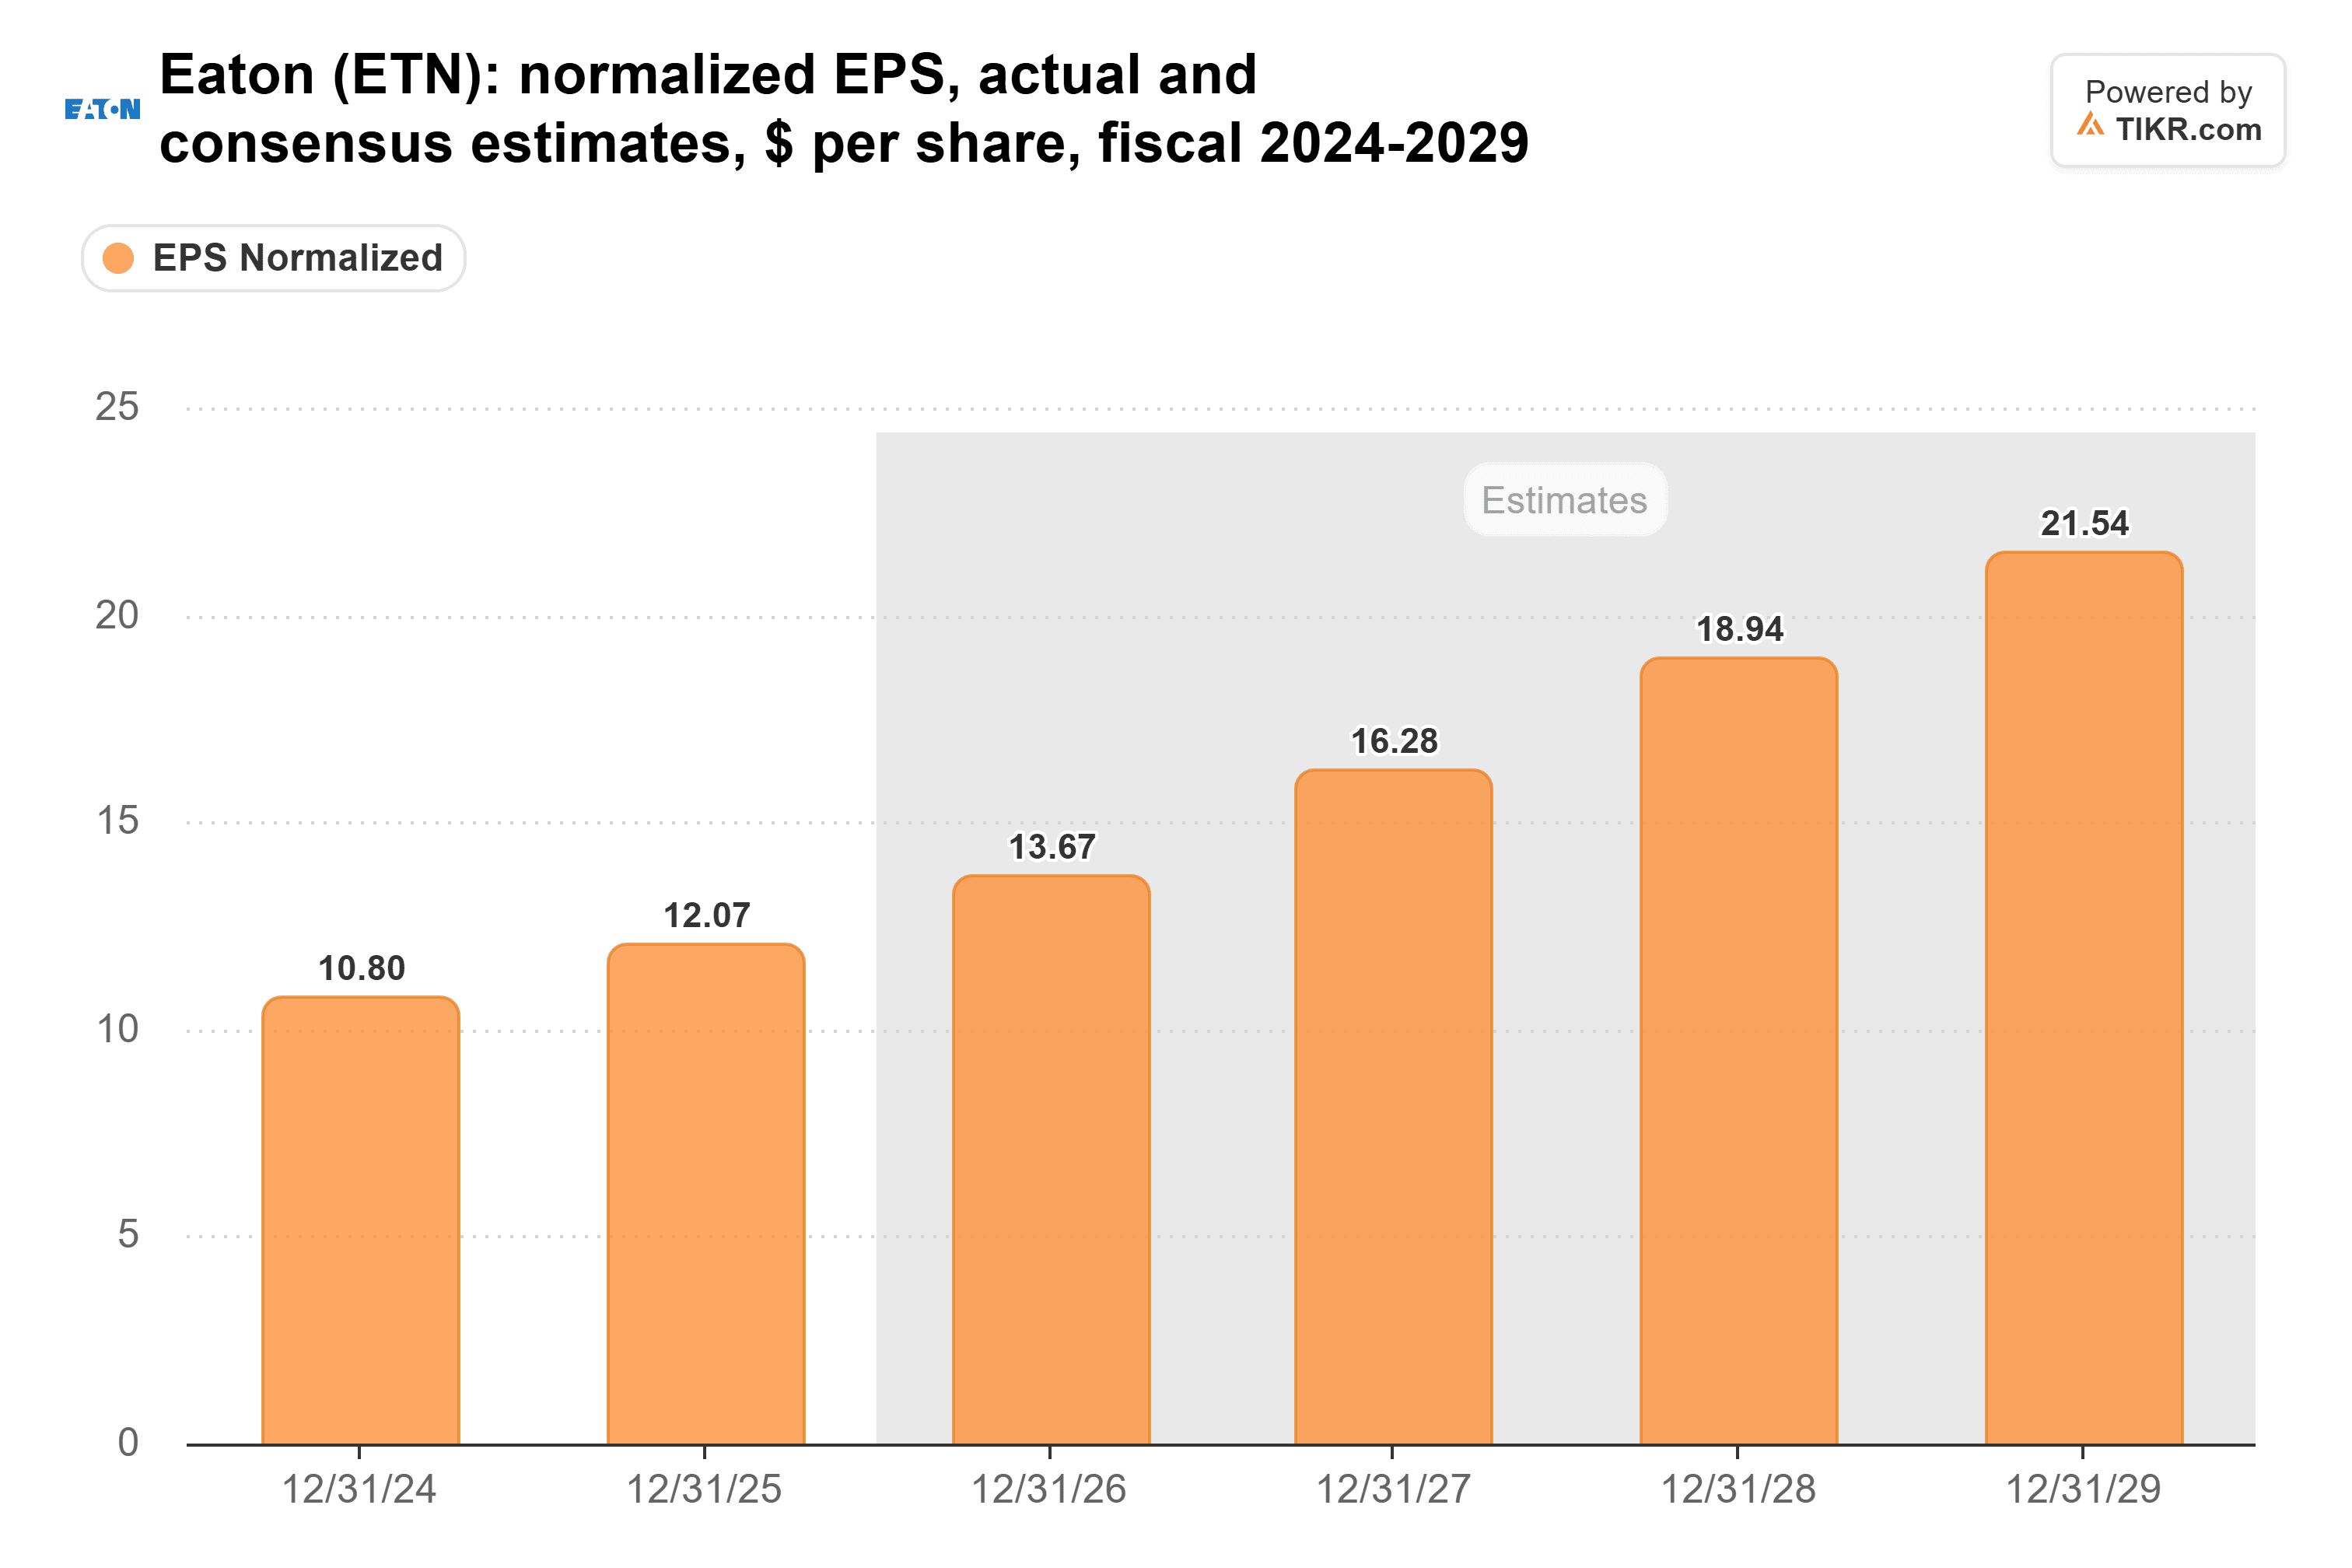
Even the low end of the new guide tops the $13.67 consensus for 2026, so nothing here points to estimate cuts. The stock jumped 7% that day, then lost almost 10% the next.
TIKR tracks 28 analysts on Eaton. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Eaton, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Eaton’s Analyst Ratings
Meta and the midterms sank the whole group
The trouble started with Meta’s third-quarter report after the close on Oct. 21. Its free cash flow turned negative, and it raised the low end of its 2026 capex range, to $135-145 billion. That means more data-center spending, but investors worried how hyperscalers will pay for it. Meta is down 17% over the month, and Eaton fell 6% on Oct. 22 with the rest of the group.
Then Democrats won both chambers of Congress, and Texas’ governor-elect, Gina Hinojosa, has pledged to halt new data-center approvals until lawmakers pass new rules. That revived fears that US data-center construction could slow. Eaton fell 10% on Nov. 4, and the next day an AI-led market rout took the S&P 500 down more than 4% and Eaton down another 7%.
Vertiv and GE Vernova fell harder, though their quarters look a lot like Eaton’s. On Oct. 28, Vertiv reported third-quarter sales up 61% to $4.31 billion, organic orders that more than doubled and a higher 2026 guide. The same day, GE Vernova reported orders up 96% organically to $29 billion, which took its backlog to $197 billion.
The market is pricing in a slowdown none of the three has reported yet. Neither the new Congress nor Texas’ new governor takes office until January, and Eaton’s Electrical book-to-bill held at 1.2 on a rolling 12-month basis.
Does $539 add up?
RBC Capital raised its target to $539 from $526 on Nov. 4 and kept its Outperform rating. That’s 58% above the Nov. 6 close of $341.72.
Eaton now trades at 22x forward earnings, below its 25x five-year average and well off the 33x peak it hit in April:
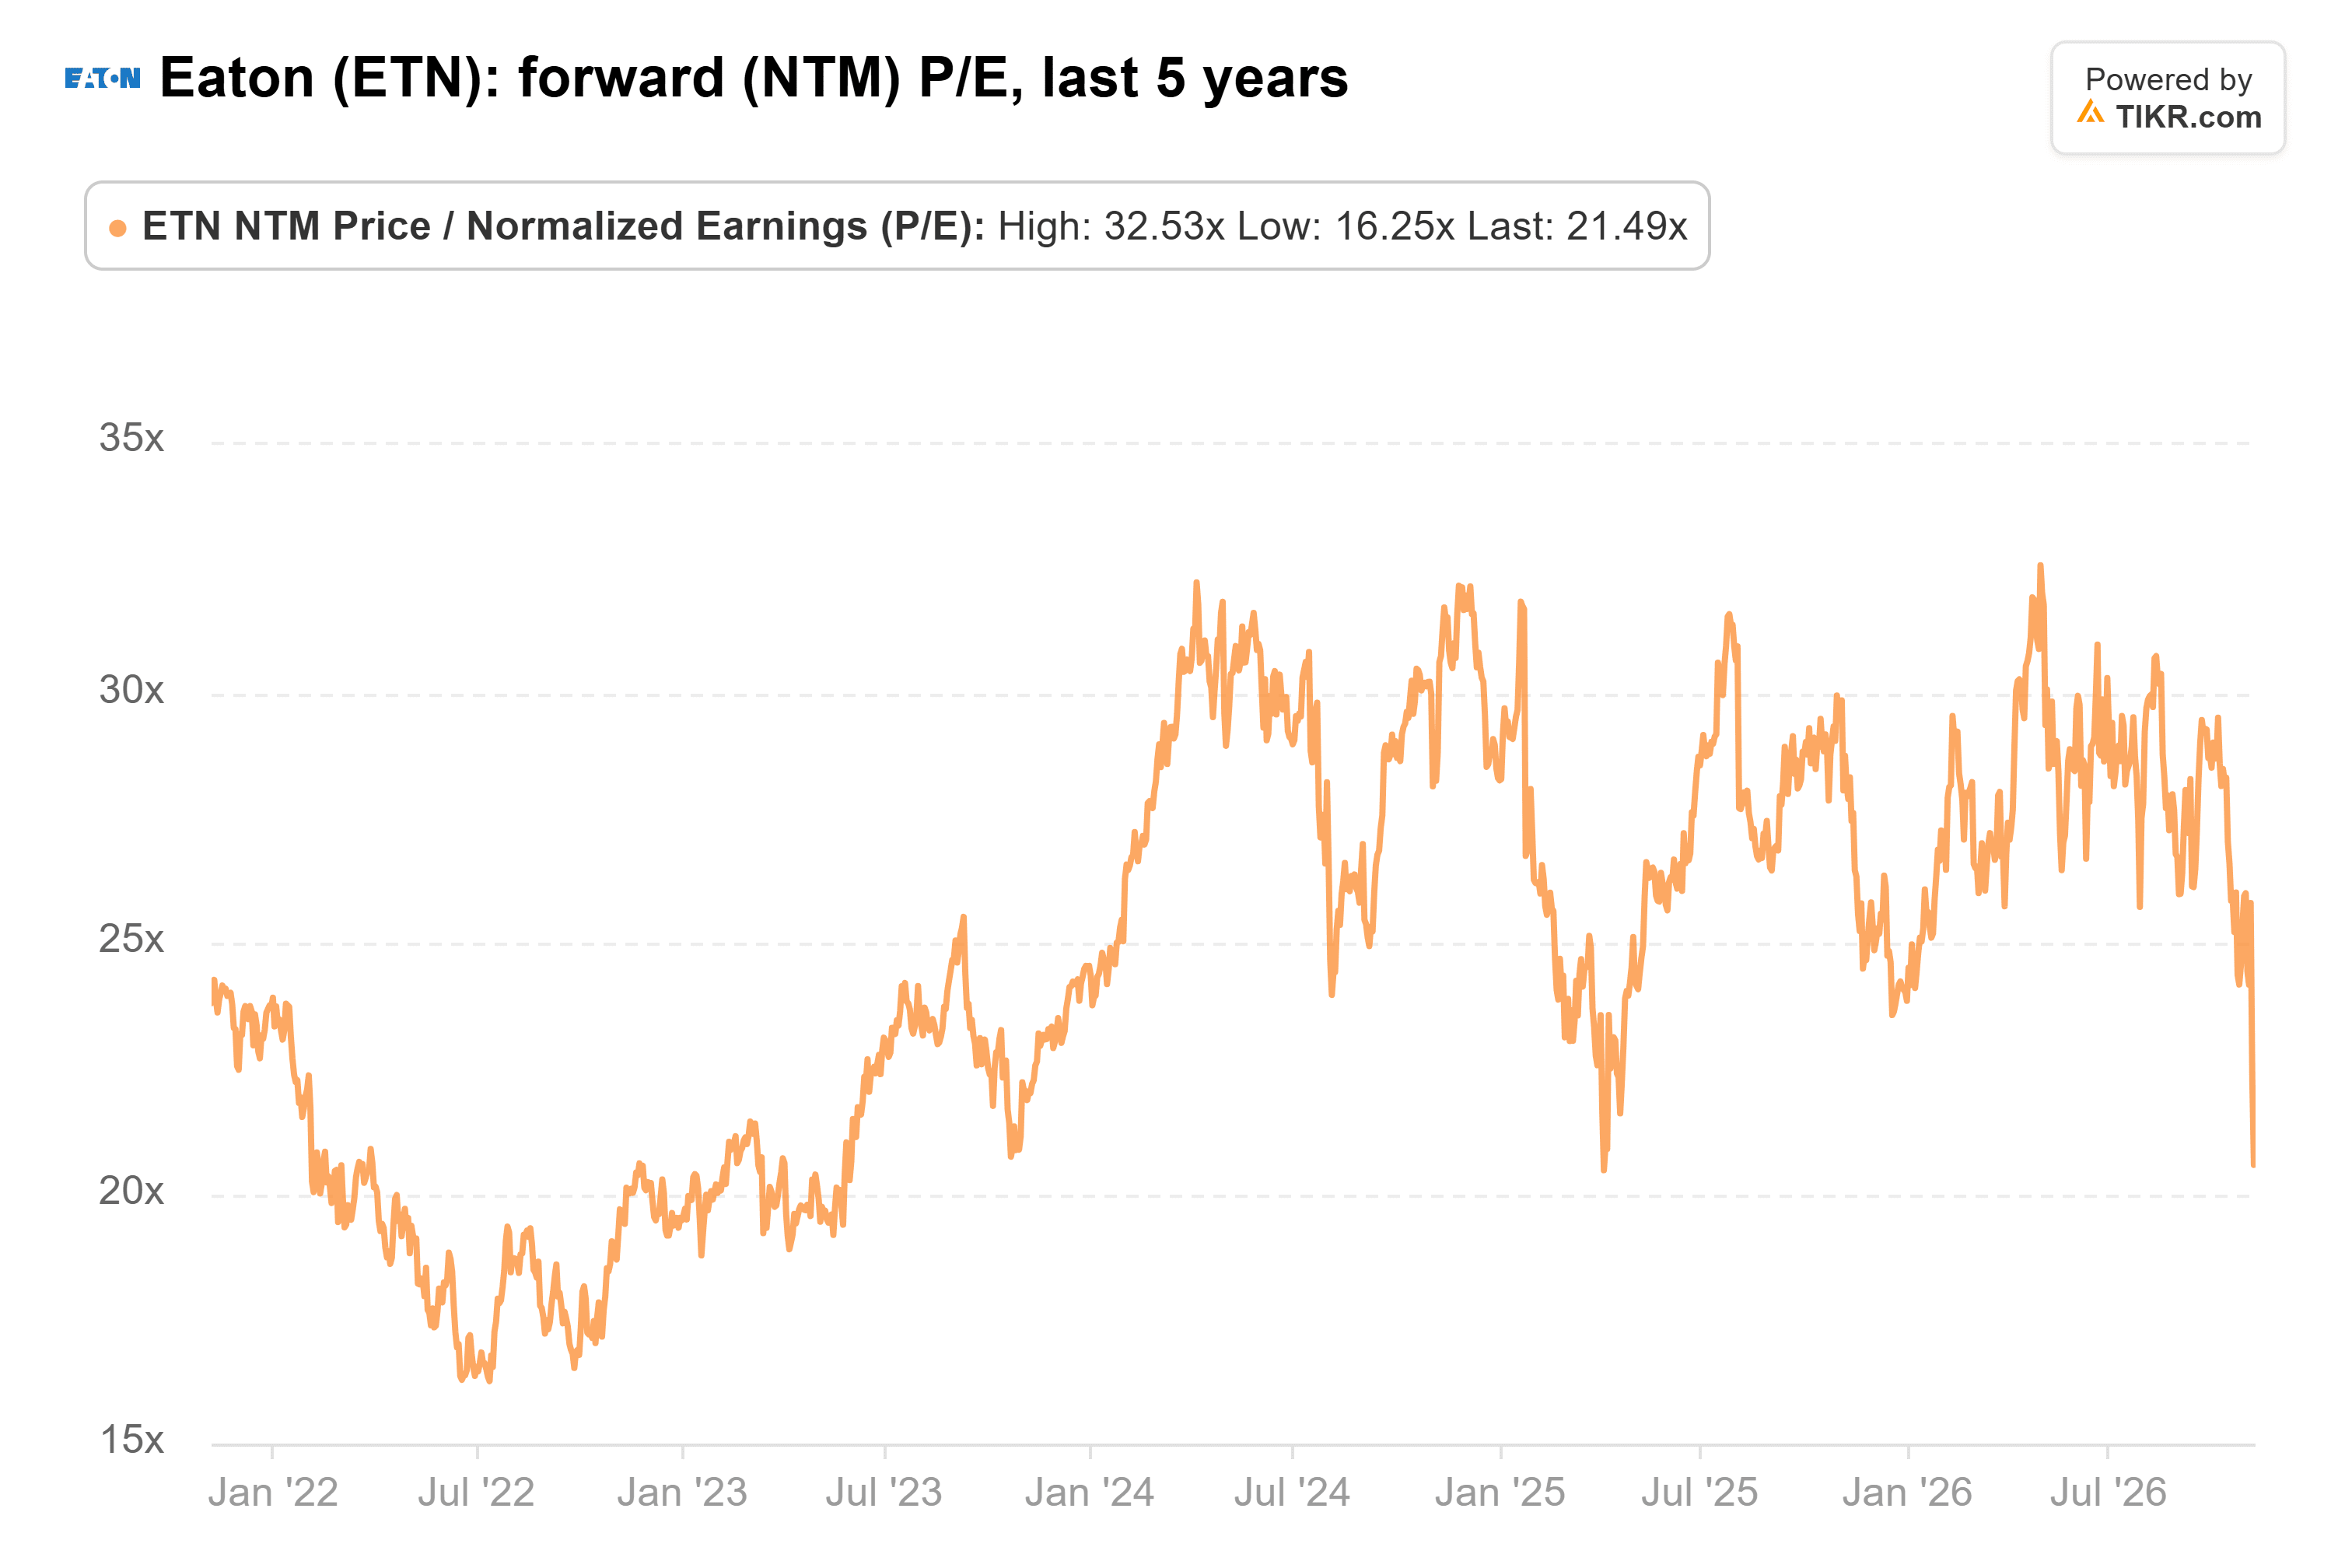
A return to that average alone would be worth about 15%. To get to RBC’s $539 on today’s estimates, though, investors would have to pay about 34x forward earnings, more than at any point in five years. The Street’s average target has barely moved through the selloff and stood at $484 on Nov. 4:
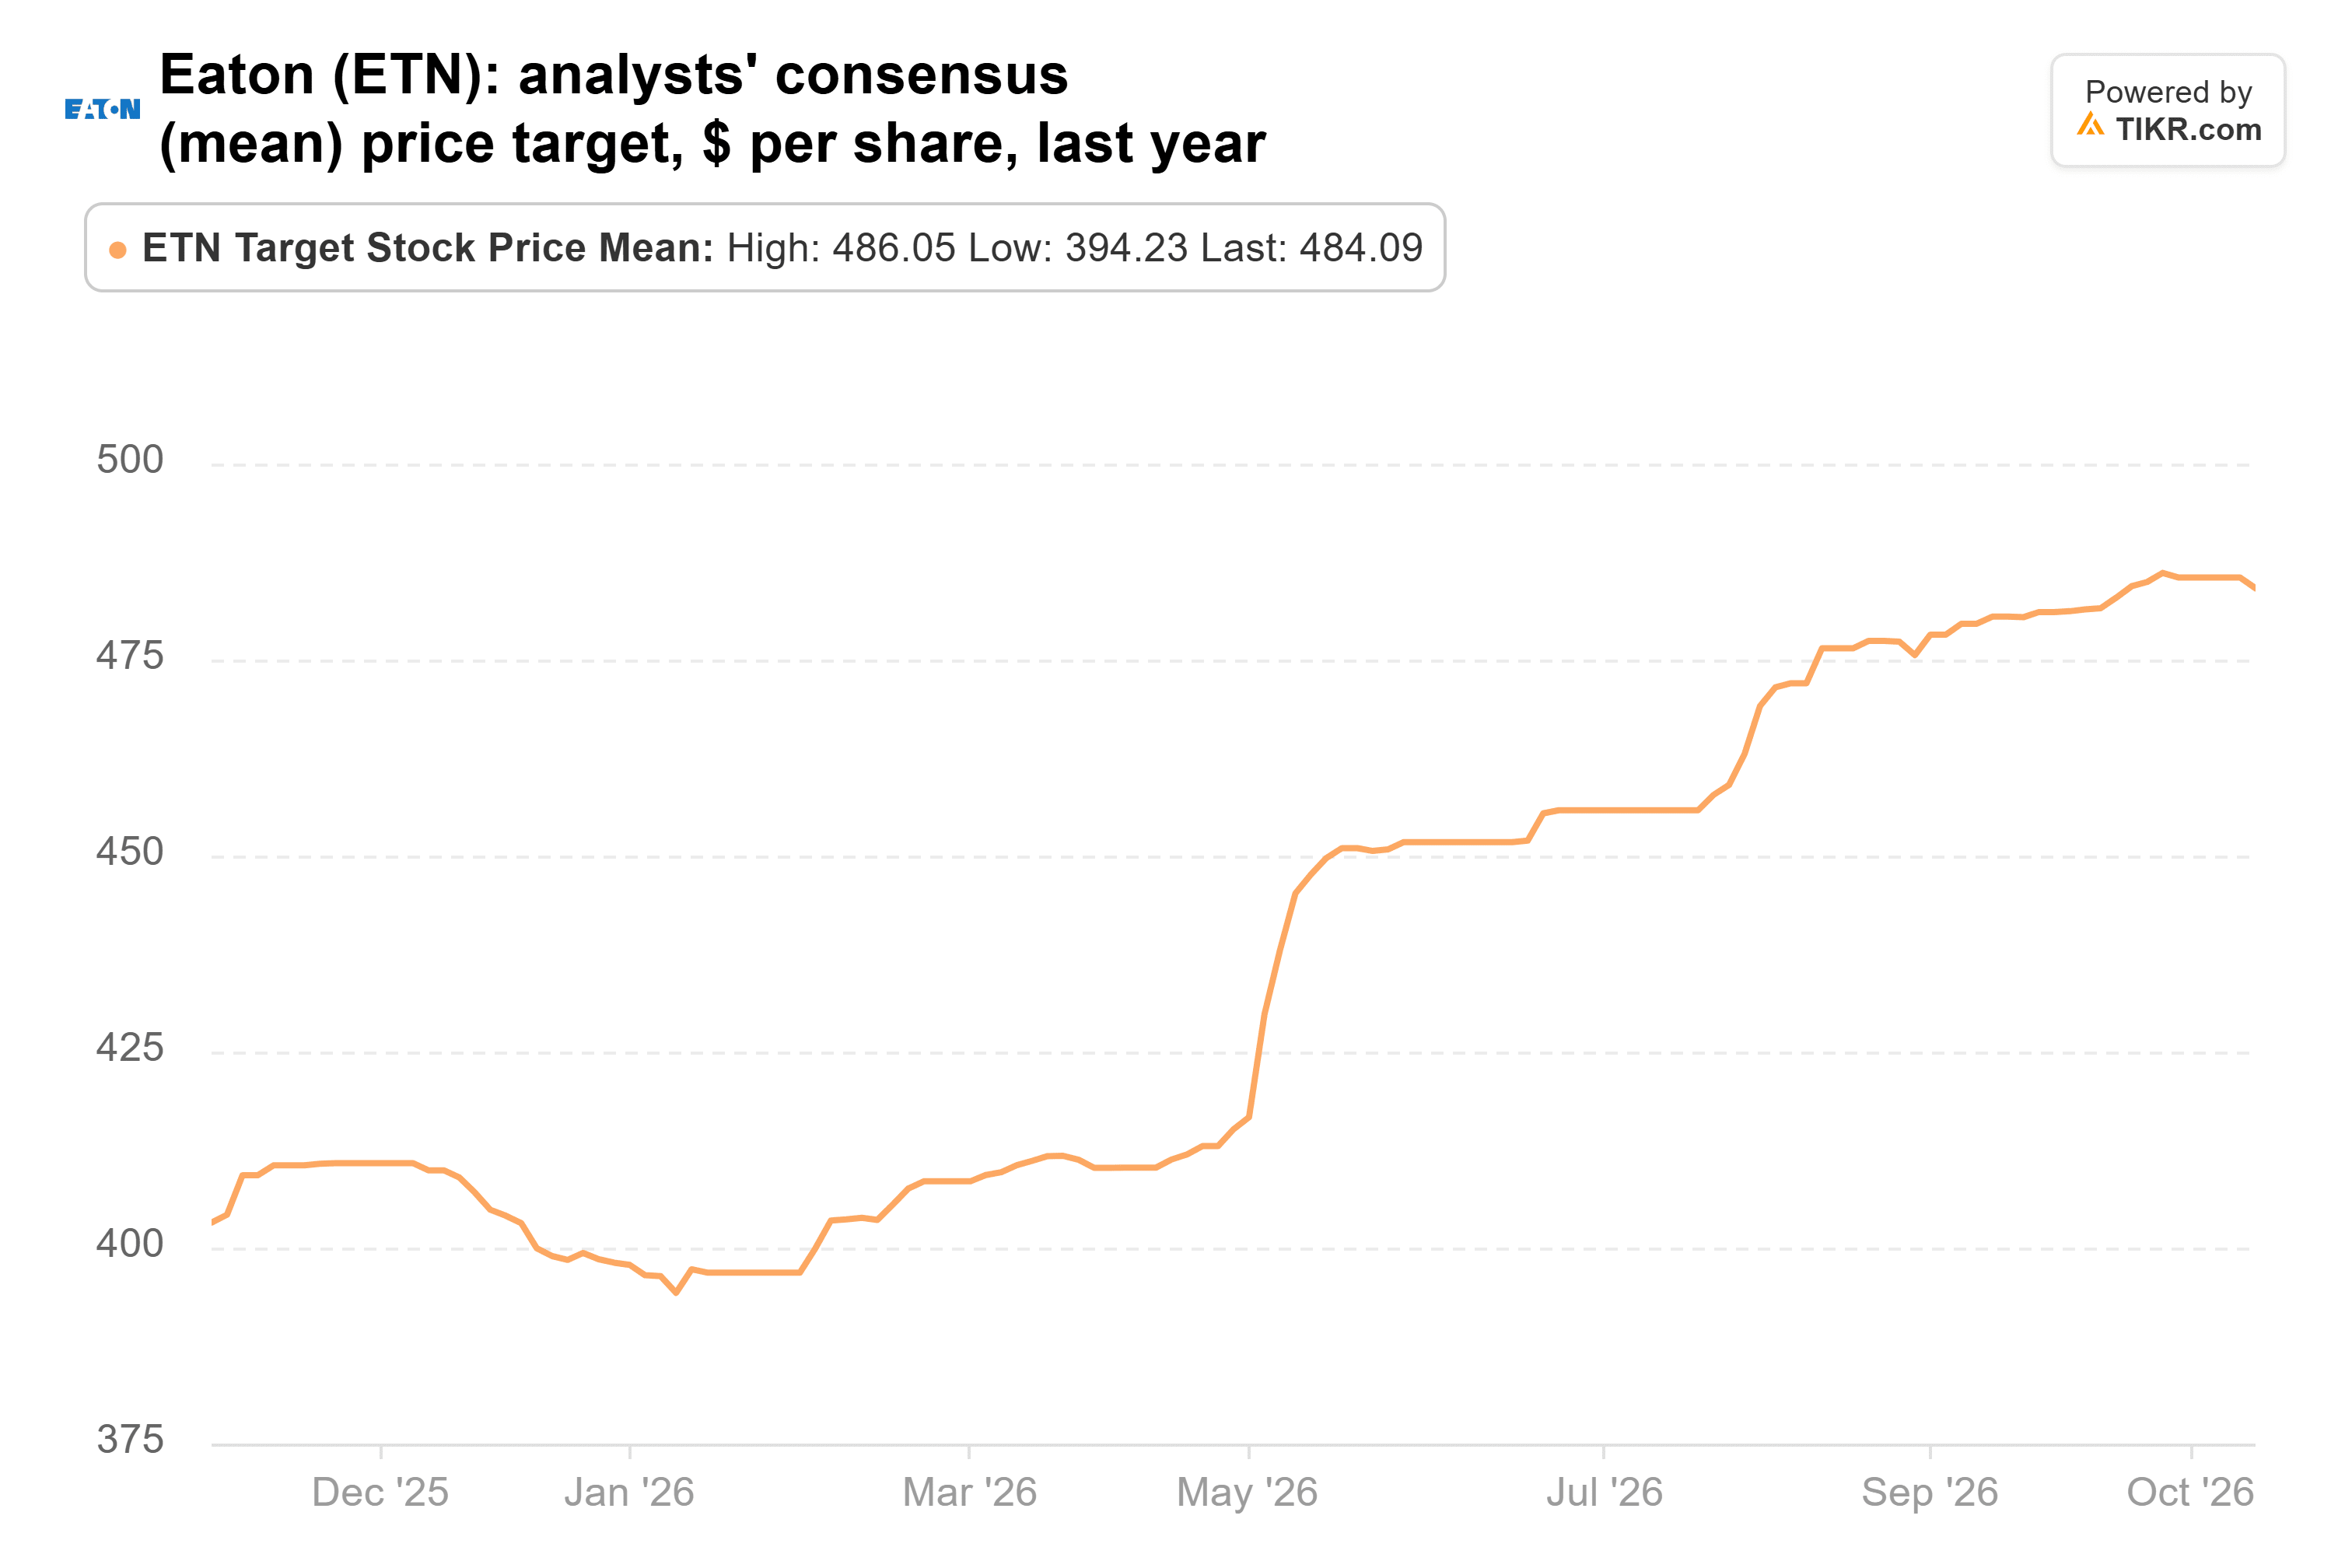
That’s 42% above the Nov. 6 close, and still works out to about 30x forward earnings.
The risk is that Washington or Texas does slow data-center construction, and Eaton’s orders start to show it next year. Still, Eaton looks like a buy: its orders are growing, and it trades below its usual multiple. Just don’t count on $539 within a year. February’s fourth-quarter report will show whether data-center orders are holding up.
So what is Eaton stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Eaton could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!