Key Takeaways
- DraftKings reports third-quarter results after the close on Nov. 5. The stock has bounced since late October but is still more than a third below its January high, as Predictions spending cuts into profit.
- To reach the low end of its 2026 adjusted EBITDA guidance, DraftKings needs $418 million in the second half, nearly double what it earned in the second half of 2025.
- Flutter’s FanDuel US profit nearly vanished last quarter, while BetMGM more than doubled its adjusted EBITDA on 7% revenue growth.
- Until DraftKings holds its guidance and shows Predictions spending can come down in 2027, the drop from January looks like a fair read on costs.
DraftKings (DKNG) reports third-quarter results after the close on Thursday, Nov. 5, and the stock has run up into it. It rose 5% to $23.11 on Nov. 4 and is about 11% above its Oct. 30 close. It’s still more than a third below its January high, because Predictions spending has cut into profit. On Nov. 2, Needham argued the selloff went too far. Now DraftKings has to show the profits to back that up.
The rivals that reported first send mixed signals. Flutter Entertainment (FLUT) said FanDuel’s US profit nearly vanished in the third quarter. MGM Resorts International (**MGM**) grew its share of BetMGM’s profit. And Robinhood Markets (HOOD) grew its event-contract revenue more than sixfold, which shows how much money is chasing prediction markets.
DraftKings Needs a Big Second Half
DraftKings guides to 2026 adjusted EBITDA of $700 million to $900 million, a range that already includes $200 million to $300 million of Predictions spending. The company kept that range in August. It earned $282.5 million in the first half, so it needs $418 million in the second half to reach the low end. That’s nearly double the $217 million it earned in the second half of 2025.
Some analysts think Predictions will cost more than planned. Guggenheim now assumes about $400 million of net Predictions investment this year, above the company’s range.
Analysts still expect earnings to grow. Normalized EPS of $0.85 for 2026 would be 29% above 2025’s $0.66, and the Street sees it doubling again in 2027:
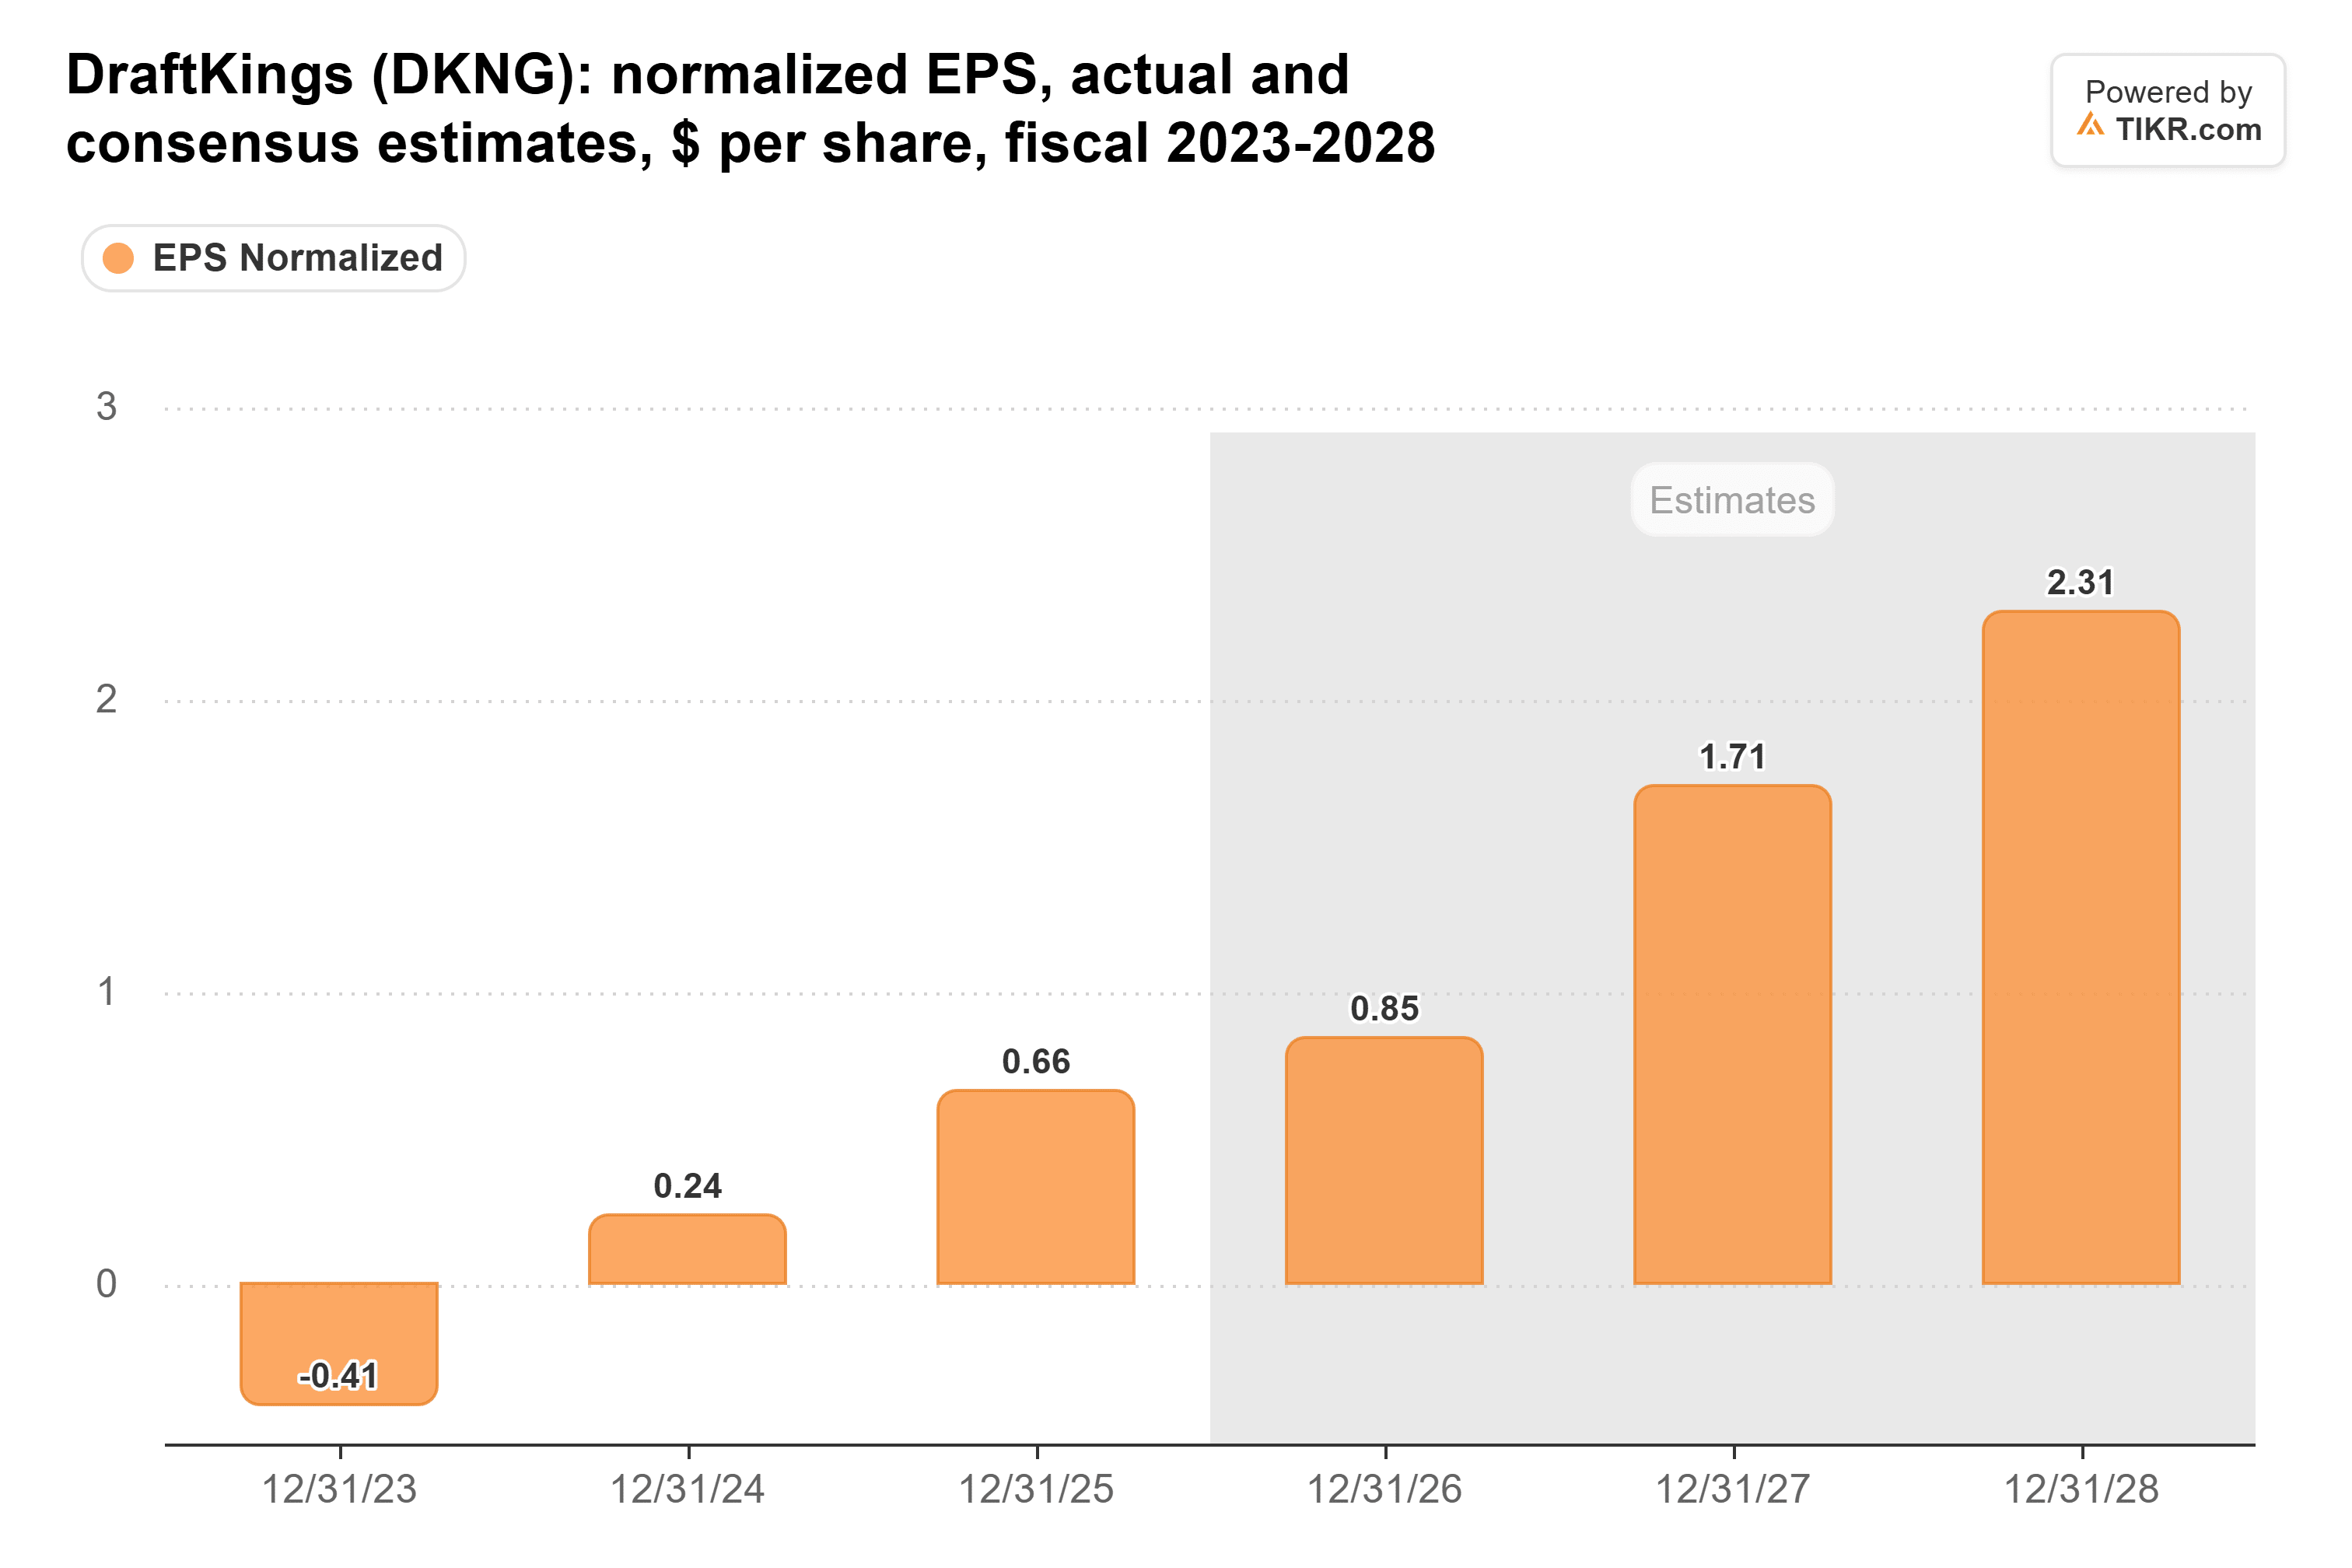
That $0.85 is already down from $1.07 at the end of June, and a guidance cut on Thursday would likely push it lower.
TIKR Tracks 36 Analysts on DraftKings. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on DraftKings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See DraftKings’ Analyst Ratings
Last Year’s Third Quarter Set a Low Bar
On TIKR’s figures, DraftKings’ EBITDA margin has been negative in each of the last three third quarters, including -18.0% last year:

Bad luck hurt last year’s number. Management said customer-friendly results cut revenue by more than $300 million across September and October 2025. The Sportsbook net revenue margin was 5.2% in the third quarter, on $11.4 billion of handle. Anything above 5.2% is the least this quarter has to show.
The bigger test is whether revenue grows faster than spending. In the second quarter, revenue fell 5% while sales and marketing jumped 38% to $322.5 million. For the third quarter, analysts expect an adjusted EBITDA loss on revenue near $1.37 billion.
DraftKings’ Cash Is Expected to Shrink
DraftKings has had positive free cash flow in each of the last three third quarters, even with negative margins. That’s because its cash moves with the timing of customer deposits and withdrawals:

DraftKings brought in $283 million in last year’s third quarter. Analysts expect $556 million of free cash flow for all of 2026, down from $648 million in 2025. It made $52 million in the first half, so it needs about $505 million in the second half to hit that forecast. That’s nearly $100 million less than the $600 million it brought in during the second half of last year.
FanDuel Just Showed What the Race Costs
Flutter’s quarter tells us the most. FanDuel’s US revenue rose 6% to $1.46 billion, but US adjusted EBITDA fell to $3 million from $51 million a year earlier. Flutter also cut its full-year adjusted EBITDA guidance by $160 million, citing adverse sports results and its Brazil closure.
BetMGM shows the other path. Its adjusted EBITDA rose 112% on a 7% revenue gain in the third quarter. MGM’s share of its operating income rose 13% to $26.7 million. Will DraftKings’ quarter look more like BetMGM’s, or FanDuel’s?
Robinhood shows why DraftKings can’t easily pull back. Its event-contract revenue rose more than sixfold to $173 million in the third quarter, on a record 16.4 billion contracts traded. DraftKings is still far behind in that market. Needham counted Kalshi taking 76% of sports prediction-market volume in the NFL’s opening week, against 3% for DraftKings’ exchange. On Thursday, investors will see how far Predictions volume has grown since July’s $11 billion annualized pace, and what that growth cost.
Watch the Guidance, Then 2027
Until DraftKings shows its spending can fall while FanDuel’s and Robinhood’s keep climbing, I think the drop from January is a fair read on costs, and the late-October bounce is ahead of the numbers.
If DraftKings holds the $700 million floor on Thursday, and the 2027 update it promised for the Nov. 6 call shows Predictions spending falling, the rebound case has its numbers. A guidance cut or a bigger Predictions bill would make the selloff look right.
DraftKings doesn’t trade on costs alone, either. In the third quarter, the Ninth Circuit ruled that Kalshi’s sports event contracts likely aren’t federally regulated swaps, splitting with the Third Circuit. Legal fights over that question could move the stock more than any one quarter’s margin.
So what is DraftKings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DraftKings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!