Key Takeaways
- DoorDash shares fell 13% today after Amazon and Uber said Prime members now pay a $0 delivery fee on Uber Eats restaurant orders of $25 or more.
- Prime members have had free Grubhub+ since 2022, and DoorDash still took 59% of delivery-app spending last quarter, so I think the selloff overshoots the threat.
- Analysts expect DoorDash’s revenue to reach $25.7 billion by 2028, and the stock trades near its lowest forward P/E in five years.
DoorDash (DASH) stock is down 13% today after Amazon (AMZN) and Uber Technologies (UBER) said this morning that U.S. Prime members now pay a $0 delivery fee on Uber Eats restaurant orders of $25 or more, ordered right on Amazon.
That wiped out Wednesday’s 8% jump on Uber’s delivery numbers, on a day when plenty of tech stocks fell hard.
Uber Eats gets a front door to Prime
Members don’t need a new app or an Uber account. Uber Eats replaces Grubhub, whose deal with Amazon ended today, an Amazon spokesperson told TechCrunch.
Uber’s delivery business was already growing fast: its delivery gross bookings rose 22% to $28.5 billion in the third quarter, and that segment’s operating income grew 30%. Its shares are off 2% today all the same. Can Prime push that growth higher?
For Amazon, it’s one more reason to keep paying for Prime, and one more step into local delivery. It said last week that items ordered through its ultra-fast Amazon Now service are up 10x year over year. Amazon’s stock is down 4% too. And a Prime member ordering dinner inside Amazon never opens DoorDash’s app, or sees its ads.
TIKR tracks 42 analysts on DoorDash. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on DoorDash, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See DoorDash’s Analyst Ratings
DoorDash has beaten a Prime perk before
Prime members have had free Grubhub+ since 2022, and DoorDash still took 59% of delivery-app spending in the third quarter, against 18% for Uber Eats, according to Consumer Edge card data. Its gross order value rose 36% to $33.9 billion in the quarter.
Analysts expect its revenue to keep climbing, from $13.7 billion in 2025 to $25.7 billion in 2028.
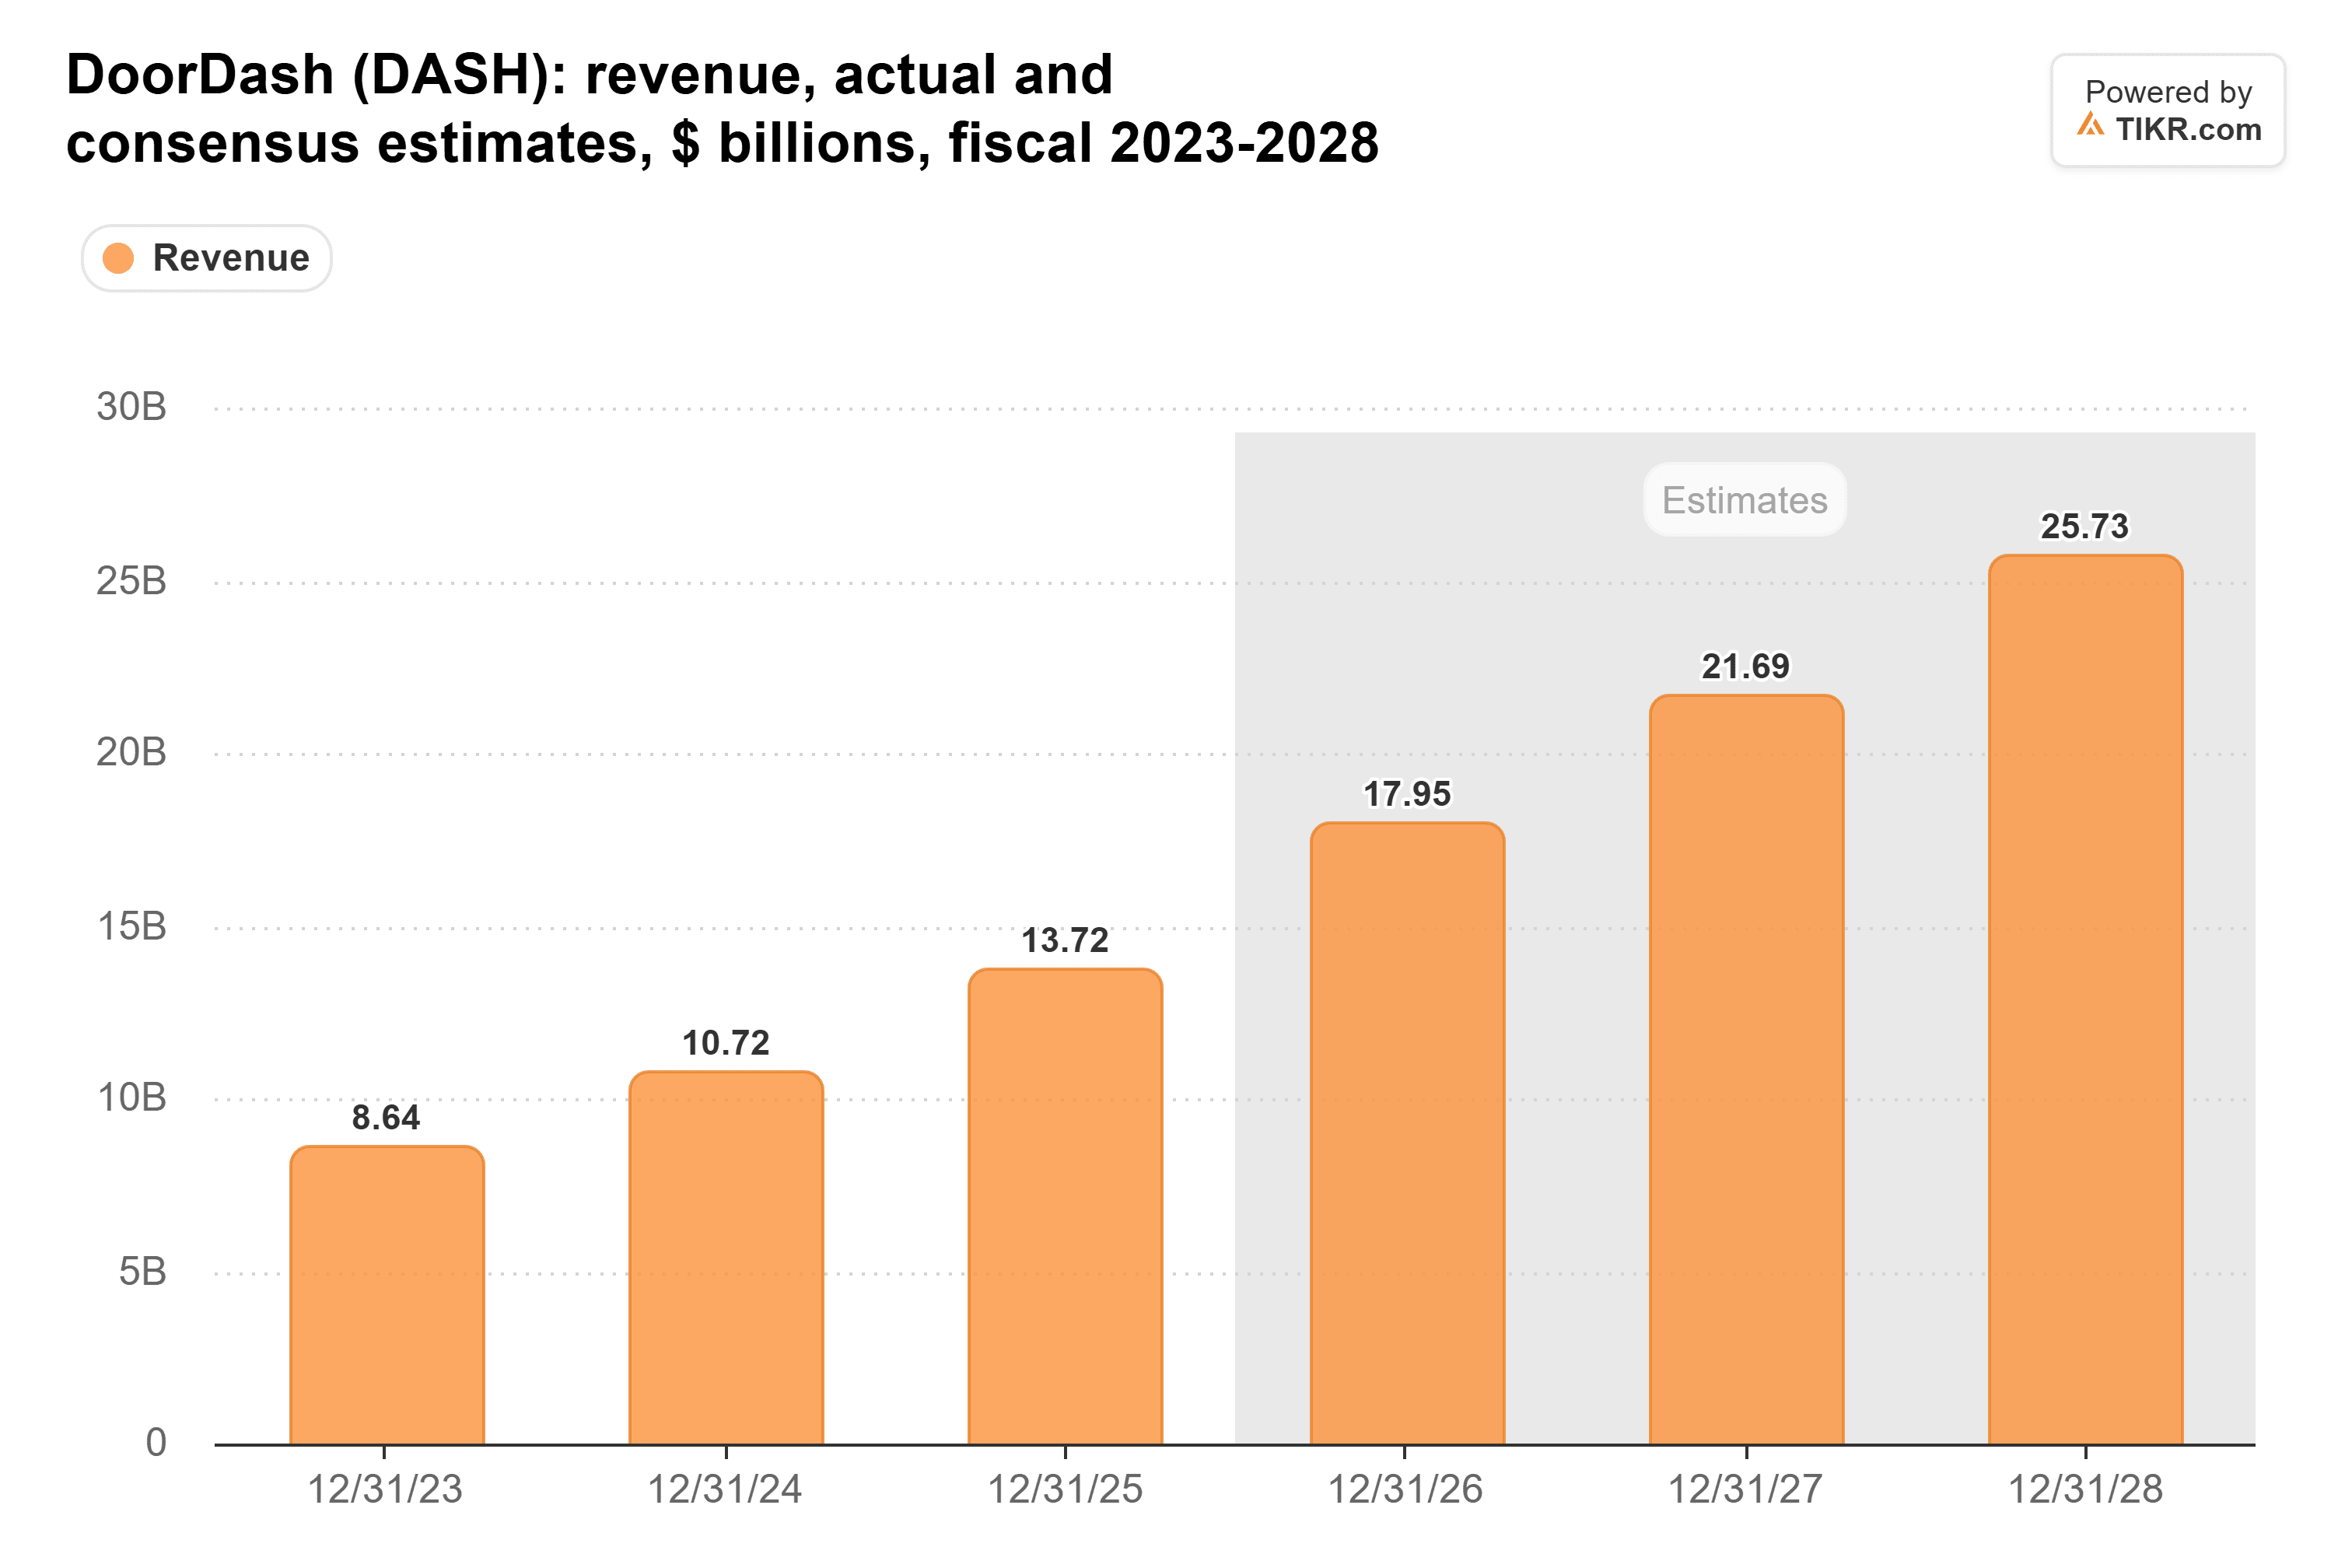
I don’t see a reason for those estimates to come down yet. DoorDash guided fourth-quarter order value to $35.4 billion to $36.4 billion a week ago.
The drop looks overdone
DoorDash traded at 28x forward earnings before today’s drop, against a three-year average of 39x. At today’s price, it’s even lower.
The way I see it, investors are pricing in more damage than one Prime perk is likely to do. The bigger question is how DoorDash pays for the $17 billion Instacart deal, at least 75% of it in cash, with $6.8 billion of cash and investments on hand at the end of September.
Of course, Uber Eats brings Prime members one of the largest restaurant networks in the U.S., and Uber’s early-February report will show how many Prime orders it’s winning.
So what is DoorDash stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DoorDash could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!