

Key Takeaways
- Dan Loeb’s Third Point raised its TransDigm (TDG) stake 216% in the quarter ended June 30, while Edgewood Management, which manages $22 billion, cut its stake 55%.
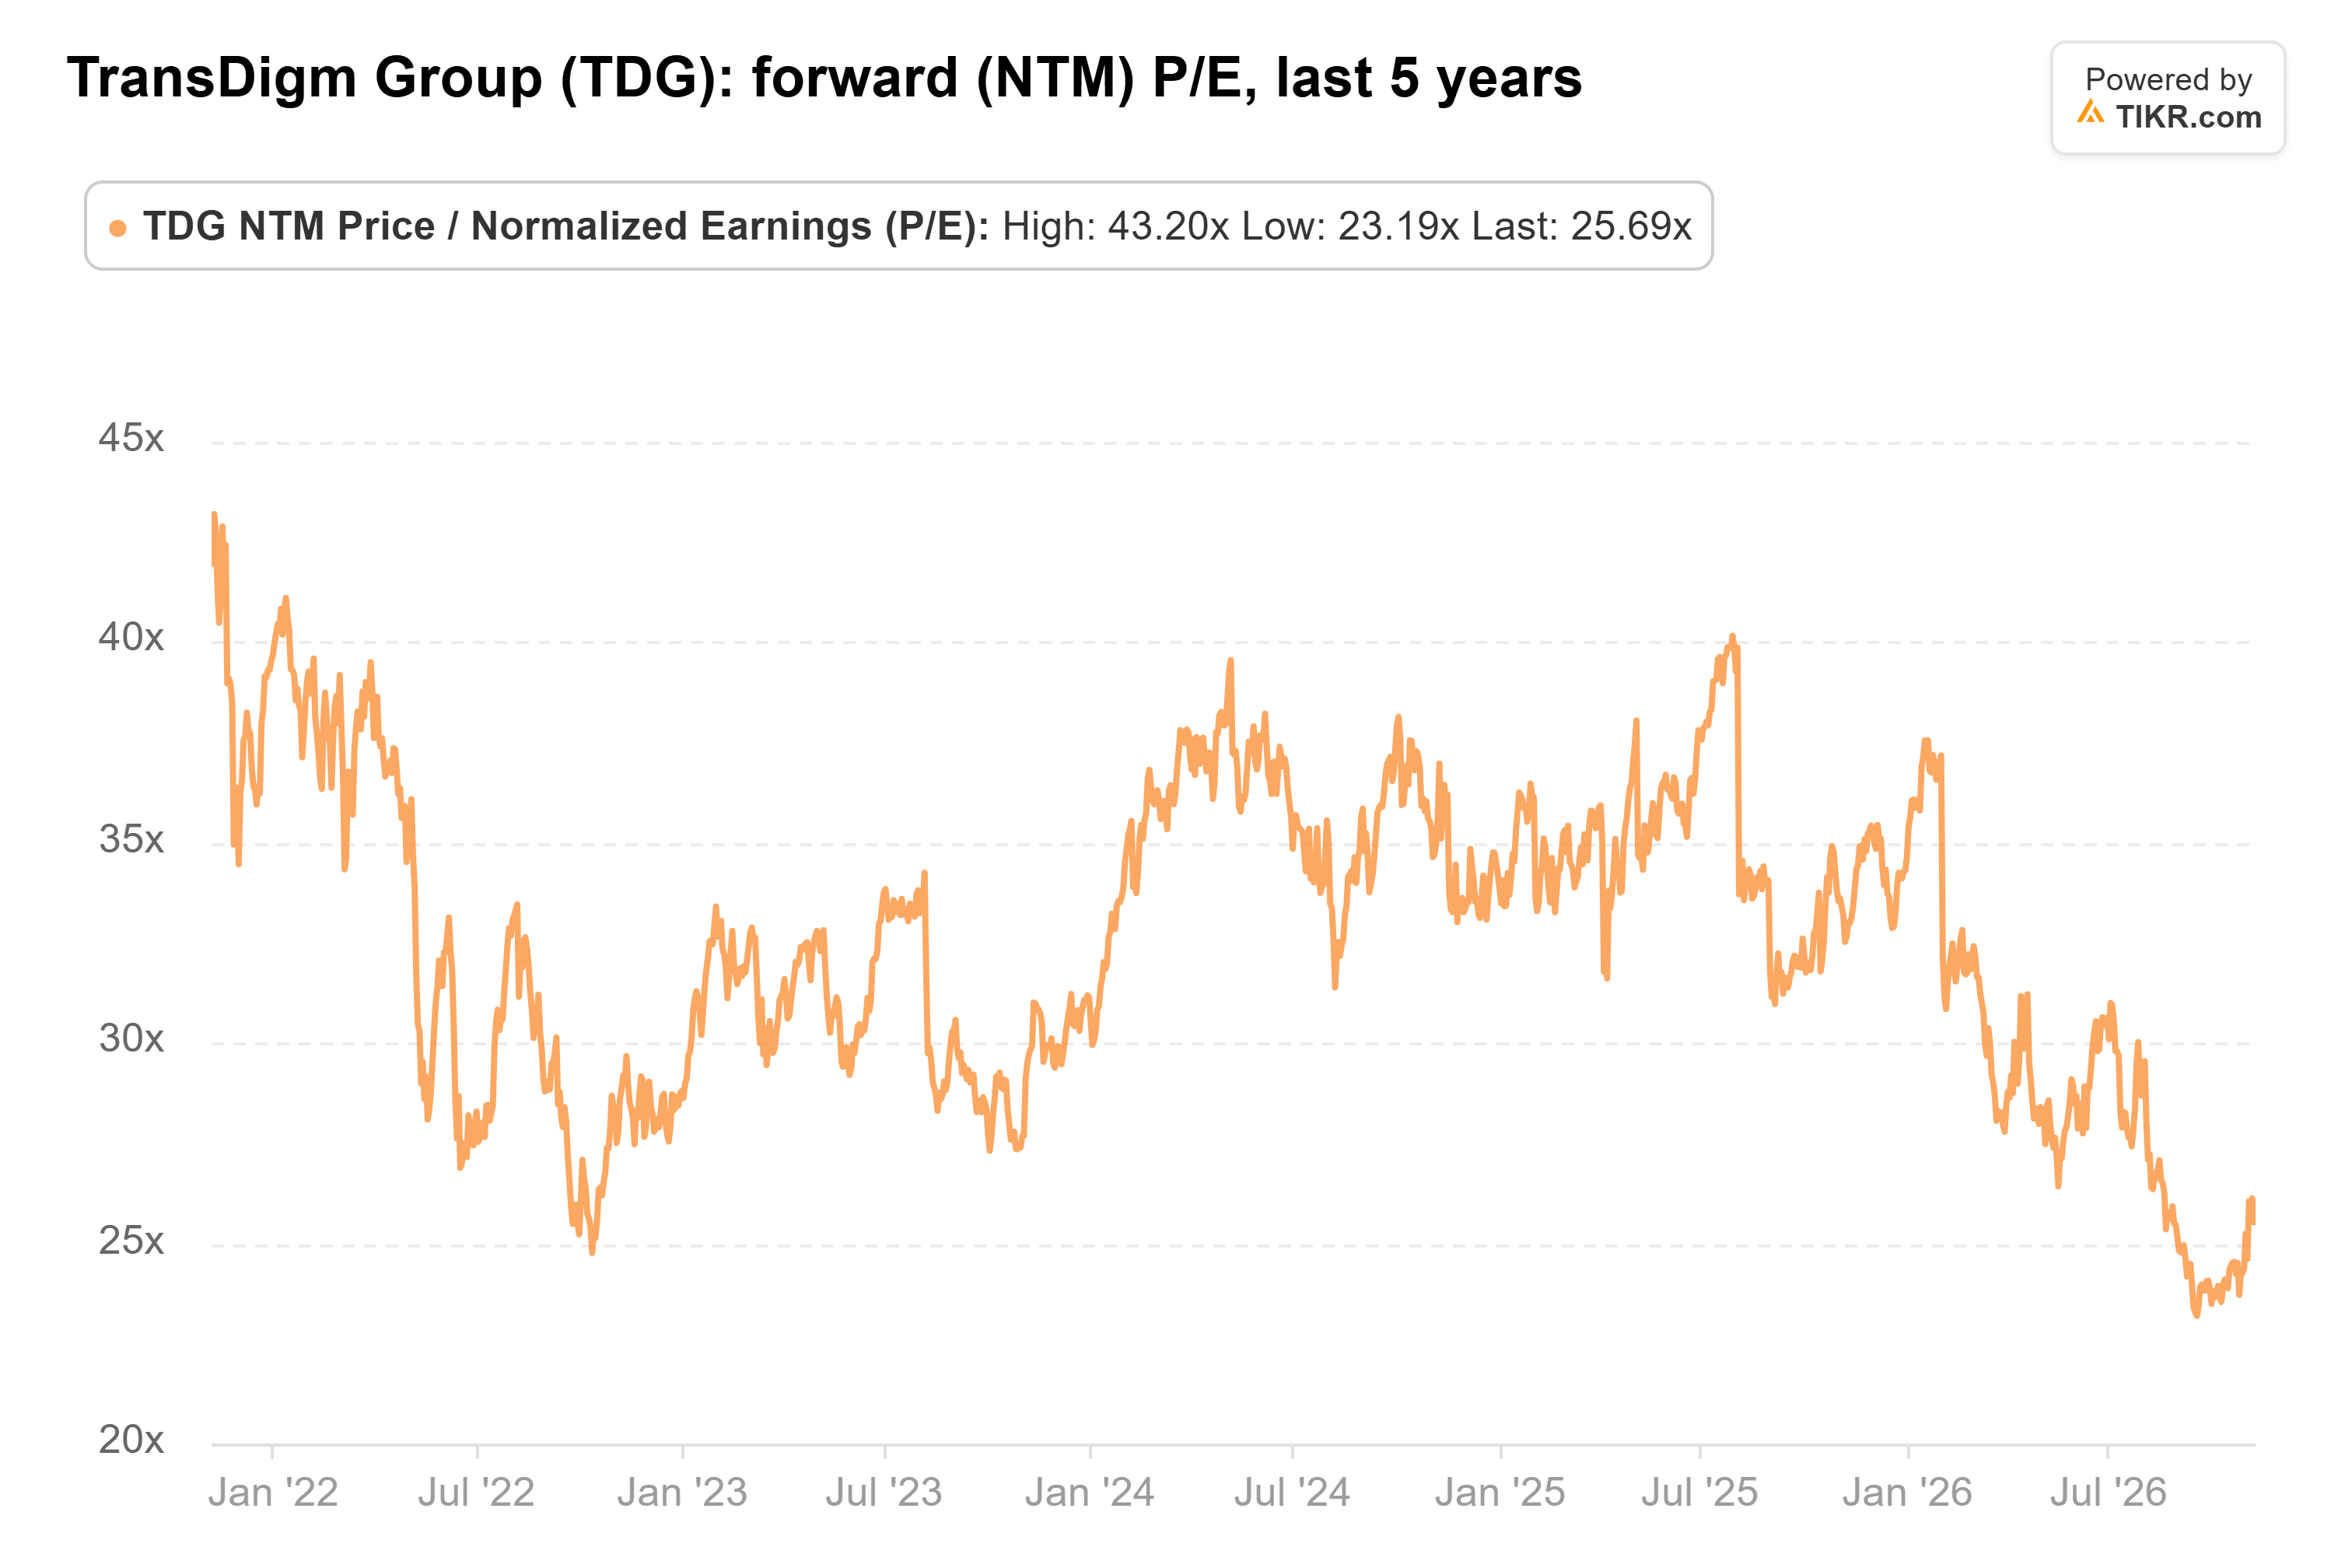
- TransDigm trades at 26x forward earnings, well below its five-year average of 33x, and analysts expect its earnings per share to rise every year through fiscal 2028.
- The main risk is the analysts’ average price target, which has fallen to its lowest point in the past year.
- Loeb looks to have the better side of the trade, and both funds’ next 13Fs are due by Nov. 16.
Two big investors went opposite ways on TransDigm in Q2.
Dan Loeb’s Third Point more than tripled its stake, while Edgewood Management cut its own by more than half, according to their 13Fs for the quarter ended June 30, still their latest filings.
The seller still owns more
Third Point, which manages $29 billion, filed its 13F on Aug. 14. It held 79,000 TransDigm shares worth $105 million at June 30, after raising its share count 216% over the quarter. That made TransDigm 2.3% of its 13F holdings and its 18th-largest position.
The $22 billion fund went the other way. Its 13F, filed Aug. 13, showed it cut its share count 55% in the quarter, to 278,240 shares worth $371 million.
Even so, TransDigm was still 3.8% of its 13F holdings and its 14th-largest position, a bigger bet than Loeb’s in dollars and in weight.
So the seller hadn’t given up on TransDigm as of June 30.
TIKR tracks 23 analysts on TransDigm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on TransDigm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See TransDigm’s Analyst Ratings
TransDigm kept delivering
Since June 30, TransDigm has given the buyer more to like. On Aug. 4, it reported that sales rose 23% to $2.74 billion in its fiscal Q3, which ended June 27, with double-digit growth in all three of its main markets. Commercial aftermarket sales grew 17%, and the company bought back about $1.0 billion of its own stock in the quarter.
It also raised its fiscal 2026 guidance, lifting the midpoint of its EBITDA As Defined outlook by $100 million to $5.52 billion.
Analysts expect TransDigm’s normalized EPS to climb every year through fiscal 2028, from $37.33 in fiscal 2025 to $55.88:
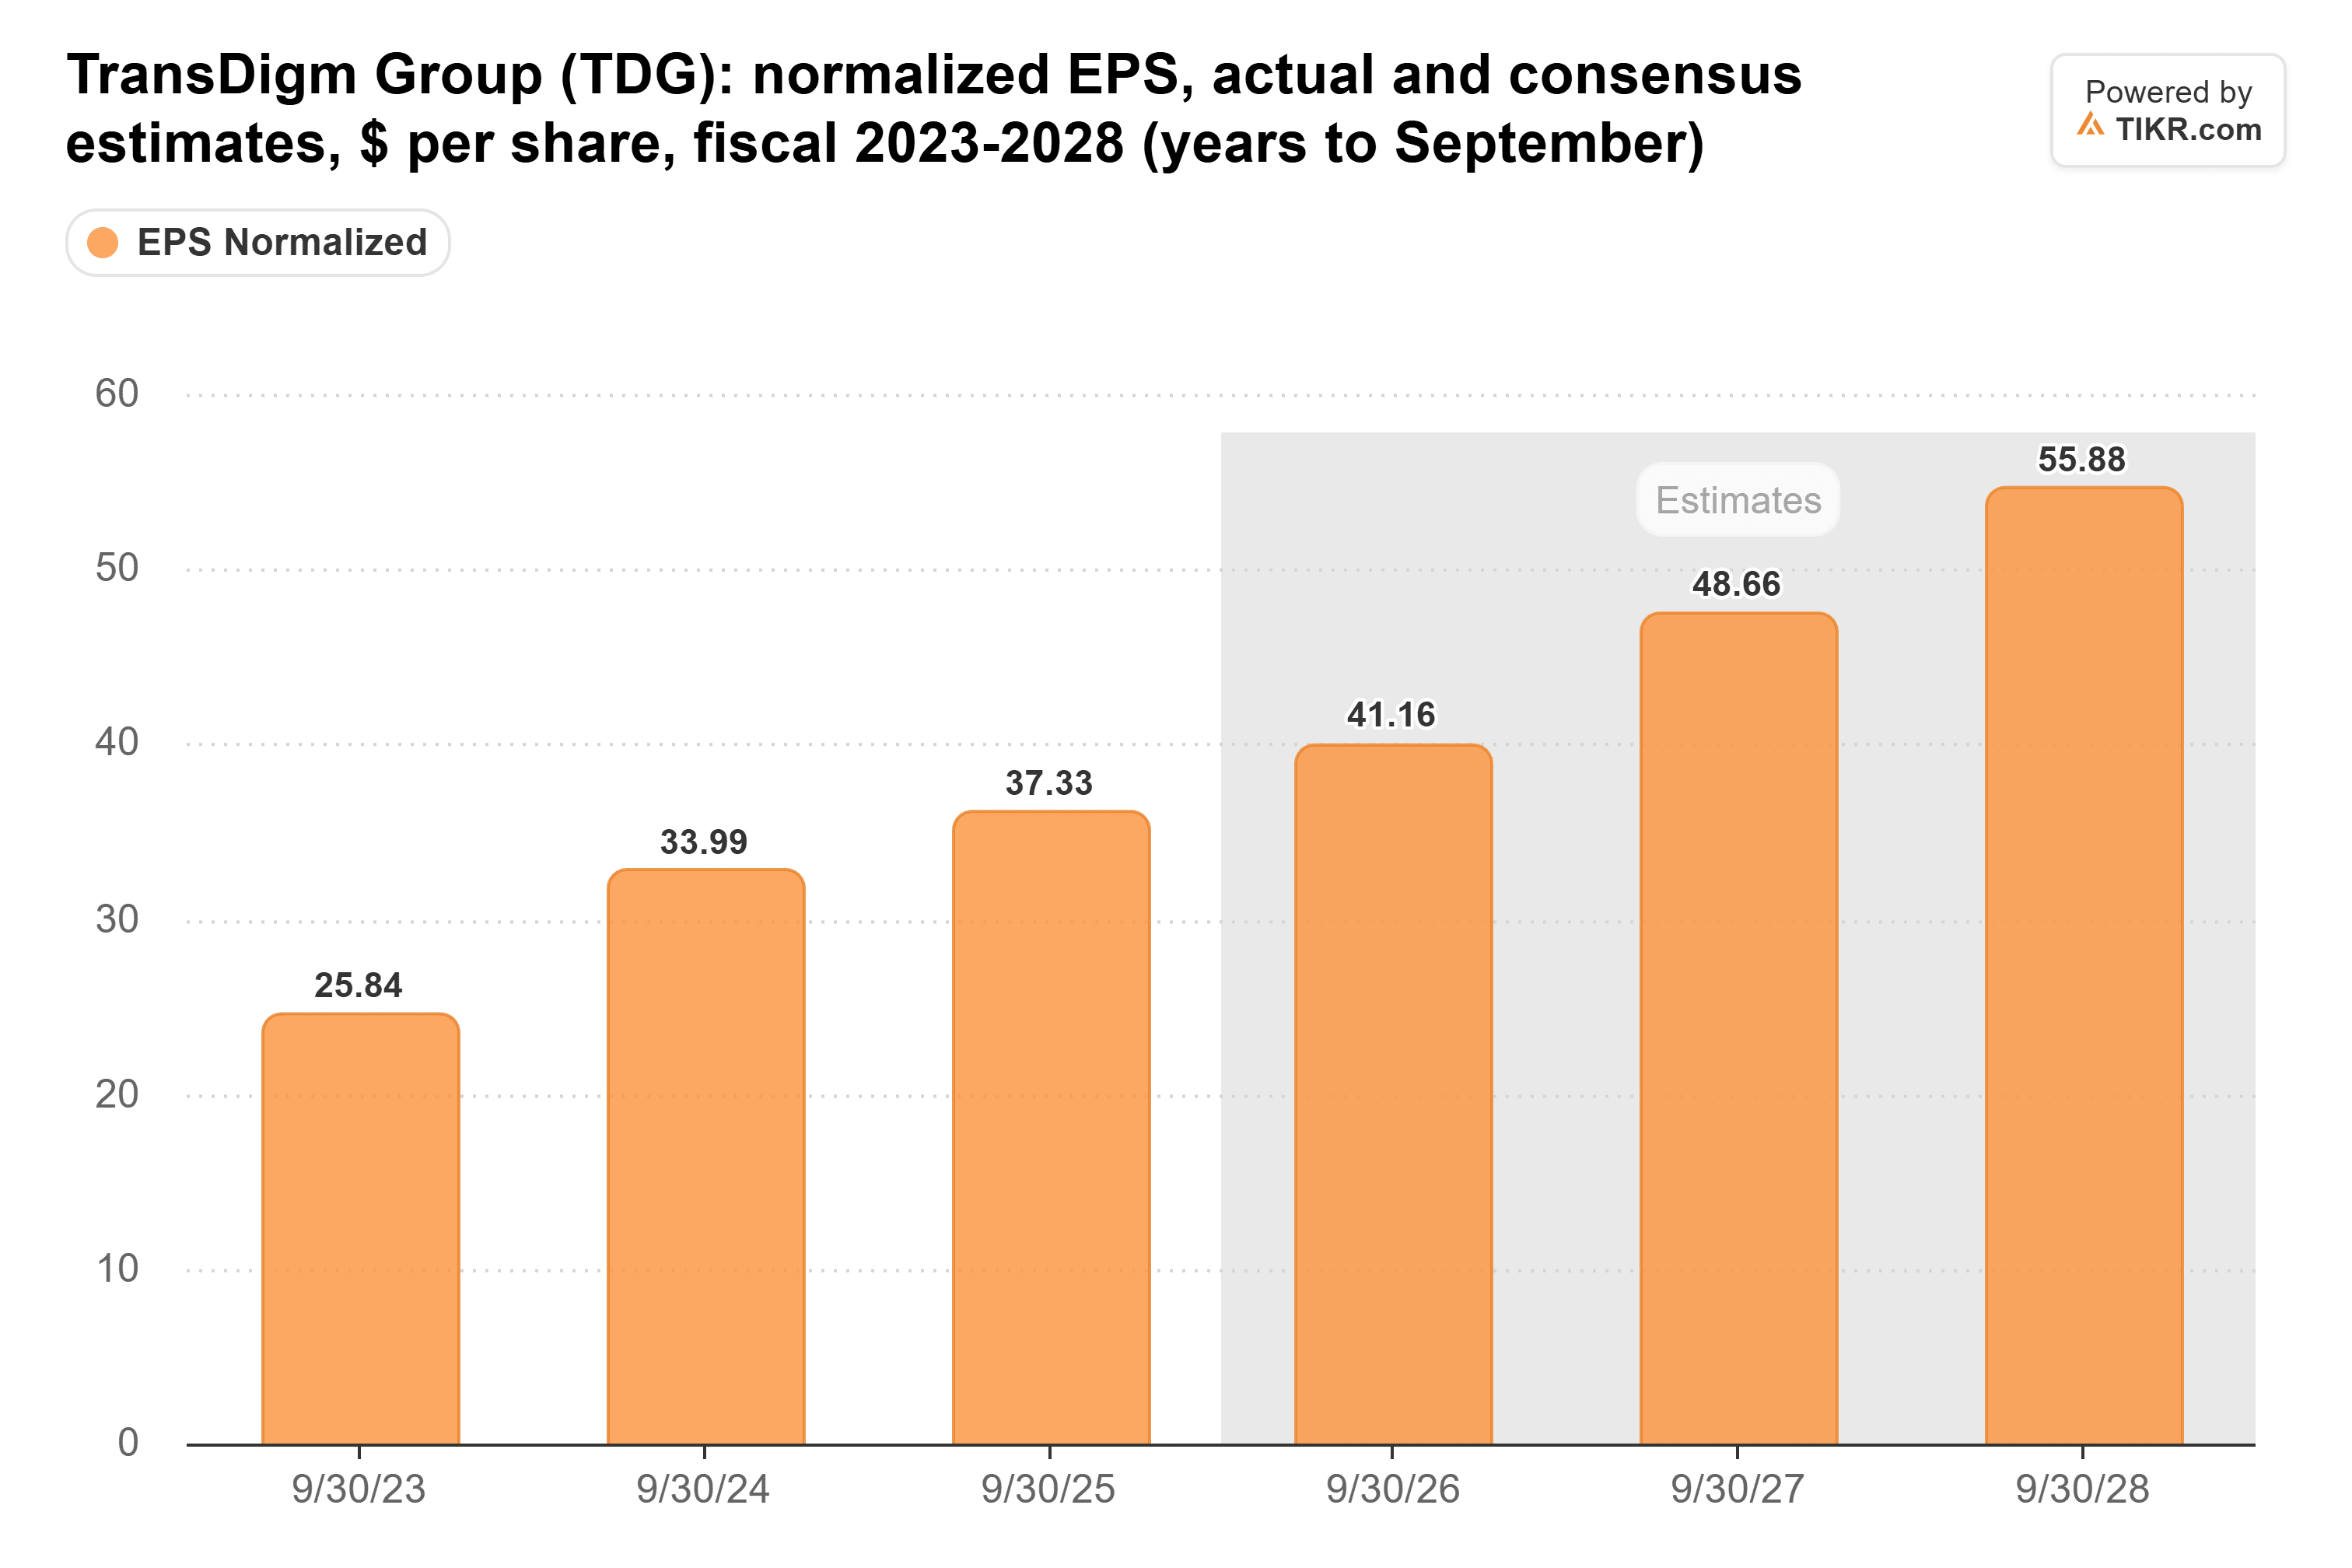
Nothing in August’s raised guidance gives me a reason to expect those estimates to come down.
Near its cheapest in five years
The stock hasn’t kept pace with the business. TransDigm trades at 26x forward earnings, well below its five-year average of 33x and not far above the 23x low it hit on Sept. 17:
Analysts have grown more cautious, though. Their average price target has fallen from $1,558 a year ago, and a January peak of $1,622, to $1,414, its lowest point of the past year:
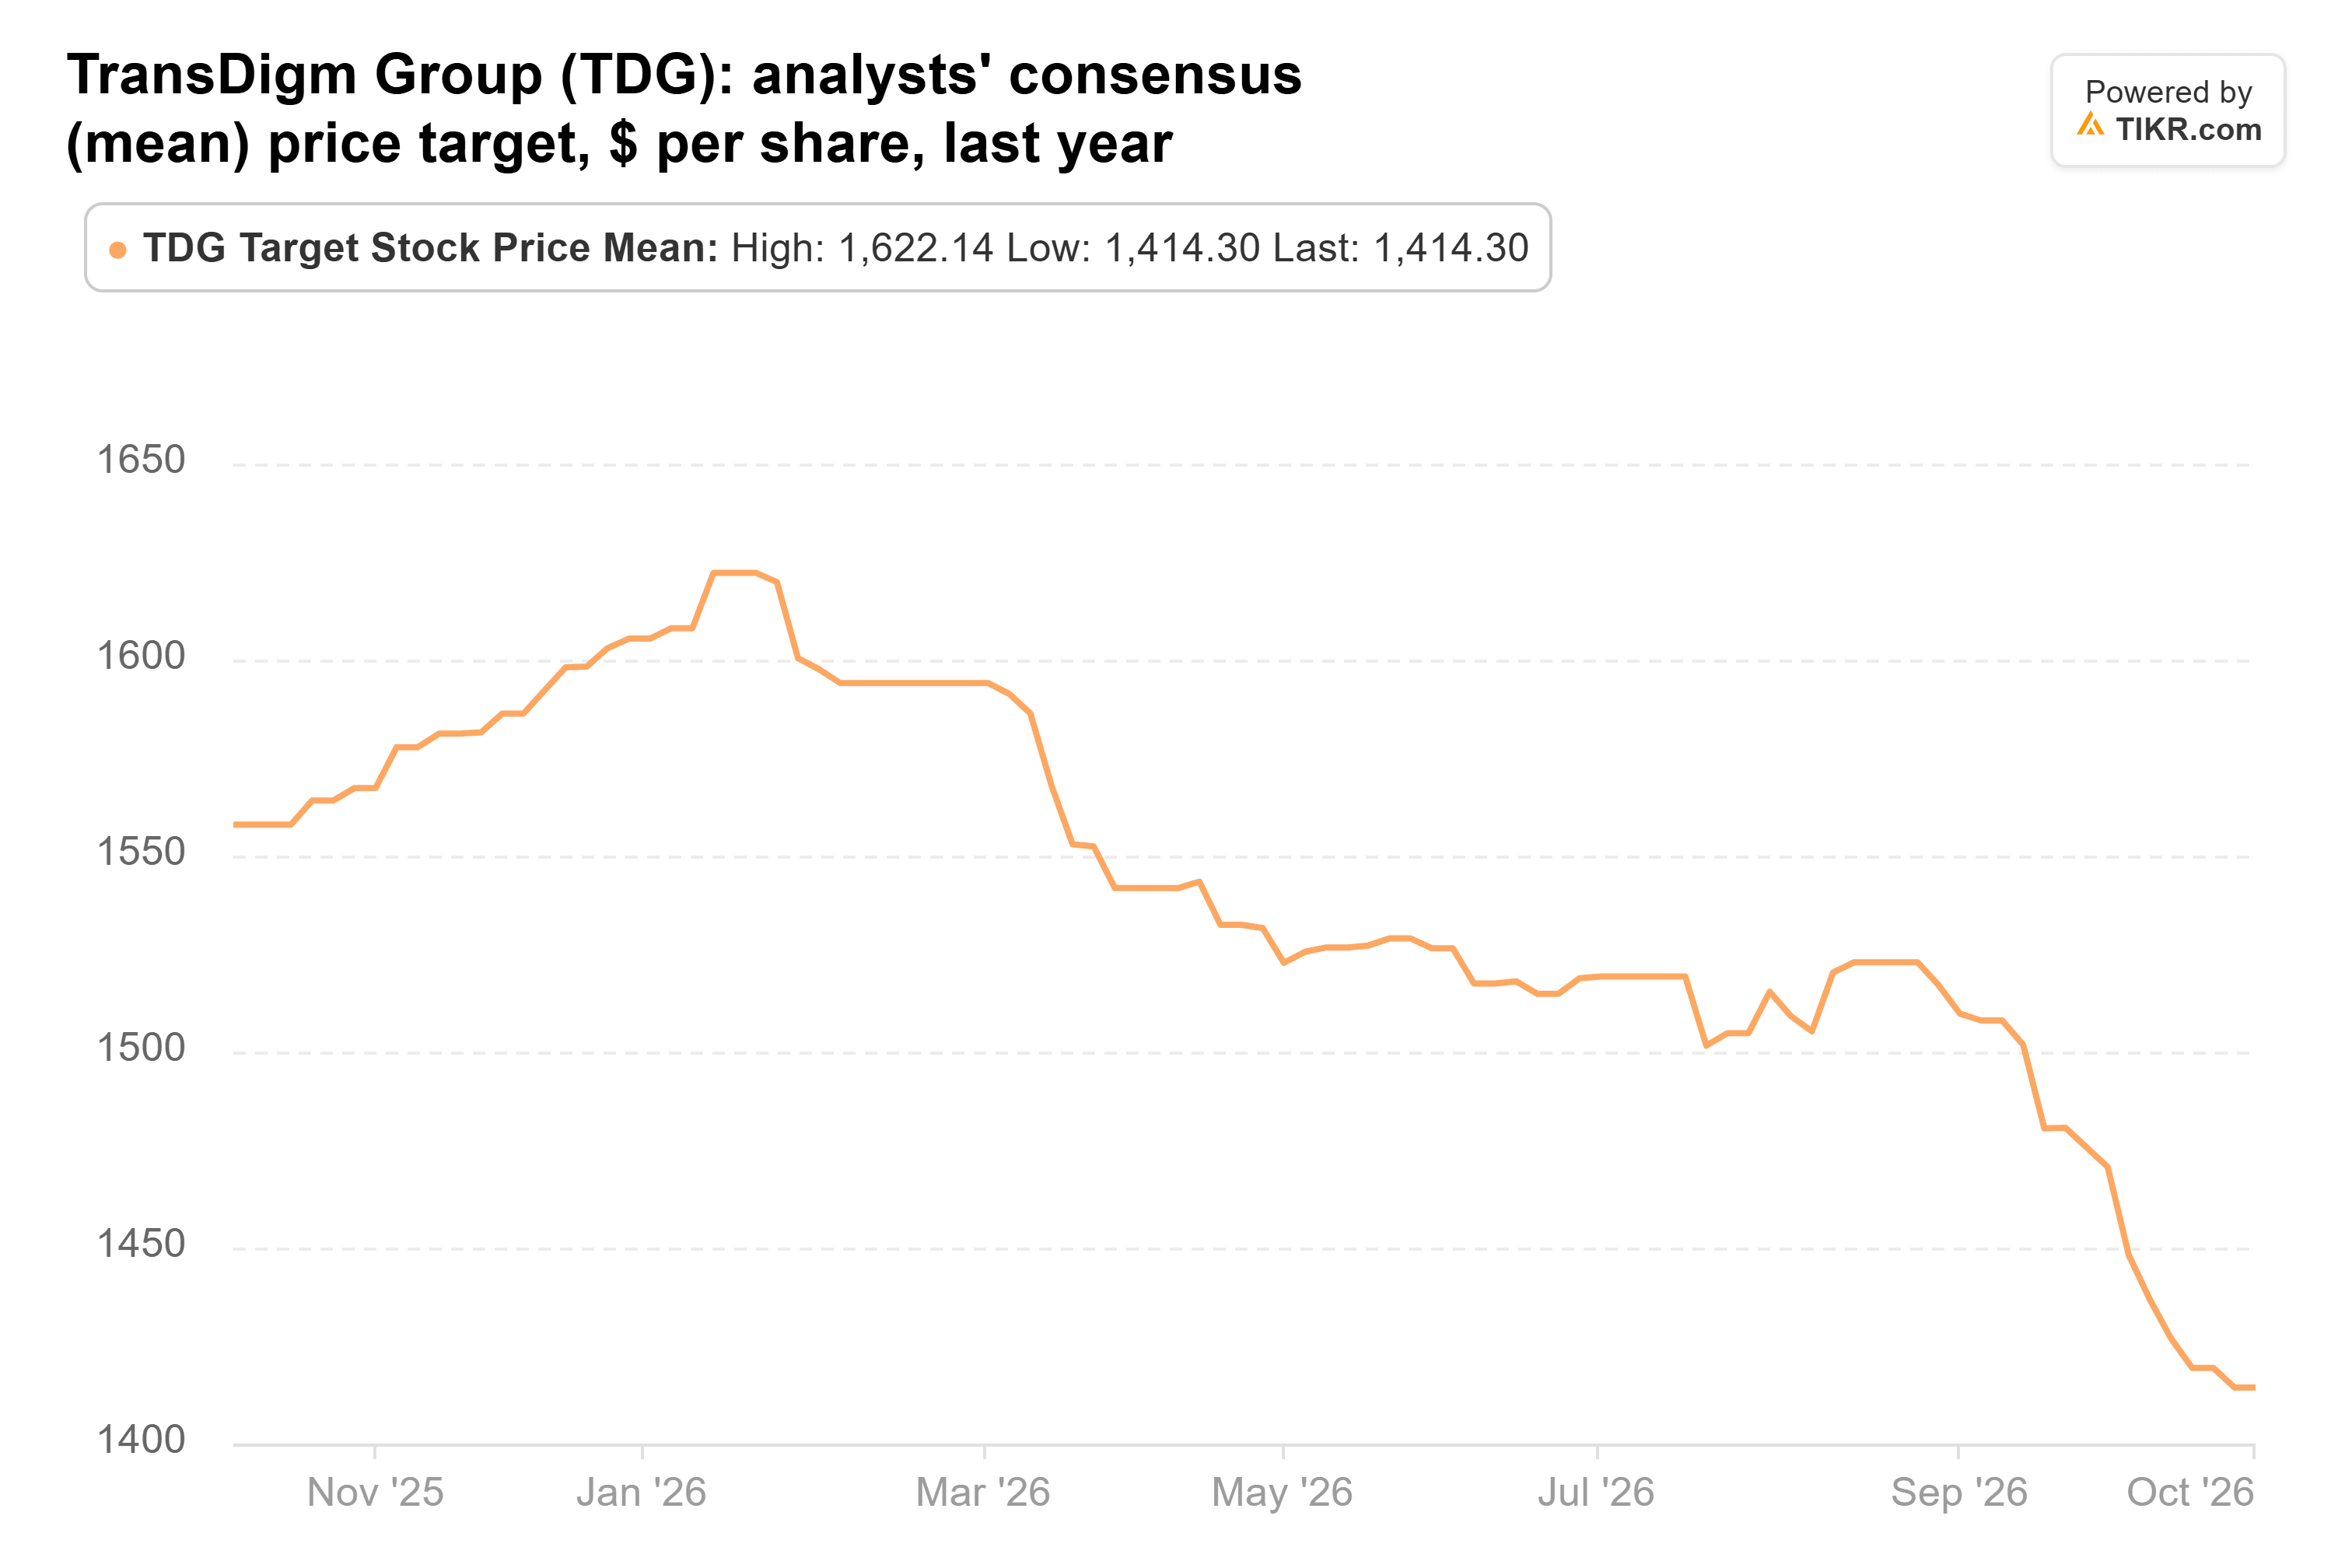
Even after those cuts, that average is 18% above Friday’s close of $1,197. Twenty-three analysts cover the stock, and the highest target is $1,745.
Loeb has the better side of this
The way I see it, Loeb is buying a business that keeps raising its guidance, at one of its lowest multiples in five years.
Earnings per share are expected to rise every year through fiscal 2028, so the stock doesn’t need its old 33x to do well from here. If the multiple climbs even part of the way back toward that average while the estimates hold, shareholders should do well.
The seller has had the better few months on price alone, with the stock down 10% from its June 30 price. And the risk is that analysts keep cutting: the lowest target on the Street, $1,100, is already below Friday’s close.
TransDigm’s fiscal Q4 report, expected in the next few days, will show whether August’s raised guidance held up.
Then both funds’ 13Fs for the quarter ended Sept. 30, due by Nov. 16, will show whether Loeb kept adding and whether the $22 billion fund kept selling.
So what is TransDigm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what TransDigm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!






