Key Takeaways
- Credo Technology is down 57% from its June high, a bit more than Astera Labs or Marvell, even though its first-quarter revenue rose 115% to $479 million.
- MaxLinear wants 20% to 30% of the next generation of active electrical cables, the product behind most of Credo’s growth.
- Credo is answering with optics and is targeting more than $600 million of optical revenue this fiscal year, while Marvell’s $115 billion deal for Lumentum is a bet on the same shift.
- Credo’s forward P/E is far below its own history and analysts still expect its earnings to nearly triple by fiscal 2028, so the stock looks due for a bounce if its Dec. 1 report shows the optical ramp on track.
Credo Technology (CRDO) is down 57% from its June 22 high, a bit worse than its closest peers. Astera Labs (ALAB) is down 50% over the same stretch, and Marvell (MRVL) is off 49%.
Investors stopped paying up for its near-monopoly in active electrical cables (AECs), the copper links between AI servers and switches. Now MaxLinear (MXL) wants 20% to 30% of the next generation.
TIKR tracks 20 analysts on Credo Technology. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Credo Technology, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Credo Technology’s Analyst Ratings
Holding the optics target cost Credo
After a summer slide on no news and steady forward estimates, the bigger hit came with the Sept. 1 report. First-quarter revenue jumped 115% to $479 million, and the $525 million to $535 million second-quarter guide topped the $516.5 million analysts expected.
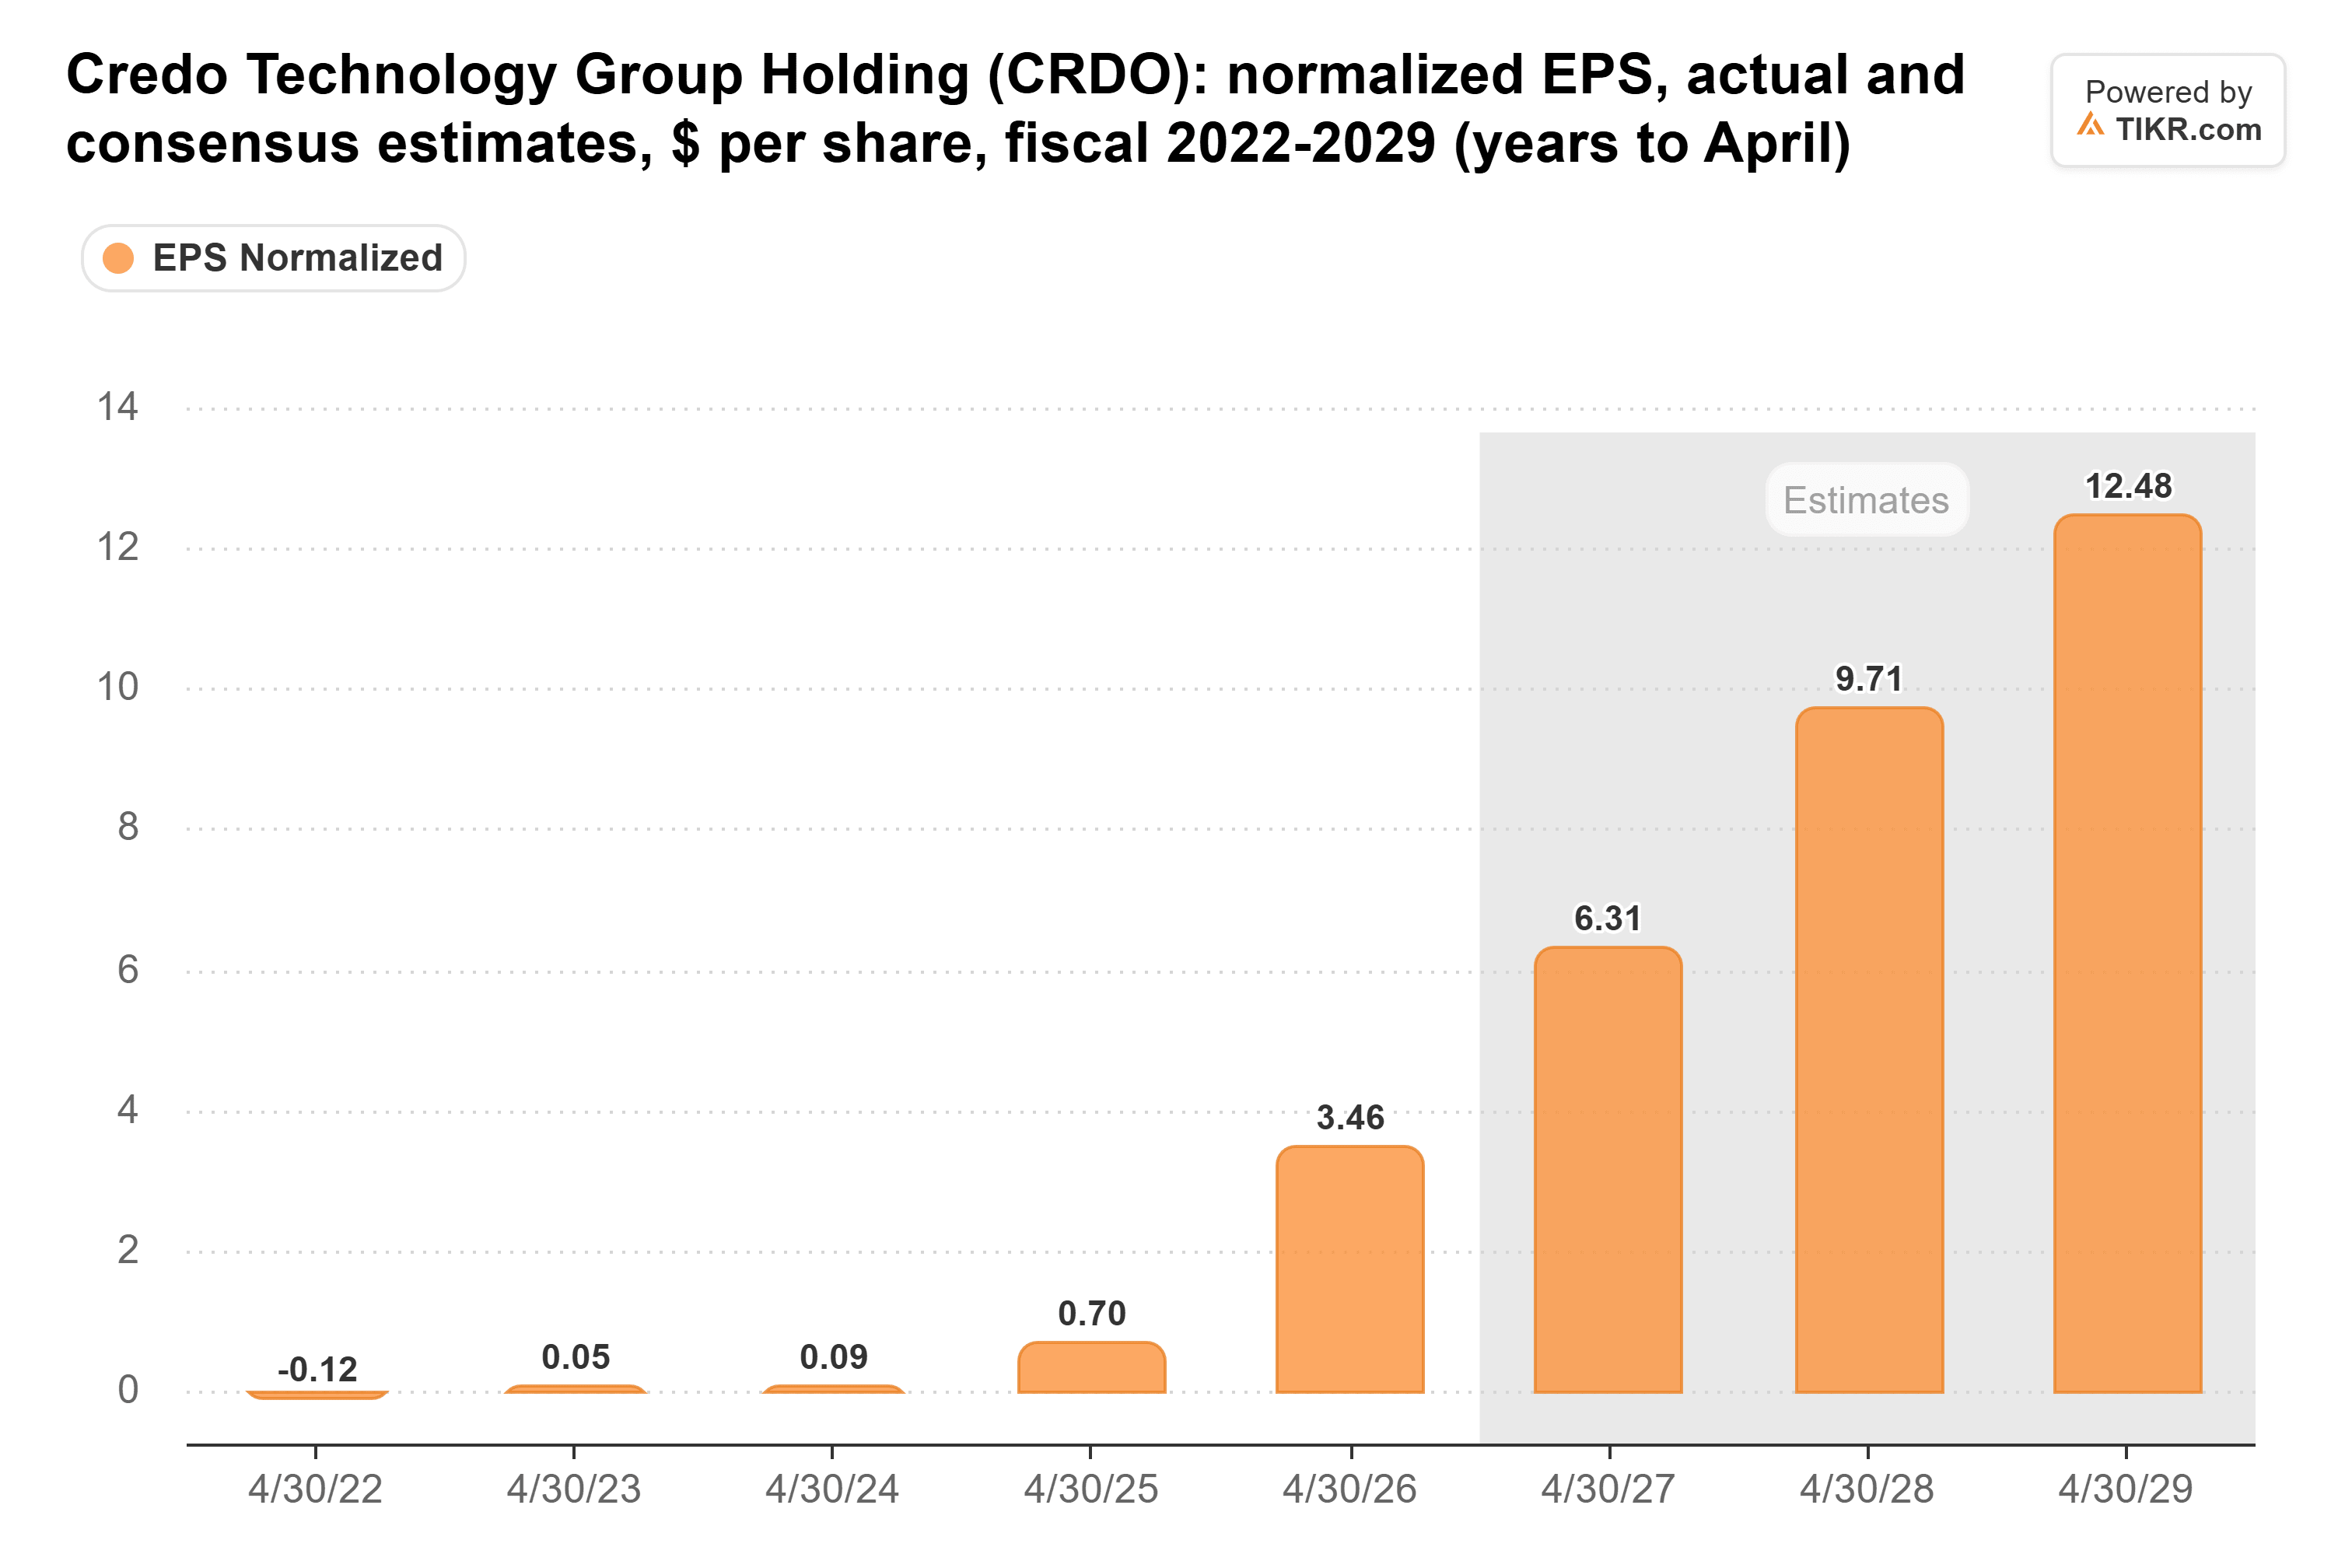
But management only repeated its target of more than $600 million in optical revenue this fiscal year. Investors wanted a raise. The stock fell 20% the next day. Analysts still expect Credo’s earnings to nearly triple, with normalized EPS climbing from $3.46 in fiscal 2026 to $9.71 in fiscal 2028:
MaxLinear wants a piece of the cable business
Cables are behind most of Credo’s growth: AECs drove more than 90% of the first quarter’s revenue gain from a year earlier, its quarterly report says. On MaxLinear’s Oct. 22 earnings call, CEO Kishore Seendripu put Credo’s AEC share at “93% or maybe 99%” and said “there are going to be multiple AEC vendors.” MaxLinear is aiming for 20% to 30% of the 1.6T generation over the next couple of years. An Edgewater Research note pointed to a Cisco program quoting 100,000 1.6T cables a month that could use Broadcom or MaxLinear chips.
Still, MaxLinear expects its first 1.6T revenue in 2027 and volume in 2028, after Credo’s fiscal year ends next spring. A 93% share can only shrink, but the real fight comes in fiscal 2028.
Optics is the hedge, and the group sank together
Credo’s answer is optical DSPs, silicon photonics chips and ZeroFlap transceivers, each expected to top $100 million this fiscal year. Marvell made the same bet on a far bigger scale on Nov. 2 with a $115 billion all-stock deal for Lumentum, framed as a wager on optics replacing copper. That deal isn’t expected to close until the first half of 2028, after Credo’s own optical ramp is due to land.
Then the whole group sank. Democrats swept the midterms on Nov. 3 on promises of tougher limits on data-center construction. AI hardware then sold off for two days. Astera Labs had just reported record third-quarter revenue of $584.9 million, up 154%, and got caught in the selling anyway. So I’d put most of Credo’s fall on the AI connectivity trade as a whole.
Due for a bounce, if December delivers
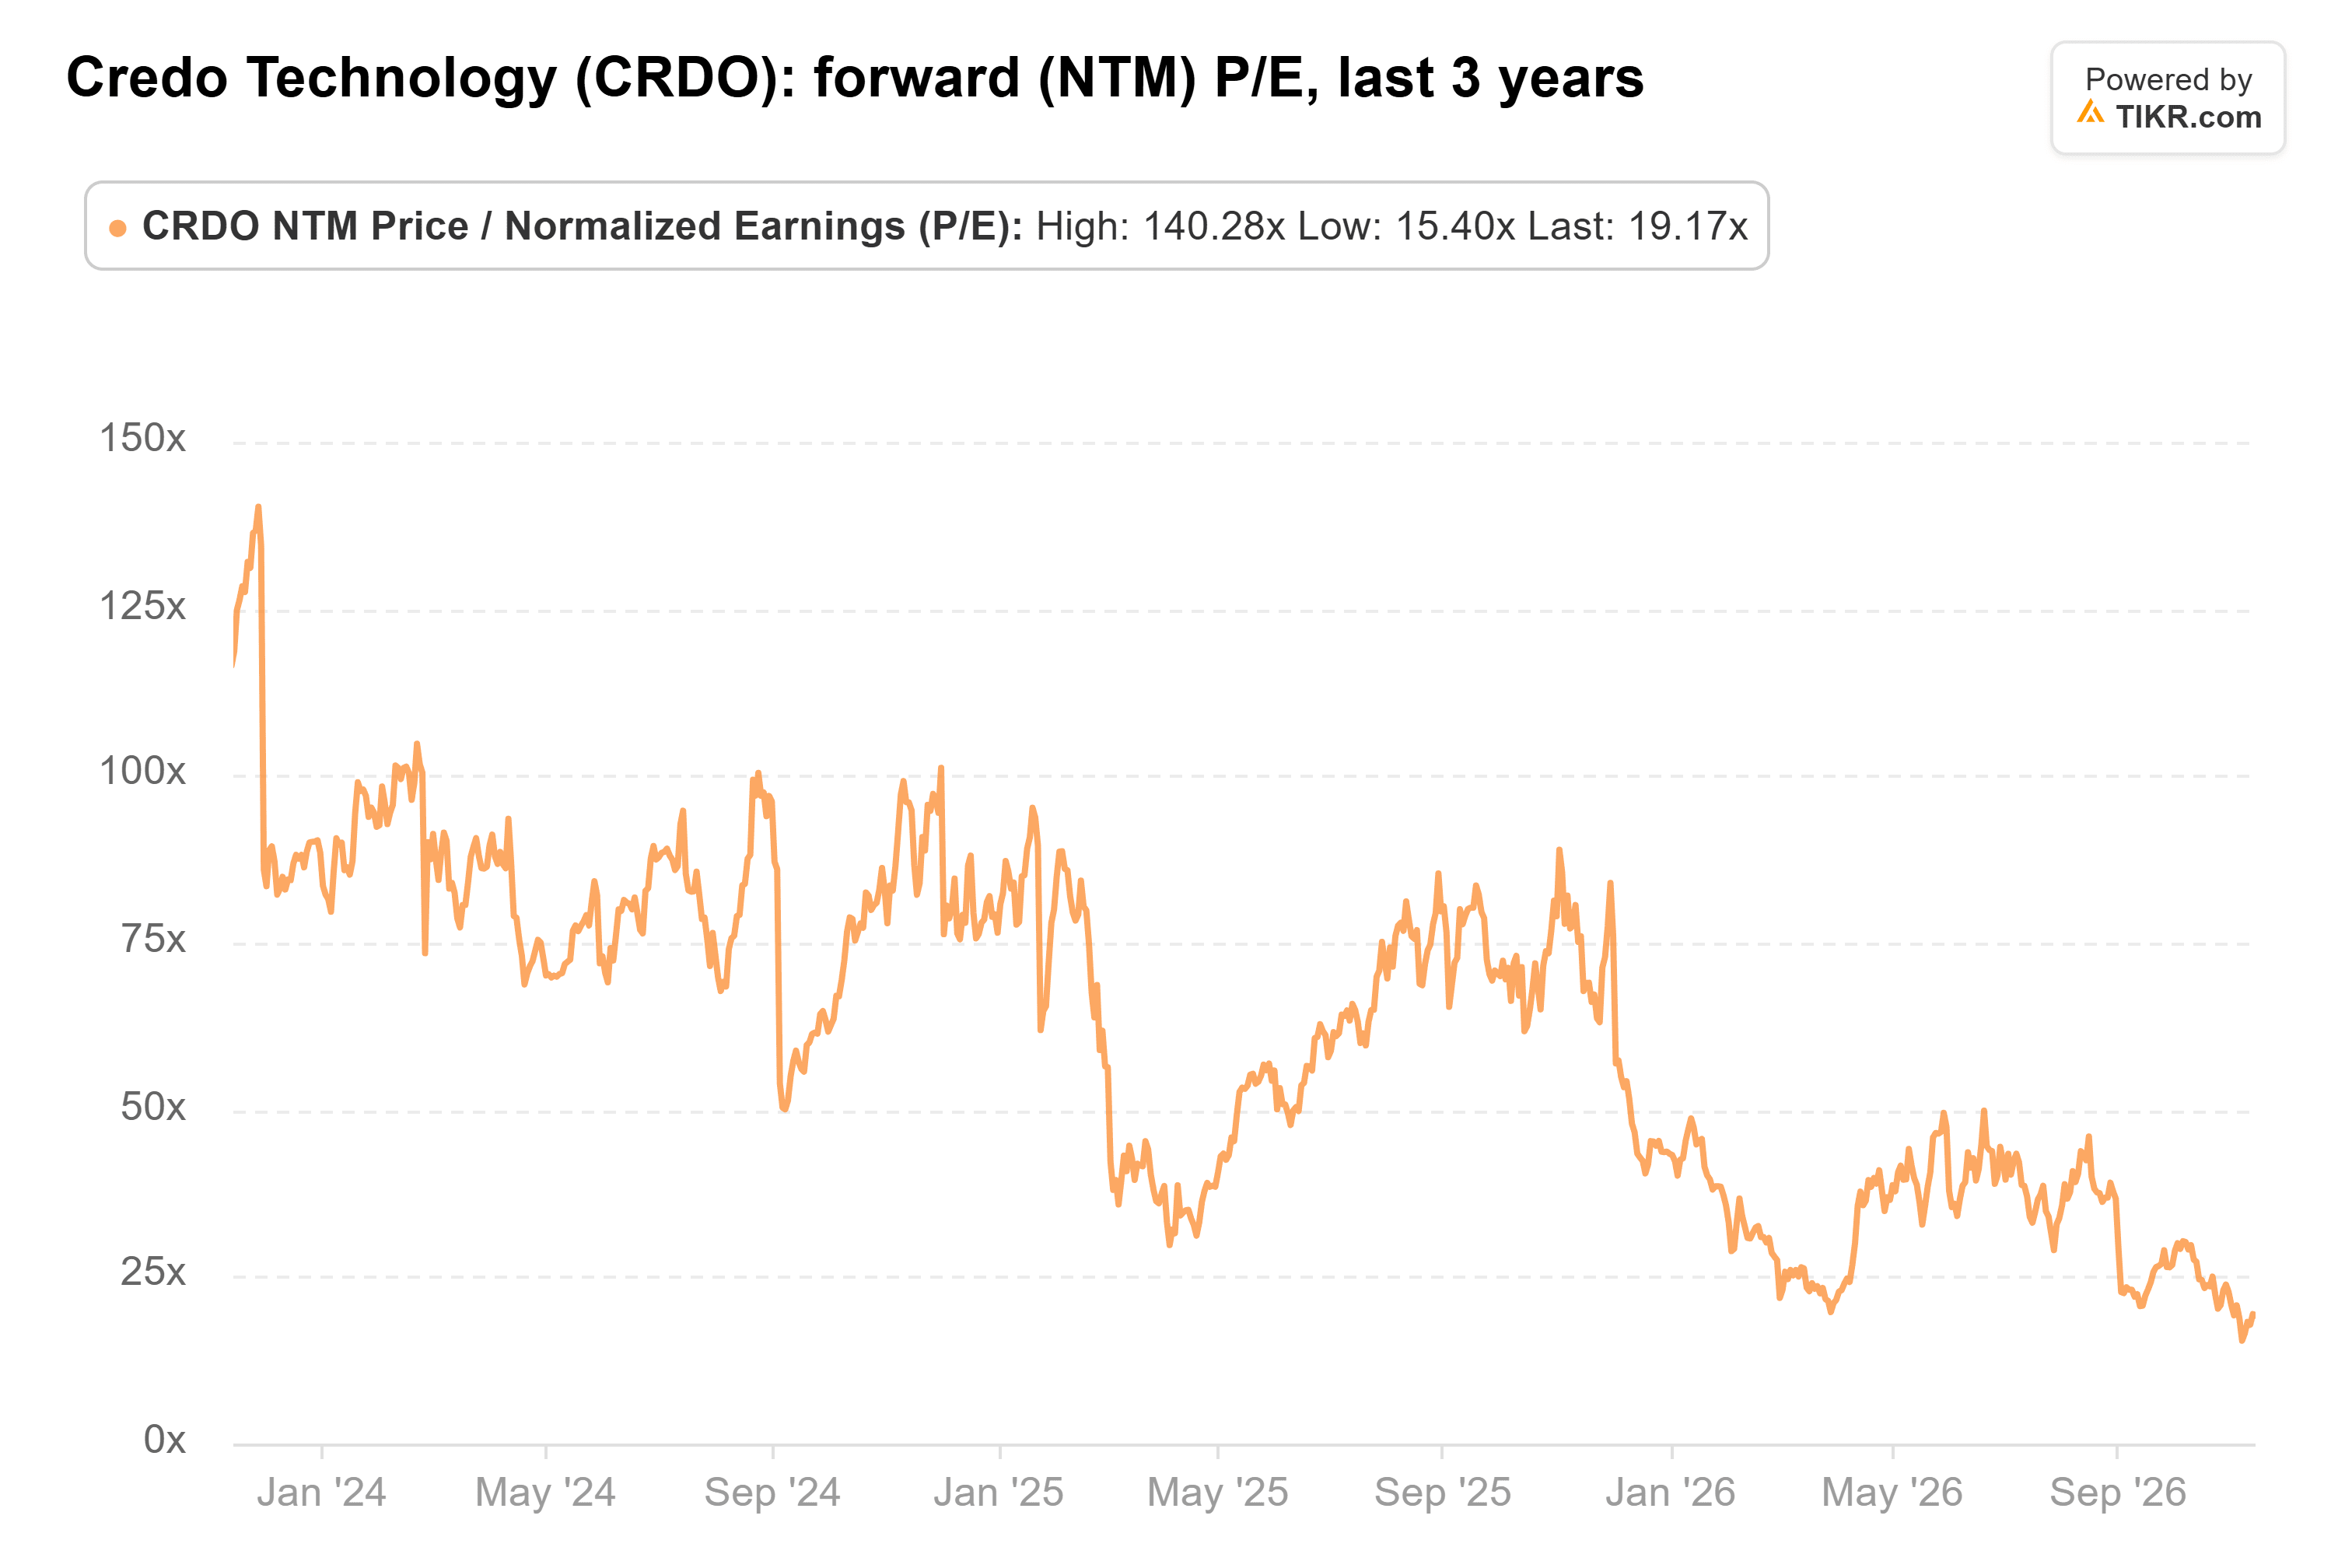
Investors are paying far less for those earnings now. Credo’s forward P/E has dropped to about 19x, from 44x at the end of June and against a three-year average of 62x:
The big risk is concentration: four customers bought 84% of first-quarter revenue. Even so, Credo looks due for a bounce to me. The stock is priced as if its cable lead were already gone, and I don’t think it is.
Of course, Credo’s target of more than 85% growth this fiscal year needs at least $1.46 billion of second-half revenue. That would be up 73% or more from a year earlier. It reports after the close on Dec. 1. A sharply higher third-quarter guide, with optical revenue in dollars, would go a long way. Another modest guide could leave the stock stuck for a while.
So what is Credo Technology stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Credo Technology could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Credo Technology for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!