Key Takeaways
- Credo shares fell 32% in the week through Nov. 5 in an AI hardware selloff, and Astera Labs and Marvell fell even further.
- Credo had no bad news of its own, and its one announcement, with Oracle, was a small win in optics.
- Analysts expect Credo’s normalized EPS to nearly triple from fiscal 2026 to fiscal 2028, yet its forward P/E hit a three-year low.
- The selling looks overdone, and Credo’s early-December report will show whether its growth outlook still holds.
Credo Technology (CRDO) stock fell 32% in the week through Nov. 5, with no bad news of its own, before bouncing 7% on Nov. 6. Its closest rivals had it even worse: Astera Labs (ALAB) and Marvell Technology (MRVL) fell harder as the Nasdaq 100 dropped 9%.
Washington did most of the damage
Most of the drop came after the Nov. 3 midterms. Democrats won both chambers of Congress and key governors’ races, and several winners campaigned on tougher limits on building data centers. Texas, whose new governor-elect promised an immediate data-center moratorium, is the AI trade’s “biggest worry,” according to Yorkville Ives & Co.’s Dan Ives.
Intel’s weak fourth-quarter outlook, issued after the close on Oct. 29, had already hit chip stocks on Oct. 30.
Astera Labs and Marvell fell even harder
Astera Labs is down 38%, even though it reported record third-quarter revenue of $584.9 million on Nov. 3, up 154% from a year earlier, and guided fourth-quarter revenue to $730 million to $750 million.
Marvell, down 39%, agreed on Nov. 2 to buy Lumentum in an all-stock deal valuing it at $115 billion, betting that optical links will replace copper. So what happens to Credo’s copper cables, which drove over 99% of its revenue growth in fiscal 2026?
But Credo has its own optical push: management expects more than $600 million of optical revenue in fiscal 2027. And on Nov. 4, Credo and Oracle said the Open Compute Project had approved two optical telemetry specifications from a workstream the two companies lead. A small win, but in the right direction.
TIKR tracks 20 analysts on Credo Technology. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Credo Technology, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Credo Technology’s Analyst Ratings
Cheaper than it’s been in three years
Management still guides fiscal 2027 revenue growth of more than 85%, and analysts expect normalized EPS to climb from $3.46 in fiscal 2026 to $9.71 in fiscal 2028:
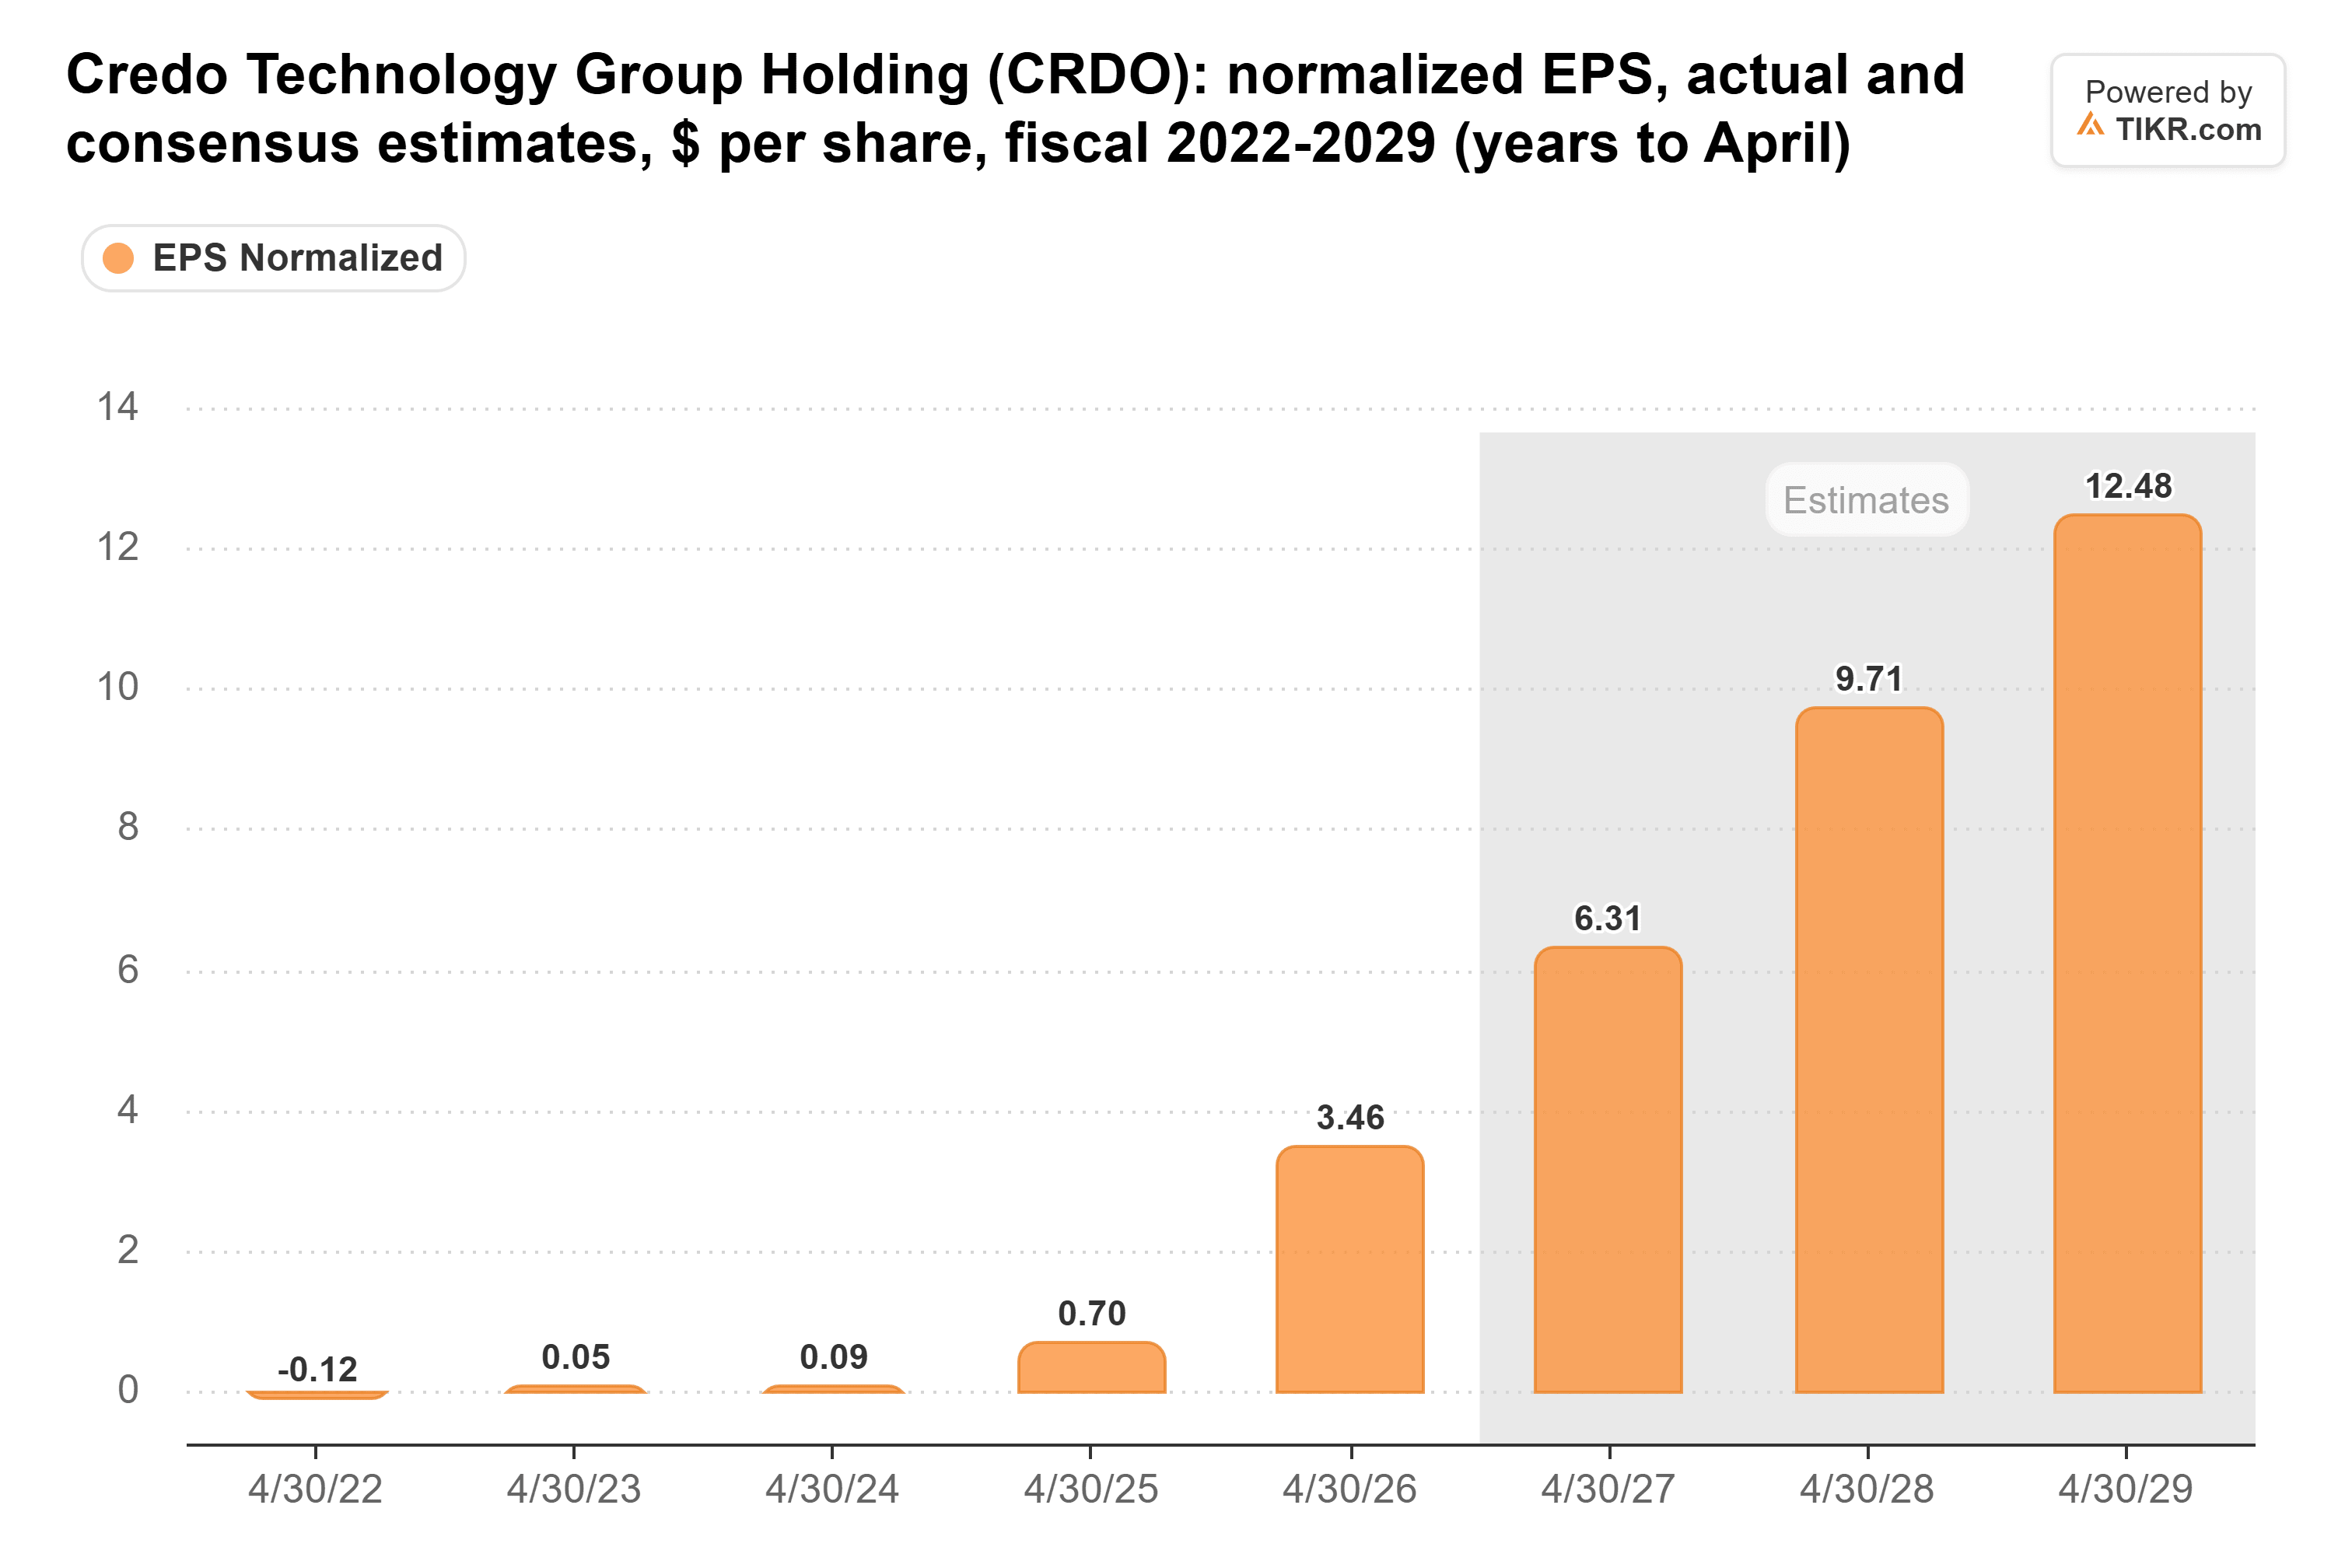
Nothing Credo said during the selloff gives analysts a reason to cut those numbers. Yet its forward P/E was 19x on Nov. 2, far below its 63x three-year average:
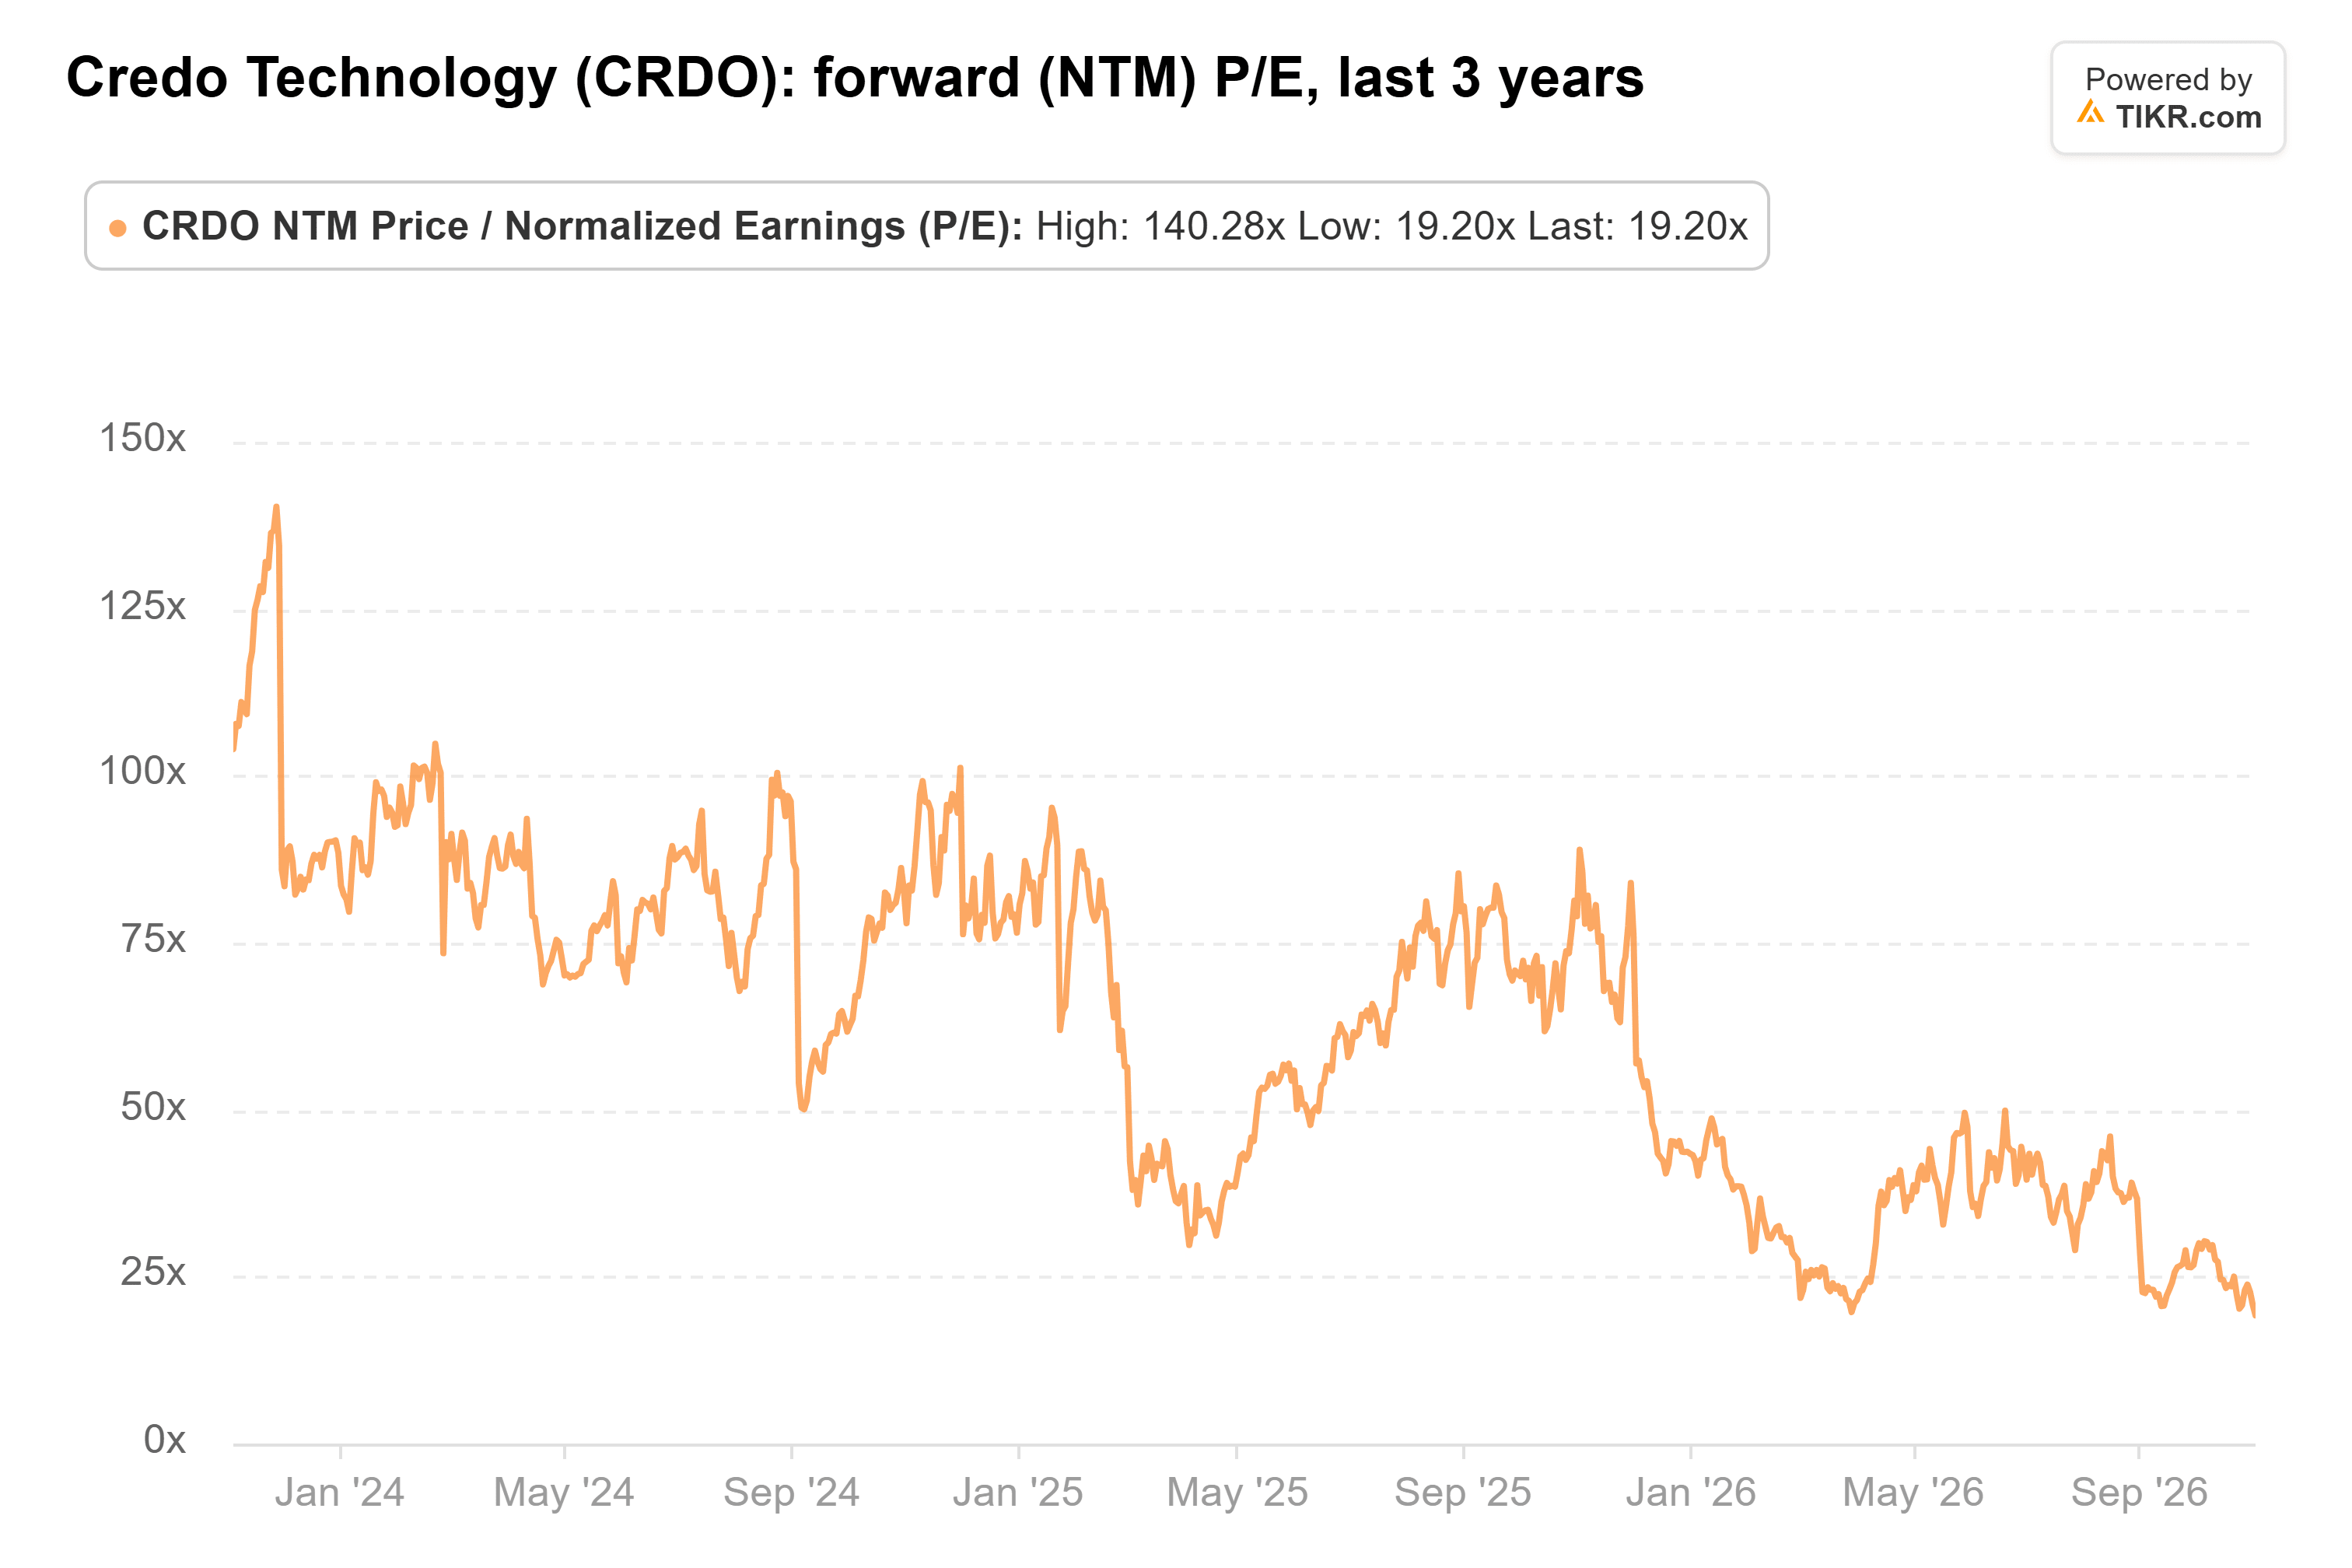
Even after the Nov. 6 bounce, it’s under 17x. The average analyst target of $284 is more than twice the stock’s price:
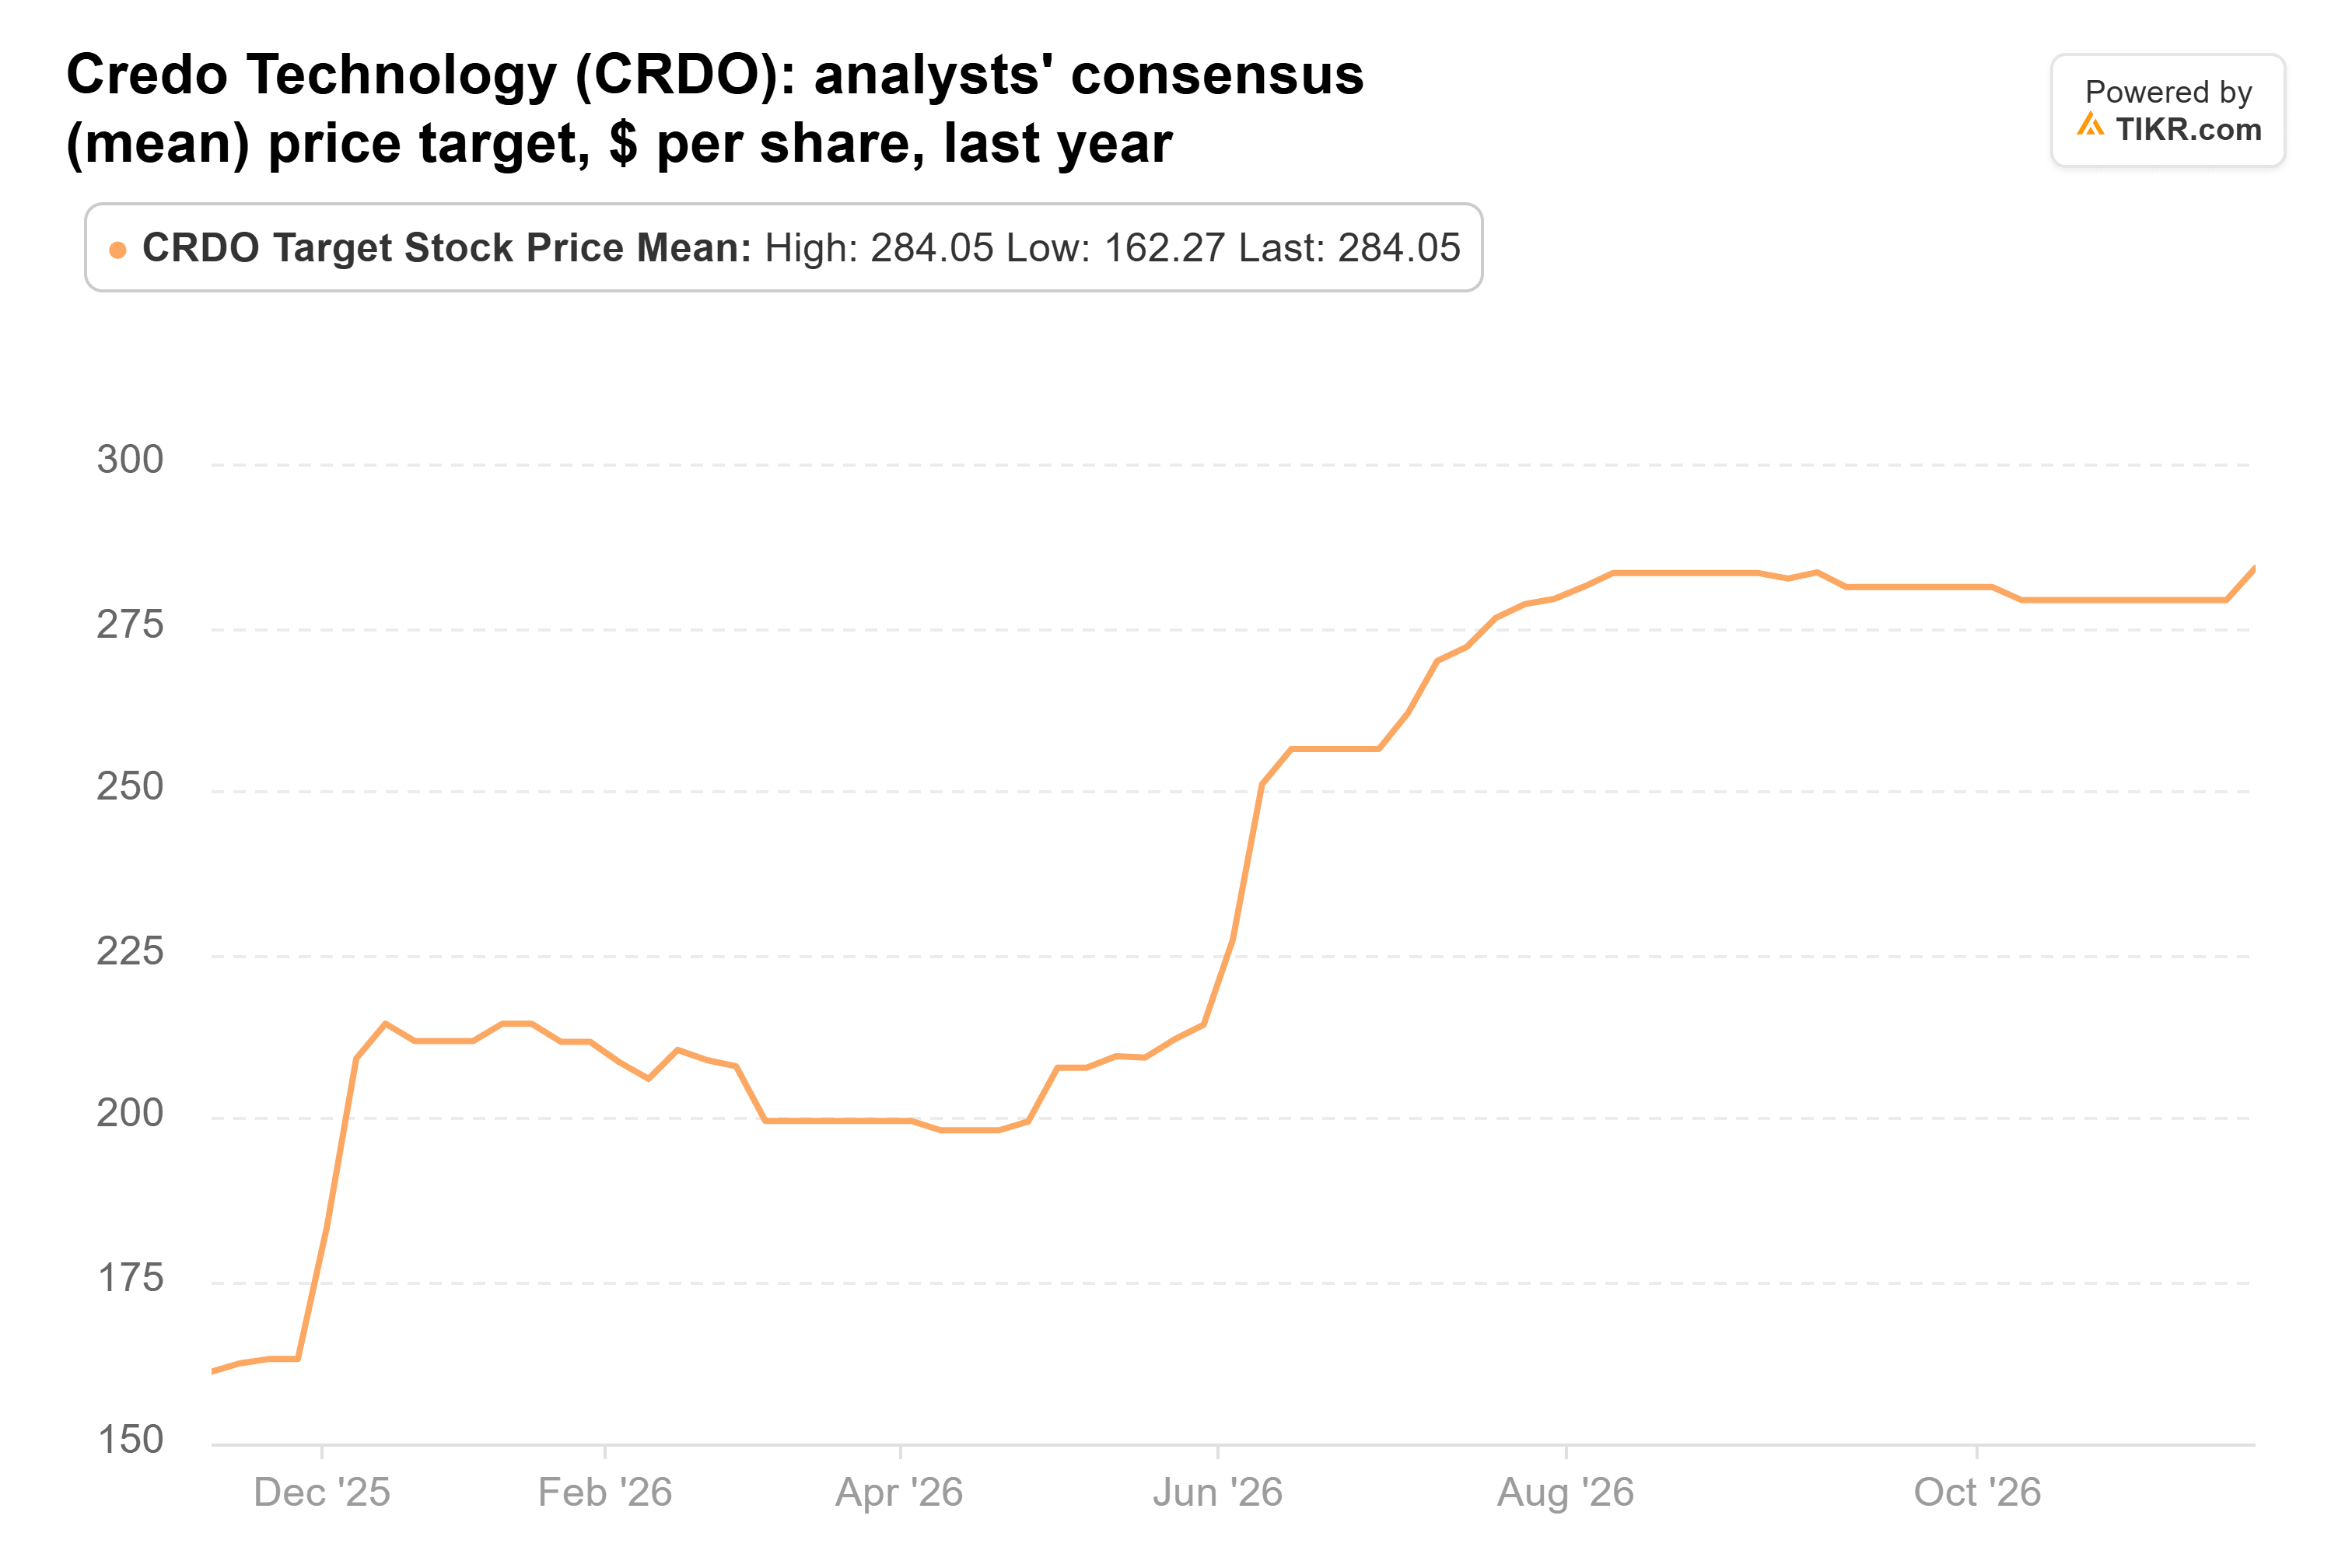
Data-center limits could slow Credo’s buyers, and MaxLinear is going after Credo’s share of next-generation cables. Still, Credo’s business looks the same as it did before the selloff. At under 17x forward earnings, the case for loading up looks stronger than the case for selling.
The early-December report will show whether any of this reached Credo’s customers: watch whether management still guides fiscal 2027 growth above 85%.
So what is Credo stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Credo could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!