Key Takeaways
- Costco shares rose 1.6% Friday to $1,012 and are up 19% in 2026, as September net sales climbed 13% to $30.02 billion.
- Fiscal Q4 EPS of $6.75 included a $0.15 one-time benefit from $184 million of tariff refunds, most of which Costco reinvested into lower prices.
- Membership fee income growth slowed to 7.3% in Q4, and the stock trades at 44.4x forward earnings with only 5.5% upside to the Street’s target.
- The November 4 October sales report and December 10 Q1 results will show whether comps stay in double digits.
Costco Wholesale (COST) got a windfall and handed most of it back to shoppers. That’s about as Costco as it gets.
The warehouse club collected $184 million in tariff refunds in its fiscal fourth quarter and used most of it to cut prices on produce, meat, beverages, home furnishings and hardware. Walmart (WMT) has said it will use billions of dollars in its own refunds to keep prices low, so the value fight just got fresh ammunition.
CEO Ron Vachris said Costco reinvested the money “to give value back to our members.”
Investors like the approach. Shares closed Friday at $1,012, up 1.6% on the day and 19% this year.
Refunds flattered a strong quarter
Fiscal fourth-quarter results were solid before any help:
- Net sales rose 11.2% to $93.9 billion.
- EPS of $6.75 beat estimates and rose 15%, including a $0.15 one-time refund benefit.
- Digitally enabled comparable sales jumped 19.5%.
Excluding the refund, EPS still grew 12.4%. September kept the pace going, with net sales up 13% to $30.02 billion and total comps up 11.4%.
U.S. comps ran 12.5%, or 8% excluding gas and currency, so fuel is doing real work. “Our gas business has had a record year,” Vachris said on the call.
Strip out the noise, and earnings keep compounding at a steady clip:
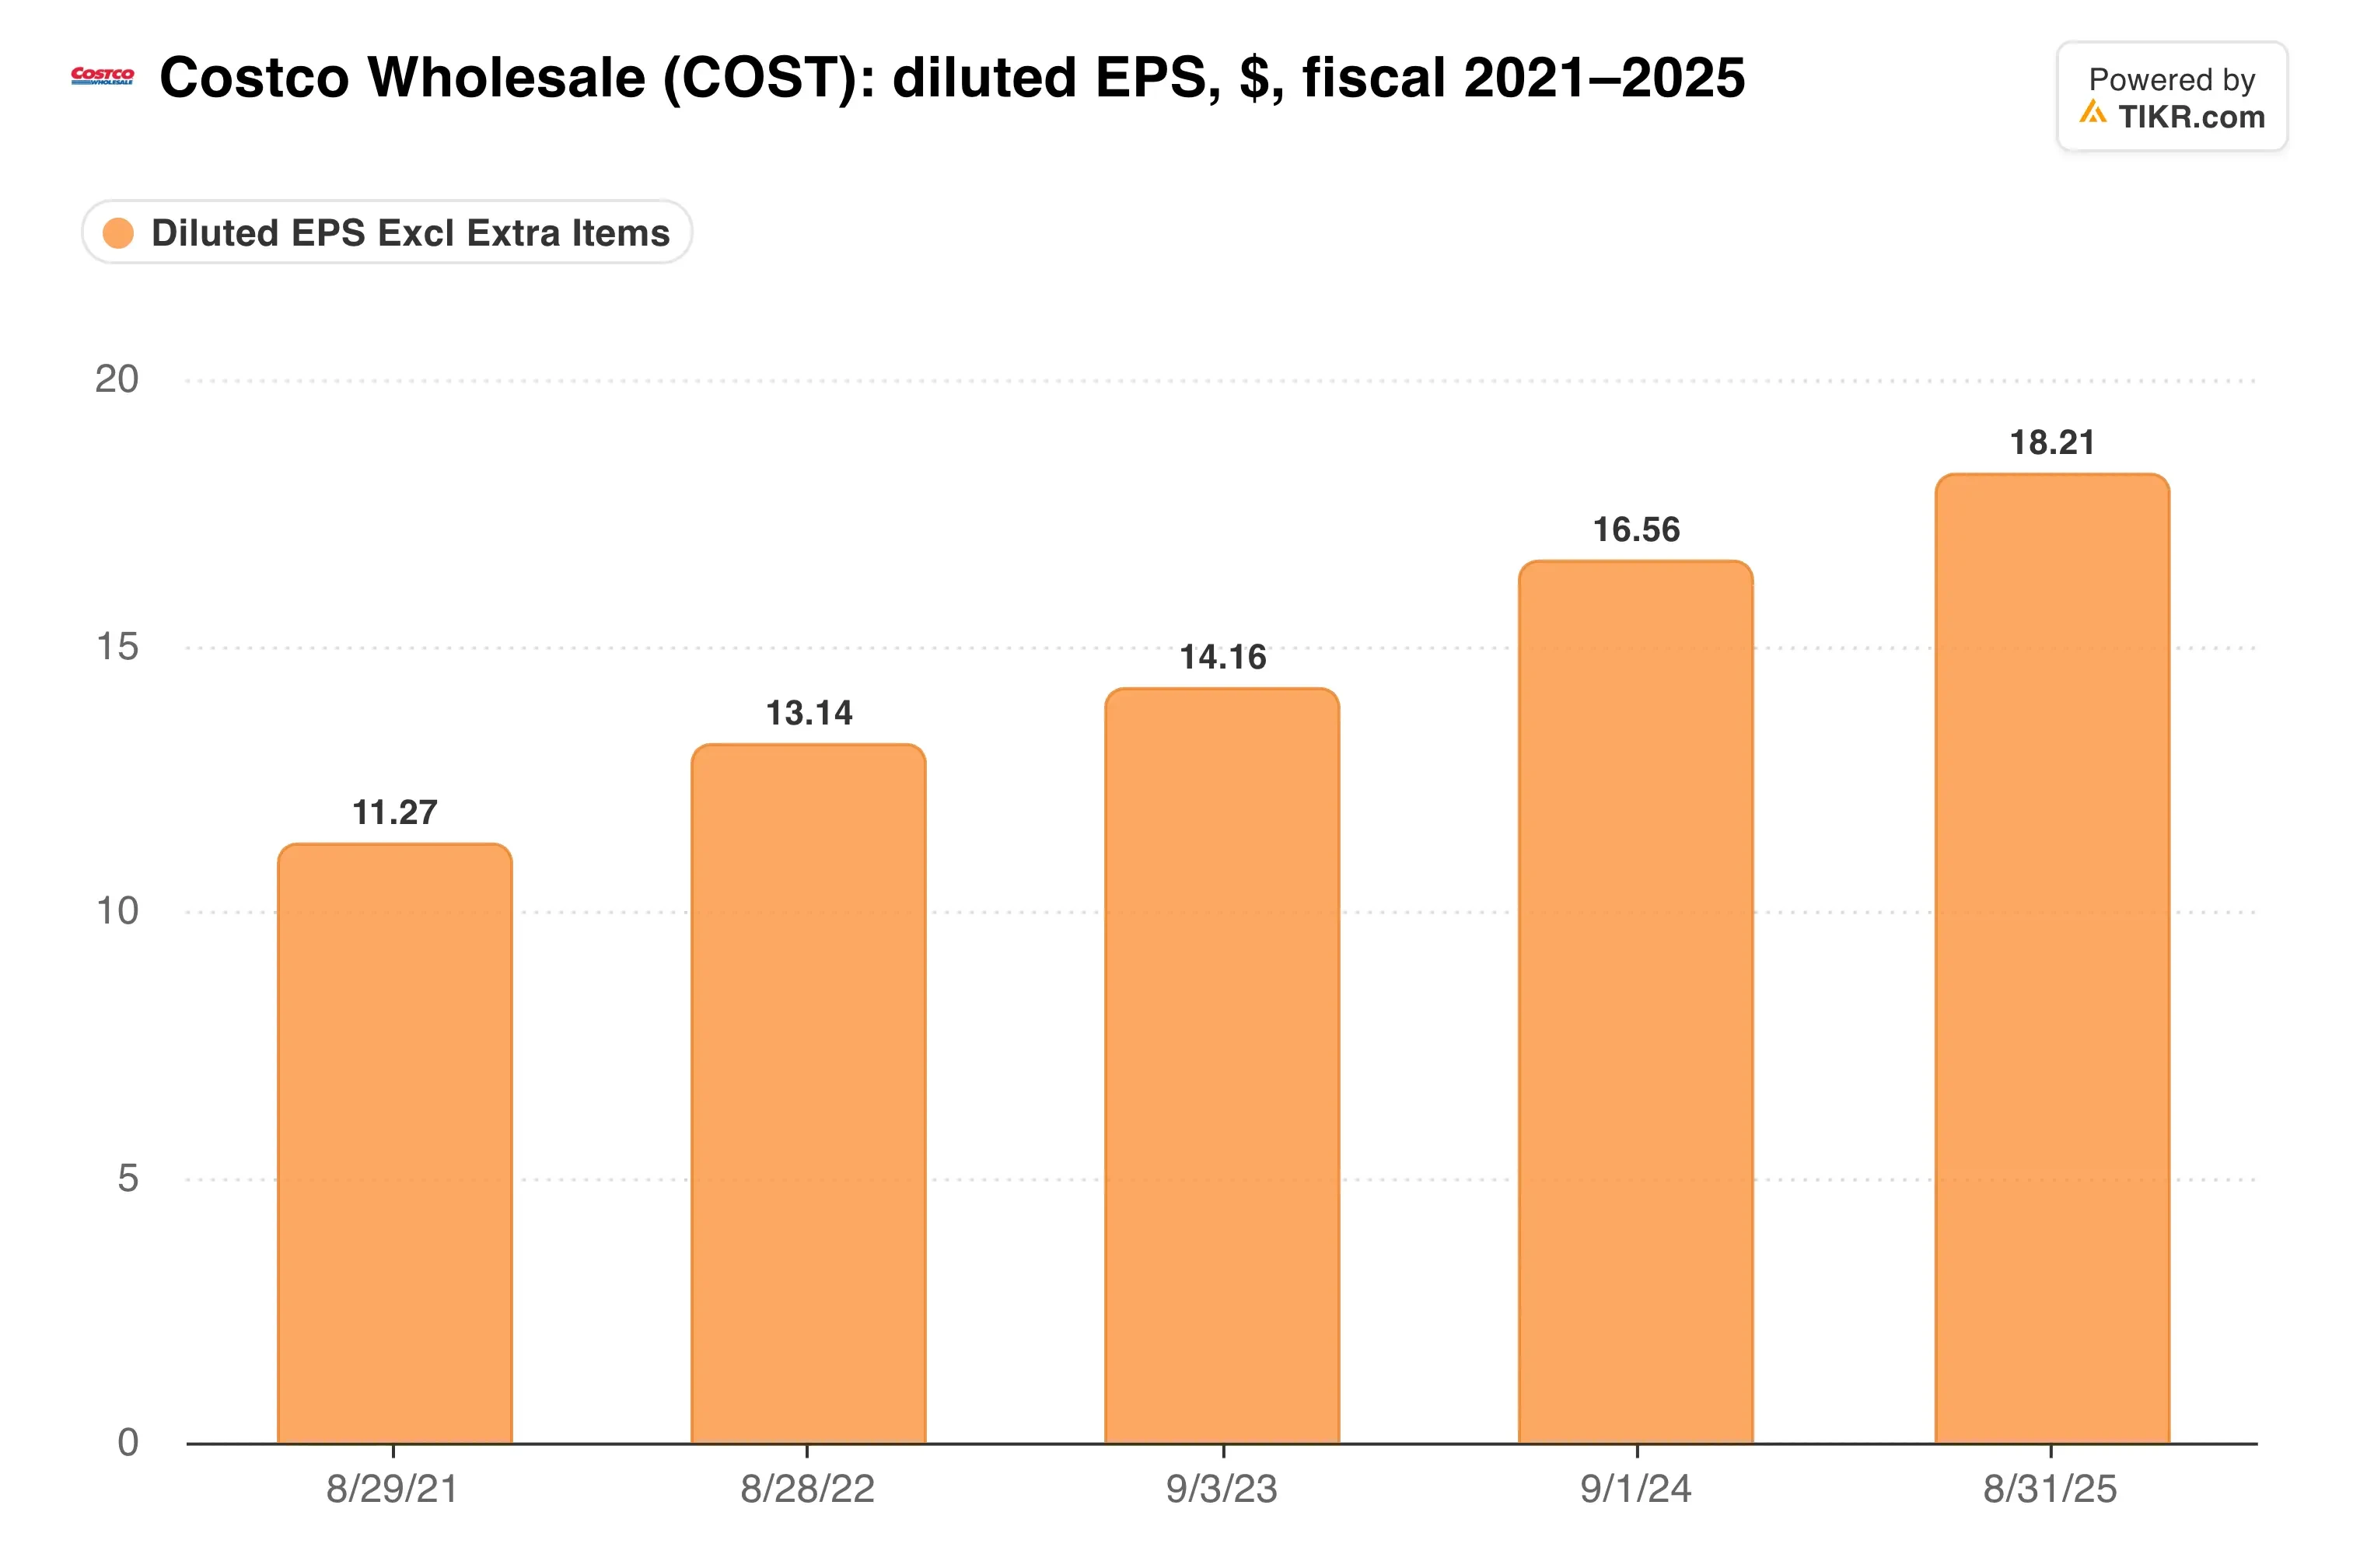
Fiscal 2026 diluted EPS reached $20.76, up from $18.21.
The fee engine is cooling
Membership fees are where Costco makes its real money. They totaled $5.9 billion in fiscal 2026, about half of the $11.7 billion operating profit.
That line is slowing. Fourth-quarter fee income rose 7.3% to $1.85 billion, versus 11% for the full year, as the 2024 fee increase laps. Underneath, the base looks healthy: paid executive members grew 9.4% to 42.3 million, and the U.S. and Canada renewal rate ticked up to 92.3%.
Growth will lean more on new buildings. Costco ended the year with 939 warehouses and plans 33 more in fiscal 2027.
Where does the price reinvestment show up? In a gross margin Costco keeps thin on purpose…
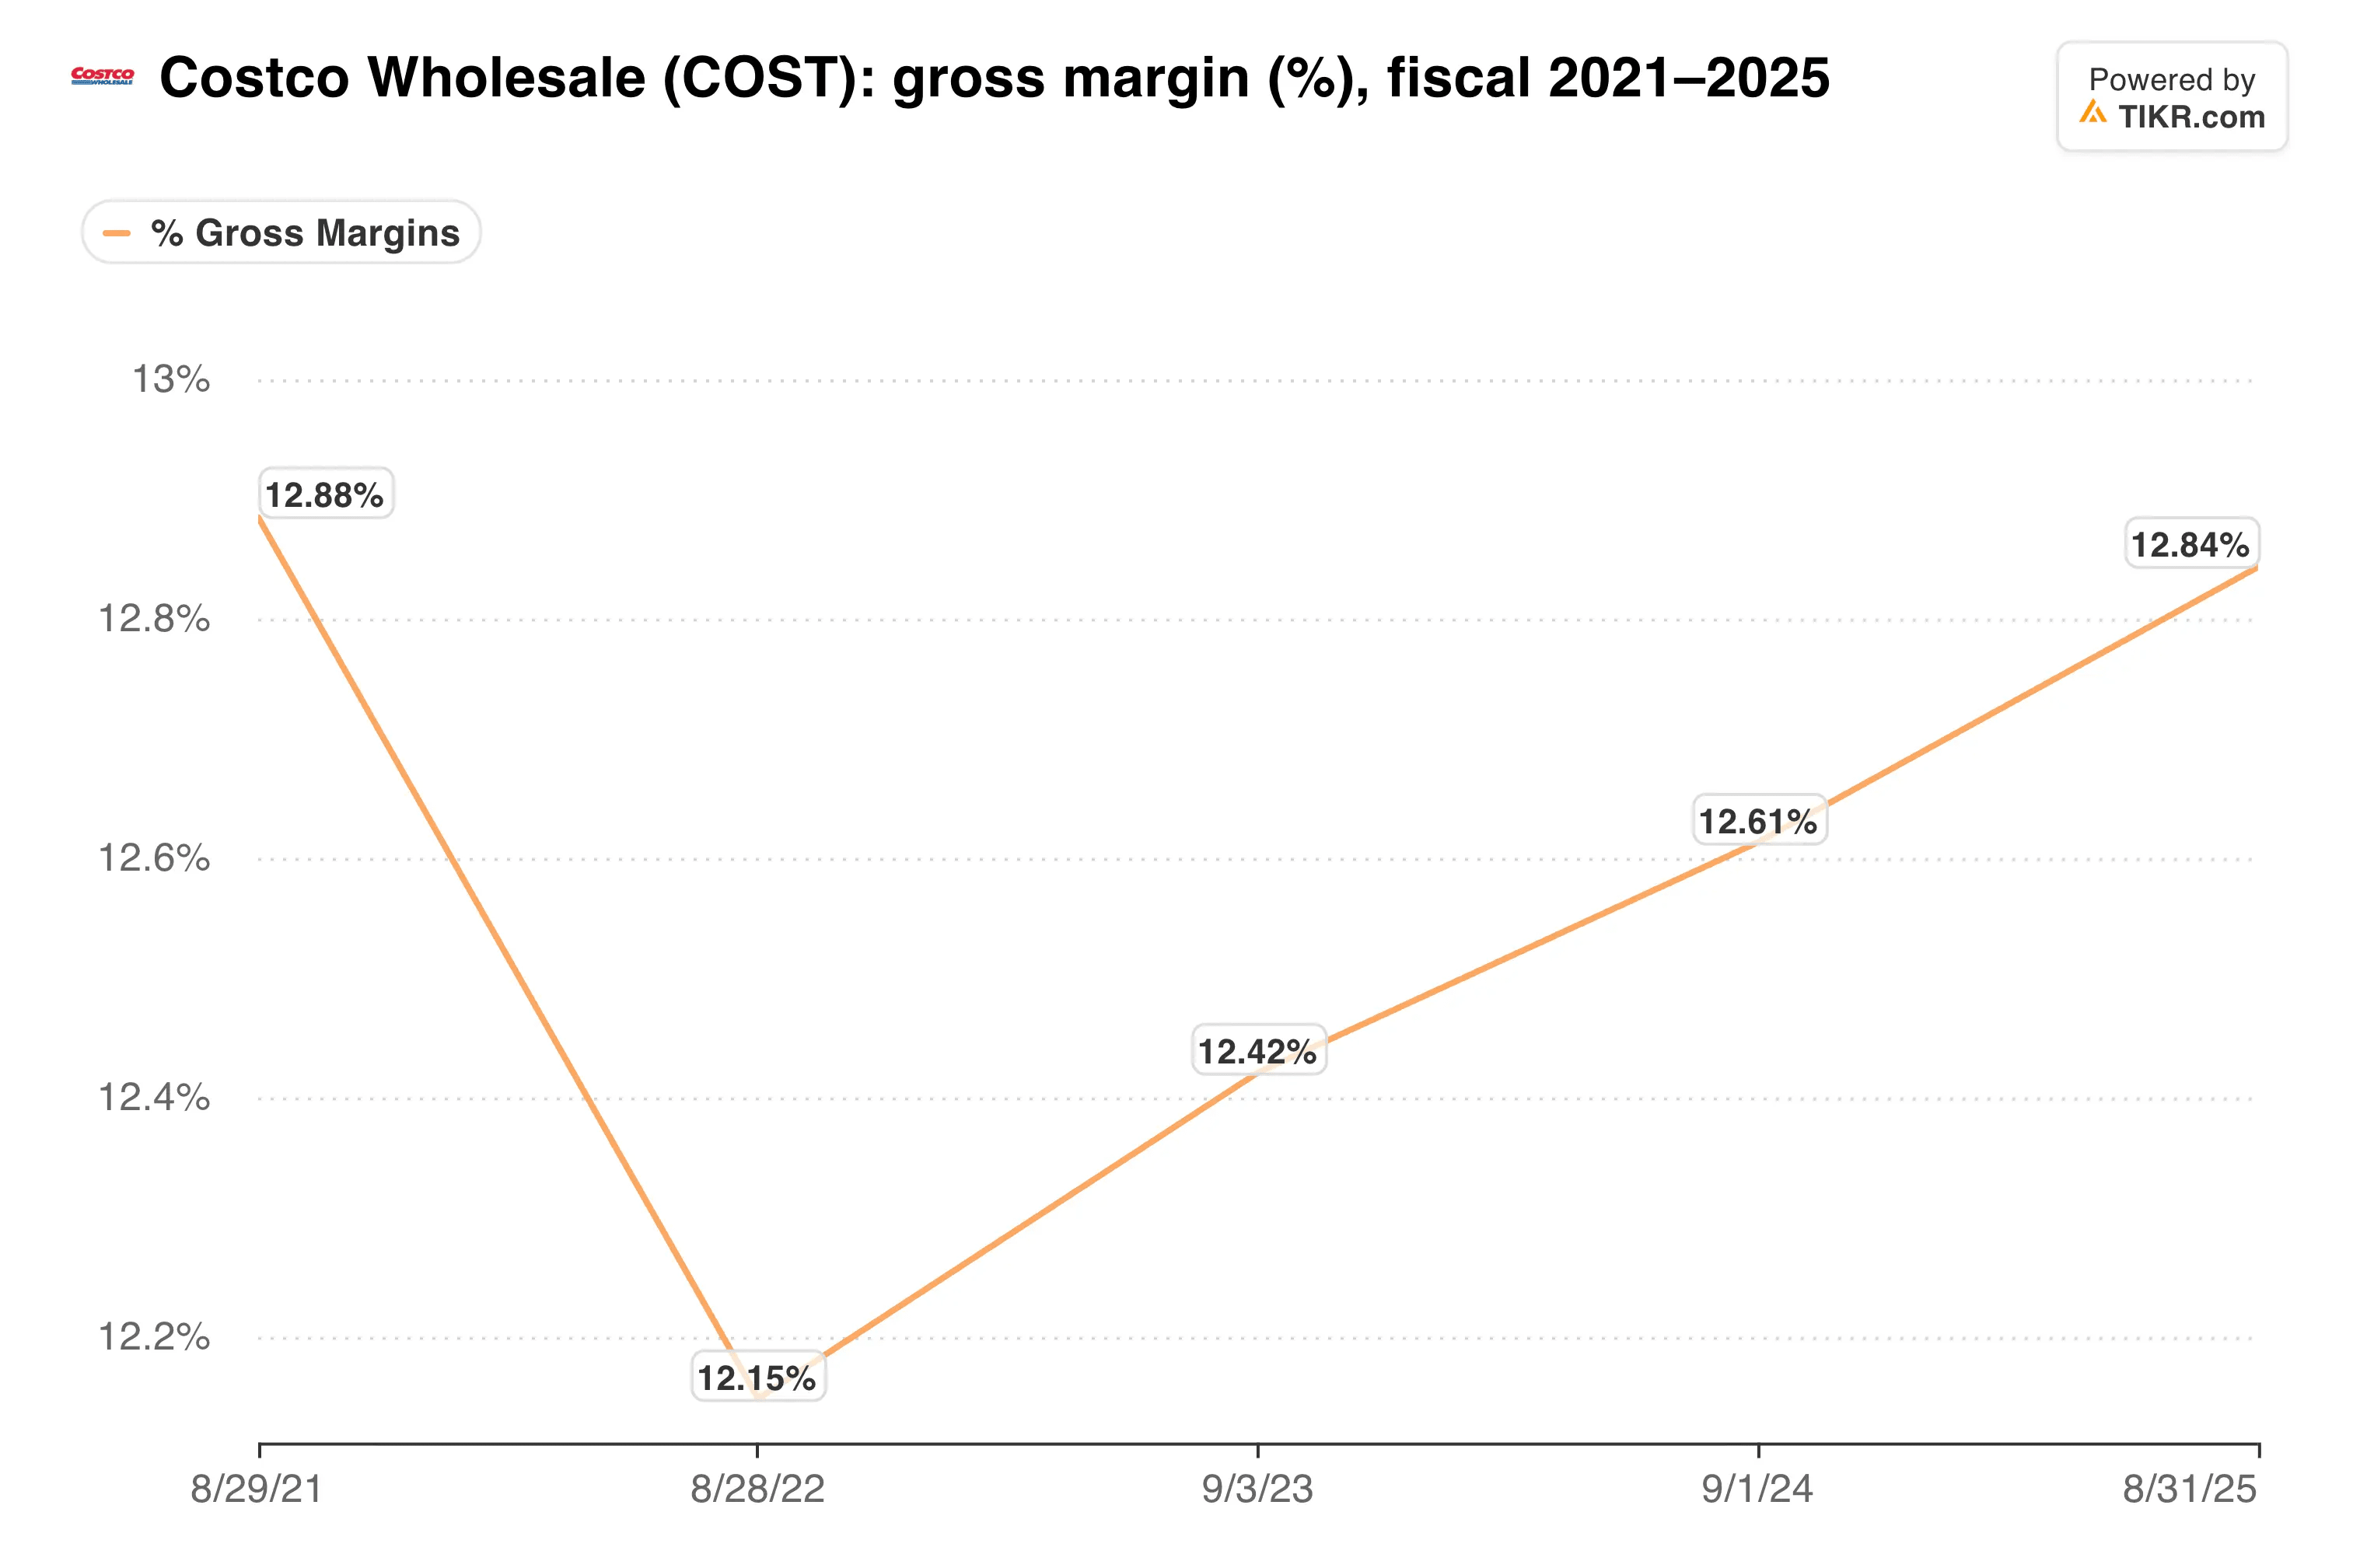
Fourth-quarter gross margin on net sales slipped about 0.1 point to 11.0%, which is what reinvesting refunds should look like.
TIKR tracks 40 analysts on Costco. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Costco, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Costco’s Analyst Ratings
Paying 44 times for consistency
The valuation is the catch. Costco trades at 44.4x forward earnings and nearly 60x forward free cash flow. The Street’s $1,068 average target implies just 5.5% upside, while shares sit about 8% below their $1,097 high.
The refund boost is also temporary. The fourth-quarter haul was a little over a third of what Costco expects in total, and management plans to keep reinvesting most of it. Meanwhile, four class actions filed in March seek to claim the IEEPA refunds Costco receives.
How does the multiple compare with its biggest rival?
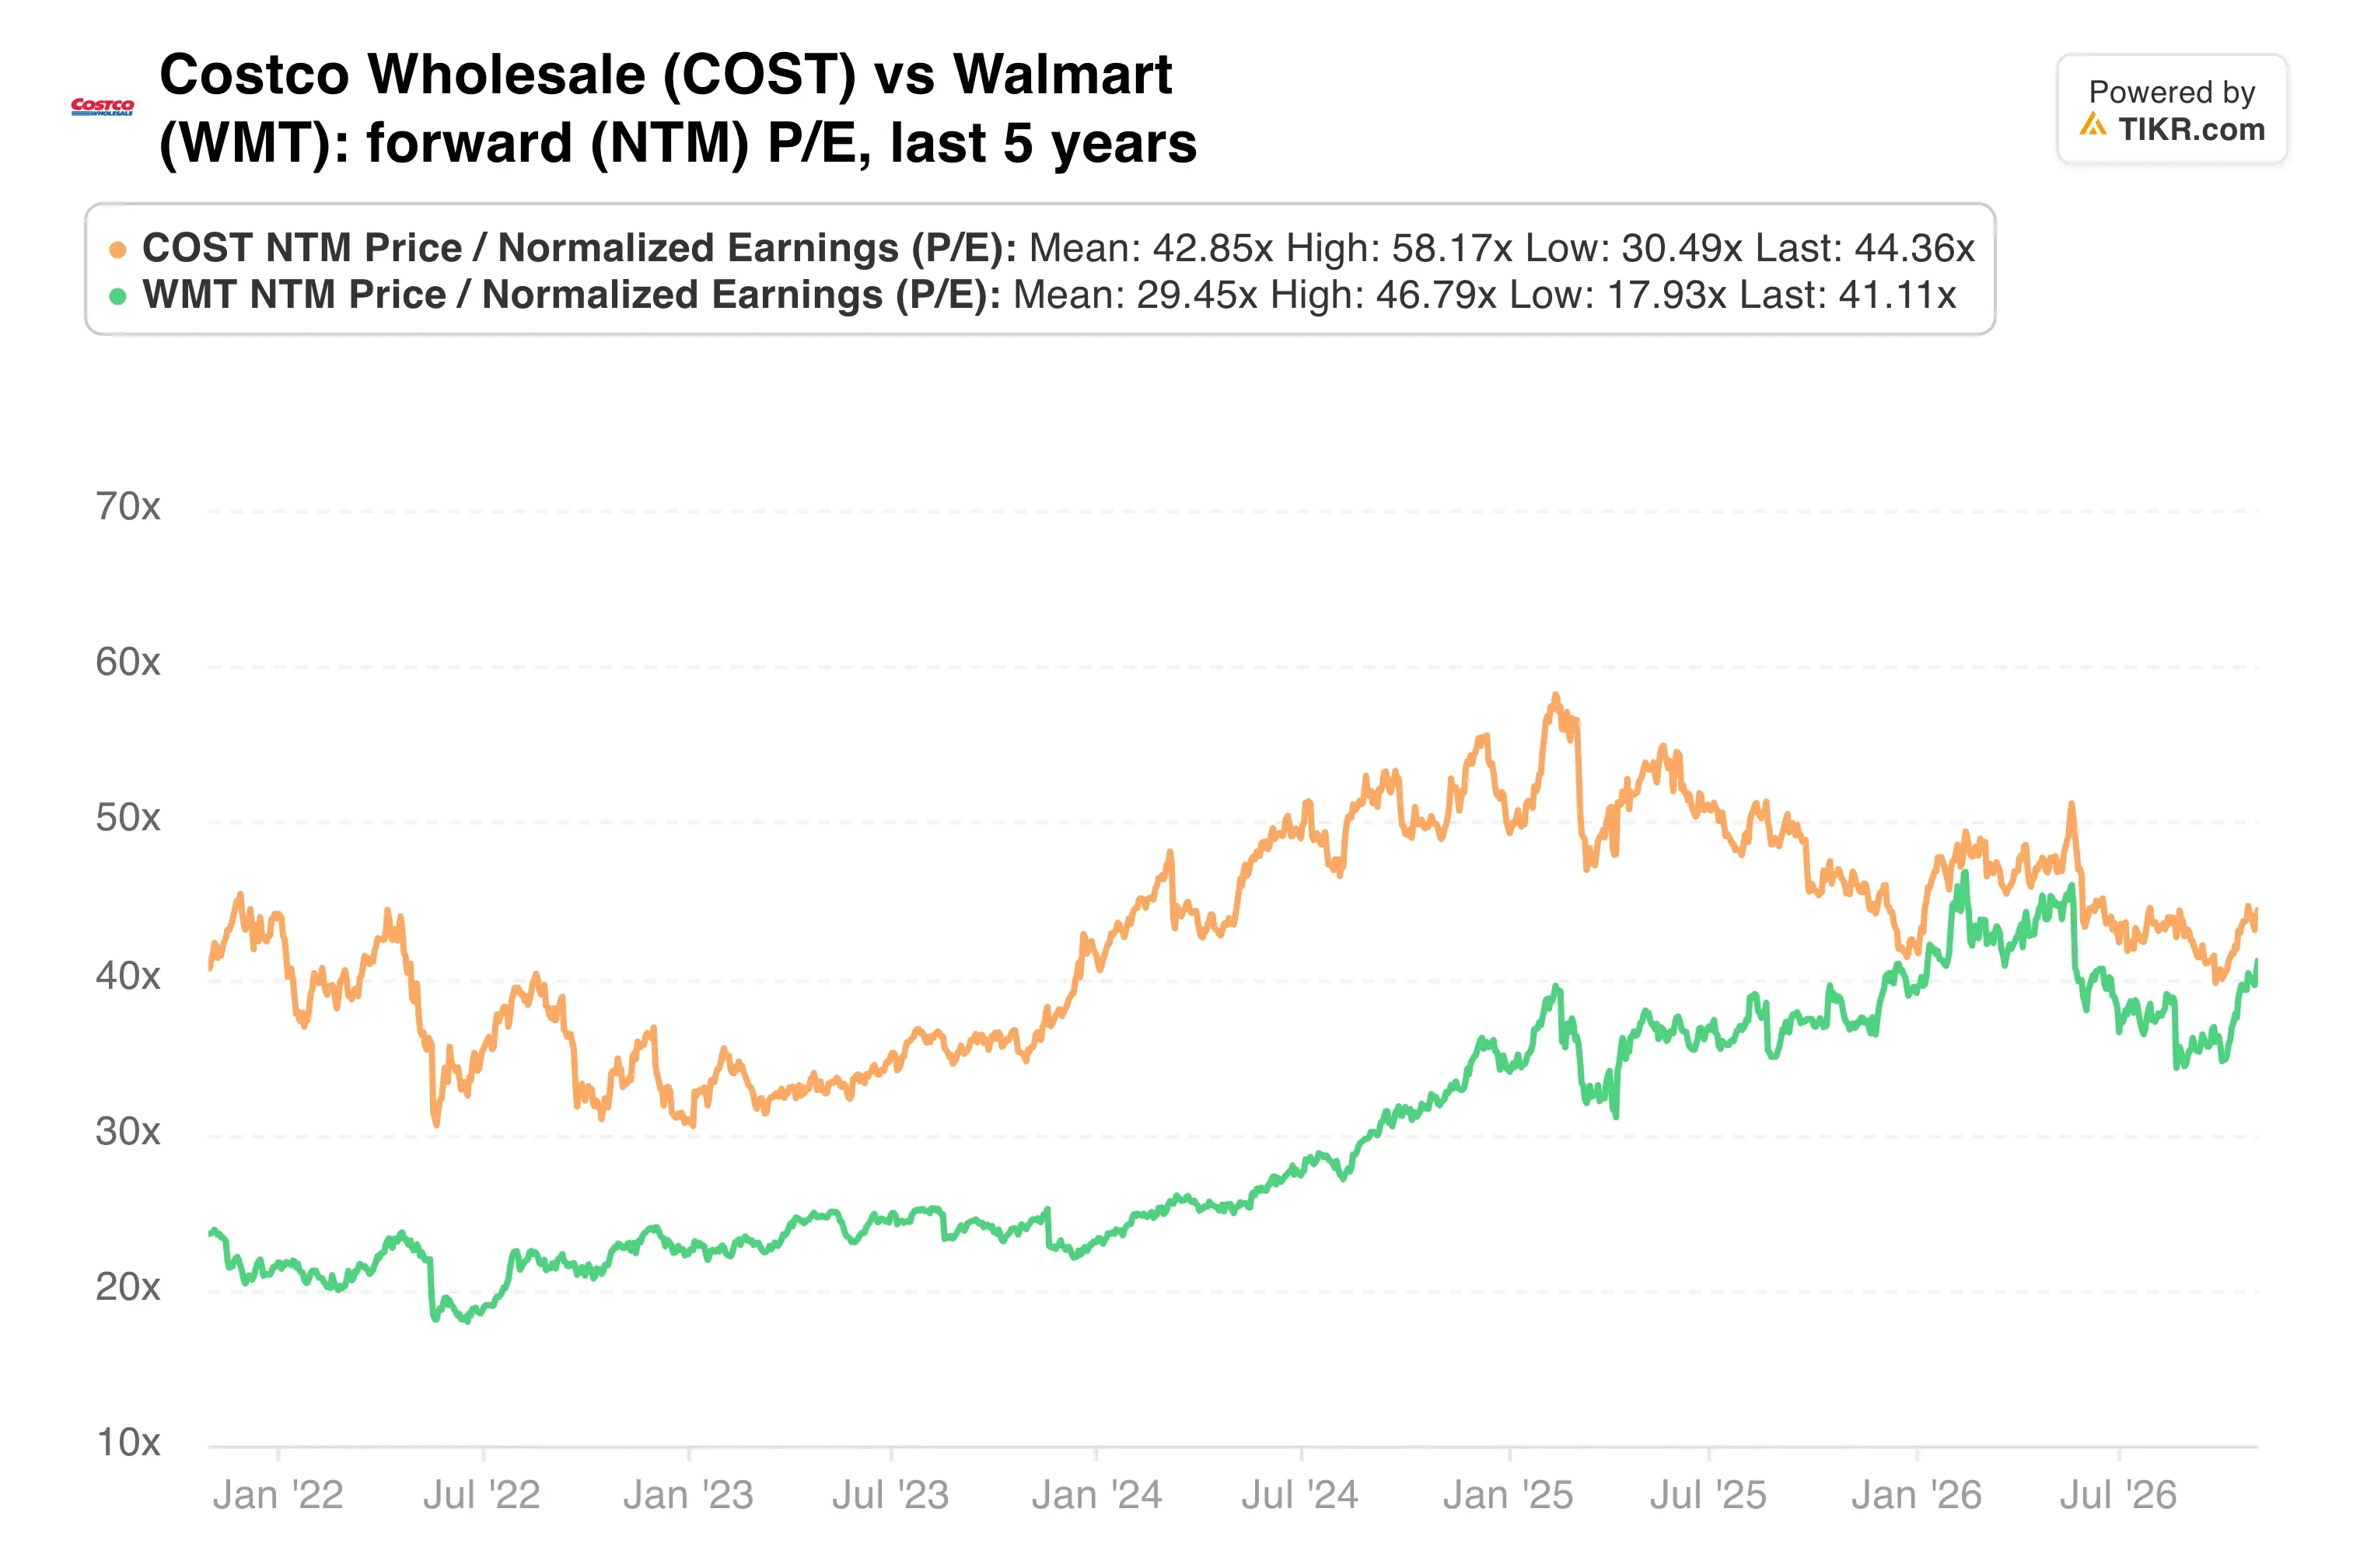
Costco has carried a premium to Walmart for years, and its fee income and steadier comps explain most of it.
My take: Reinvesting refunds into prices is the right long-term call, and it should keep renewal rates high. At 44x earnings, though, the stock already prices in years of this execution. I’d own it, but I’d buy on pullbacks rather than at $1,012.
The next checkpoints come quickly. October sales arrive November 4 and will show whether comps stay in double digits. Fiscal first-quarter results follow December 10, with a first look at how much refund benefit is left.
So what is Costco stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Costco could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!