Key Takeaways
- CoStar Group shares fell 14% today after third-quarter net new bookings came in at $37 million, down from $84 million a year earlier.
- CoStar’s record profit came from holding costs down while revenue grew, but the sales engine that drives future revenue is slowing.
- Management’s guidance points to about 10% revenue growth in the fourth quarter, and its raised 2026 revenue range is still below Wall Street’s estimate.
- The stock trades near its lowest forward P/E in five years, and bookings in the fourth-quarter report are the number to watch.
CoStar Group (CSGP) posted record adjusted EBITDA after Tuesday’s close, and the stock is down 14% today anyway.
The problem is bookings. As founder and CEO Andy Florance put it on CoStar’s third-quarter call, “Our annualized net new bookings were below our expectations, coming in at $37 million for the third quarter.”
That’s less than half the $84 million CoStar booked a year earlier.
What exactly happened
The rest of the quarter looked great:
- Revenue grew 14% to $952 million.
- Adjusted EBITDA doubled to $229 million, well above its $190 million to $210 million guidance.
- Adjusted EPS of $0.38 beat the $0.34 consensus, and the company raised its full-year EPS and EBITDA guidance.
But bookings turn into future revenue. Florance blamed the shortfall on economic headwinds and a sales force that’s growing more slowly than expected.
TIKR tracks 21 analysts on CoStar Group. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CoStar Group, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CoStar Group’s Analyst Ratings
The cost cuts are working
Revenue grew 14% while total costs fell 2%, so nearly all the new revenue went straight to profit. And CoStar has found at least $200 million more in savings for the next 12 to 18 months, which Florance says will “improve efficiency without sacrificing revenue growth.”
I’m not sure the revenue outlook backs that up. CoStar’s raised 2026 range of $3.75 billion to $3.77 billion is still below Wall Street’s $3.79 billion, and its fourth-quarter guidance points to about 10% growth. Analysts expect growth to slow further from there…

That’s about 10% growth in 2027 and 7% in 2028. And $37 million of bookings gives analysts little reason to raise those estimates.
Priced like a slower grower
Coming into today, CoStar traded at 19x forward earnings, against a five-year average of 66x…
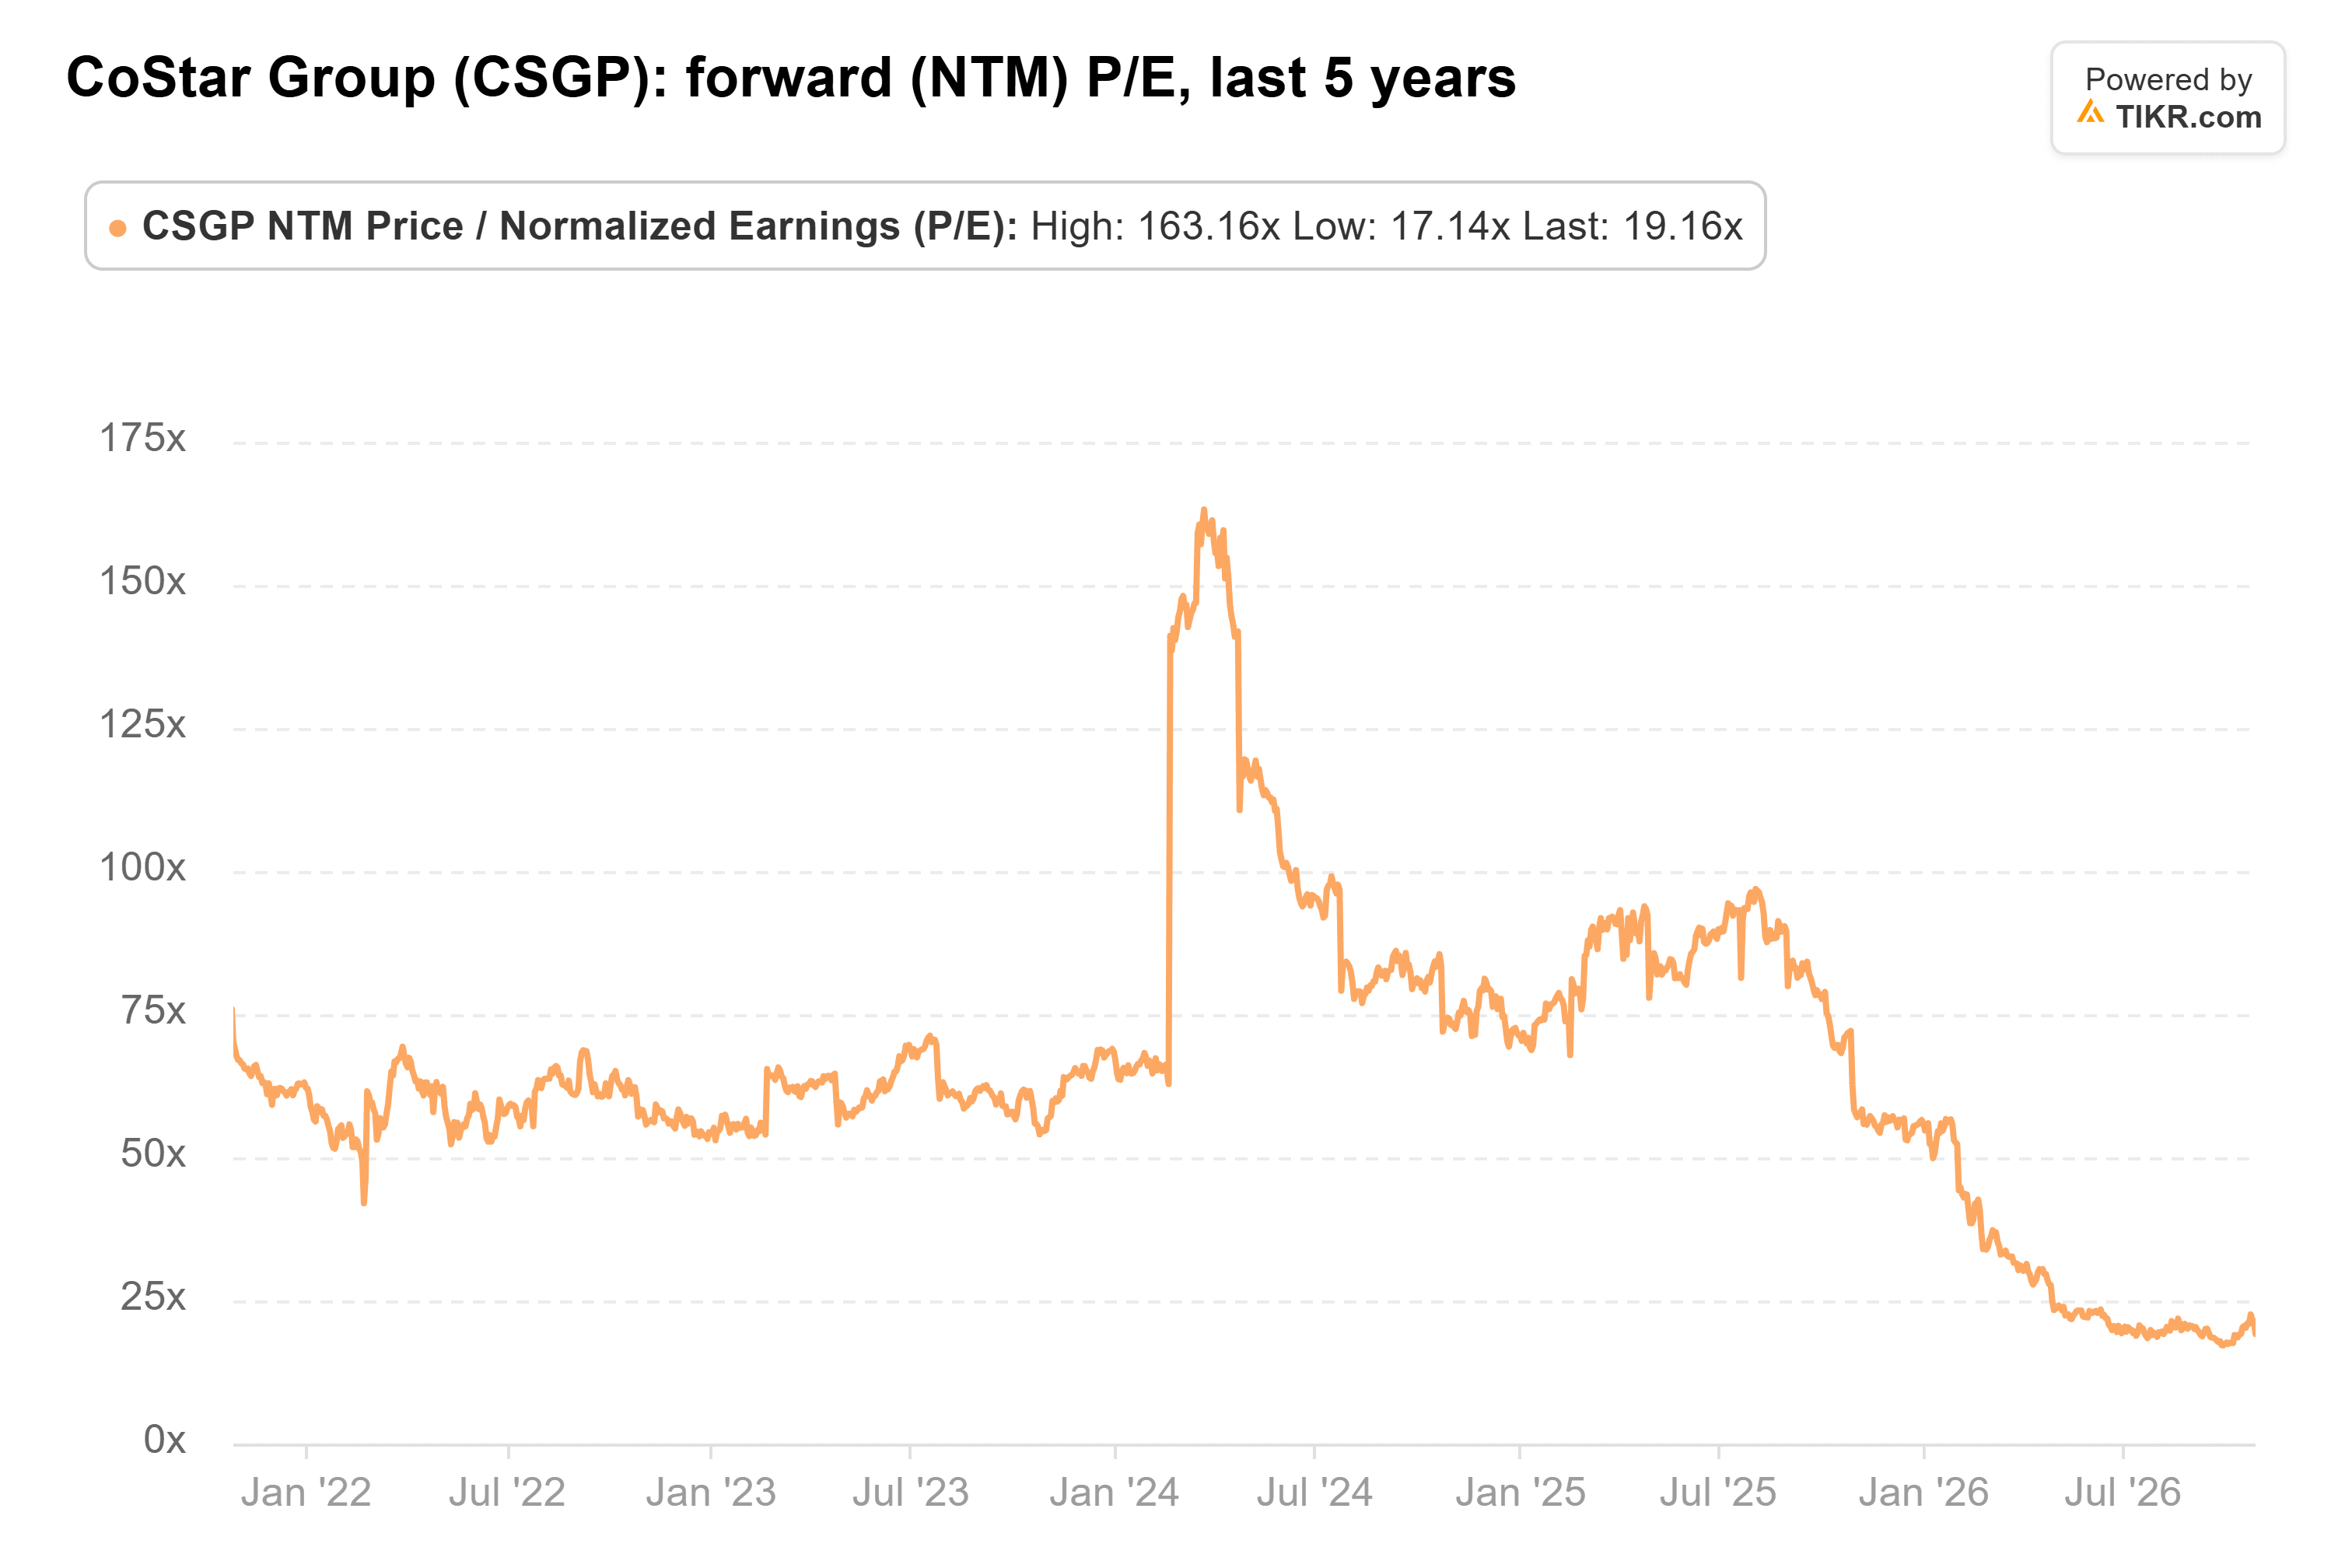
After today’s drop, it’s back near September’s five-year low of 17x. Five firms cut their price targets this morning, including BTIG, which pointed to CoStar’s fifth bookings miss.
Plus, CoStar is paying about $730 million for Vexcel, an aerial imagery company. It’s using its cash ($500 million at the end of September) and its credit line.
My take: The cost cuts are real. But even with another $200 million of savings, CoStar is still about $200 million short of its $1.25 billion adjusted EBITDA target for 2028, and that has to come from sales. Until bookings turn, I think the stock stays cheap for good reason.
Of course, management said on the call that it expects bookings to improve in the fourth quarter. That report, due early next year, is the one to watch.
So what is CoStar stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CoStar could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!