

Key Takeaways
- Comfort Systems shares fell 11% today after the company reported a third quarter that beat estimates and, minutes earlier, said co-founder and CFO Bill George will retire.
- The CFO handoff to a long-time insider looks orderly, and the selloff looks like an overreaction.
- Revenue rose 54% to $3.77 billion, and backlog almost doubled from a year earlier to $17.81 billion.
- The stock traded at 23x forward earnings at Thursday’s close, below its five-year average of 26x, and today’s call is the next test.
Comfort Systems USA (FIX) sank 11% this morning, after a third-quarter report that beat Wall Street’s estimates on revenue and earnings.
And here’s why: Five minutes before the results came out after Thursday’s close, the company said co-founder and CFO Bill George will retire.
The quarter was huge
Compared with the same quarter last year:
- Revenue rose 54% to $3.77 billion, against a $3.40 billion consensus.
- Diluted EPS climbed 69% to $13.91, against $12.85 expected.
- Backlog reached $17.81 billion, up $3.8 billion since June and up from $9.38 billion a year ago.
- Operating cash flow topped $1 billion, up from $553 million, and the board raised the quarterly dividend 11% to $1.00 a share.
CEO Brian Lane’s explanation for the backlog: “Relentless demand, together with our competence and reputation.”
TIKR tracks 10 analysts on Comfort Systems USA. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Comfort Systems USA, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Comfort Systems USA’s Analyst Ratings
Two concerns
George helped found Comfort Systems in 1997 and has been CFO since 2005, so investors are losing a familiar face. But he stays until the company files its 2026 annual report. His successor, Julie Shaeff, has been chief accounting officer since 2005 and joined the company in 1999.
The other worry is that management didn’t put numbers on 2027. Lane did say the company is “well-positioned to grow organically, and to maintain high levels of profitability and solid ongoing cash flow” through year end and into 2027.
That matters, because analysts already expect revenue to climb from $9.10 billion in 2025 to $15.5 billion in 2027…

Those estimates came before Thursday’s report, and nothing in it argues for cutting them.
Cheaper than usual
The selloff has also left the stock cheaper than it usually trades. At Thursday’s close, Comfort Systems was at 23x forward earnings. That’s below its five-year average of 26x and less than half its April peak of 47x…
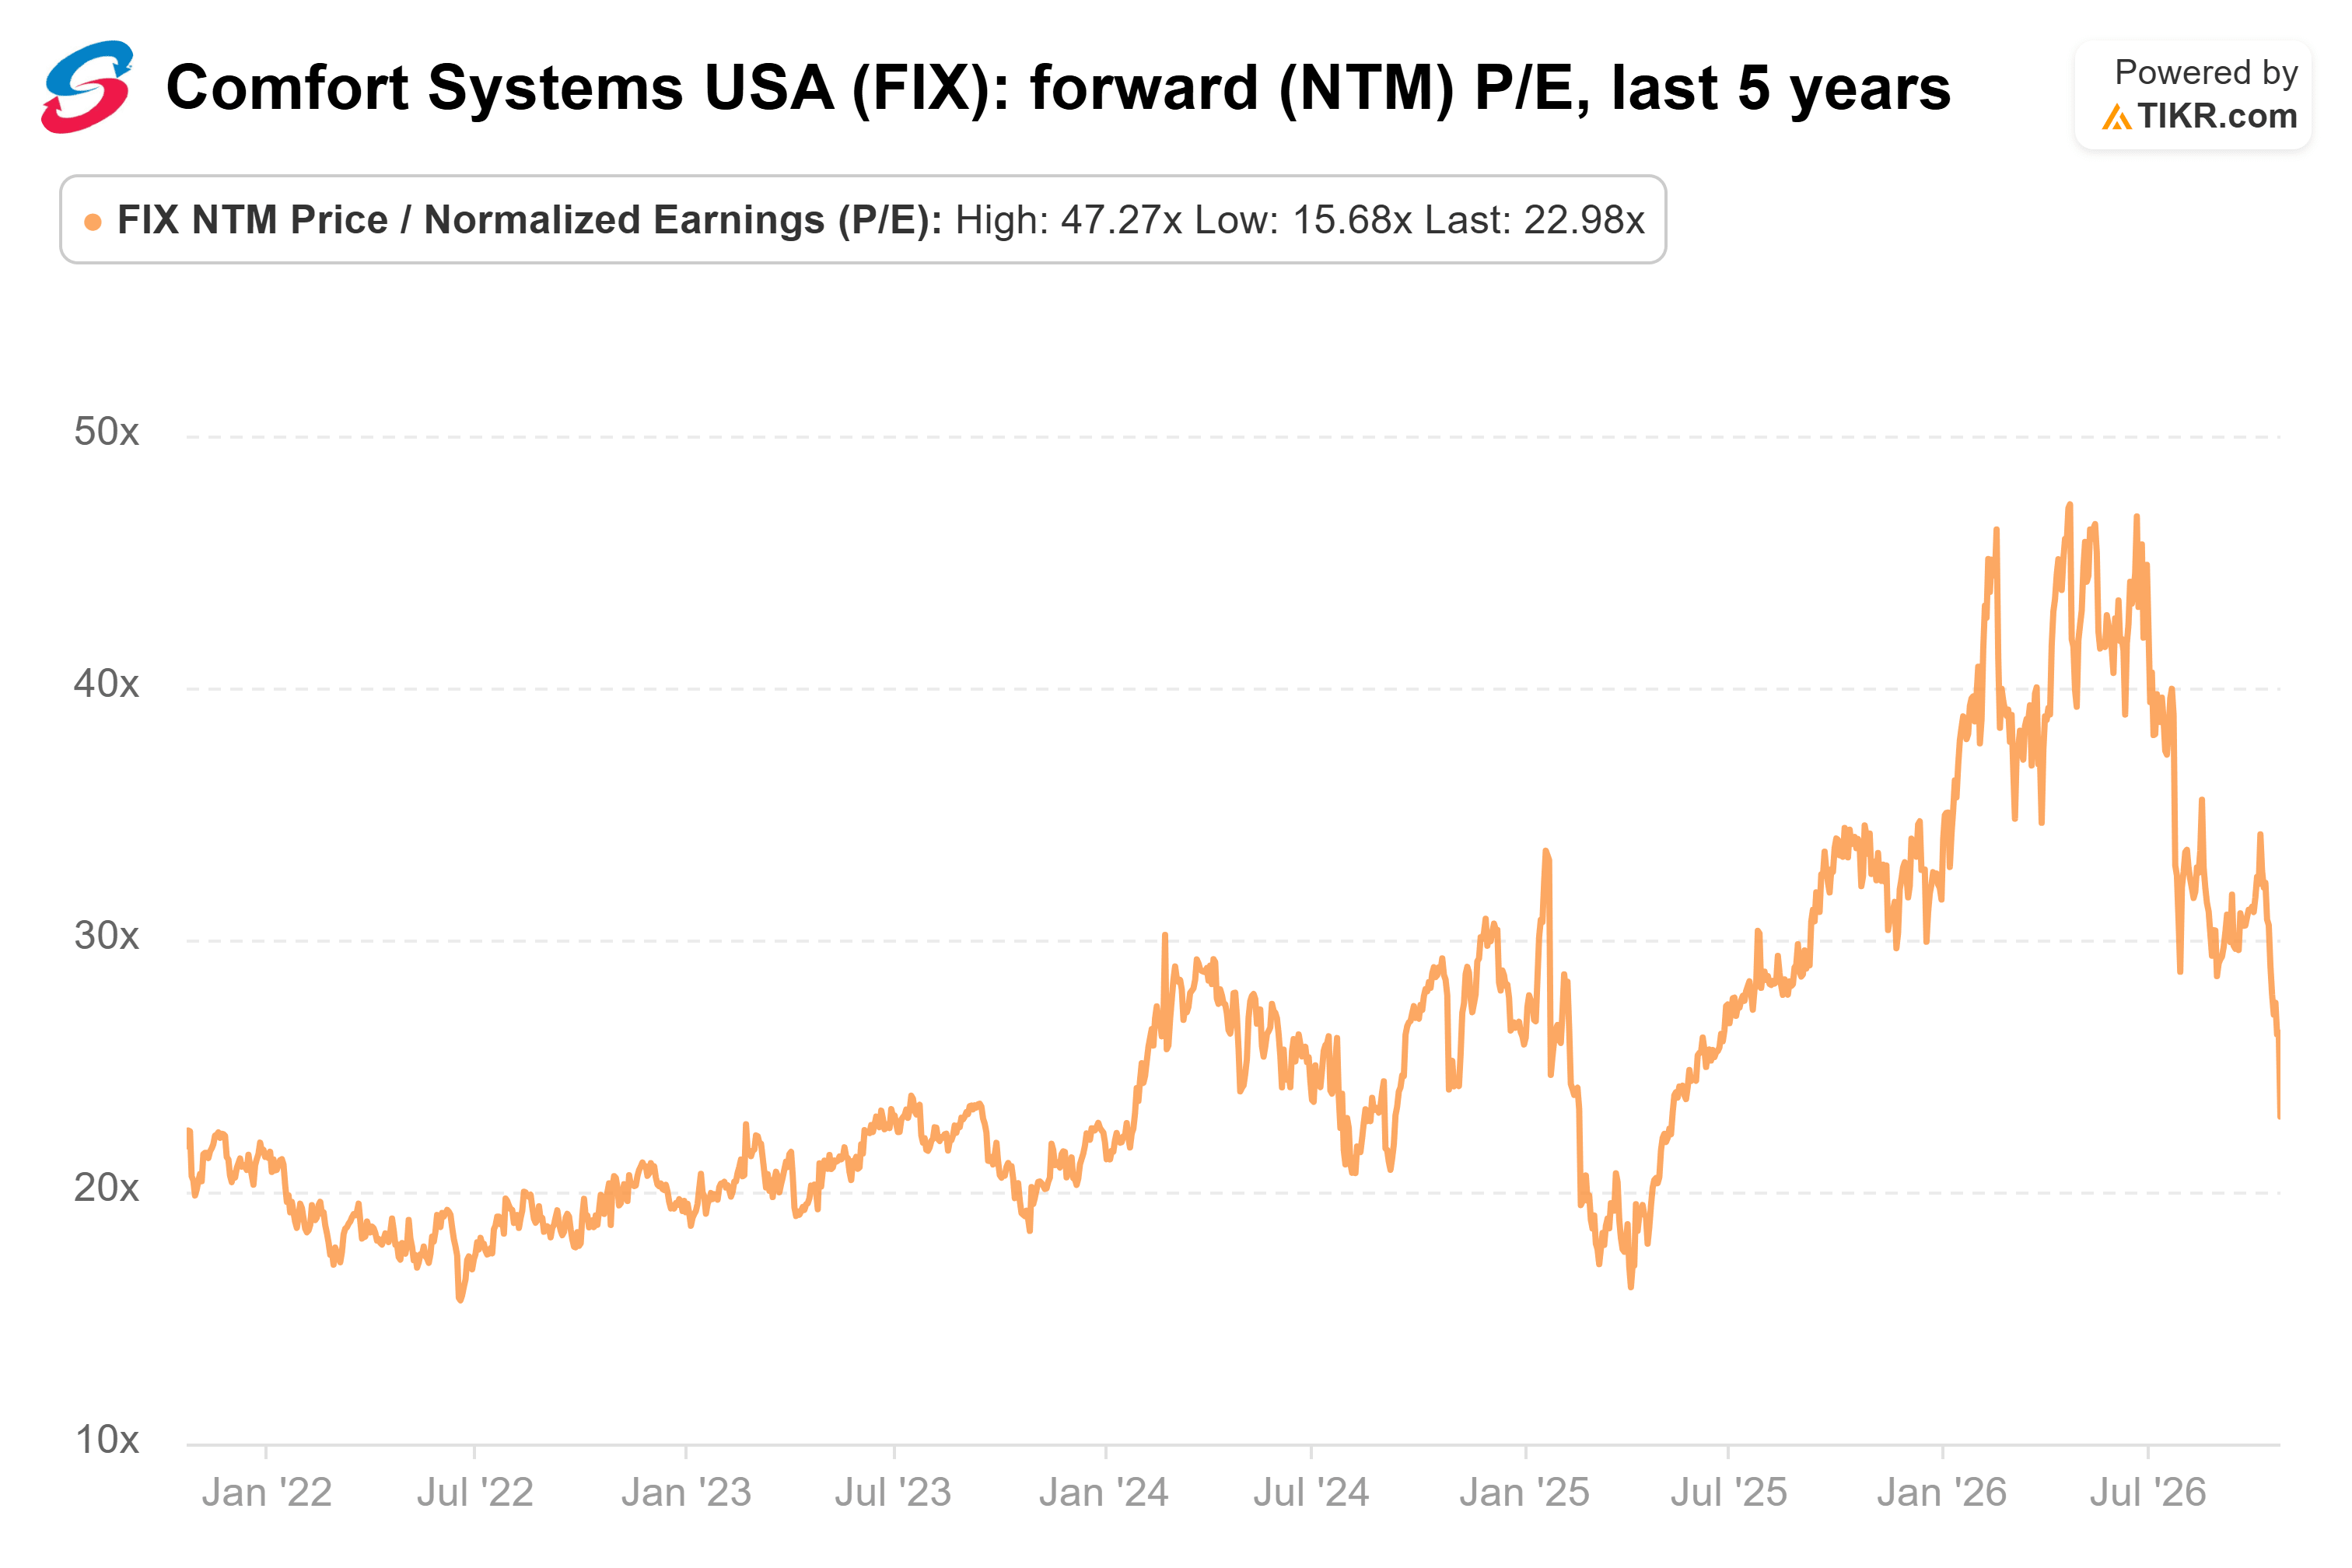
After today’s drop, it’s closer to 21x.
Today’s call is the next test
My take: investors are selling an orderly handoff. A business growing this fast, at a below-average multiple, looks like a buying opportunity to me.
Of course, today’s 11 a.m. ET conference call gives management a chance to talk about 2027. Any sign that new orders are slowing or margins are slipping would change that view.
So what is Comfort Systems stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Comfort Systems could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Comfort Systems for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


