Key Takeaways
- Steve Eisman says reckless mortgage lending inside banks is less of a risk than at any point in his career, and puts Citigroup’s leverage at 10 to 1, down from about 40 to 1.
- The past week’s scares came from technology: a JPMorgan outage and a Fed warning that AI agents could speed up bank runs.
- Citigroup trades at 1.2x tangible book against JPMorgan’s 2.9x, and higher returns could narrow that gap.
Steve Eisman made his name betting against the mortgages that sank the big banks in 2008. Now he says that danger is about as small as he’s ever seen it, and he used Citigroup (C) to show why. The timing is awkward: a software bug at JPMorgan Chase (JPM) disrupted services for hours on Nov. 16, and customers at Wells Fargo (WFC) and other banks reported problems.
On a Nov. 18 episode of The Real Eisman Playbook, Eisman said leverage “came down fast” after Dodd-Frank: “A bank like Citigroup went from something like 40 to 1 leverage before the crisis to 10 to 1.” On “reckless mortgage underwriting hidden inside the regulated banking system,” he didn’t hedge: “I genuinely tell you it’s safer today than at any point in my career.”
The Loan Books Are Holding Up
The credit numbers back him up. Citi now expects its 2026 U.S. card net credit loss rate around 4%, the low end of earlier guidance. Wells Fargo wrote off 0.38% of average loans (annualized) in the third quarter, below 0.40% a year earlier.
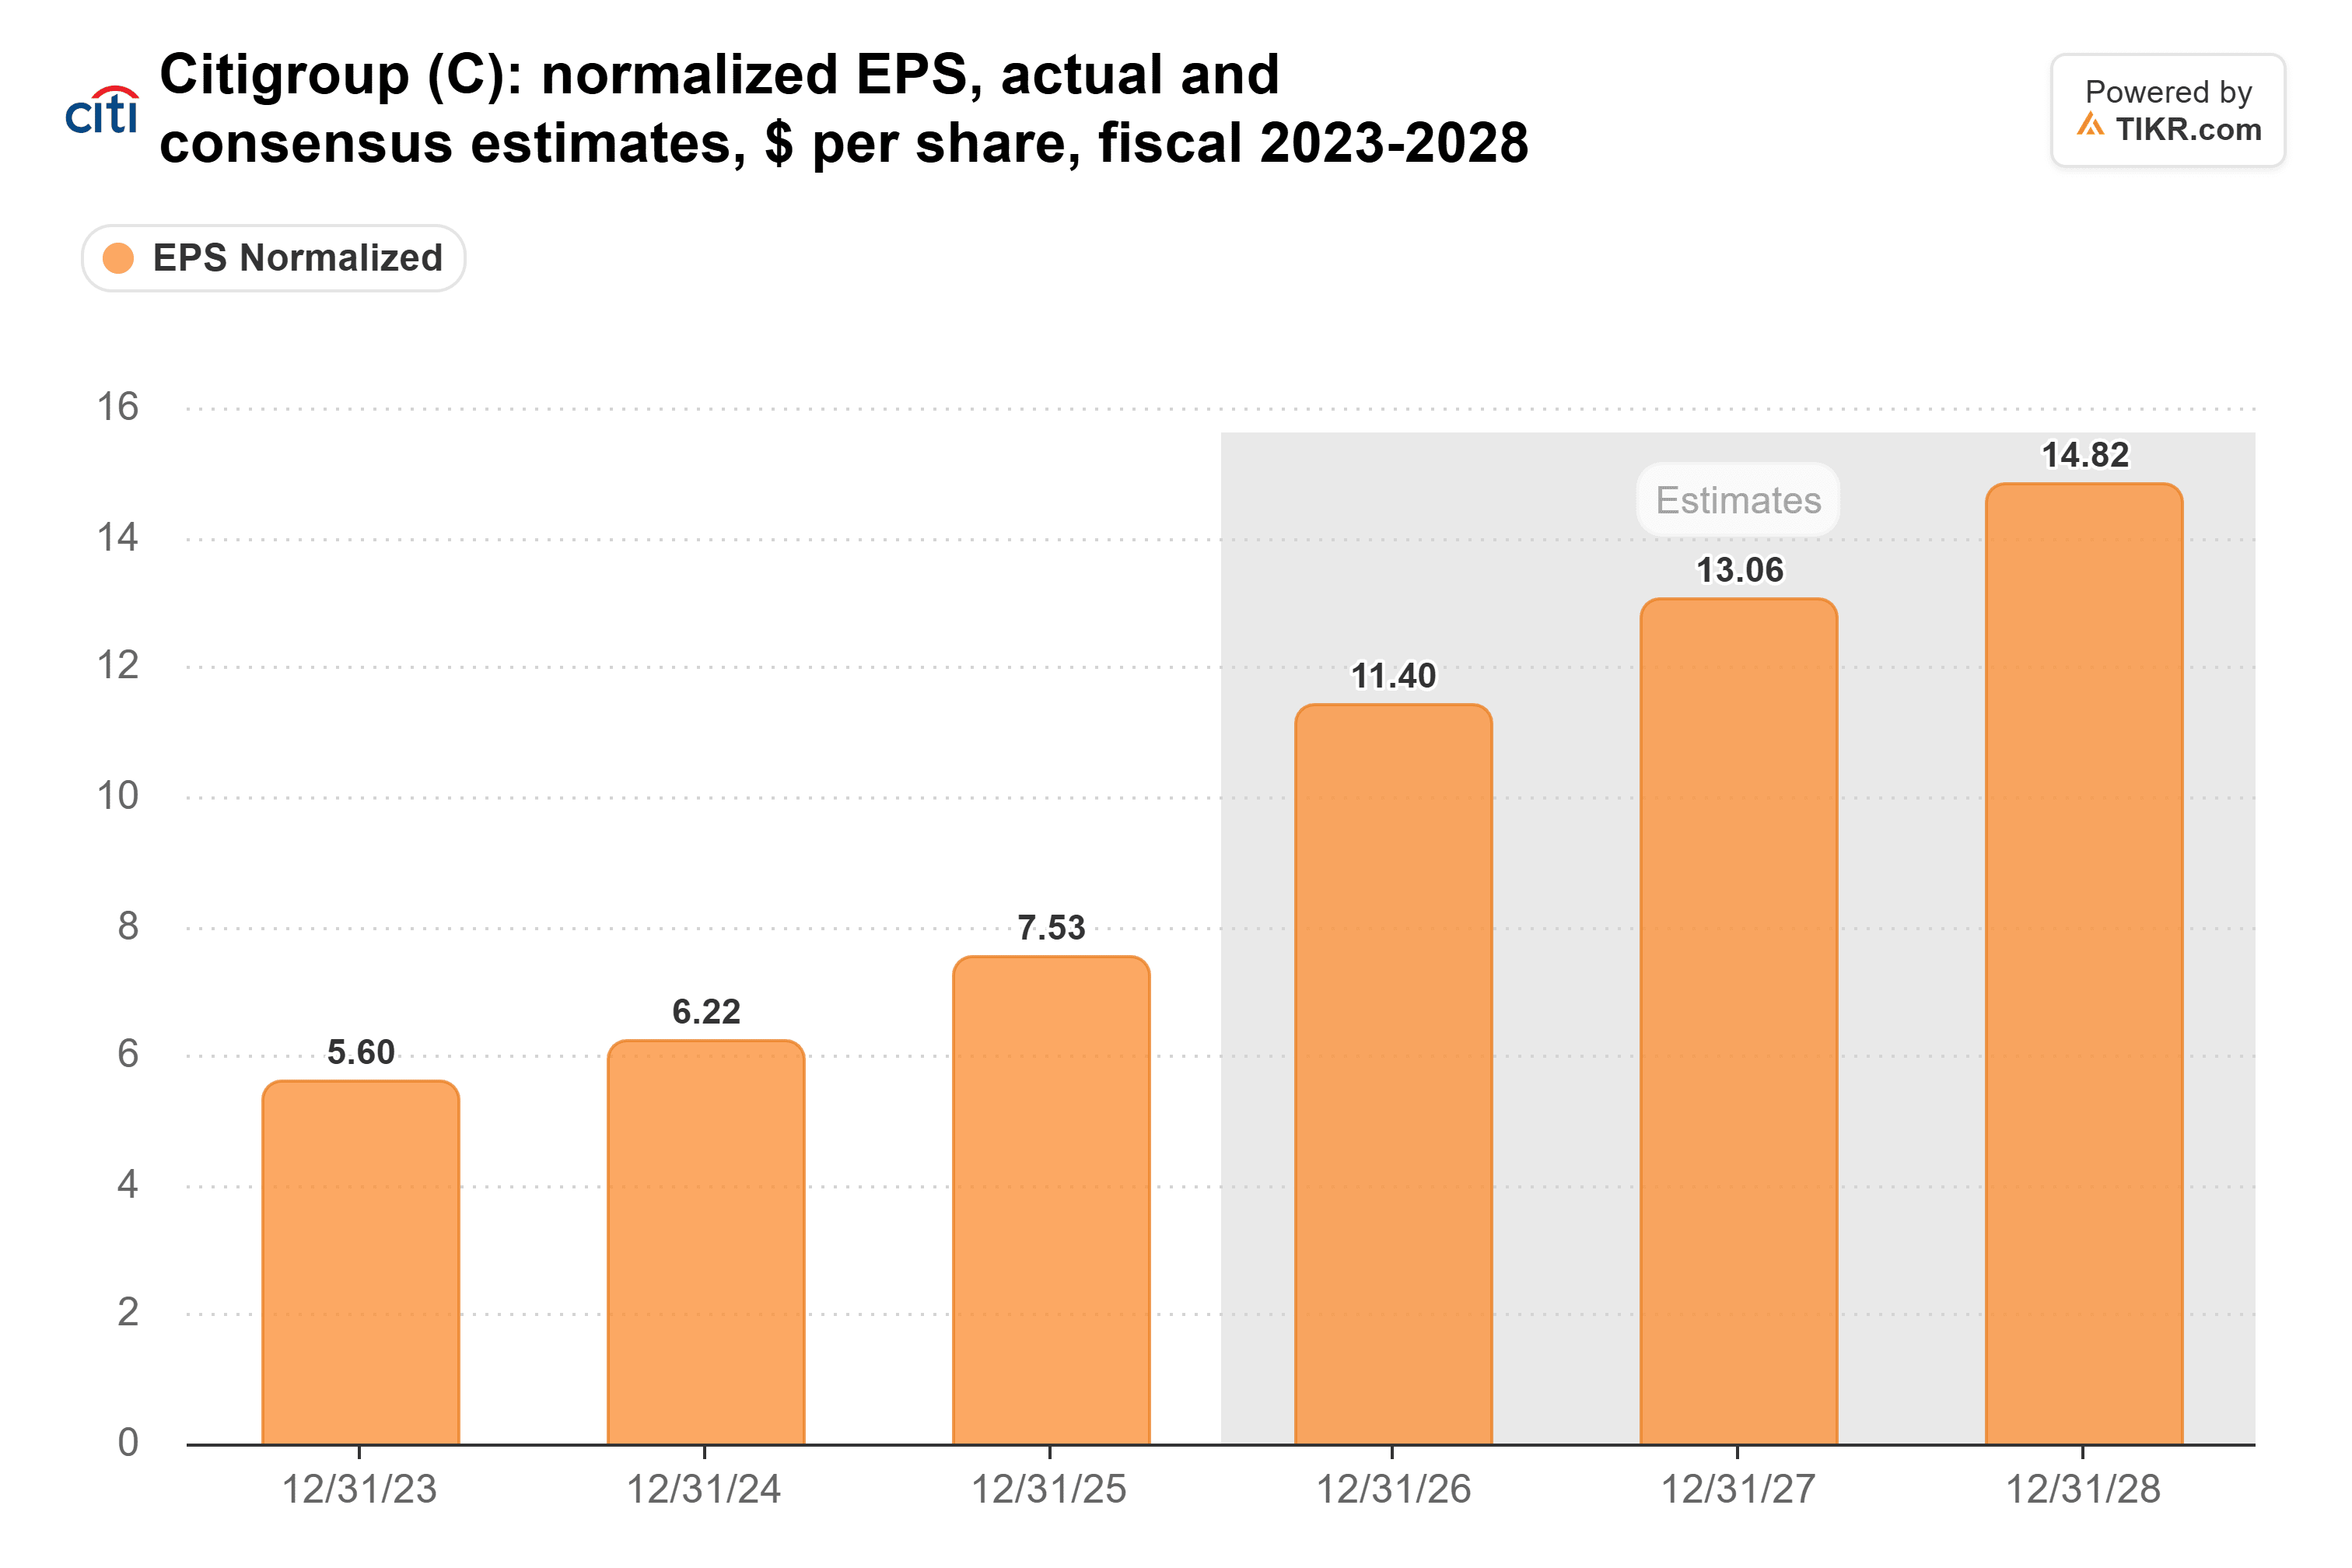
Analysts expect Citi’s normalized EPS to climb from $7.53 in 2025 to $11.40 this year and $14.82 by 2028, nearly doubling in three years.
The nearer risk is trading: management expects fourth-quarter Markets revenue to fall about 20%, possibly more, from the third quarter.
Rates and Outages Are the New Worries
Eisman skipped rates, which Wells Fargo CEO Charlie Scharf flags as an economic risk. Wells Fargo’s net interest margin slipped to 2.43% in the third quarter from 2.61% a year earlier, as lower-yielding Markets assets and interest-bearing deposits grew, though net interest income rose 5%.
Speed is the other worry. In Milan on Nov. 16, Fed Governor Michael Barr warned that AI agents moving deposits on their own risk “potentially accelerating runs that unfold in minutes.”
Citi CEO Jane Fraser expects more disruption. At a Bloomberg Newsmakers event in Washington on Nov. 18, she said “we should be expecting for a while, some more downtime, some more outages,” though “it doesn’t mean it’s a disaster.”
TIKR Tracks 23 Analysts on Citigroup. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Citigroup, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Citigroup’s Analyst Ratings
Citi’s Discount Comes Down to Returns
Investors have already paid up for a safer Citi. Its price to tangible book climbed from 0.4x in October 2023 to 1.2x at the Nov. 18 close, above its five-year average of 0.8x.
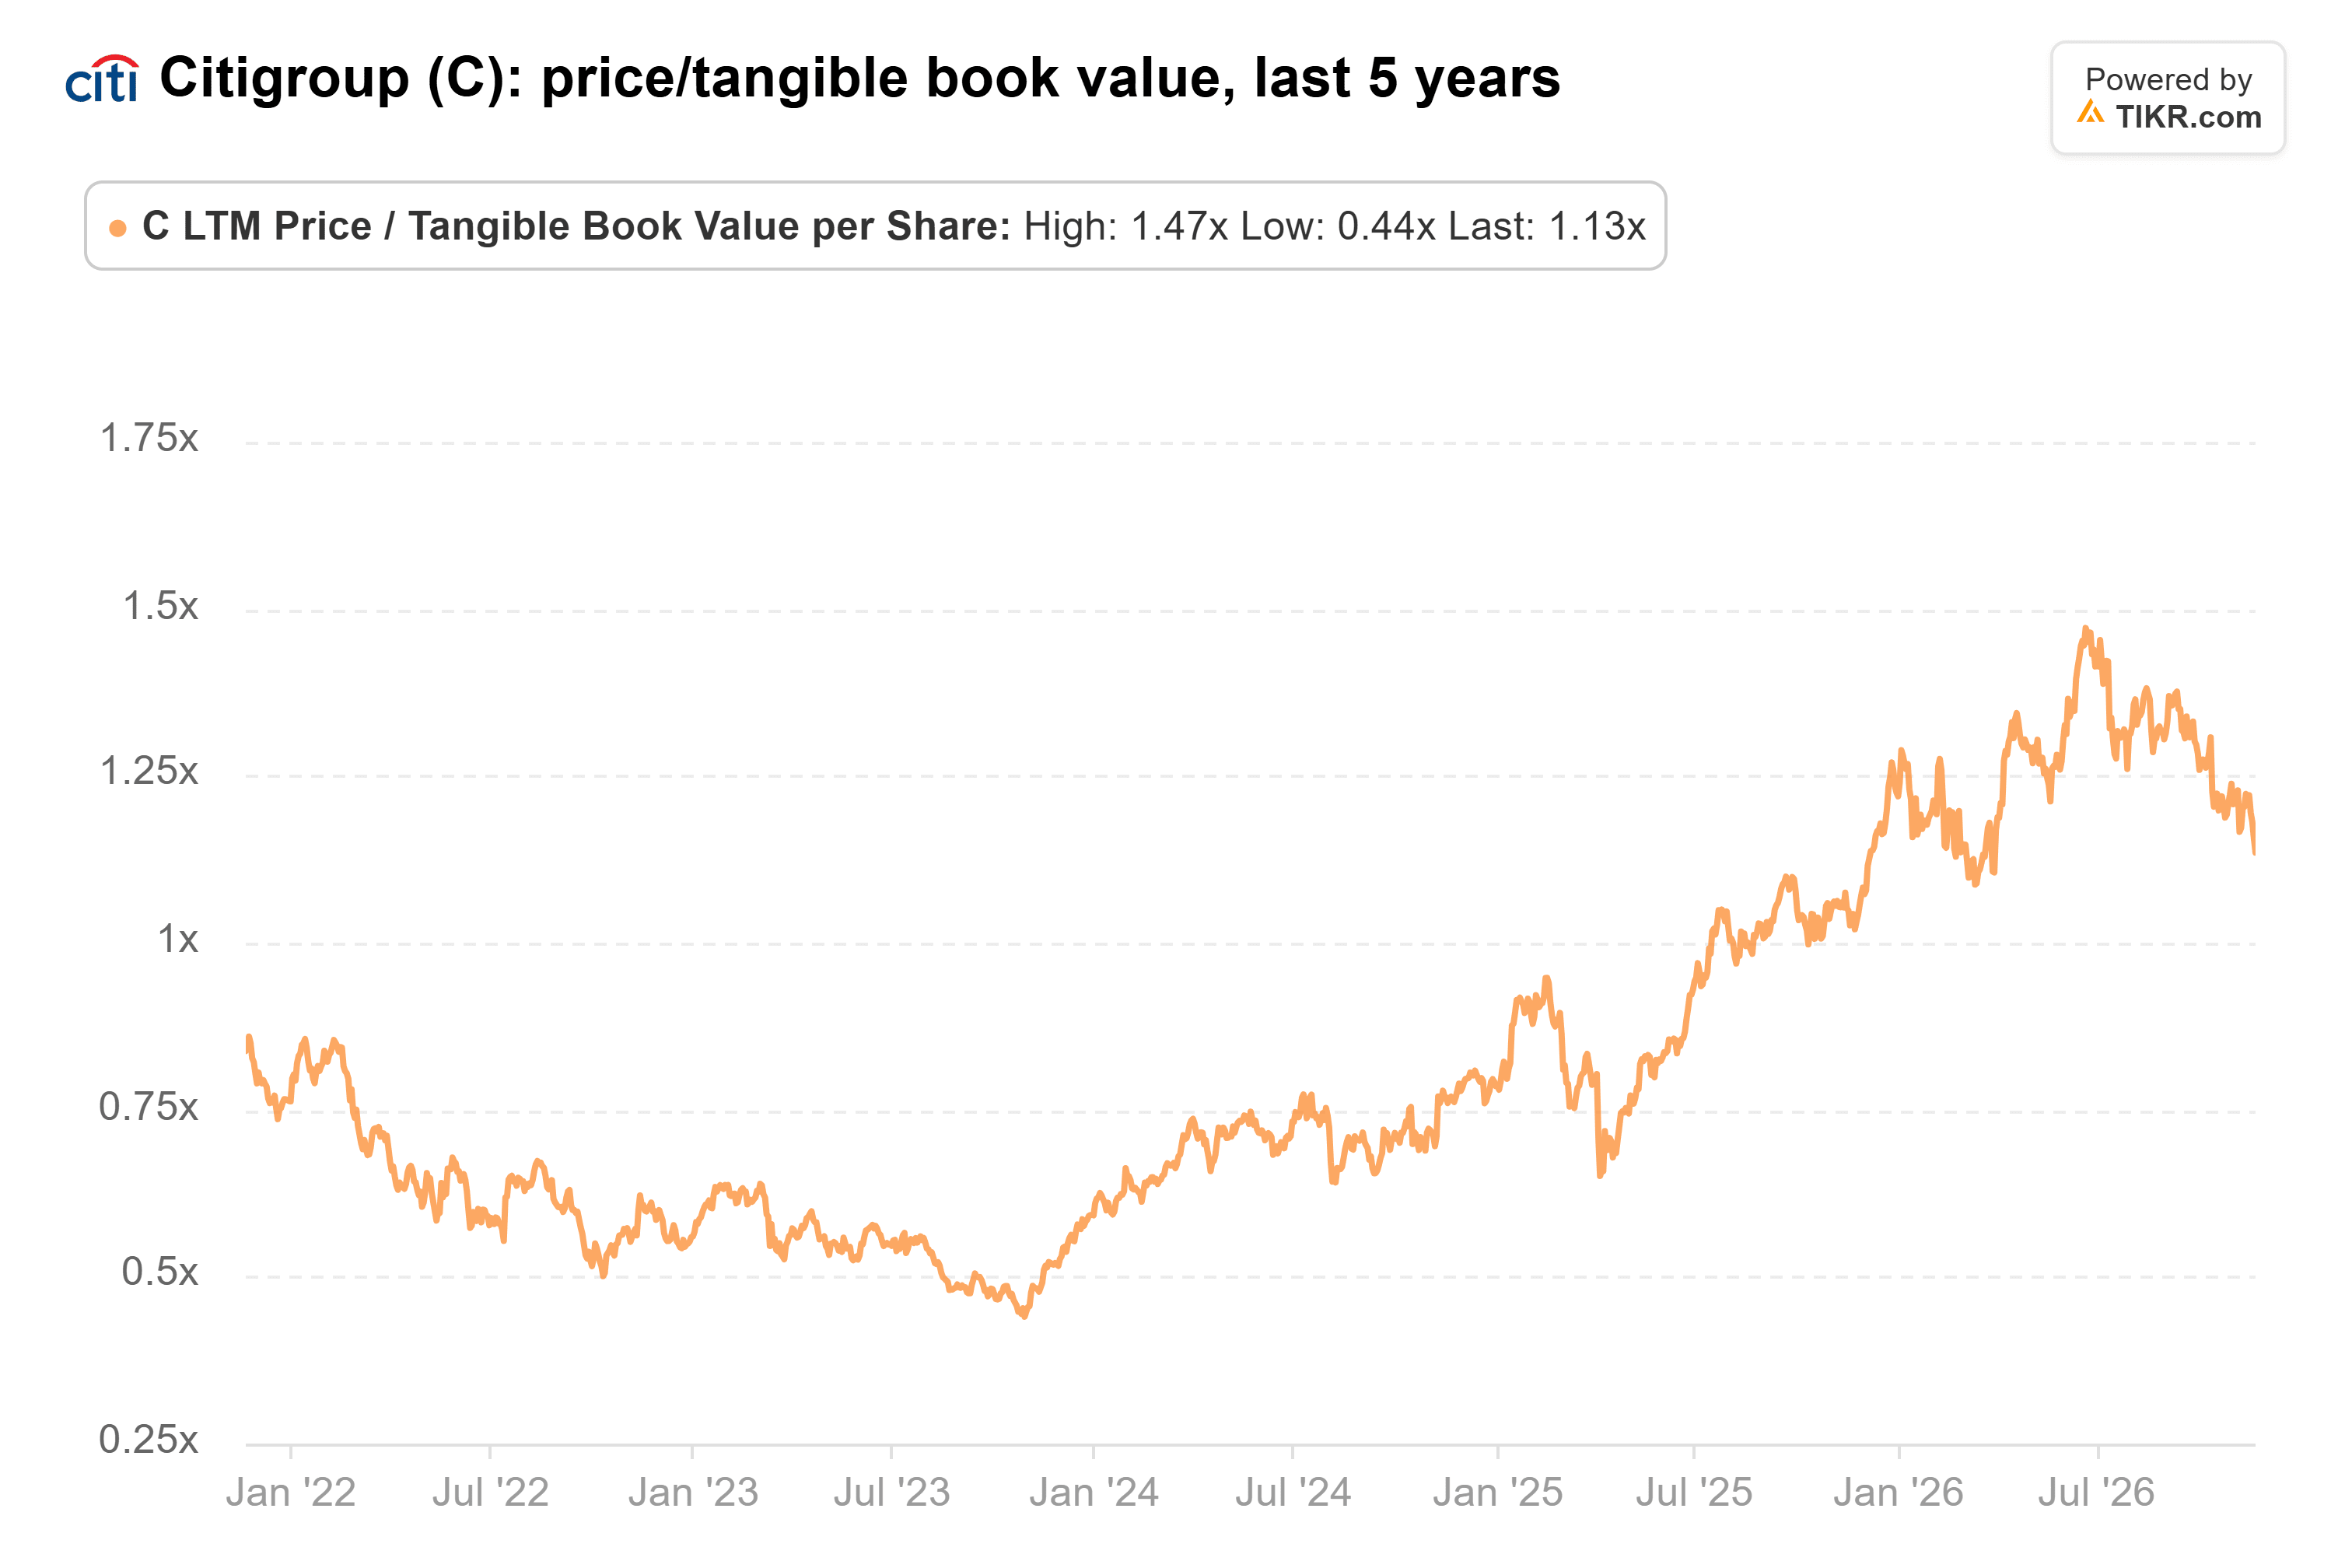
JPMorgan, under the same post-2008 rules, trades at 2.9x against a five-year average of 2.3x. Citi sits at well under half that.

Closing more of that gap takes higher returns. Citi earned 12.6% on tangible common equity in the first nine months of 2026, and targets 11% to 13% for 2027 and 2028, then 14% to 15% longer term.
Citi’s Jan. 14 Report Is the Next Test
Eisman is right that 2008’s failure isn’t today’s risk. If Citi hits those targets, 1.2x has room to climb.
Jan. 14 brings the fourth-quarter report and 2027 outlook, and management has already flagged a high-single-digit fourth-quarter return. More outages, higher rates, or the roughly $9 billion Banamex accounting loss due in early 2027 could stall the rerating.
So What Is Citigroup Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Citigroup could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!