Key Takeaways
- Verizon yields 6.8% and Crown Castle 5.4%, after Crown Castle cut its dividend per share from $6.26 in fiscal 2024 to $4.75 in fiscal 2025.
- Verizon’s cash dividend payout ratio was 54% over the twelve months to June 30, 2026, and analysts expect 54% again in fiscal 2026.
- Crown Castle’s AFFO payout ratio was 109% in fiscal 2025, and analysts expect 93% in fiscal 2026 as AFFO grows again.
- Crown Castle’s net debt is 6.5x EBITDA, against 3.4x for Verizon.
Anyone hunting for a 5%+ yield is going to come across Verizon Communications (VZ), at 6.8%, and Crown Castle (CCI), at 5.4%. On Oct. 9, the same news sent one down 8.7% and the other up 15.6%.
In January 2026, Verizon raised its quarterly dividend 2.5% to $0.7075 a share. Crown Castle is still paying the $1.0625 a quarter it paid a year ago, after last year’s cut.
So which is the better high-yield dividend stock?
| Metric | Verizon (VZ) | Crown Castle (CCI) |
|---|---|---|
| Dividend yield | 6.8% | 5.4% |
| Dividend growth, fiscal 2020–2025 | 1.9% a year | -0.7% a year |
| Dividend record | 20 straight years of increases (company’s count) | Cut in fiscal 2025 |
| Coverage measure | Cash dividend payout ratio | AFFO payout ratio |
| Coverage, last reported | 54% (TTM to June 30, 2026) | 109% (fiscal 2025) |
| Coverage, forward (fiscal 2026 consensus) | 54% | 93% |
| Net debt/EBITDA (LTM) | 3.35x | 6.51x |
Verizon’s dividend has room to spare
Verizon’s core business is growing: in the second quarter of 2026, mobility and broadband service revenue rose 2.8% from a year before to $23.4 billion, and free cash flow rose 24.4% to $6.4 billion. Management expects 9% to 10% free cash flow growth for all of 2026.
That leaves plenty of room for the dividend. Verizon’s cash dividend payout ratio was a well-covered 54% over the twelve months to June 30, 2026, and analysts expect the same 54% in fiscal 2026. Its highest of the last five fiscal years was 77%, in fiscal 2022.

“We are growing our dividend, and we are paying down our debt,” management said on its July call, and a 54% payout leaves room for both, though the dividend rose just 1.9% a year from fiscal 2020 to fiscal 2025.
The newest risk is competition. SpaceX agreed on Oct. 8 to buy nationwide low-band spectrum for its Starlink phone service, and Verizon’s stock fell 8.7% the next day. The deal still needs the FCC’s approval, and Verizon says spectrum alone “does not provide the network or infrastructure to offer true nationwide coverage.”
Crown Castle is still rebuilding its cushion
Crown Castle’s numbers run the other way. It’s a REIT, so its dividend is judged against AFFO, and its AFFO payout ratio climbed from 73% in fiscal 2020 to an uncovered 109% in fiscal 2025, as AFFO per share fell from $6.98 in fiscal 2024 to $4.36 in fiscal 2025.
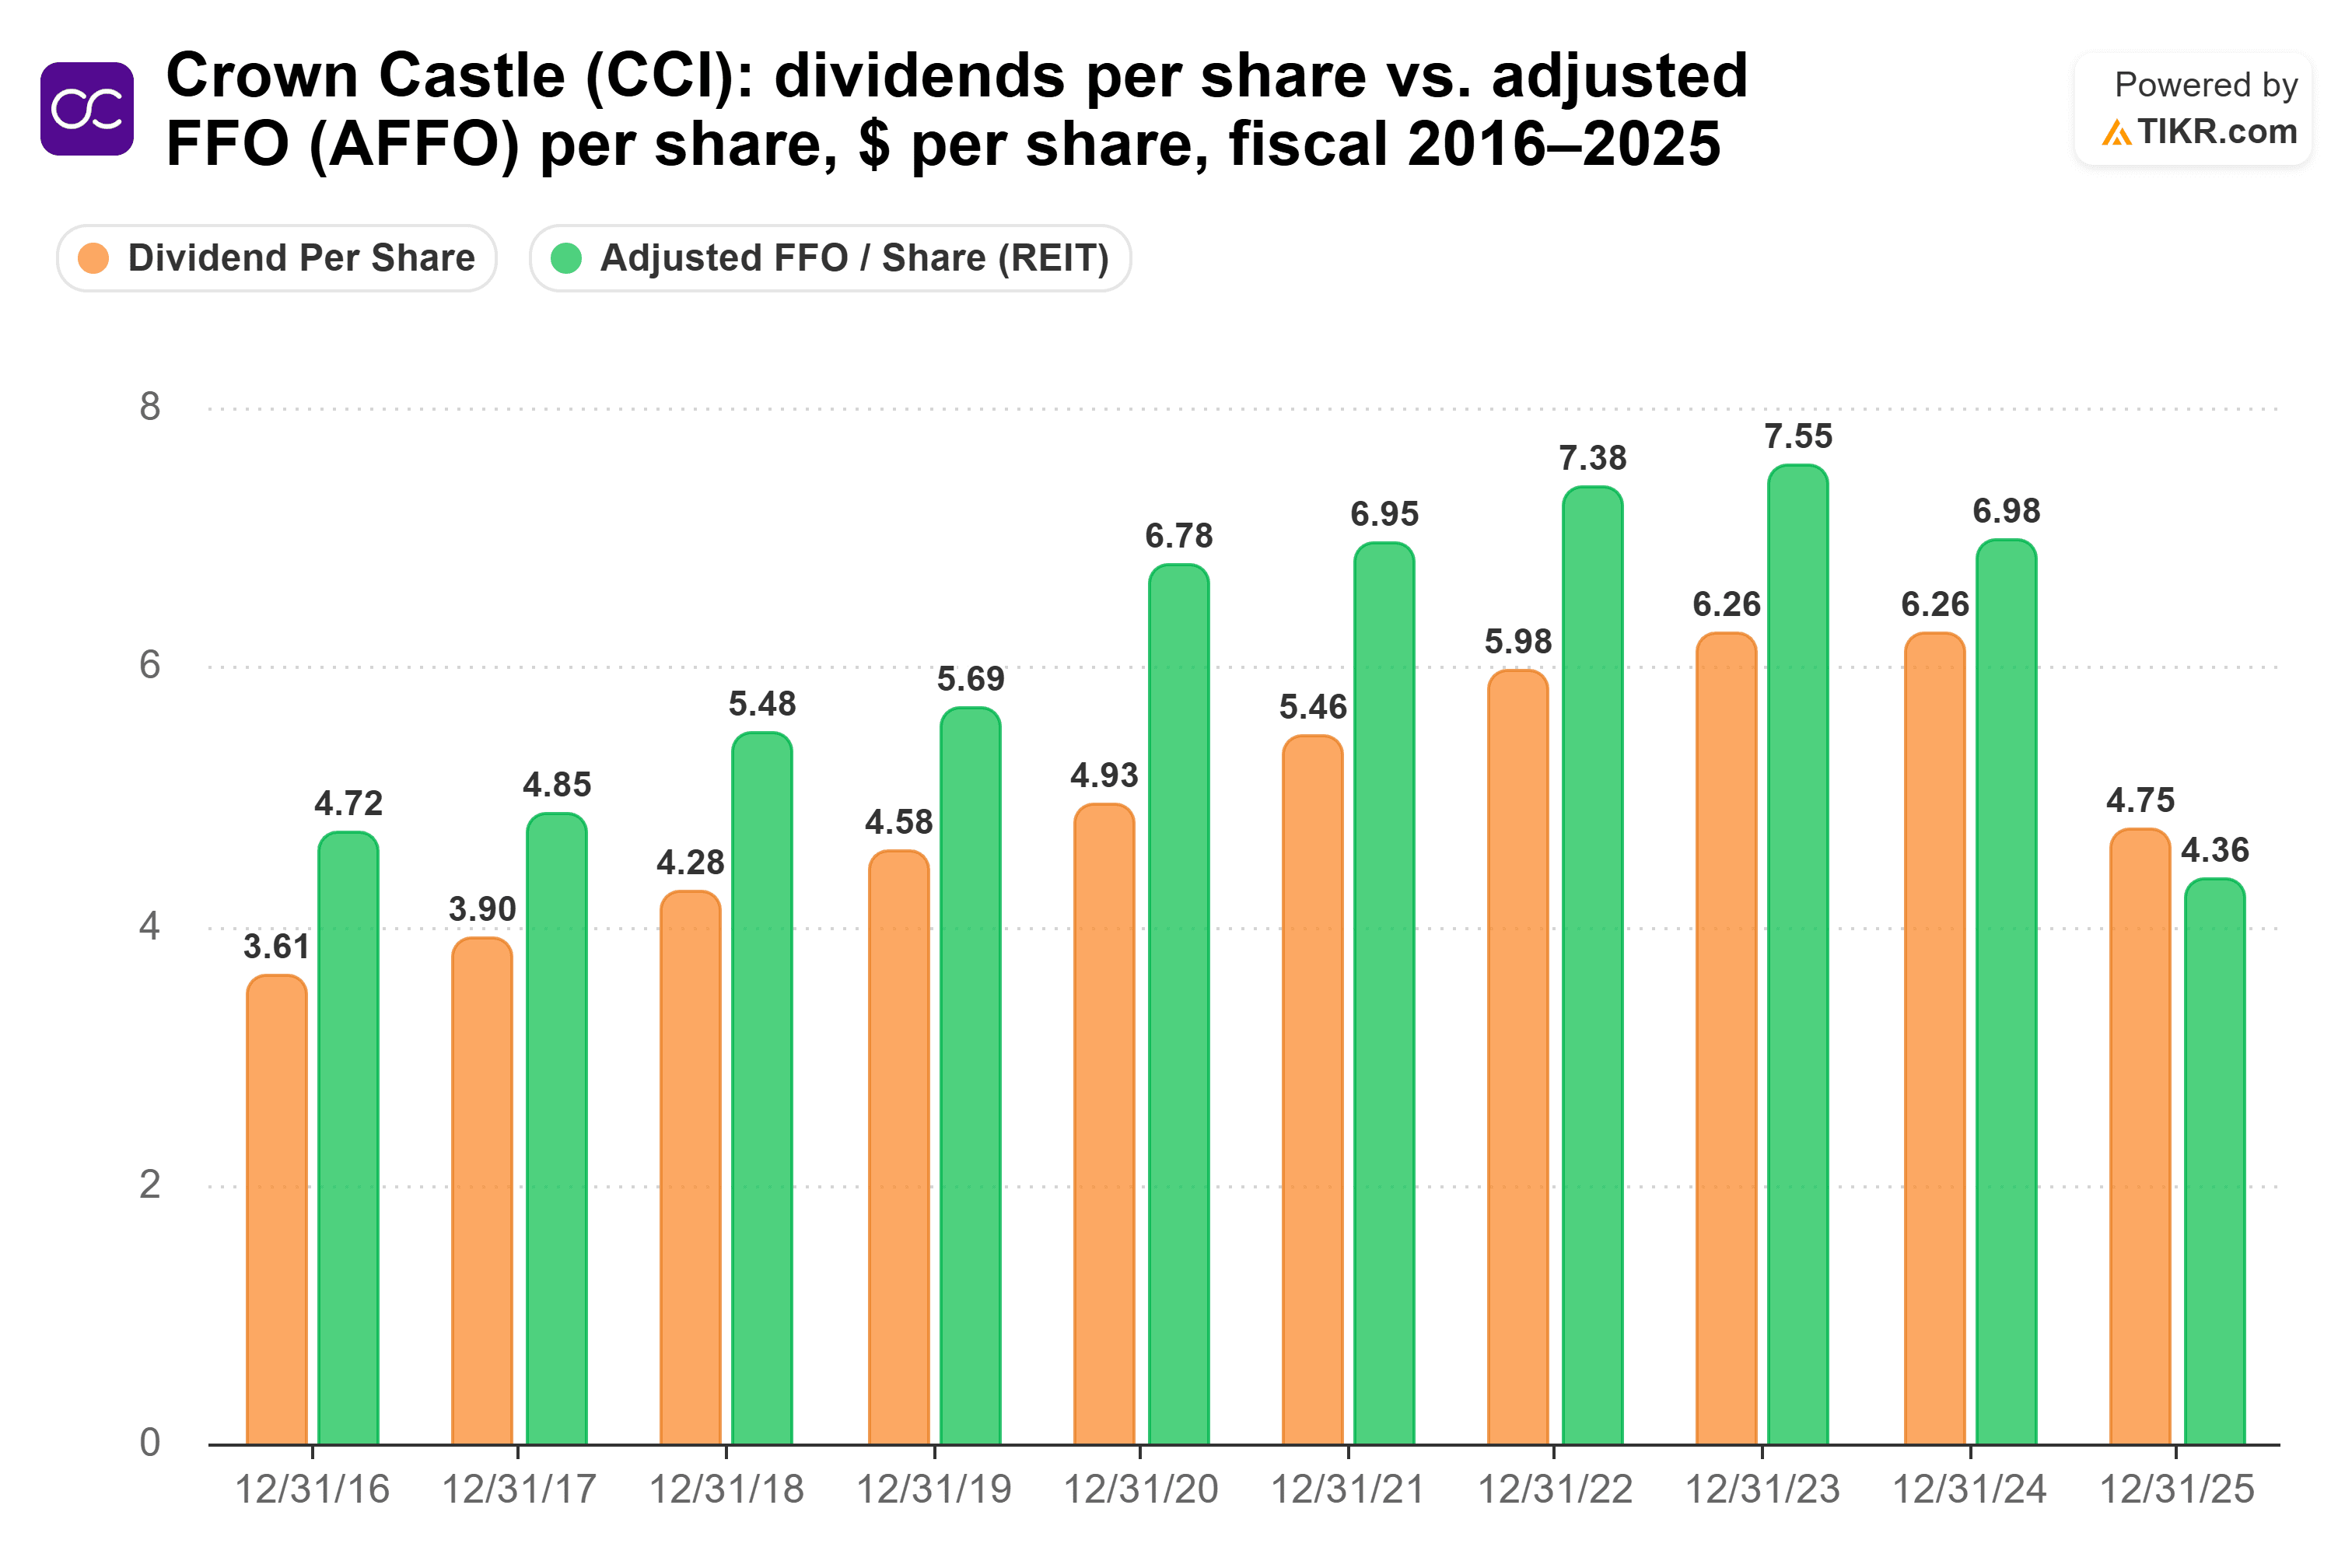
The cut is helping. Against the $4.58 of AFFO per share analysts expect for fiscal 2026, today’s $4.25 dividend makes for a tight 93% AFFO payout ratio. AFFO rose to $1.13 a share in the second quarter of 2026 from $1.02 a year before, even as DISH terminations and Sprint cancellations cut site rental revenue 4%.
CEO Christian Hillabrant calls the dividend “sacrosanct,” and CFO Sunit Patel, who retires at the end of March 2027, said in April that “we will, over the next couple of years or so, get to the point where the dividend payout is within the ratio of the range that we’ve talked about.” A 93% payout says it isn’t there yet.
SpaceX’s deal sent Crown Castle’s stock up 15.6% on Oct. 9, to $79.64, on the hope that its satellites will still need towers. SpaceX hasn’t signed a lease, so that’s a hope, not rent.
The main risk is debt. Net debt sits at a heavy 6.51x EBITDA over the last twelve months, just above Hillabrant’s “target investment-grade leverage range of 6x to 6.5x,” and EBIT covers interest just 2.13x.
So which dividend wins?
Verizon is the better high-yield dividend stock. It pays the bigger check, covers it with a 54% cash dividend payout ratio both over the last twelve months and on fiscal 2026 estimates, and carries half Crown Castle’s leverage.
$10,000 in Verizon at its 6.8% yield pays $680 a year now, against $540 for Crown Castle at 5.4%. At Verizon’s 1.9% five-year growth rate, that becomes about $808 in year 10, an 8.1% yield on your original $10,000. Crown Castle’s five-year rate of -0.7% a year, which takes in last year’s cut, would shrink its $540 to about $505.
And you don’t pay up for Verizon’s safety. The stock trades at 8.2x forward earnings, below its five-year average of 8.8x and well off its 10.5x high in March 2026.

This isn’t to say Crown Castle’s dividend is in trouble. AFFO is growing again, the company’s 2026 guidance of $4.53 to $4.65 a share sits above the $4.25 dividend, and management treats the payout as untouchable. It’s just that I’d rather own the dividend with 20 years of raises and a wide cushion behind it.
Of course, Crown Castle is still pursuing a $3.5 billion claim in DISH’s bankruptcy court. A big recovery would help its balance sheet, and that fight is far from over.
So what is Verizon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Verizon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!