Key Takeaways
- Kraft Heinz yields 7.2% and Clorox 6.1%, after Kraft Heinz guided 2026 adjusted operating income 16% to 18% lower and Clorox’s free cash flow fell from $761 million in fiscal 2025 to $405 million in fiscal 2026.
- Kraft Heinz paid $1.60 a share in both fiscal 2020 and fiscal 2025, while Clorox’s dividend grew 2% a year from fiscal 2021 to fiscal 2026.
- Kraft Heinz’s dividend took 50% of free cash flow over the trailing 12 months and Clorox’s took 149%, though forward estimates put them at 69% and 71%.
- Clorox’s net debt went from 1.8x EBITDA in fiscal 2025 to 4.3x in fiscal 2026 after the GOJO deal, against 2.7x at Kraft Heinz.
Anyone hunting for a big dividend check is going to look hard at Kraft Heinz (KHC) and Clorox (CLX).
On Aug. 5, Kraft Heinz guided 2026 constant-currency adjusted operating income 16% to 18% below 2025’s, as it puts about $700 million more behind its brands. That came two days after Clorox closed a fiscal year in which its dividend took 149% of free cash flow.
So which is the better high-yield dividend stock?
| Metric | Kraft Heinz (KHC) | Clorox (CLX) |
|---|---|---|
| Dividend yield | 7.2% | 6.1% |
| Annual dividend | $1.60 | $5.00 |
| Dividend growth, 5 years | 0.0% a year (fiscal 2020–2025) | 2.0% a year (fiscal 2021–2026) |
| Cash dividend payout ratio, TTM | 50% | 149% |
| Cash dividend payout ratio, forward | 69% (fiscal 2026) | 71% (fiscal 2027) |
| Net debt/EBITDA | 2.71x | 4.29x |
Kraft Heinz pays a big check from a shrinking business
Kraft Heinz’s sales are still slipping. Net sales of $6.3 billion in the quarter ended June 27, 2026, were 1.4% below the same quarter of 2025, with North America’s organic sales 2.7% lower.
The dividend has plenty of room. Since fiscal 2019, when dividends paid dropped to $1.95 billion from $3.18 billion in fiscal 2018, free cash flow has covered them every year but fiscal 2022.

Over the twelve months to June 27, 2026, the cash dividend payout ratio was a well-covered 50%. Consensus puts it at 69% for fiscal 2026. That estimate has free cash flow at $2.76 billion, 25% below fiscal 2025’s $3.66 billion, the year operating income is guided lower and the extra spending lands.
Management’s priorities are “sustaining the dividend and protecting our investment-grade credit profile,” and sustaining is the right word: Kraft Heinz paid $1.60 a share in both fiscal 2020 and fiscal 2025. The risk is that the extra spending doesn’t stop the slide in North America.
Clorox’s raises have outrun its cash
Clorox’s dividend has the growth Kraft Heinz’s lacks, rising from $4.49 a share in fiscal 2021 to $4.96 in fiscal 2026. “Dividend has increased annually for a decade,” CFO Luc Bellet said on the Aug. 3 call.
The cash behind it has gone the other way. Free cash flow fell from $1.29 billion in fiscal 2020 to $405 million in fiscal 2026, while dividends paid rose from $533 million to $602 million, so free cash flow fell short of the dividend in fiscal 2022, 2024 and 2026.
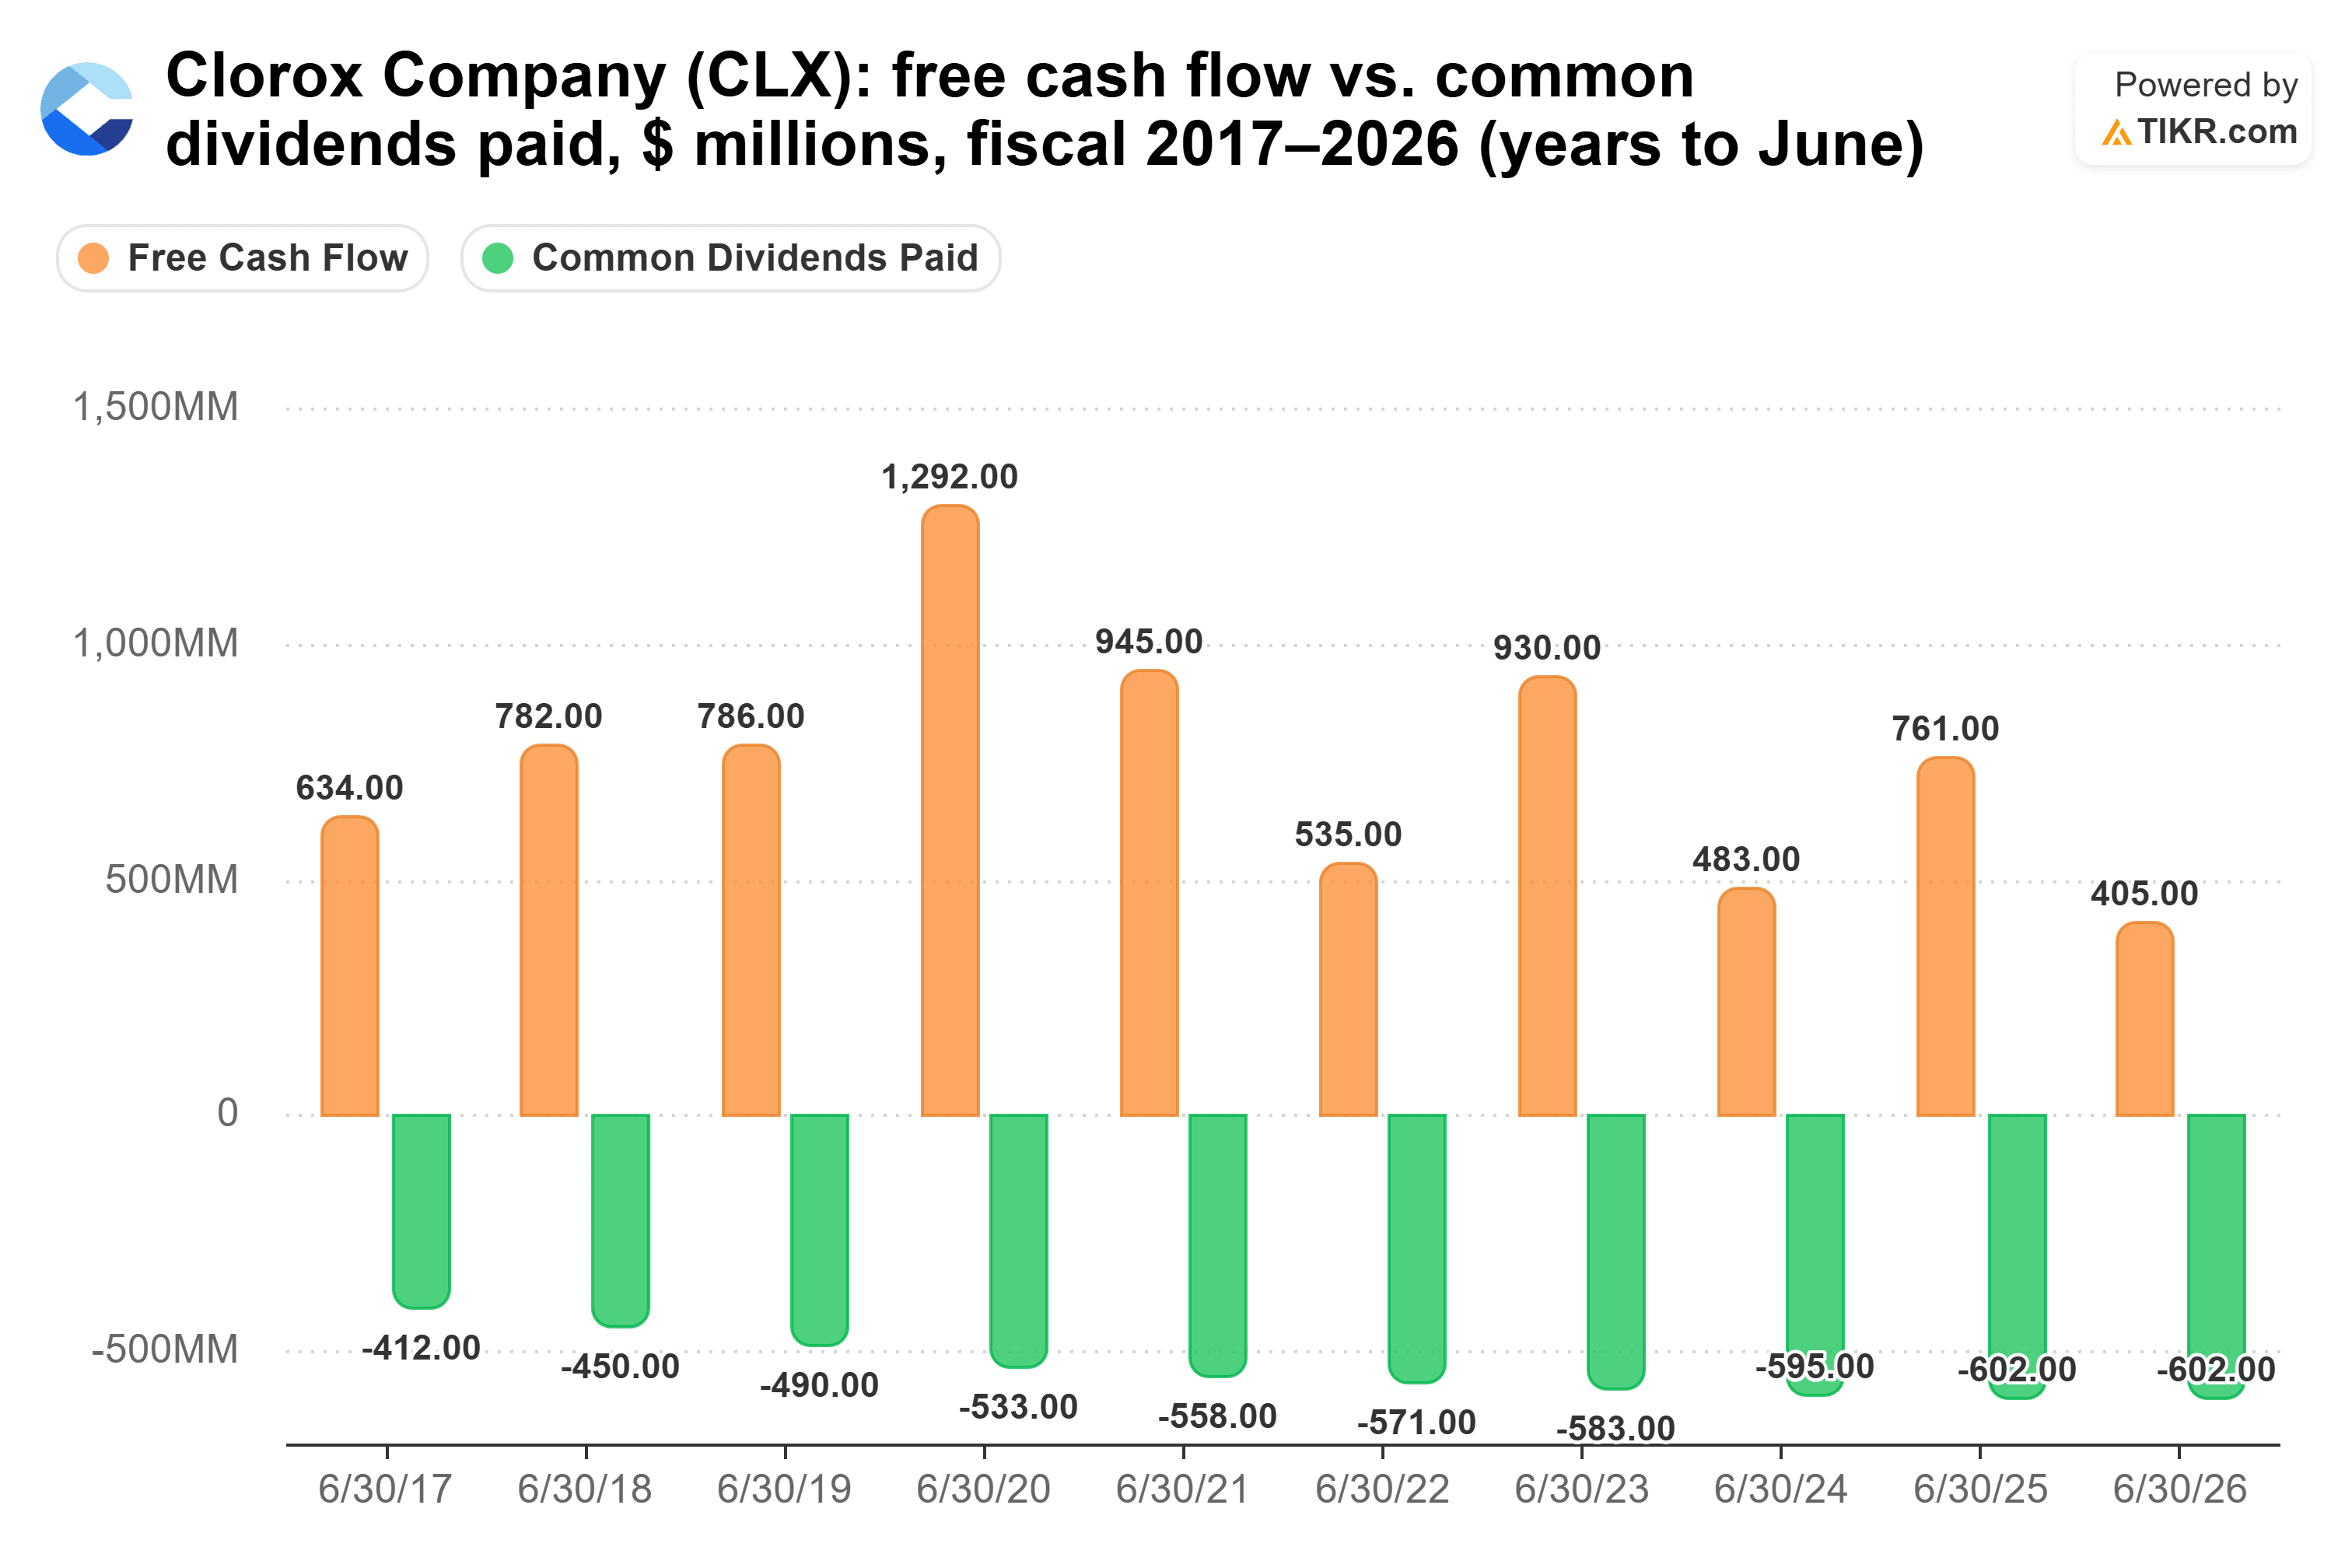
That left a risky 149% cash dividend payout ratio for fiscal 2026, and even its $612 million of operating cash barely covered the dividend.
Bellet calls the payout “a bit elevated, but we see this as something more transitory as we rebuild our gross margin and not something structural.” Fiscal 2027 guidance points that way: organic sales 3.5% to 4.5% higher and gross margin about 42%. Consensus has free cash flow more than doubling to $881 million, for a forward ratio of 71%. Only four analysts make that estimate, though, and last year’s consensus missed the actual by 18%.
So which dividend wins?
Kraft Heinz is the better high-yield dividend stock. It pays the bigger check, 7.2% against 6.1%, and covers it today: 50% of free cash flow over the trailing 12 months and 69% on 2026 consensus. Clorox needs its free cash flow to more than double just to get to 71%.
And Clorox is waiting on that cash with far more debt: net debt went from 1.8x EBITDA in fiscal 2025 to 4.3x in fiscal 2026 after it borrowed for the GOJO deal.

That compares with 2.7x at Kraft Heinz. Clorox’s debt is about $5.1 billion after GOJO and a Glad stake, and S&P cut its rating to BBB in February 2026. Bellet says Clorox will repay the new debt “with the free cash flow that we’ll generate over the next 12 to 18 months,” the same cash the dividend is counting on.
Clorox’s case is a strong one. Its business is guided to grow in fiscal 2027 while Kraft Heinz expects 2026 organic sales 0.5% to 2.0% lower. And its raises add up: at 2.0% a year, $10,000 would pay about $730 in year 10, a 7.3% yield on today’s money, passing Kraft Heinz’s flat $720 around 2035. Its July 31 raise was just a penny a quarter, though, to $1.25.
It’s just that all of that rests on cash Clorox hasn’t generated yet, and on a new CEO it has yet to name: Clorox said May 28 that Linda Rendle will step down for health reasons. For anyone buying a high yield for income, Kraft Heinz’s is the check I’d rather count on.
Of course, if Clorox gets its gross margin back to about 42% in fiscal 2027 and the cash follows, this one gets a lot closer.
So what is Kraft Heinz stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Kraft Heinz could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!