Key Takeaways
- Eversource Energy yields 4.6% and Truist Financial yields 4.2%, so $10,000 in each pays $460 or $420 a year today.
- Eversource’s dividend grew 5.8% a year from fiscal 2020 to fiscal 2025, while Truist has paid $2.08 a share in each of fiscal 2023, 2024 and 2025.
- Truist paid out 52% of normalized earnings in fiscal 2025, falling to 45% on 2026 estimates, against 63% rising to 68% at Eversource.
- The next things to watch are Eversource’s Connecticut rate case ruling, expected in June, and Truist’s 2027 outlook in January.
Any retiree hunting for a 4%-plus yield is going to run into stocks like Eversource Energy (ES) and Truist Financial (TFC). Eversource yields 4.6% and Truist yields 4.2%, which is close enough that you’ll want to look past the yield.
Eversource narrowed its 2026 earnings guidance on Nov. 4 after a weaker third quarter, while Truist declared its regular $0.52 quarterly dividend on Oct. 27, the rate it’s paid since fiscal 2023.
So which is the better dividend stock?
| Metric | Eversource Energy (ES) | Truist Financial (TFC) |
|---|---|---|
| Dividend yield | 4.6% | 4.2% |
| Annual dividend | $3.15 a share | $2.08 a share |
| Dividend growth, fiscal 2020-2025 | 5.8% a year | 2.9% a year |
| Payout ratio of normalized EPS, fiscal 2025 | 63% | 52% |
| Payout ratio of normalized EPS, fiscal 2026 consensus | 68% | 45% |
| Valuation | 15x forward P/E | 1.6x price/tangible book |
Source: TIKR; yields at today’s prices.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Eversource’s payout ratio is creeping up
As a regulated utility, Eversource is judged on the share of its normalized EPS it pays out. Its dividend grew 5.8% a year from fiscal 2020 to fiscal 2025, from $2.27 to $3.01 a share. Normalized EPS kept pace, climbing from $2.96 in fiscal 2016 to $4.76 in fiscal 2025.
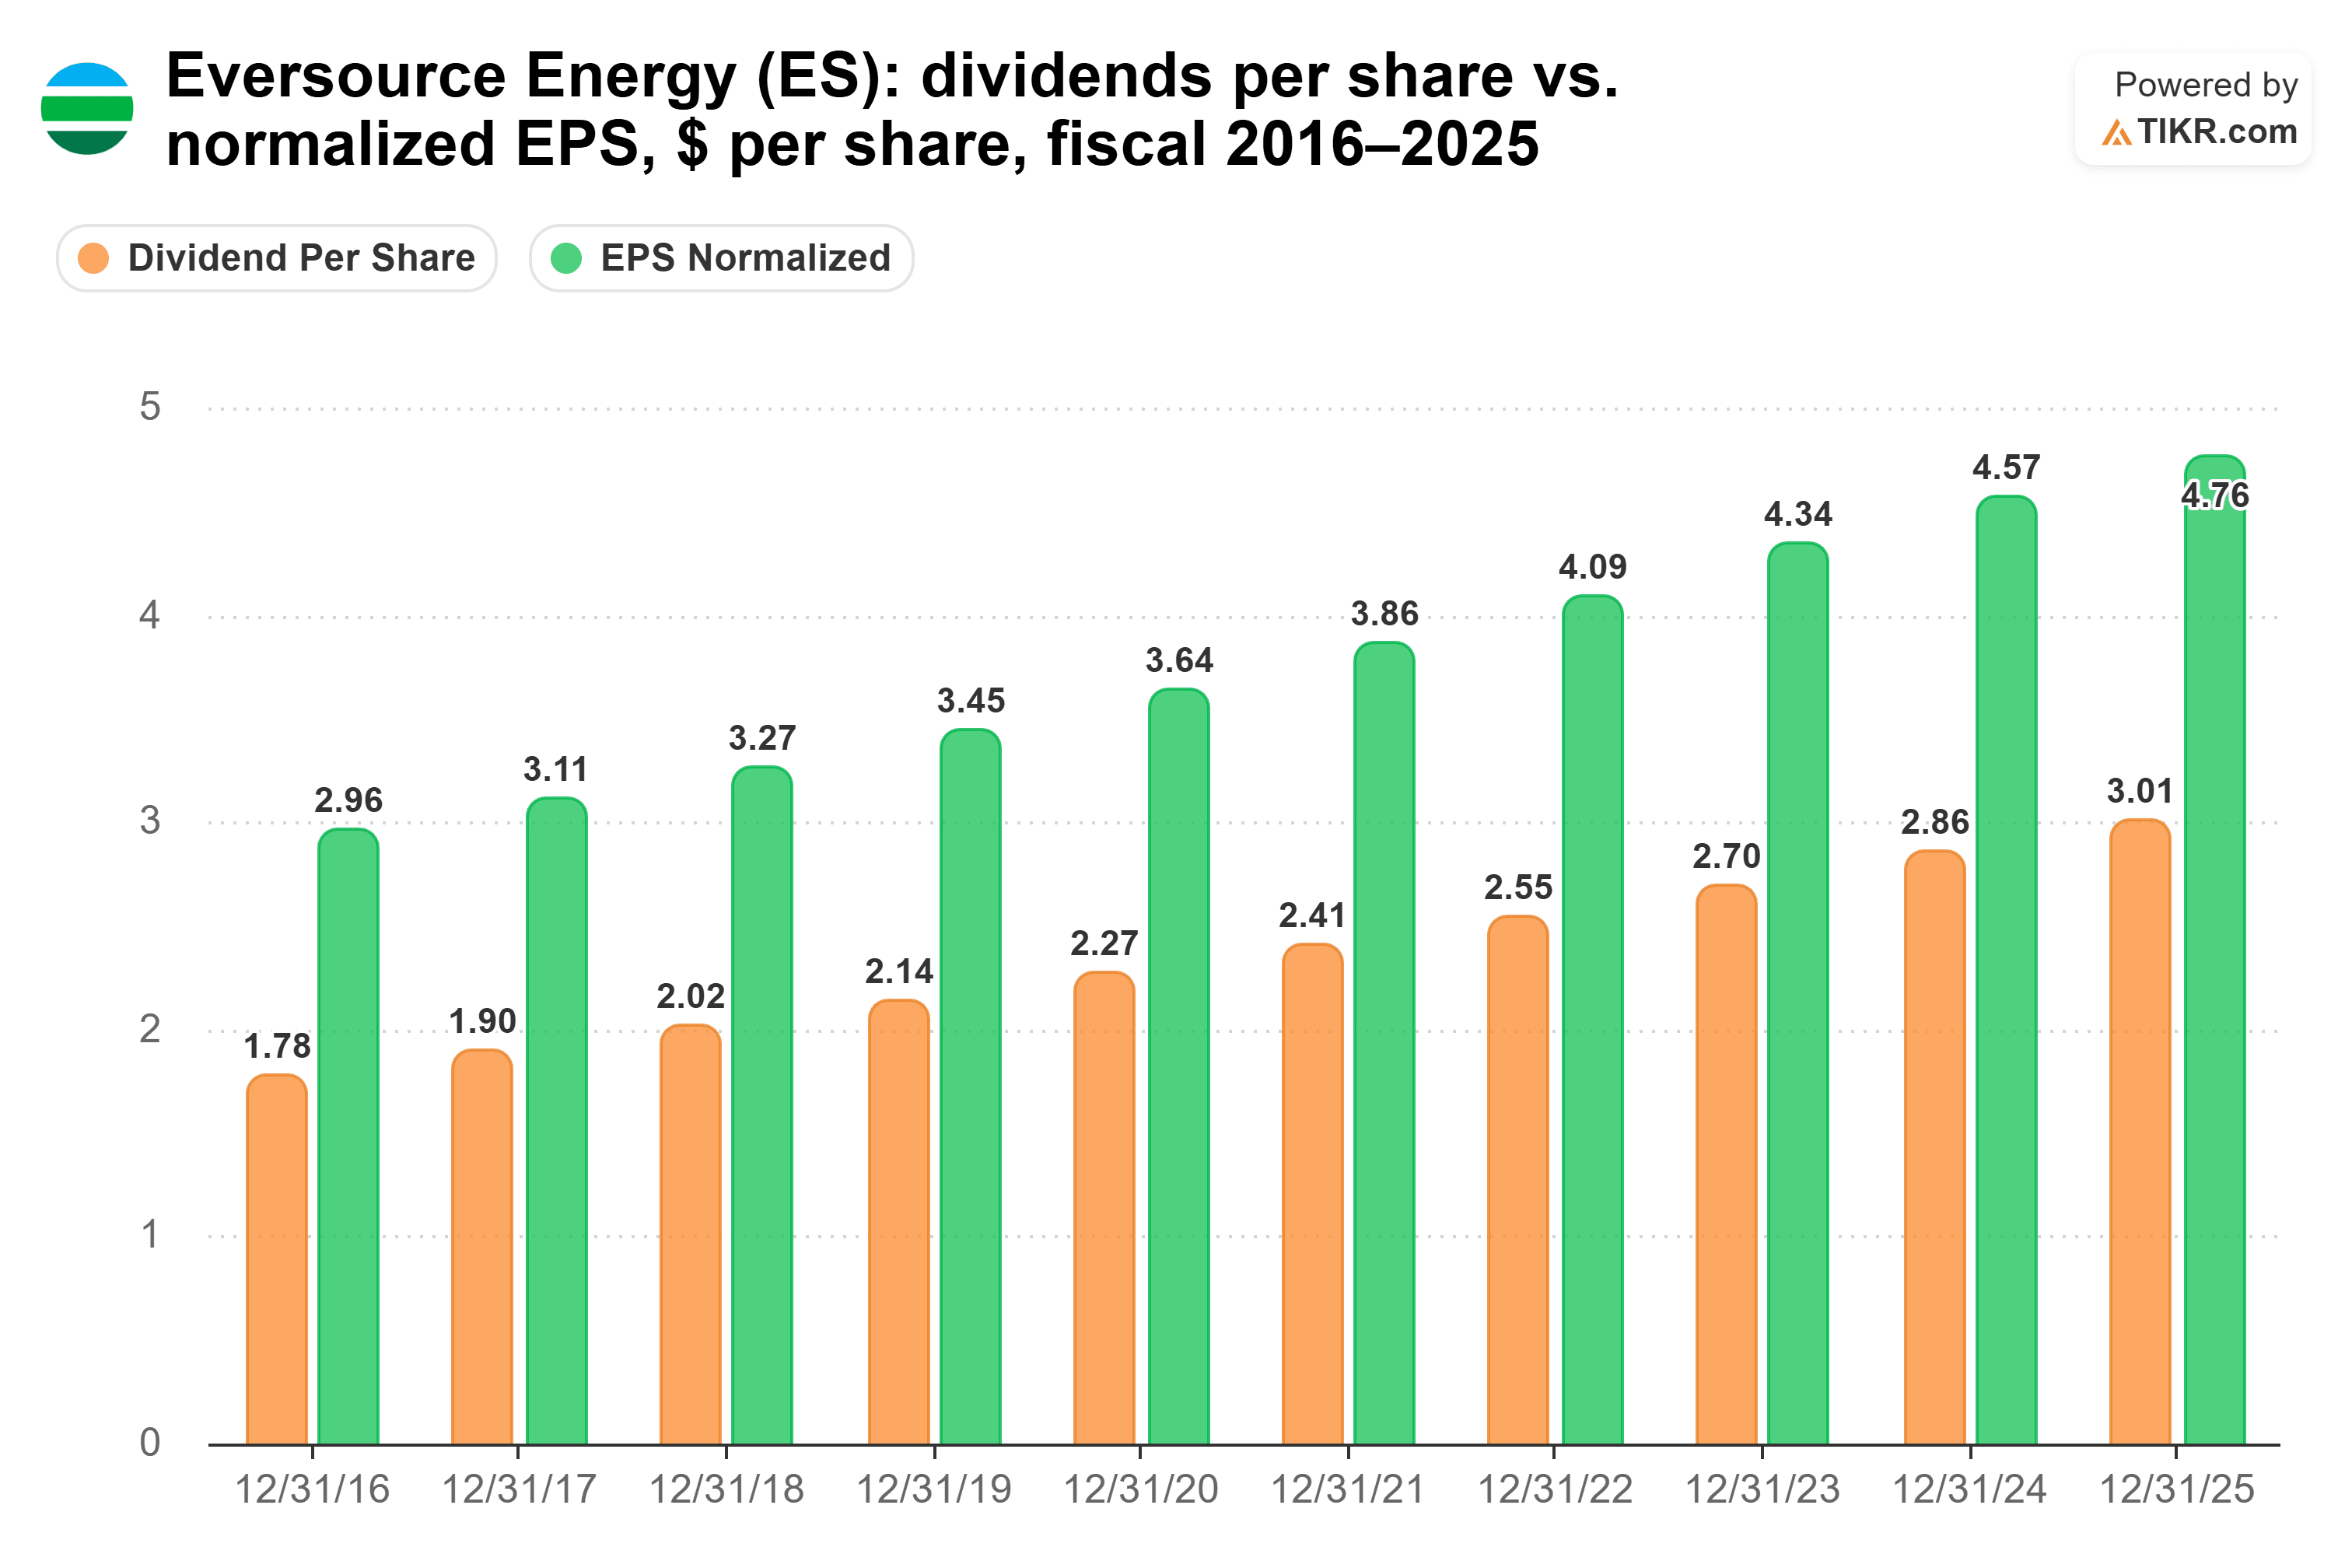
That kept its payout ratio between 60% and 63% every year of the decade.
In fiscal 2026, though, the 11 analysts covering Eversource expect normalized EPS to slip 2% to $4.66, against $3.17 of dividends, for a payout ratio of 68%. Its third-quarter results point to a lower transmission return allowed by FERC, Connecticut storm costs that regulators disallowed and a higher tax rate, among other things. Management still narrowed 2026 guidance to $4.62-$4.70 a share, a midpoint that matches the consensus, and reaffirmed 5%-7% yearly EPS growth through 2030.
The main risk is debt. Net debt is a heavy 5.8x EBITDA over the last twelve months, and EBIT covers interest a thin 2.3x.
Truist has room, and it’s spending it on buybacks
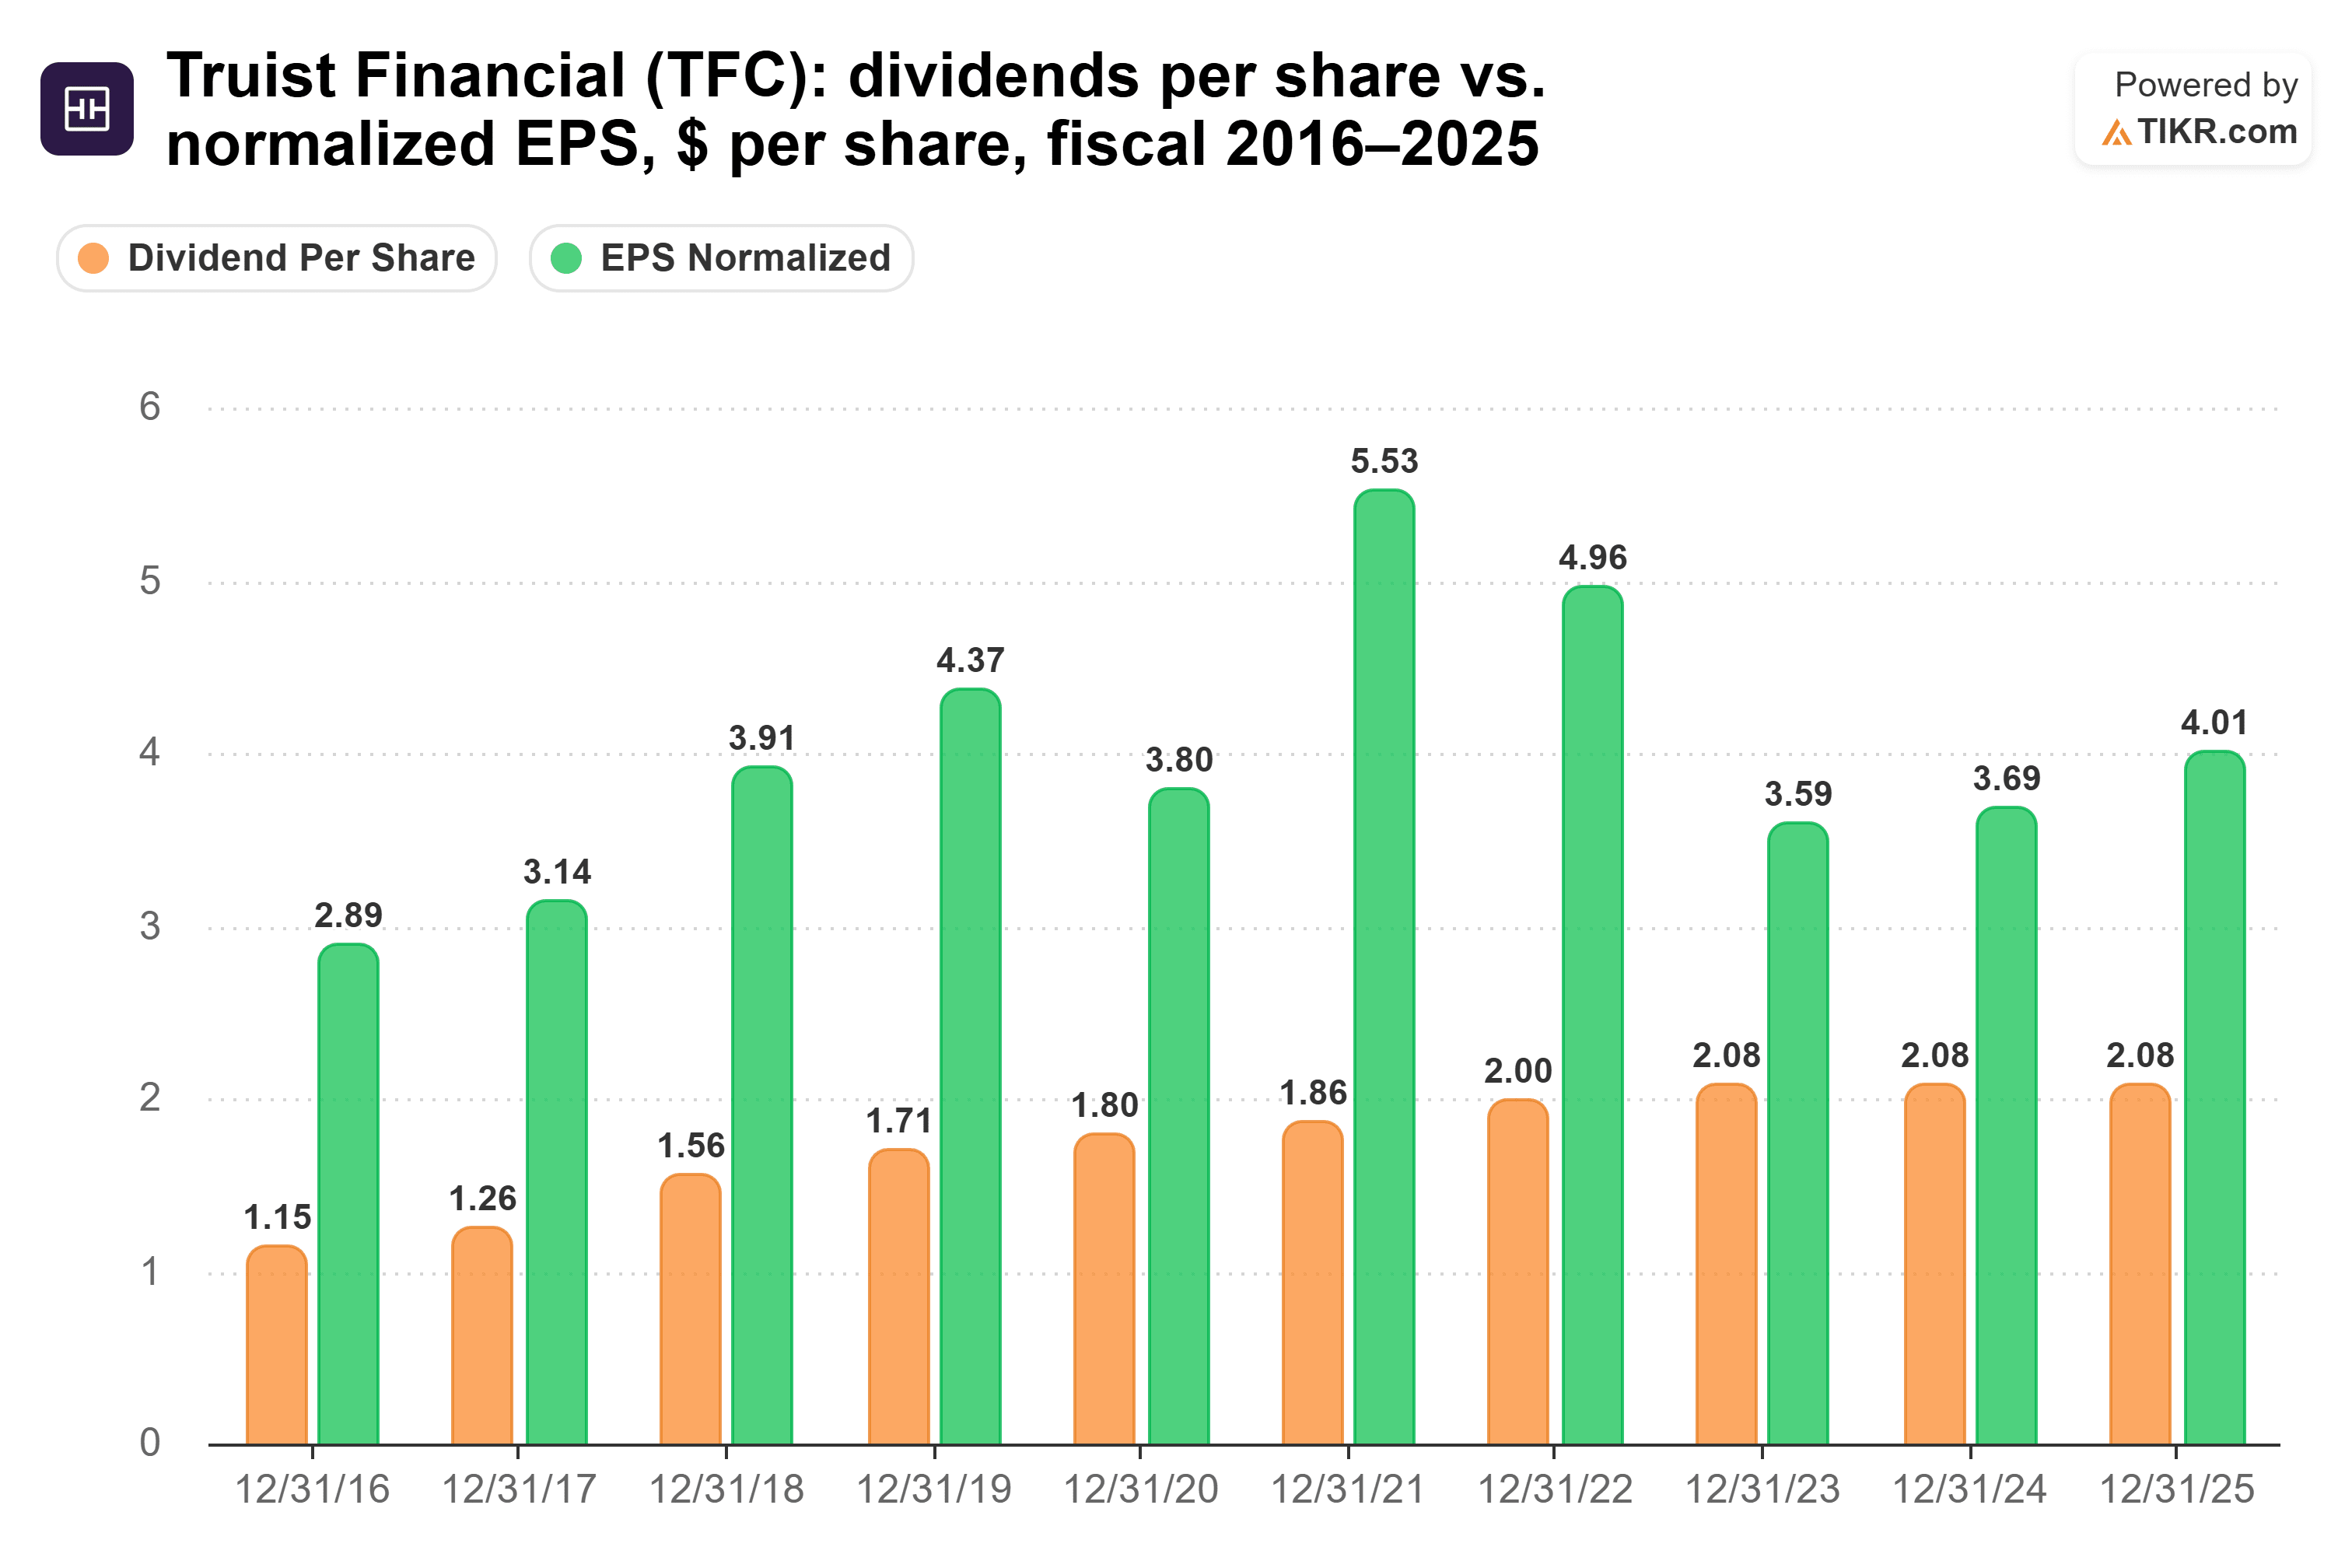
Truist’s payout ratio is heading the other way. Banks are judged on the same measure, and Truist paid out 52% of fiscal 2025’s $4.01 of normalized EPS. Its 19 analysts expect $4.67 in fiscal 2026, up 16%, which would drop the ratio to a roomy 45%.
The dividend hasn’t moved, though, and Truist’s earnings have been bumpier than Eversource’s. Normalized EPS peaked at $5.53 in fiscal 2021 and ran between $3.59 and $4.01 from fiscal 2023 to fiscal 2025. Over those three years, the dividend sat at $2.08 a share:
Truist is putting its spare capital into buybacks. It repurchased $1.2 billion of stock in the third quarter, against $632 million of common dividends, and its outlook assumes about $1 billion more in the fourth quarter.
It’s also selling and running off loan books, which CEO Michael Lyons said on Truist’s third-quarter call is “about creating a stronger foundation for both sustainable growth and higher returns over time.” Truist targets a 15% return on tangible common equity in 2027 and plans to say more about 2027 in January.
The risk is a shrinking loan book. Average loans fell $3.6 billion from the second quarter, and the net charge-off ratio rose to 0.77% from 0.50%.
So which dividend wins?
Eversource is the better dividend stock. It pays more today, it has raised its dividend faster, and its earnings have grown right alongside that dividend for a decade.
Put $10,000 in each, and the gap is clear:
- Eversource: $460 a year at its 4.6% yield. Growing 5.8% a year, that’s about $764 in year 10, a 7.6% yield on your cash today.
- Truist: $420 a year, rising to about $545 in year 10 at its 2.9% rate.
- At each dividend’s pace now: Eversource raised its dividend 5.2% in fiscal 2025 and Truist didn’t raise at all, so year 10 looks like about $729 against $420.
That isn’t to say Truist’s dividend is at risk. A 45% forward payout ratio leaves plenty of room, and Truist’s dividend grew 7.1% a year from fiscal 2015 to fiscal 2025. If management steers some of that buyback money toward raises, I’d look at Truist again. For now, though, Truist is choosing buybacks while Eversource keeps raising.
Eversource isn’t priced for perfection, either. Its forward P/E sits below its five-year average:
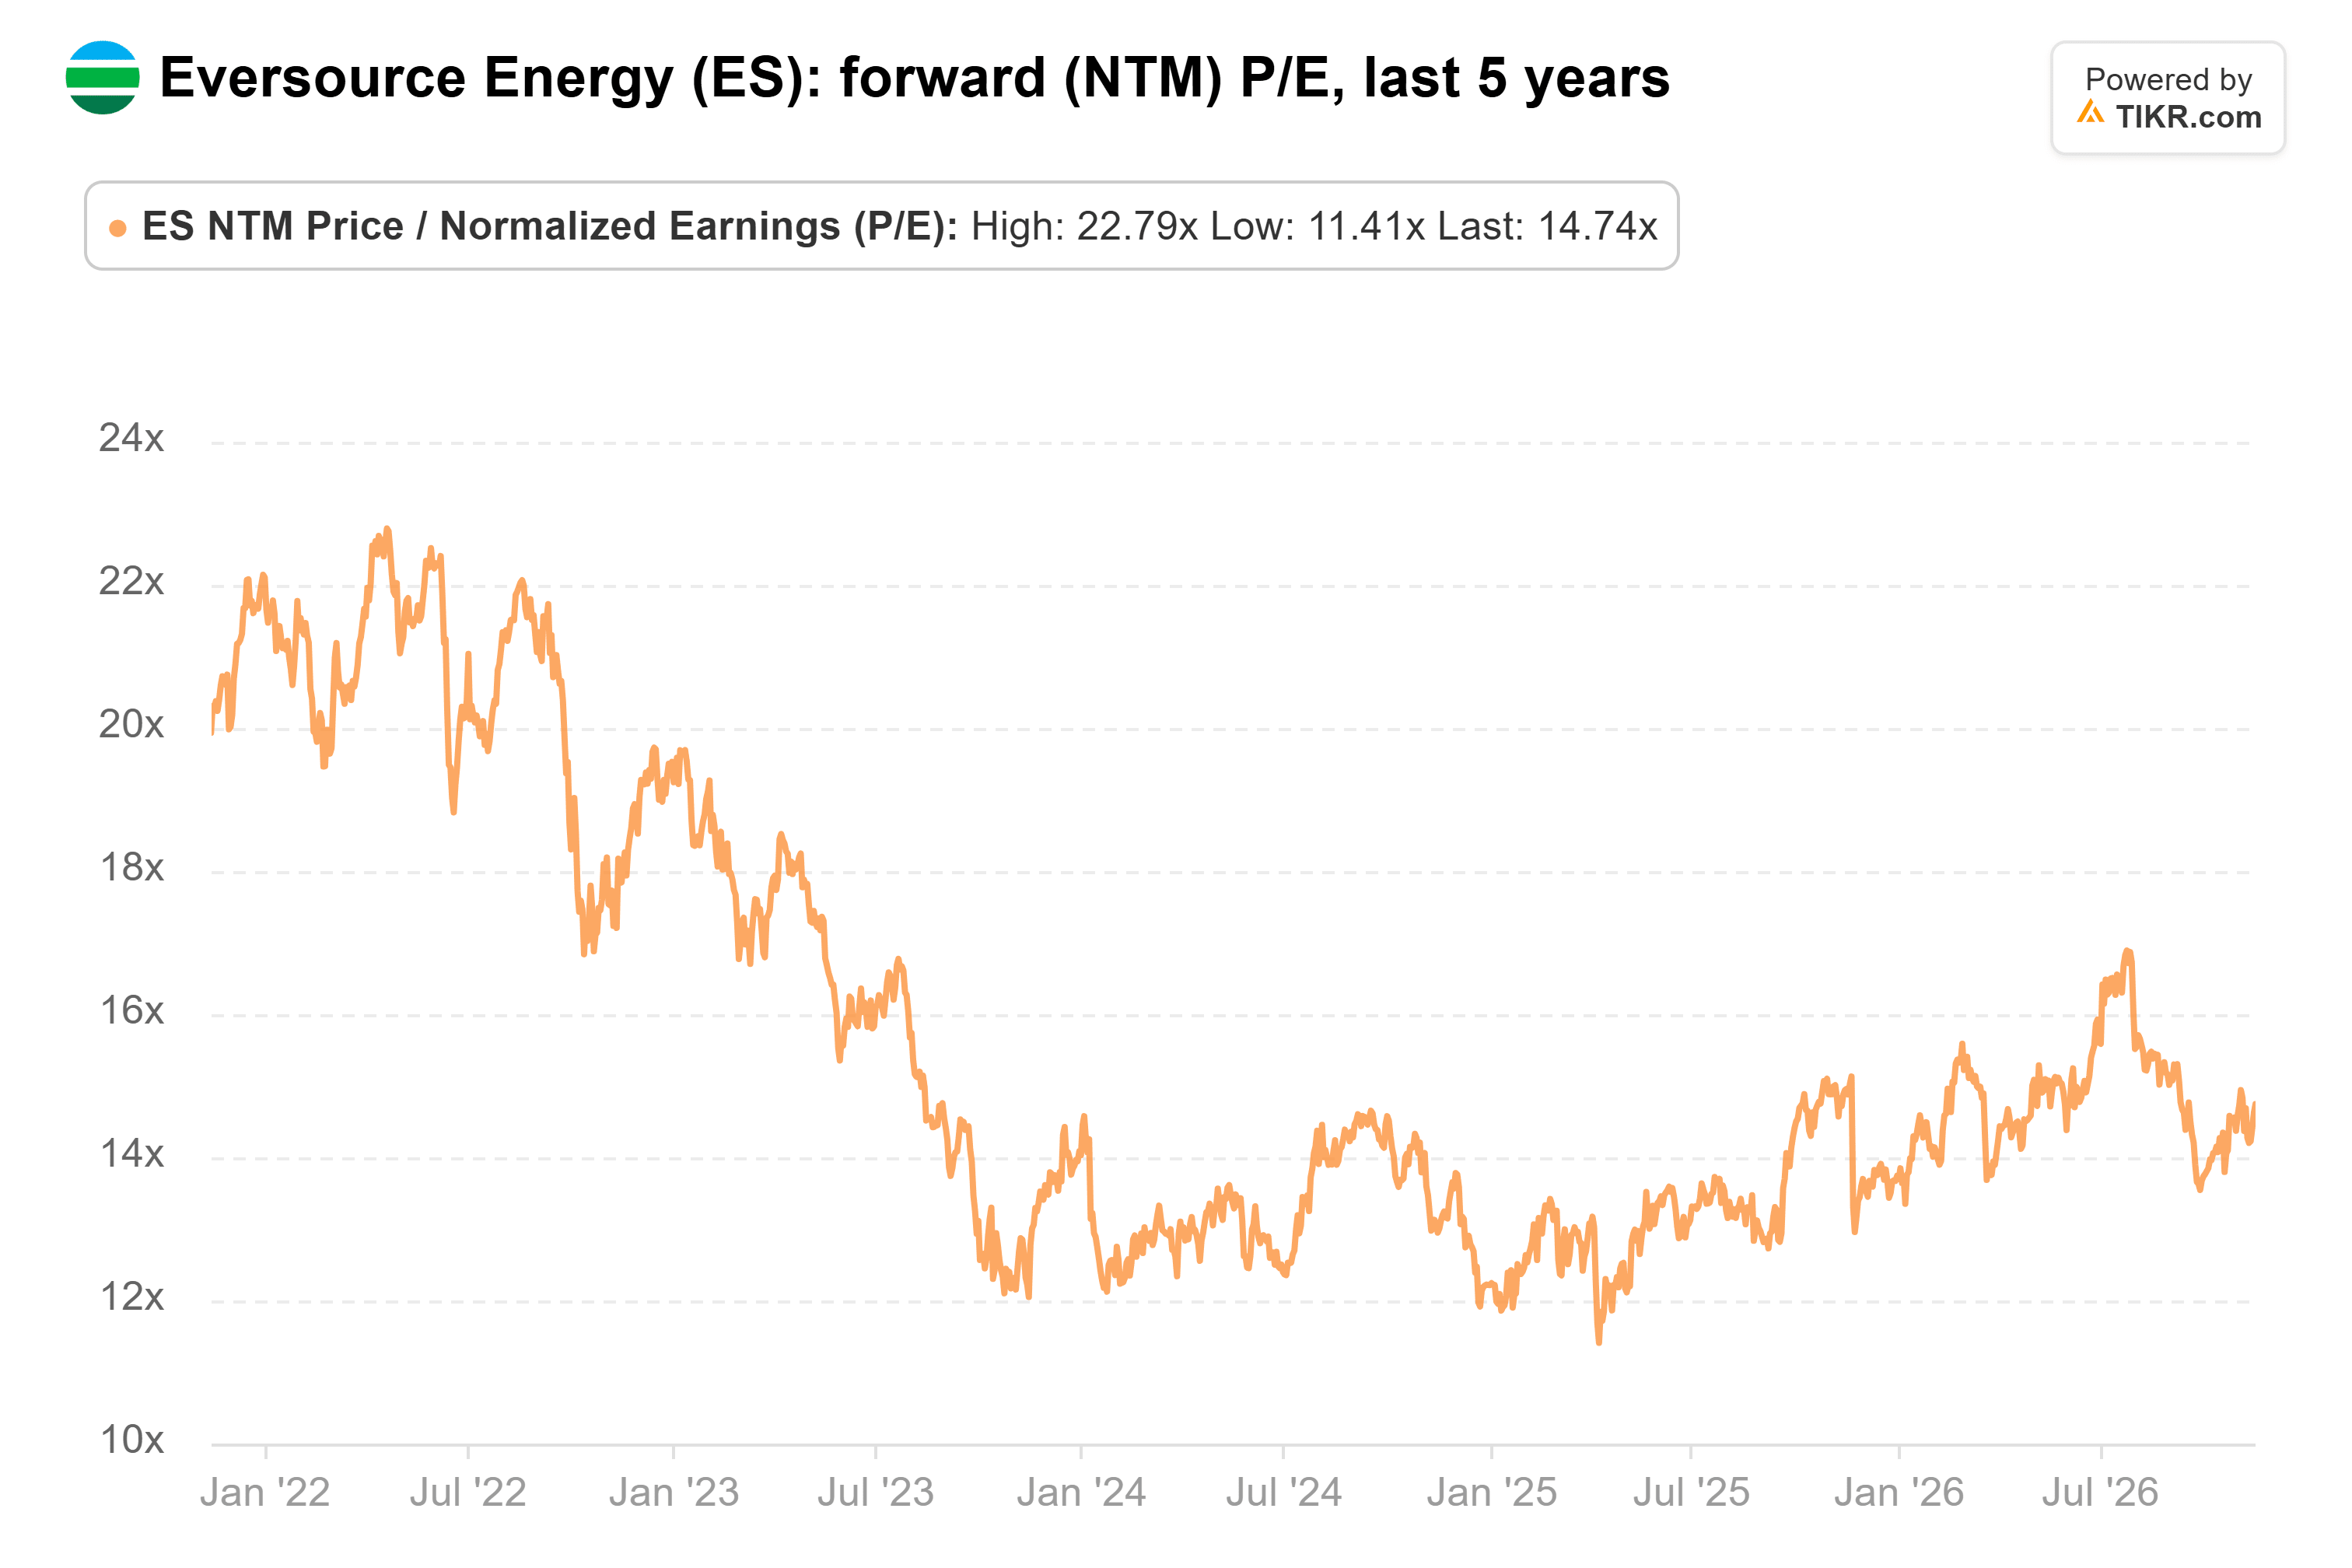
At 15x, it trades below its 16x average and far from its 23x peak in April 2022, so buyers aren’t paying up for a payout ratio climbing toward 68%.
Connecticut regulators are expected to rule on Eversource’s first CL&P rate case since 2018 in June. After this year’s disallowed storm costs, that ruling will show us how much room Eversource has to keep the raises coming.
Forget Eversource Energy: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Eversource Energy isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!