


Bank of America (BAC) stock fell about 4% in premarket trading on Wednesday, October 14, to around $52, after the bank’s third-quarter profit came in below estimates. Reported earnings were $0.91 a share, down from $1.04 a year earlier, including a $1.2 billion charge tied to the anti-money-laundering penalty FinCEN announced on Tuesday alongside action by the OCC. A separate sanctions settlement with OFAC added $11.6 million.
The fine grabbed the headlines, but it doesn’t explain the miss. Strip it out and Bank of America earned $1.08 a share, still short of the $1.10 analysts expected. That breaks its recent run of earnings beats.
The Bond Desk Missed Its Own Guide
At the Barclays conference on September 14, CEO Brian Moynihan guided sales and trading to roughly flat year over year, about $5.4 billion, and investment banking fees to $1.6 billion to $1.8 billion. Investment banking landed at $1.8 billion, the top of that range. Trading fell 5% to $5.1 billion, dragged down by fixed income, currencies and commodities.
That’s a $300 million shortfall against a forecast made barely two weeks before the quarter closed. The fine is the bigger number, but it’s a one-off: $0.17 a share, booked once.
Net Interest Income Is Still Doing the Heavy Lifting
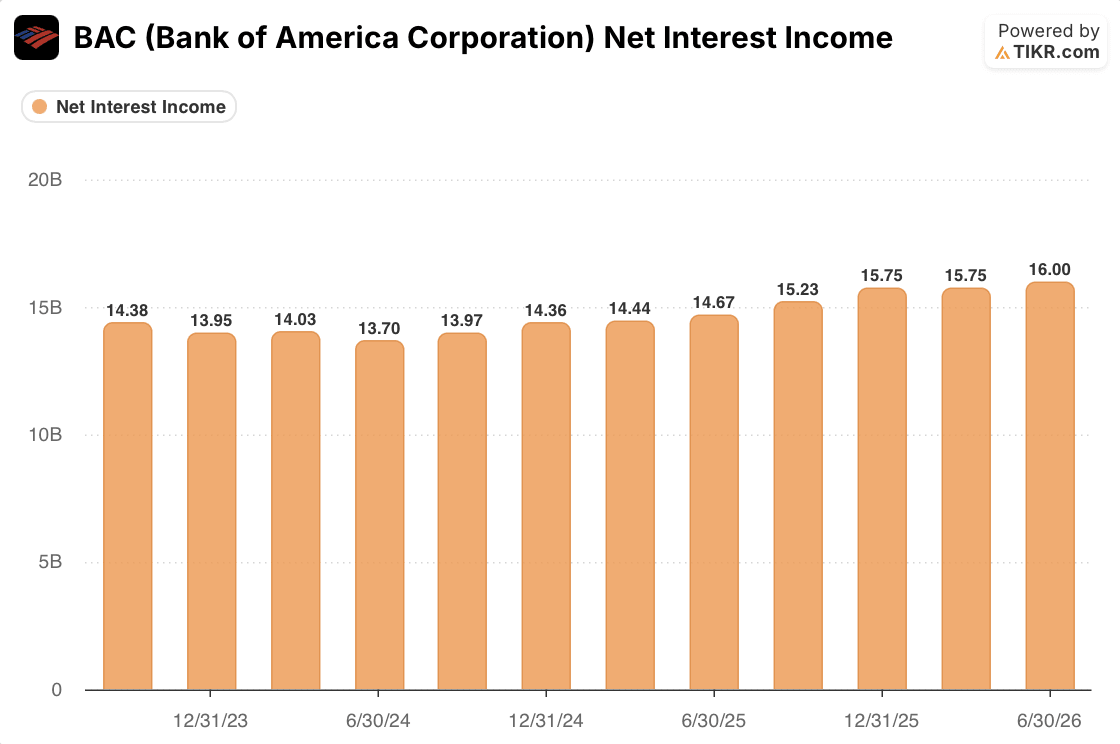
Net interest income has climbed from $13.70 billion in the June 2024 quarter to $16.00 billion in Q2 2026, with only a flat stretch at the turn of the year. Wednesday’s $16.4 billion was up 8% from a year earlier. That line is now about 55% of revenue, so one soft trading quarter barely dents the earnings base.
Average loans grew 6%, and the bank returned $8.3 billion to shareholders, including $6 billion of buybacks.
Is This a BofA Problem or a Bond Market Problem?
Partly the market. JPMorgan Chase (JPM) reported a surprise drop in fixed-income revenue on Tuesday, down 4% to $5.4 billion. But Citigroup (C) grew fixed-income markets revenue 4% to $4.4 billion in the same quarter, so the bond selloff doesn’t account for all of BofA’s shortfall.
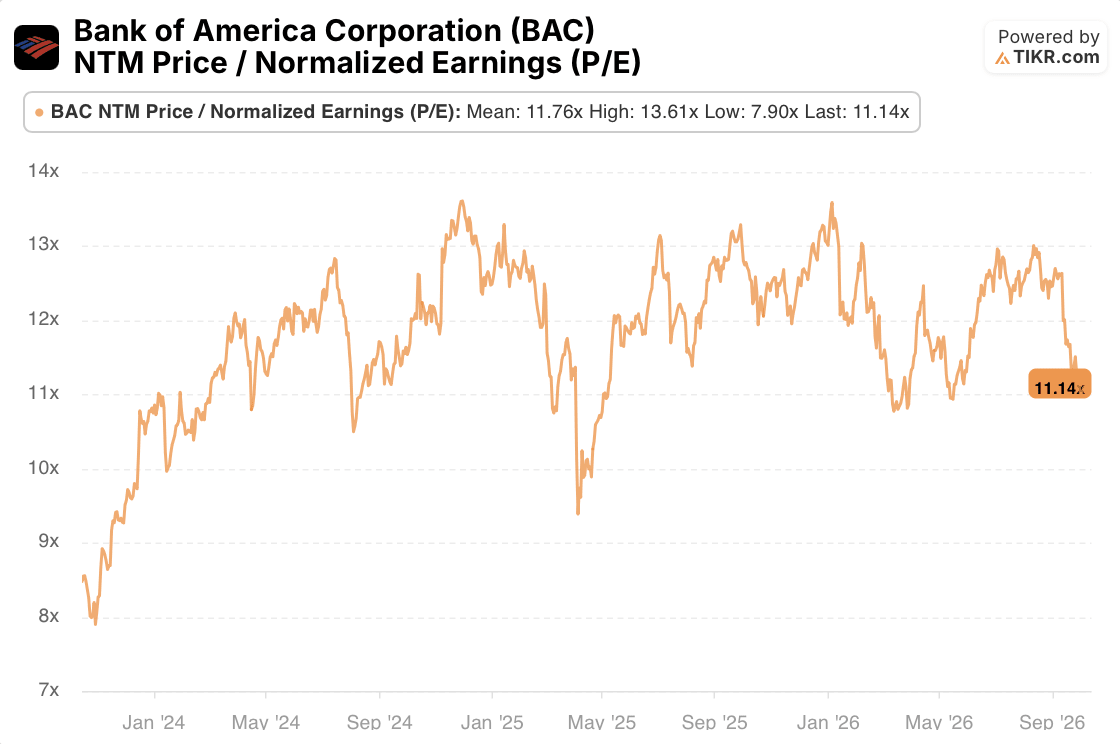
The market wasn’t paying for a trading rebound anyway. Going into the report, the stock traded at about 11.1x forward normalized earnings, below its 11.8x average since late 2023 and well off its 13.6x peak.
What BAC Stock Is Worth Without a Re-Rating
The question I wanted answered: if Bank of America never gets its old multiple back, does the stock still work? So I set the exit P/E at 11x, close to its pre-earnings forward multiple, and let the return come only from earnings growth, buybacks and dividends. I have revenue growing 4.9% a year through 2030, slower than net interest income alone, because I’m giving trading and dealmaking little help. The net income margin stays at 27.1%.
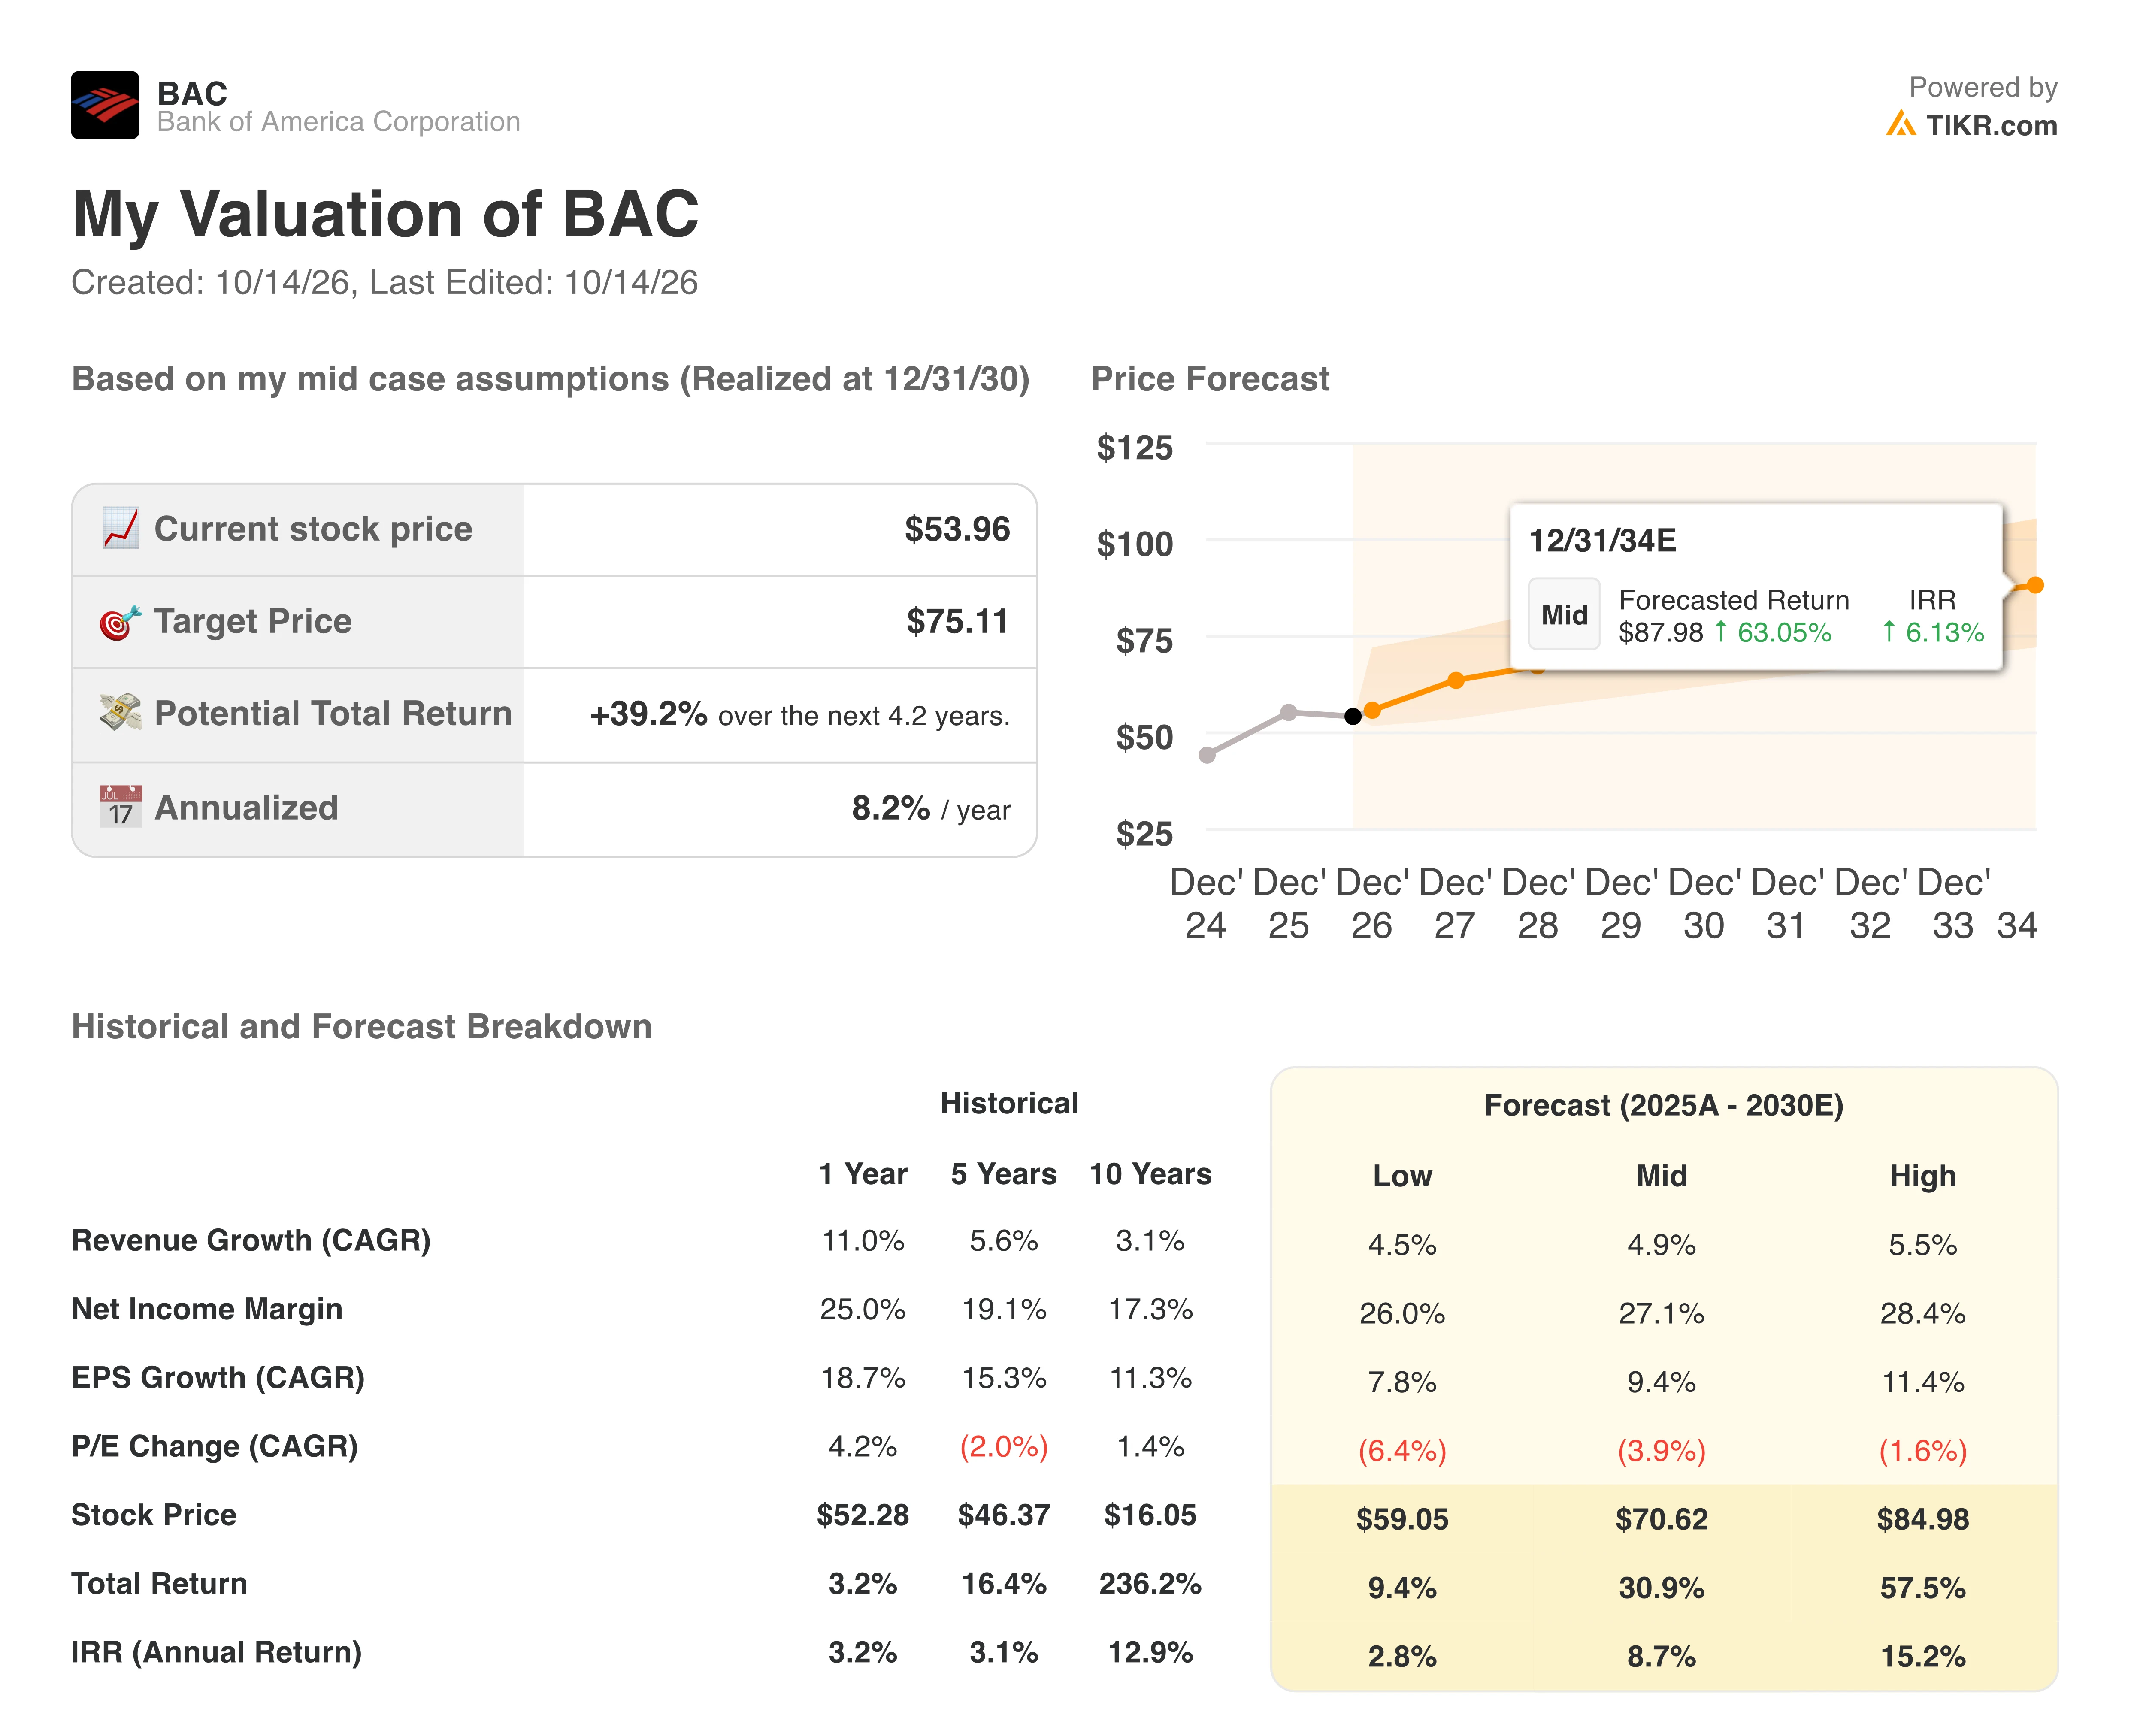
That gets me to about $75 a share by the end of 2030 with dividends included, or about $71 for the share price alone. Measured from the $53.96 pre-earnings close, that’s a 39.2% total return, or about 8.2% a year. TIKR’s September model had $80 for the same date from $58. The target is lower, but the return is almost unchanged, because the stock has already given back the difference.
Conclusion
A 4% drop is a heavy reaction to a quarter where the fine was a one-off and the trading shortfall against Moynihan’s own guide works out to roughly 3 cents a share after tax. The bank’s biggest engine, net interest income, is still growing. At 11x earnings, about 8% a year looks like a fair base case rather than a bargain. The fourth-quarter report in January is the test: if fixed income stabilizes while net interest income keeps climbing, today’s price will look too cautious.
Think my growth or multiple is too conservative? Build your own Bank of America model in about 60 seconds on TIKR for free, starting from analysts’ consensus estimates. Learn more here.
So what is Bank of America stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what BAC stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Bank of America Corporation for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


