Key Takeaways
- Badger Meter shares jumped 7% today after third-quarter earnings of $1.24 a share beat the $1.22 consensus, even though sales of $235.9 million missed.
- Investors are looking past an uneven 2026 and paying for rising margins and management’s promise of growth into 2027.
- Operating margin rose to 20.2% from 19.6% a year earlier, and the dividend went up 10% for the 34th straight year.
- Analysts expect revenue to grow about 8% in 2027, and the stock’s forward P/E is still well below its five-year average.
Badger Meter (BMI) reported third-quarter results before Thursday’s open, and the stock is up 7% today, with the Nasdaq down about 2%.
That’s a sharp turn for a stock that was down about a quarter in 2026 through Wednesday’s close.
What exactly happened
Here’s Badger Meter’s third quarter, compared with a year earlier:
- Sales were flat at $235.9 million, below the $240.78 million consensus.
- Operating margin rose to 20.2% from 19.6%.
- EPS rose 4% to $1.24, beating the $1.22 consensus.
- The annual dividend went up 10% to $1.76 a share, its 34th straight yearly raise, and the company bought back about $55 million of stock in the quarter.
Leave out UDlive, the business it bought in May, and utility water sales fell 3%. Management blamed the uneven pace of utilities’ smart-meter projects.
TIKR tracks 10 analysts on Badger Meter. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Badger Meter, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Badger Meter’s Analyst Ratings
Margins did the heavy lifting
Sales didn’t grow, but profit did. Gross margin rose 1.2 percentage points to 41.9%, and costs for selling, engineering and administration fell 2% without UDlive.
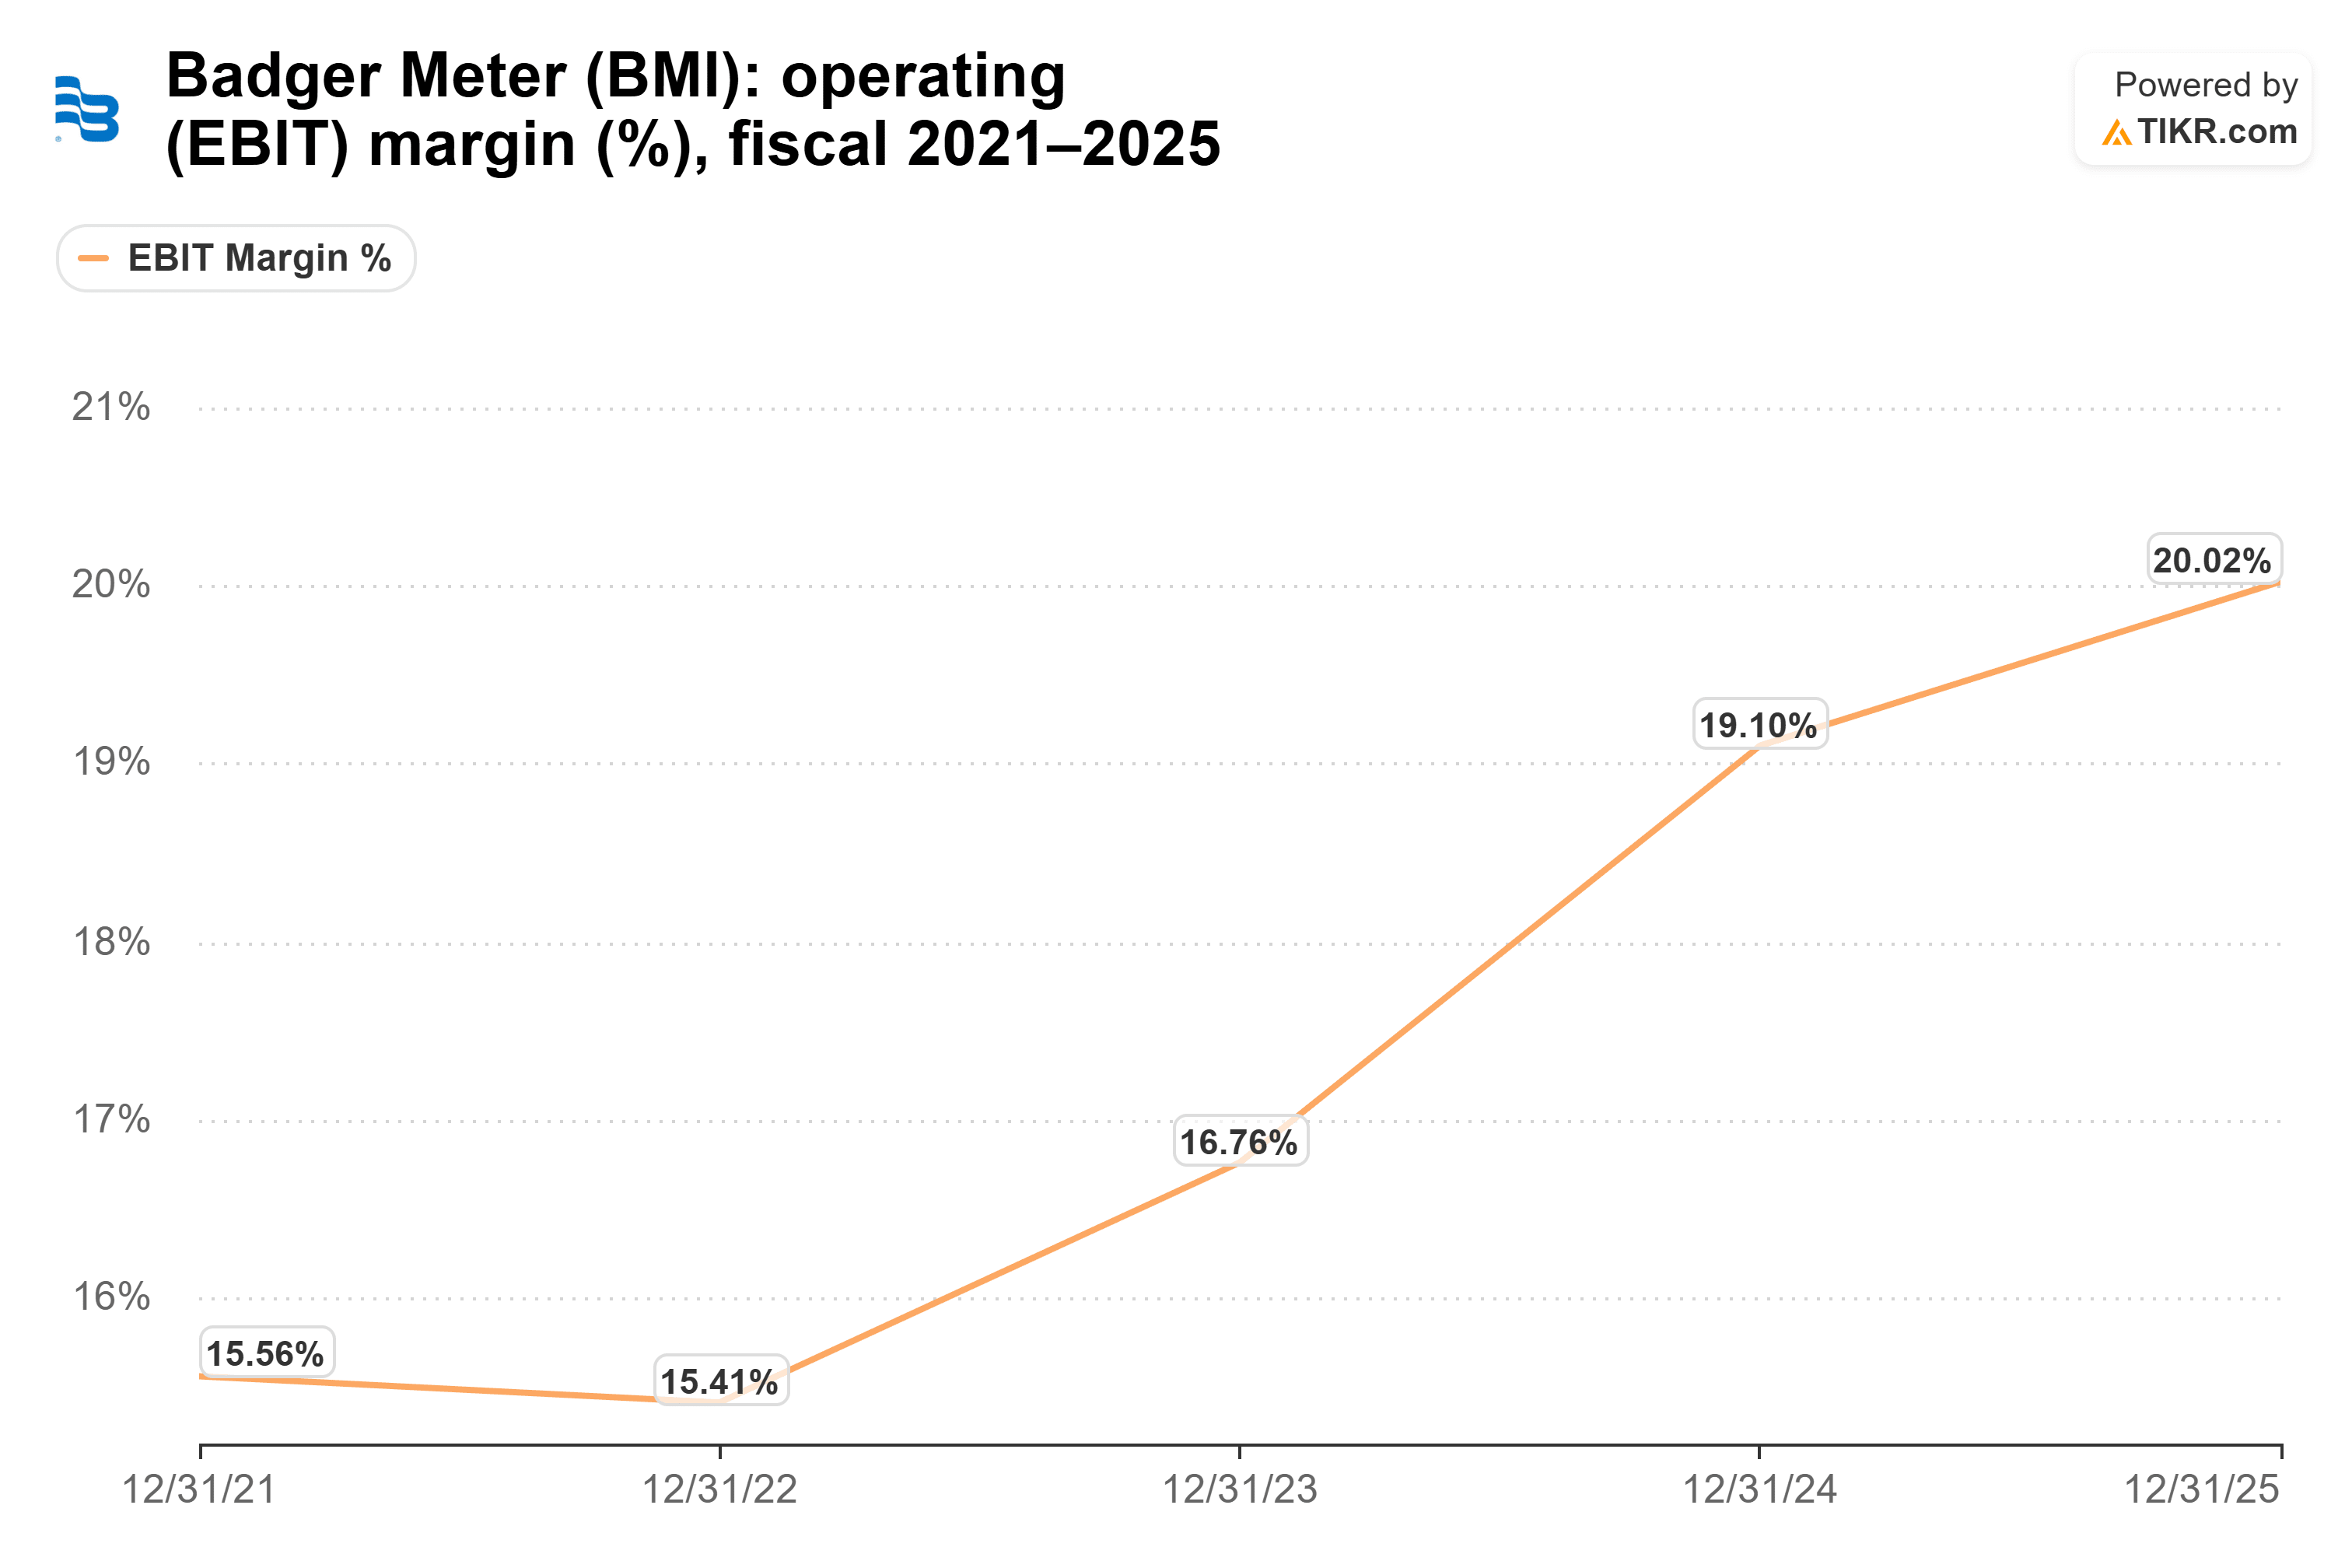
That fits a long run of wider margins. Badger Meter’s operating margin went from about 16% in 2021 to 20% in 2025…
The promise is 2027
CEO Kenneth Bockhorst said he expects Base revenue (the company’s figure without UDlive) to grow in the fourth quarter, both from the third quarter and from a year earlier. He also said Badger Meter expects to “sustain this growth momentum into 2027.”
Analysts already agree. Consensus has revenue slipping to $911 million this year from $917 million in 2025, then rising about 8% to $981 million in 2027…

The miss could pull that 2026 estimate down a little, but nothing in the release argues against the 2027 number.
The recovery isn’t priced in yet
At Wednesday’s close, Badger Meter traded at 28x forward earnings. That’s near April’s five-year low of 24x and far below its five-year average of 42x…

Even after today’s jump, it’s closer to 31x.
There are still risks. Electronics costs are putting pressure on materials, and project timing has made 2026 a lumpy year.
My take: Margins are still climbing and growth is expected back in 2027, but the stock is still priced well below its usual multiple. I think today’s jump has room to run.
Of course, the fourth-quarter report early next year will be the first real test of that promise.
So what is Badger Meter stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Badger Meter could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!