Key Takeaways
- Arm Holdings fell 19% in a week as Intel’s weak fourth-quarter outlook hit chip stocks.
- Intel blamed short supply of packaging substrates, a part Arm also needs for its own AGI CPU.
- Arm’s fiscal second-quarter revenue of $1.44 billion beat the top of its guidance range, though royalties grew just 8%.
- Back near its three-year average forward P/E, Arm looks like a better buy than it did in June, with first AGI CPU production sales due by March as the next test.
Arm Holdings (ARM) is down 19% in the past week with no bad news of its own. The trouble started with Intel (INTC), which guided fourth-quarter revenue to $15 billion to $16 billion on Oct. 29, short of the roughly $17 billion analysts expected.
Intel is down 39% over the week, and chip stocks fell with it. Then Arm reported after the close on Wednesday, Nov. 4, and the news was mostly good.
Intel’s shortage is Arm’s shortage too
Intel pinned its outlook partly on short supply of the substrates chips are packaged on. CEO Rene Haas called substrates tight on Arm’s July call, and that matters now that Arm sells a chip of its own. In July, its AGI CPU had more than $2 billion of demand across fiscal 2027 and 2028 (the years to March), but capacity secured for only about $1 billion.
On Nov. 4, Arm said its confidence in reaching up to $2 billion of AGI CPU revenue over those two years had risen, helped by additional supply. Intel’s data center and AI revenue still jumped 78%, a sign the server CPU demand Arm sells into is real.
Arm beat the top of its range
Fiscal second-quarter revenue (to September) rose 27% to $1.44 billion, above the top of Arm’s guided range. Licensing and other revenue jumped 50% to $773 million, against the roughly 30% growth Arm had guided.
Royalties were the soft spot, up 8% to $670 million against guidance for the low teens, as memory prices weighed on phones. Arm expects royalty growth to slow to the low single digits in the December quarter.
TIKR tracks 43 analysts on Arm Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Arm Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Arm Holdings’ Analyst Ratings
A Fairer Price, With a Test Due by March
Going into the report, analysts expected normalized EPS to rise from $1.77 in fiscal 2026 to $3.06 in fiscal 2028.
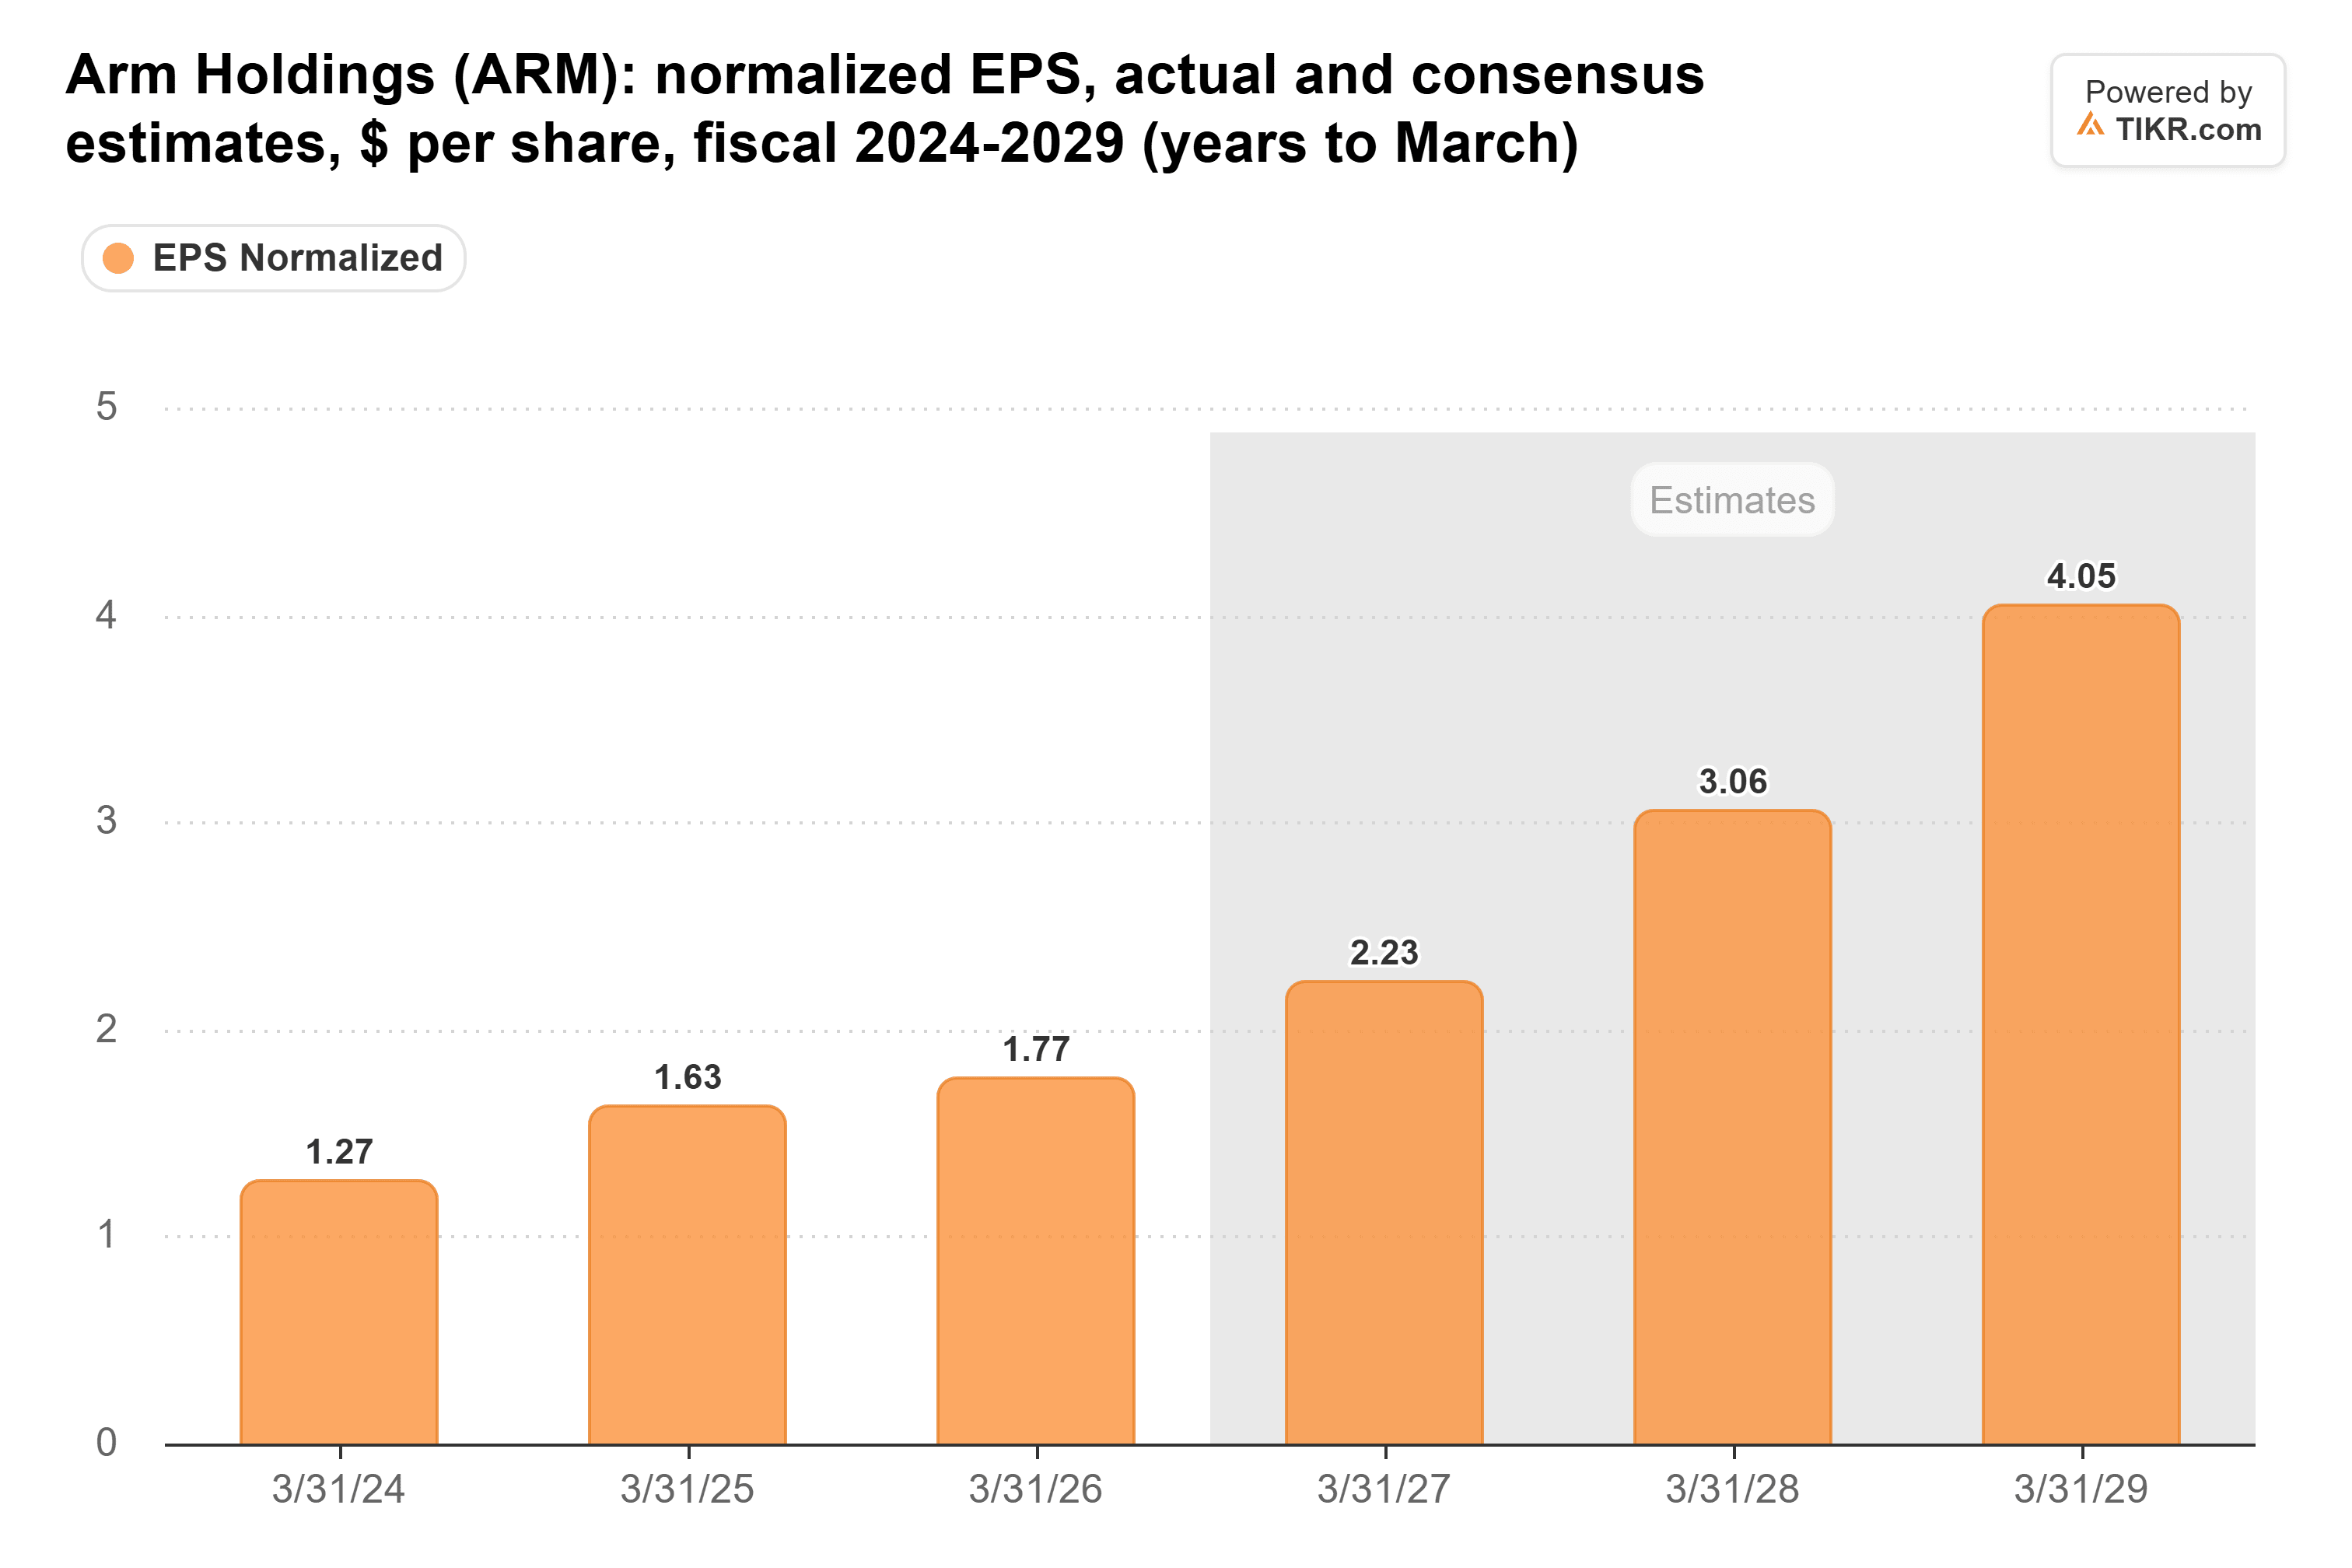
Arm guided third-quarter revenue to $1.54 billion, about in line with the $1.53 billion analysts expected, so the selling hit the multiple rather than the earnings outlook. Its forward P/E was 82x on Monday, Nov. 2, down from 202x at its June peak and just under its three-year average of 85x.
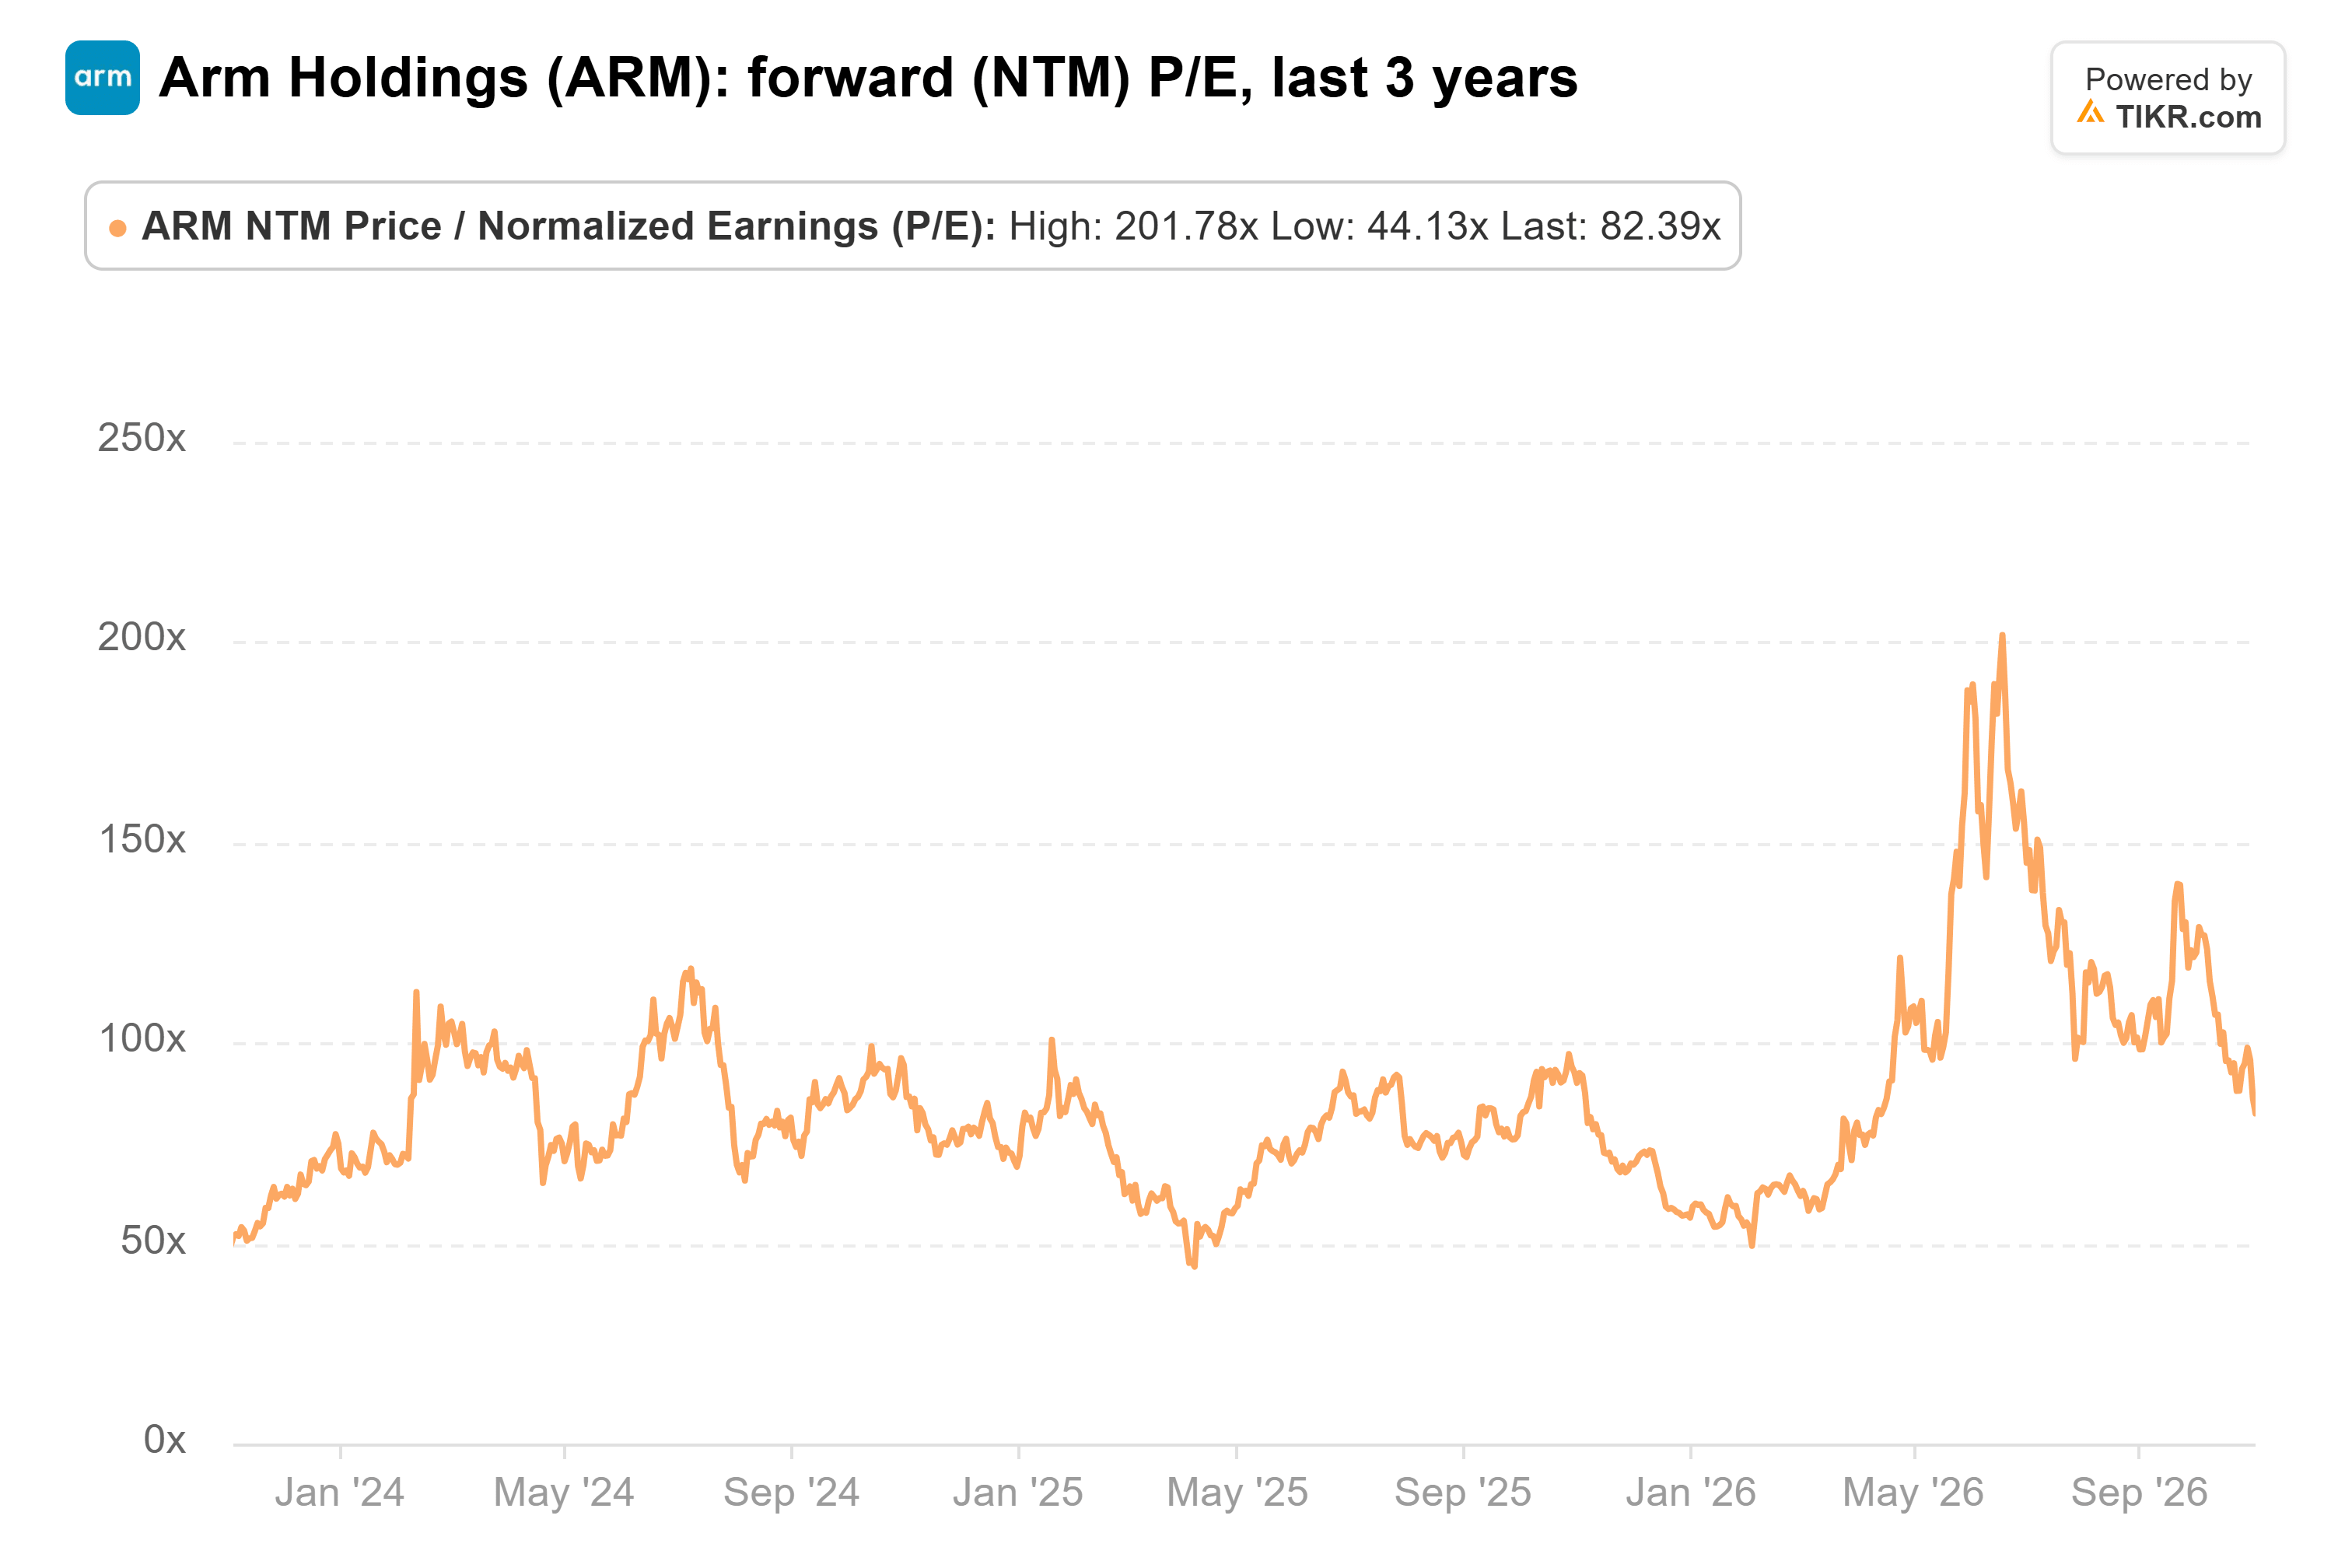
Wednesday’s 5% drop took it lower still. The mean analyst target has held near $291, 52% above Wednesday’s close.
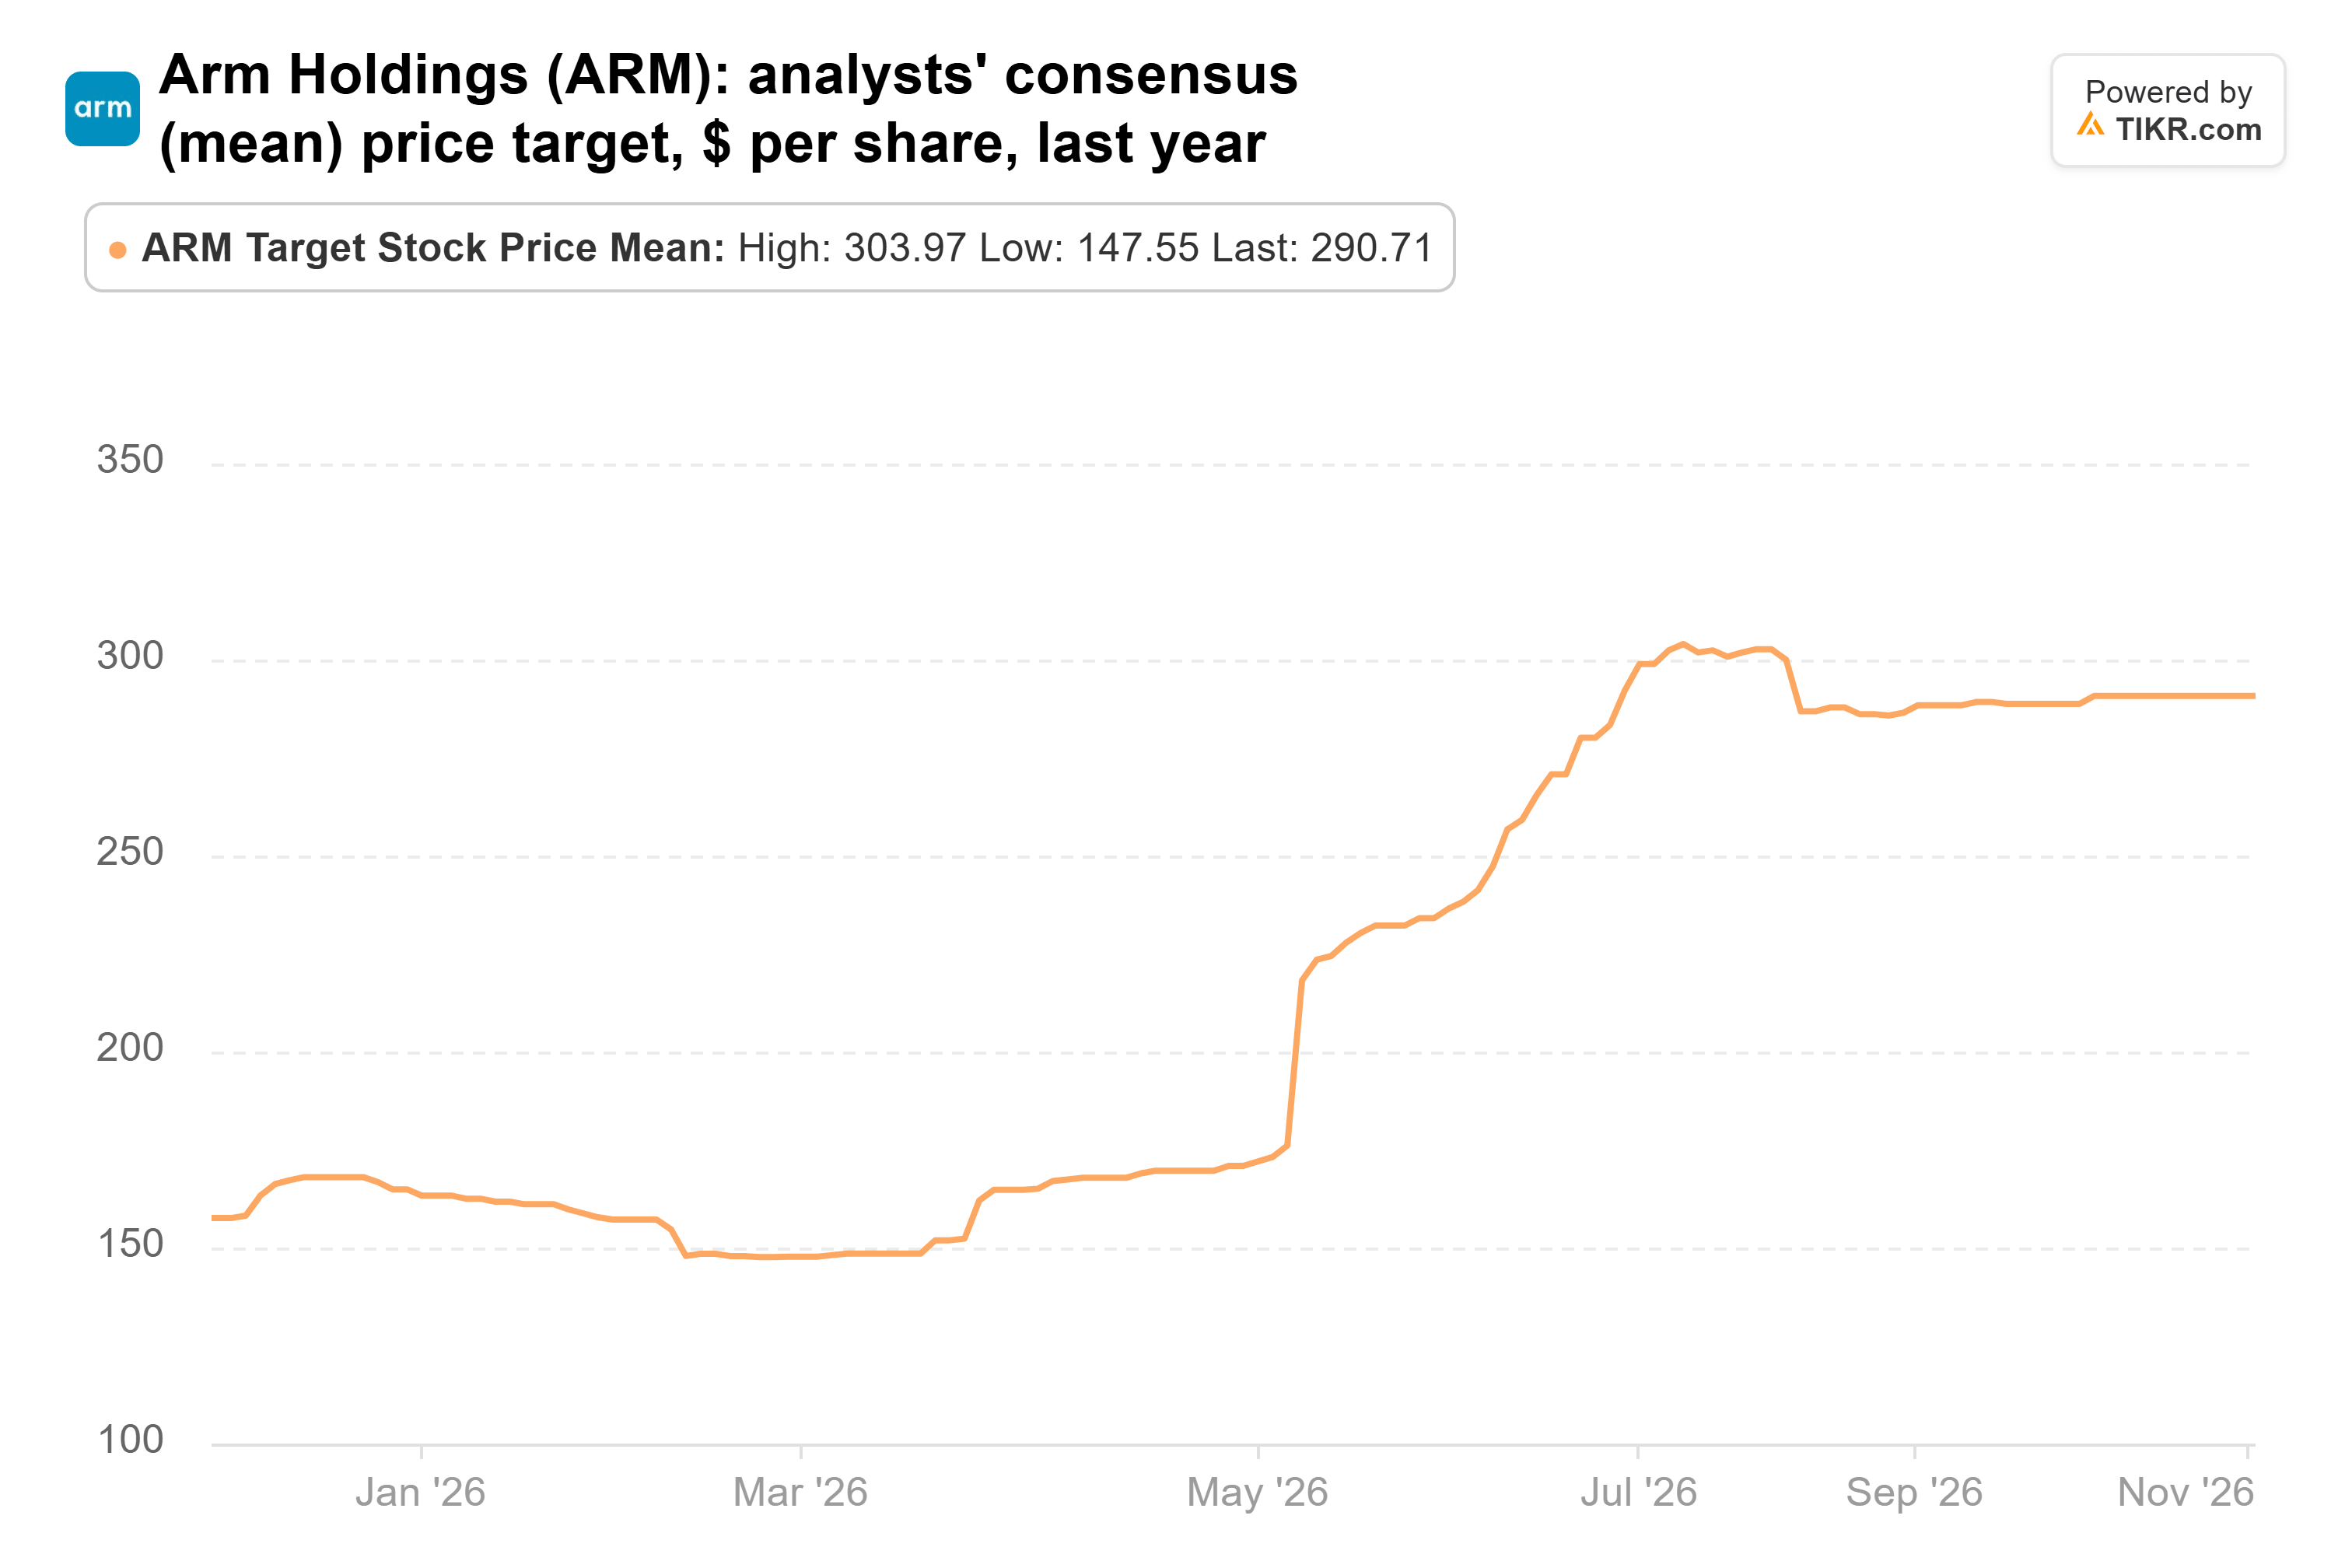
At this multiple, Arm looks like a reasonable buy for patient investors. The first AGI CPU production sales, due in the January-to-March quarter, will show whether up to $2 billion of demand turns into revenue.
Of course, a Delaware judge has yet to rule on whether Qualcomm, about 9% of Arm’s fiscal 2026 revenue, can stop paying it royalties for up to five years.
So what is Arm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Arm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!