Key Takeaways
- Jensen Huang resigned as Nvidia’s CEO on November 12, and chip stocks like AMD and Broadcom fell sharply. That puts Arista Networks’ pitch of working with many chip vendors in the spotlight.
- Arista’s third-quarter revenue rose 58.5% to $3.66 billion, its fastest growth since its IPO, and management guided 2027 revenue to about $18.5 billion.
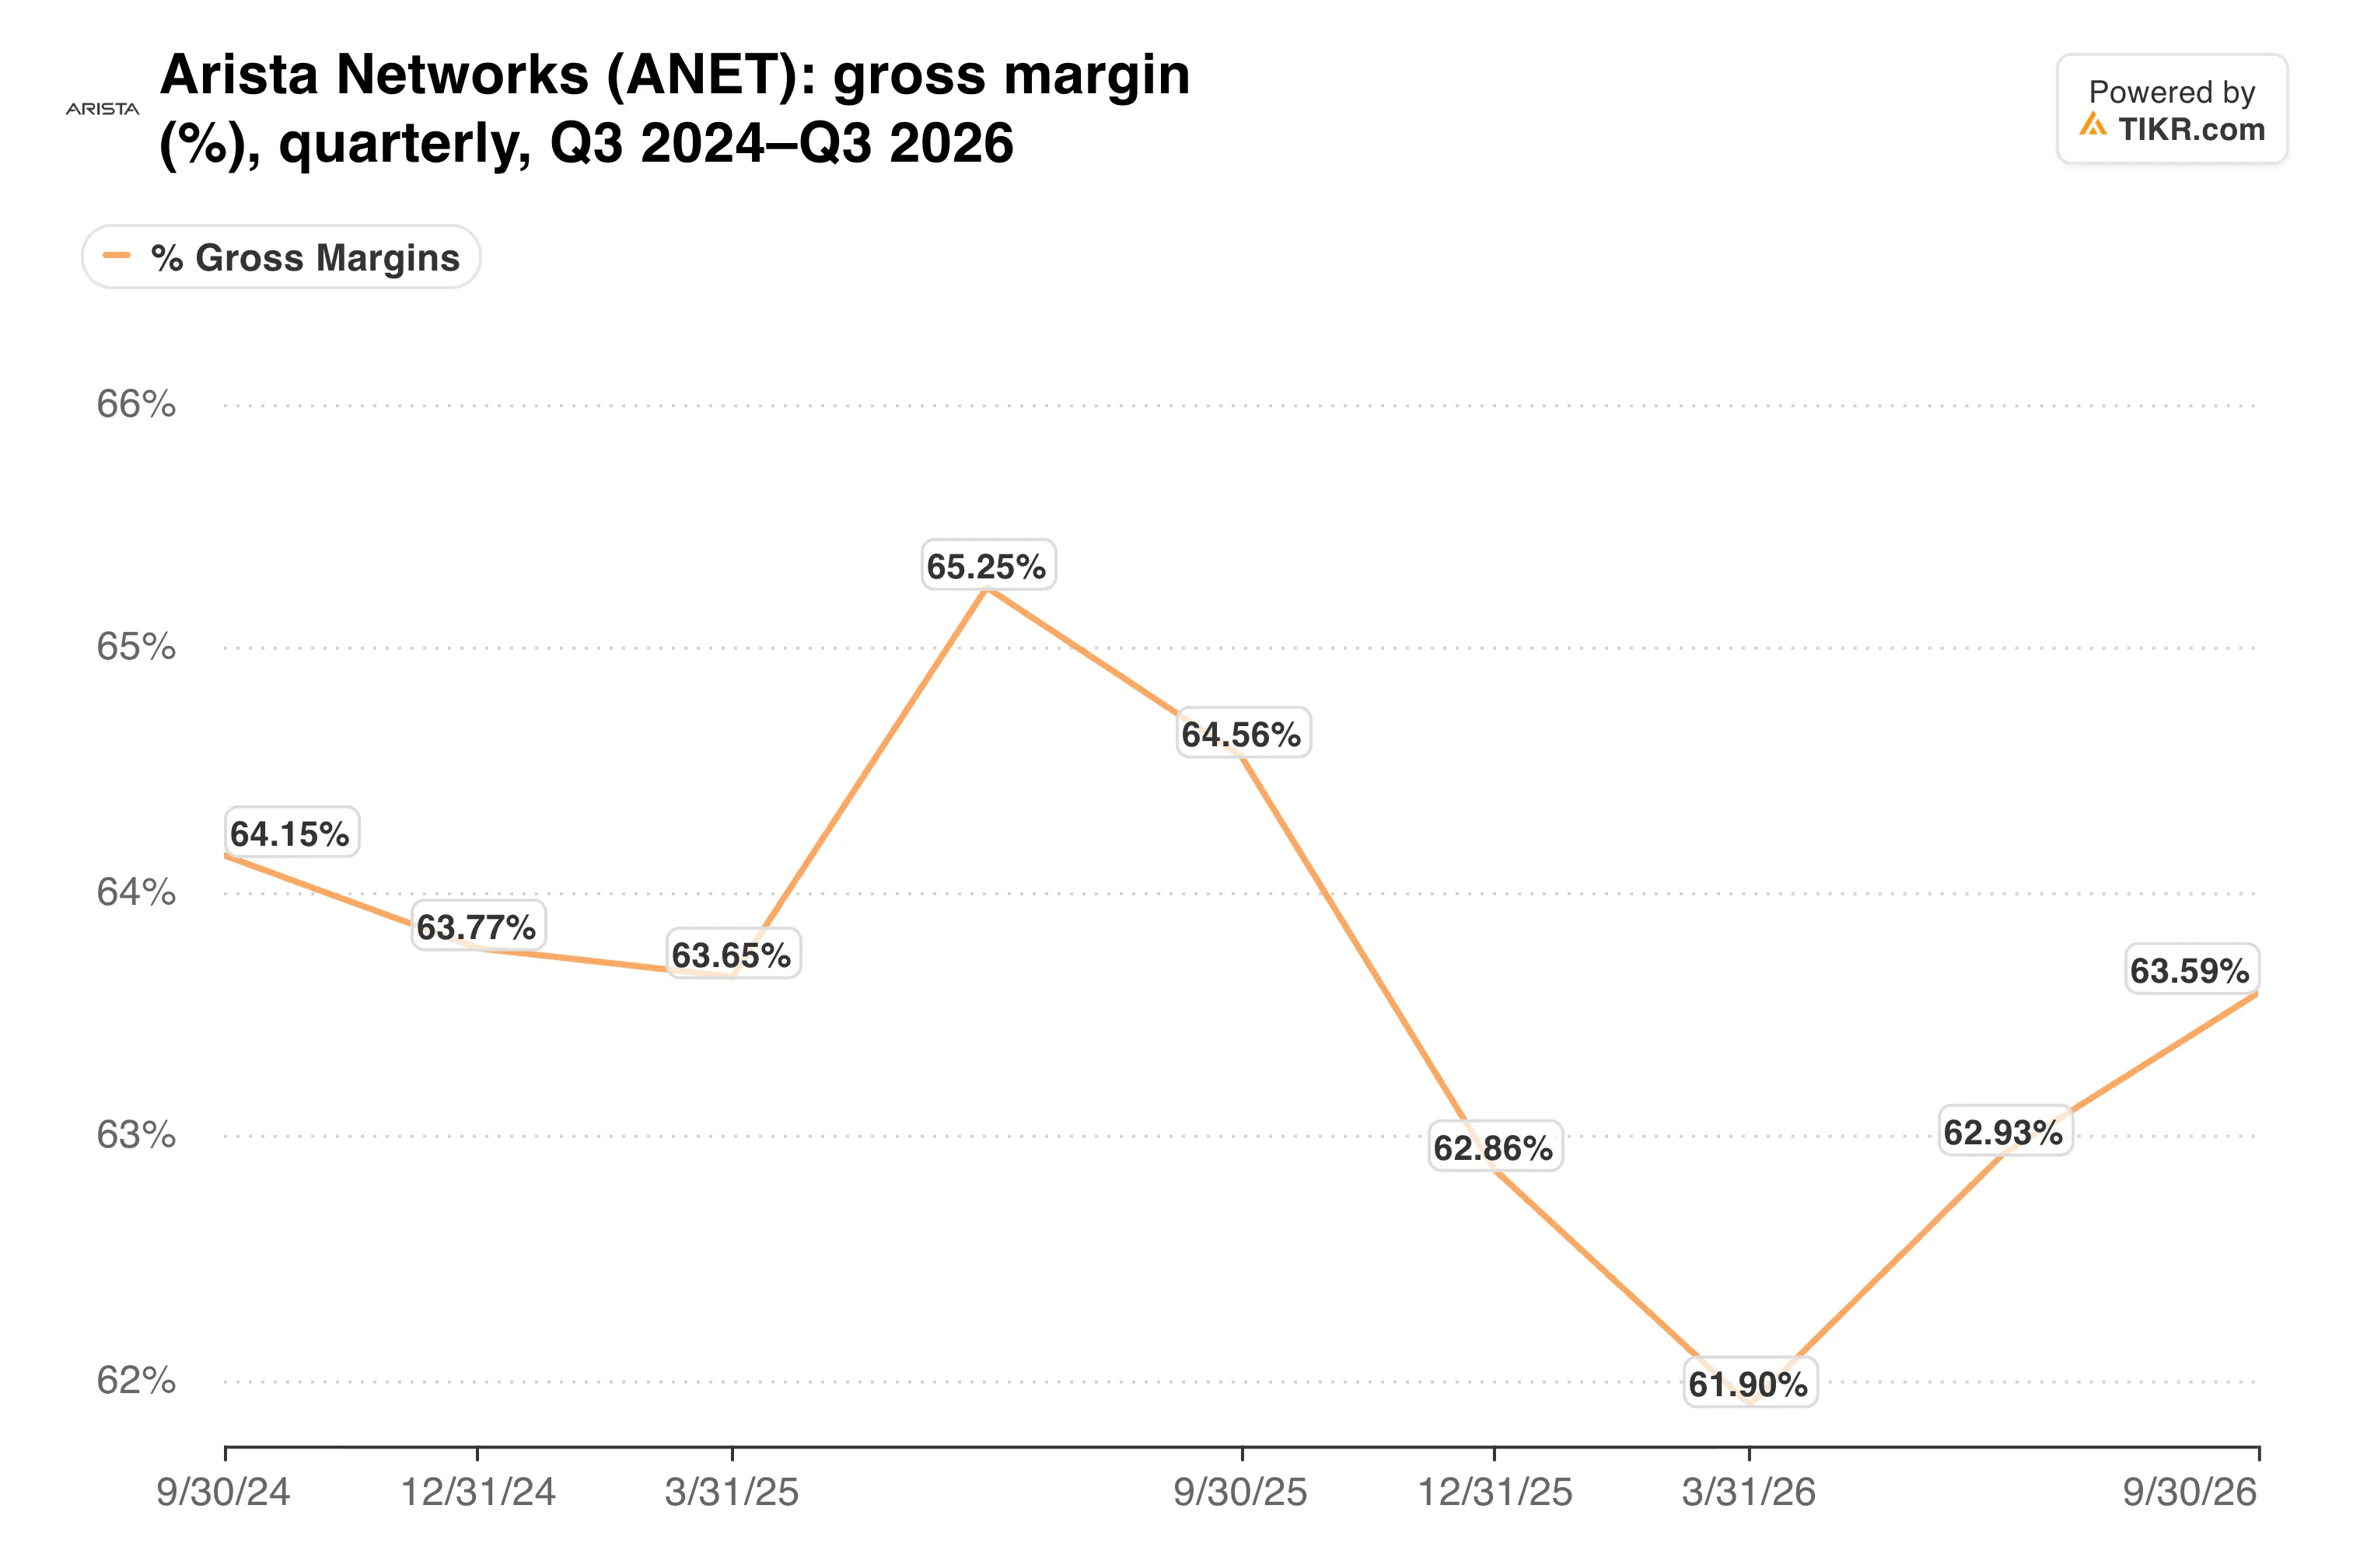
- Non-GAAP gross margin slipped to 64.0% from 65.2%, while two customers made up 42% of Arista’s 2025 revenue.
- Nvidia’s report next week, its first under interim CEO Colette Kress, is the next read on AI networking demand before Arista reports in February.
Nvidia (NVDA) lost its founder as chief executive this week, and the whole AI hardware trade felt it.
On November 12, the company said Jensen Huang had resigned, with CFO Colette Kress stepping in as interim CEO. By Friday afternoon, the Philadelphia semiconductor index was down 4%, and Advanced Micro Devices (AMD) and Broadcom (AVGO) were sharply lower.
Arista Networks (ANET) sits right in the middle of that trade. Nvidia competes with it in AI Ethernet switching, while AMD and Broadcom helped it launch new open AI racks last quarter.
So the question is simple. Does a shakeup at Nvidia hurt Arista, or does it make Arista’s open, multi-vendor pitch look smarter?
Arista’s record quarter in numbers
Arista reported on November 3, and its growth was the fastest since its IPO.
- Revenue rose 58.5% to $3.66 billion, well above its own $3.3 billion guidance.
- Non-GAAP EPS reached $1.20, up from $0.77 a year earlier.
- Operating margin on a non-GAAP basis improved to 49.1% from 48.6%.
CEO Jayshree Ullal said the quarter came in “surpassing even my high expectations.” Product sales did the heavy lifting…
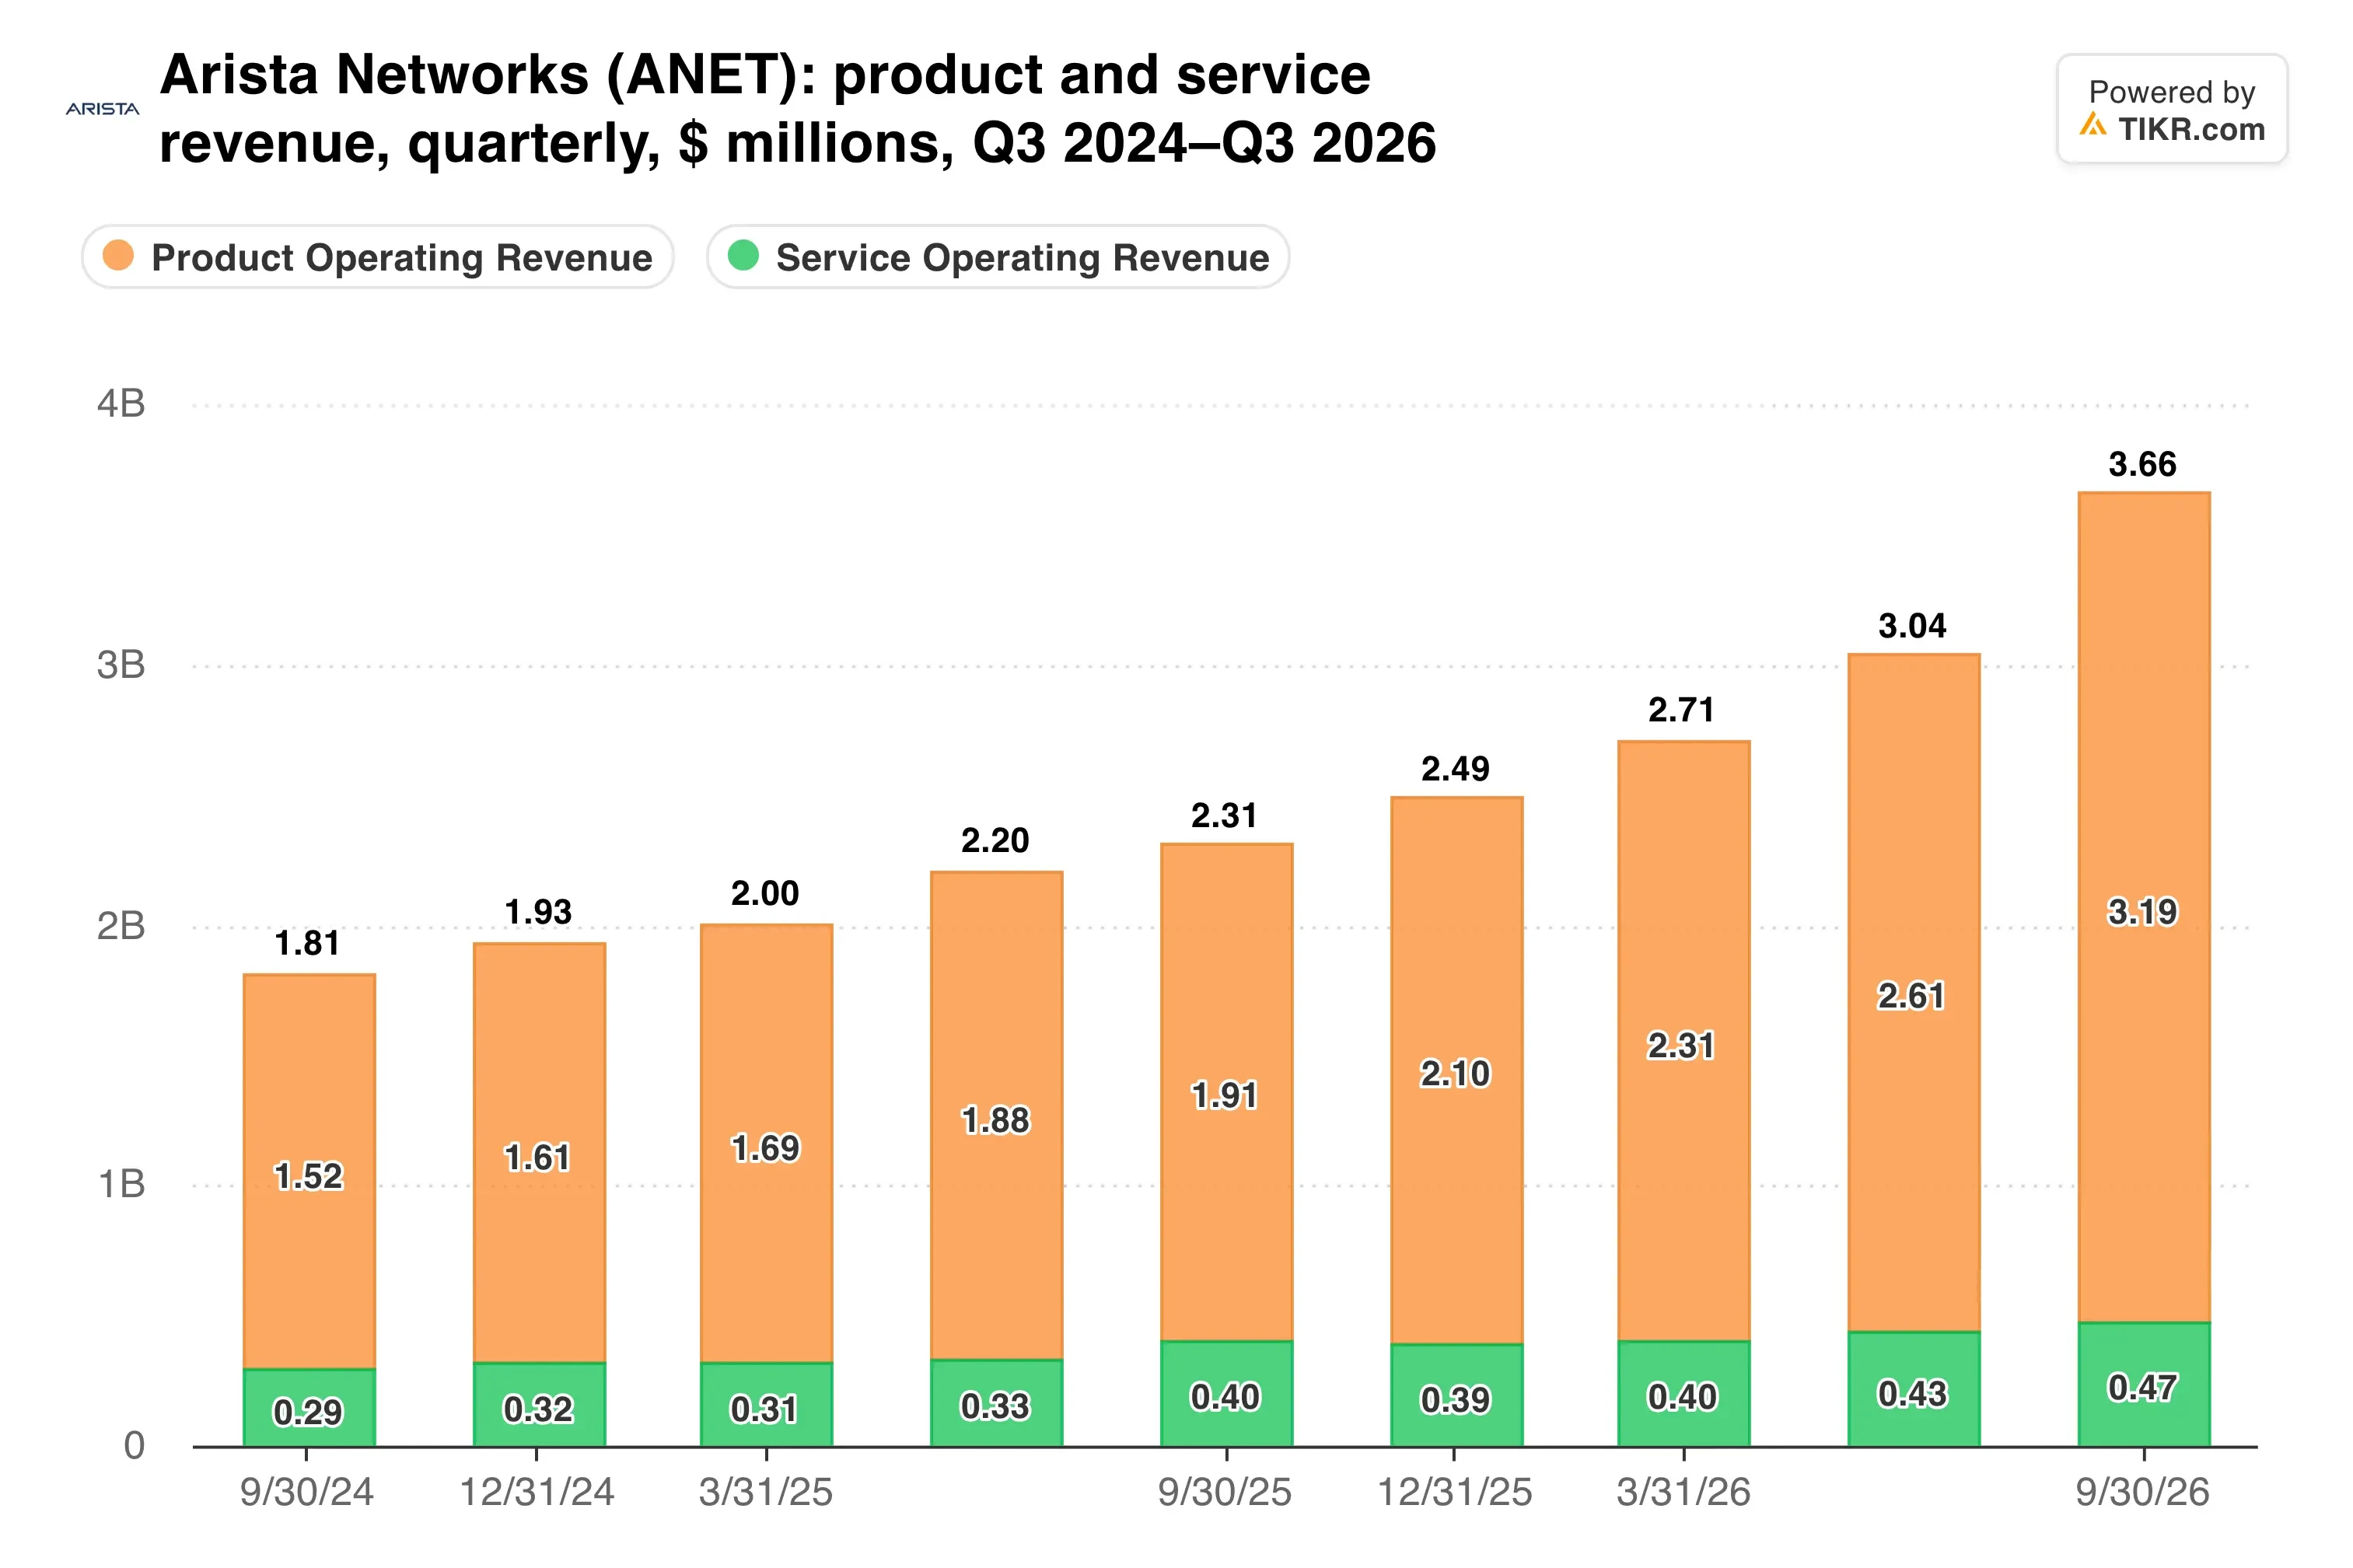
Product revenue grew 66.9% to $3.19 billion, while services grew 17.9%. Fourth-quarter guidance of $3.9 billion to $4.0 billion implies about 8% more sequential growth at the midpoint.
A bet on every accelerator
Arista’s pitch is that AI clusters will run on many kinds of accelerators, and every one of them needs a network.
Last quarter it launched open, liquid-cooled rack designs with AMD, Broadcom, Meta, Microsoft, Qualcomm and others. Its Etherlink SU-144 rack links up to 144 accelerators in a single hop.
That strategy shows up in the 2027 plan. On its earnings call, management guided revenue up 38% to 40%, to about $18.5 billion. It also expects AI networking revenue to double to roughly $7 billion.
Nvidia, though, is still growing much faster at the top line.
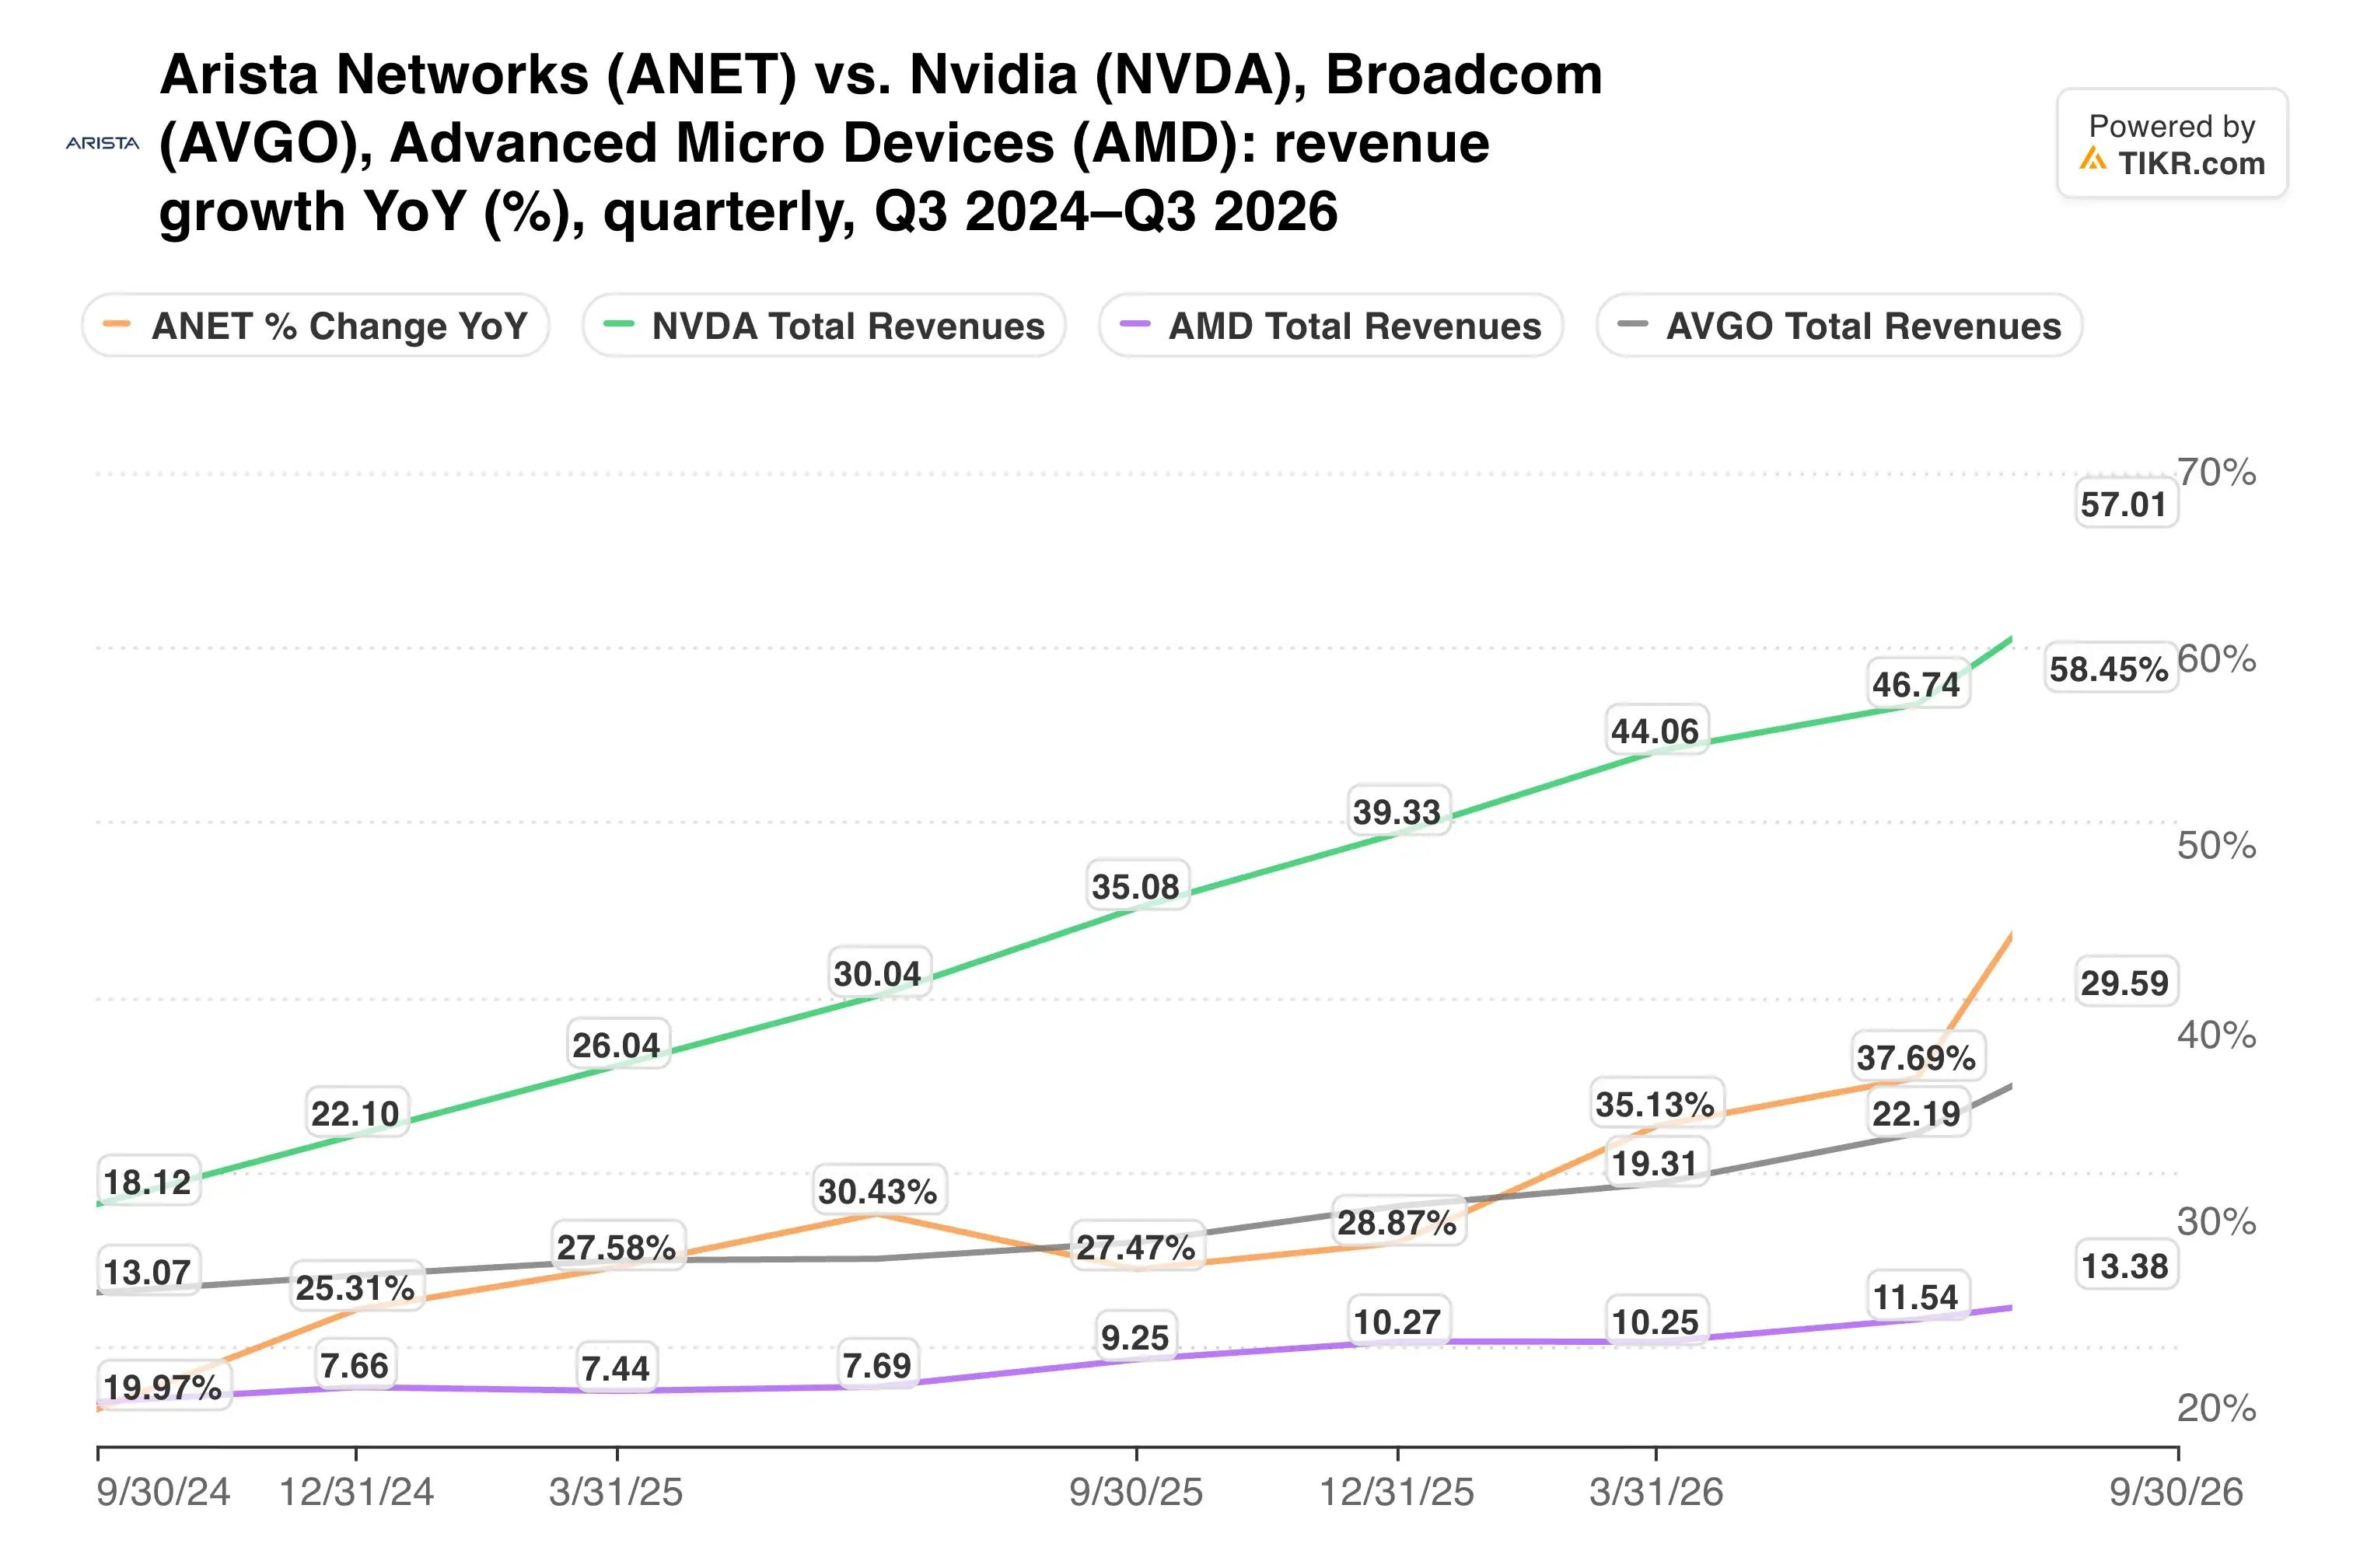
In its July quarter, Nvidia’s data center revenue jumped 117% to $89.0 billion, and its Spectrum-X Ethernet sales grew 2.6 times. A distracted Nvidia could open doors for Arista, but one week of headlines won’t prove it.
TIKR tracks 32 analysts on Arista Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Arista Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Arista Networks’ Analyst Ratings
Margins and inventory carry the risk
Growth this fast has a cost. Non-GAAP gross margin fell to 64.0% from 65.2% a year earlier, and management’s 2027 range of 62% to 64% leaves little room above that.
Where does gross margin settle once the AI ramp matures?
Inventory rose to $3.21 billion from $2.25 billion at the end of 2025. Meanwhile, deferred revenue climbed to $6.84 billion from $5.37 billion, which supports the outlook.
Concentration is the other risk. Its two largest customers made up 42% of 2025 revenue, so a pause from either would show up fast.
The balance sheet cushions all of that. Arista holds $14.36 billion in cash and marketable securities with no debt, and nine-month free cash flow rose 25.3% to $3.79 billion.
My take: Nvidia’s leadership crisis is a sentiment problem for Arista, and its fundamentals still look strong. I like the open-rack strategy because it lowers Arista’s dependence on any single chip vendor. Still, I’d want gross margin to hold near 64% before buying into the AI hardware selloff.
Next up is Nvidia’s report next week, its first under Kress. If data center and networking demand hold, Arista’s $18.5 billion target looks safer heading into its own fourth-quarter report, expected in February.
So what is Arista stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Arista could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!