Key Takeaways
- Cloudflare shares jumped 12% after third-quarter revenue rose 39% to $782.5 million, its fastest growth in nearly four years.
- Akamai grew revenue just 6% in the same quarter, while Cloudflare raised its 2026 revenue outlook to $2.963 billion to $2.964 billion.
- Non-GAAP gross margin fell to 72.4% from 75.3% as AI traffic and developer workloads lean harder on the network.
- The fourth-quarter report, expected in February 2027, will show whether management’s promised GAAP profit arrives.
Cloudflare (NET) shares jumped 12% on the morning of November 6 after its fastest revenue growth in nearly four years. Revenue rose 39% to $782.5 million, and the company lifted its profit forecast for the third time this year.
The contrast with its oldest rival is hard to miss. Akamai Technologies (AKAM) reported the same day, and its revenue grew just 6% to $1.122 billion.
“Our engine is firing on all cylinders, and we’ve found an even higher gear for this next phase of growth,” CEO Matthew Prince said in the earnings release.
That higher gear has a cost, though. Gross margin keeps sliding as AI traffic and developer workloads lean harder on the network.
Growth sped up again
This was the third straight acceleration in 2026. Revenue grew 34% in the first quarter and 36% in the second before reaching 39%.
A few other numbers stood out:
- Non-GAAP operating income rose 59.5% to $137.1 million, a 17.5% margin.
- Adjusted EPS climbed to $0.38 from $0.27, against $0.34 expected.
- Current remaining performance obligations grew 37%, so contracted revenue is keeping pace.
Guidance moved up as well. Cloudflare now expects 2026 revenue of $2.963 billion to $2.964 billion, up from $2.86 billion to $2.87 billion in August. Its adjusted EPS outlook rose to $1.35 from $1.25 to $1.26.
Here is how the top line has stacked up quarter by quarter…
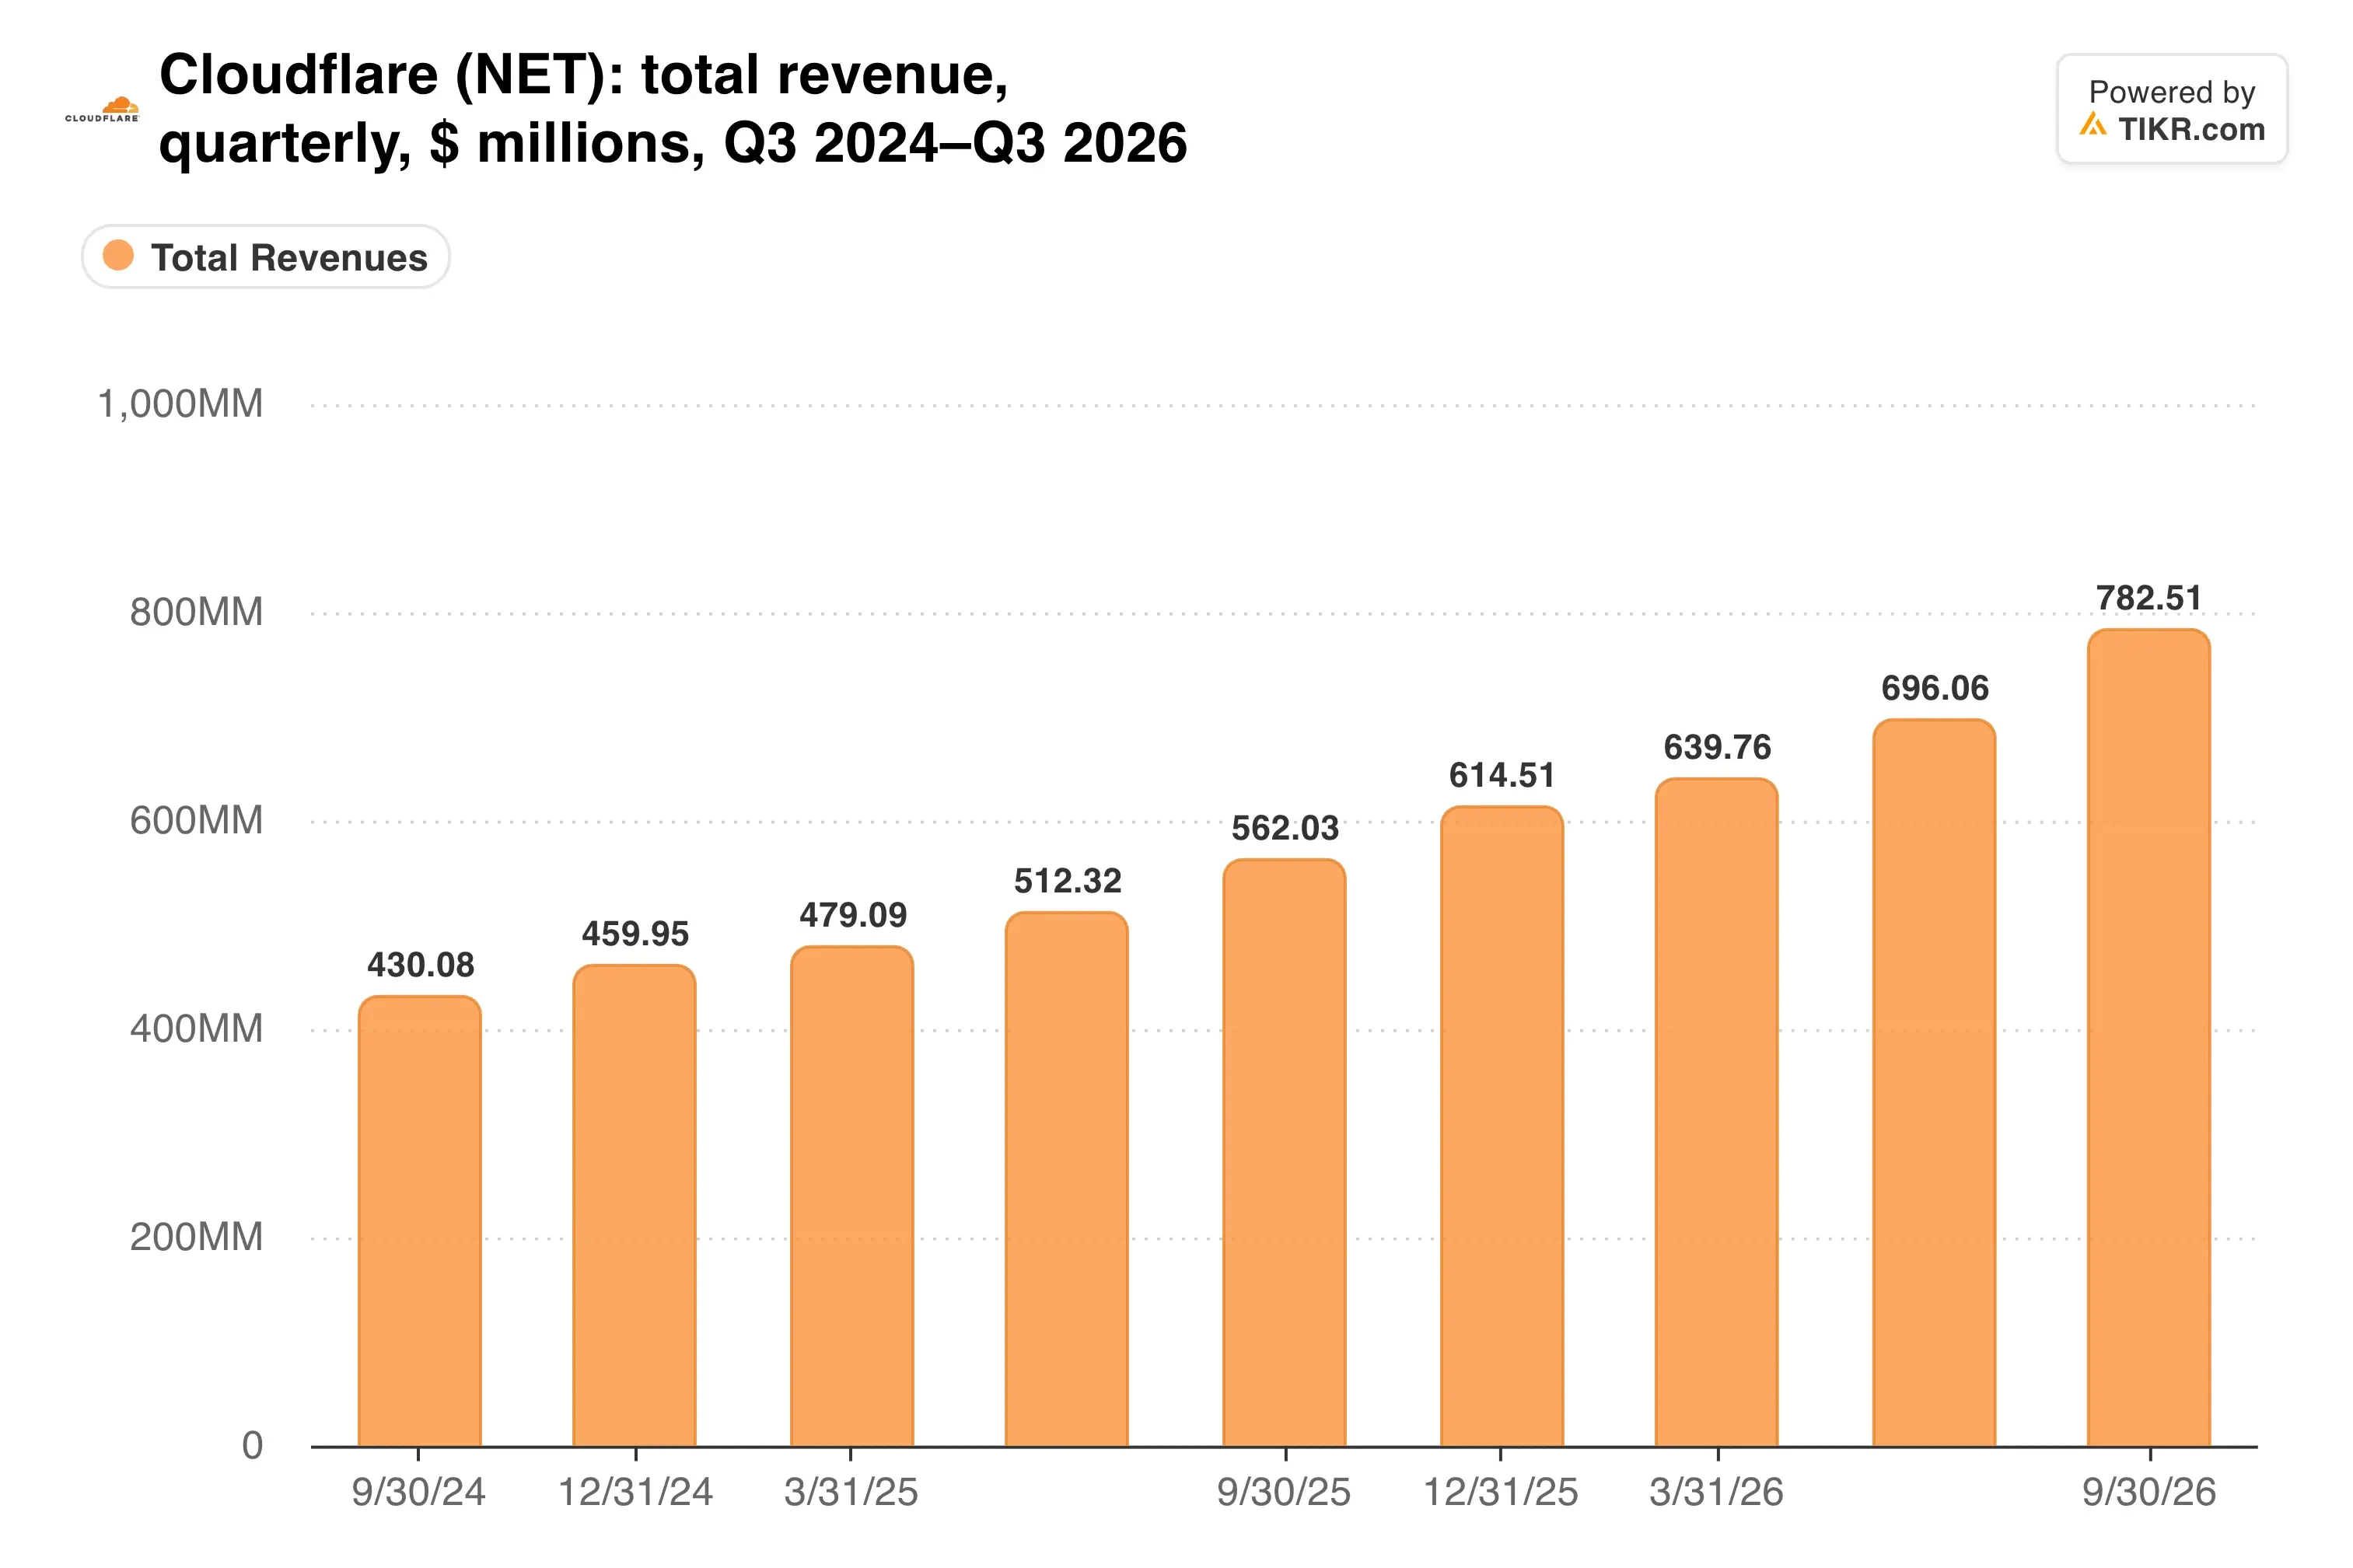
A year ago, quarterly revenue was $562.0 million. That climb is the clearest sign the AI traffic story is turning into sales.
Developers and agents carry the load
Management credits the Workers developer platform and agentic workloads. Meanwhile, customers paying over $100,000 a year grew 25% to more than 5,000.
That mix explains why Cloudflare keeps pulling away from Akamai. Akamai’s security revenue grew 9% to $622 million, and its cloud infrastructure unit grew 34% but brought in only $109 million.
Akamai gave up margin too. Its non-GAAP operating margin fell 6 points to 25%, so heavy infrastructure spending is pinching both companies.
So how far apart are the two on growth?
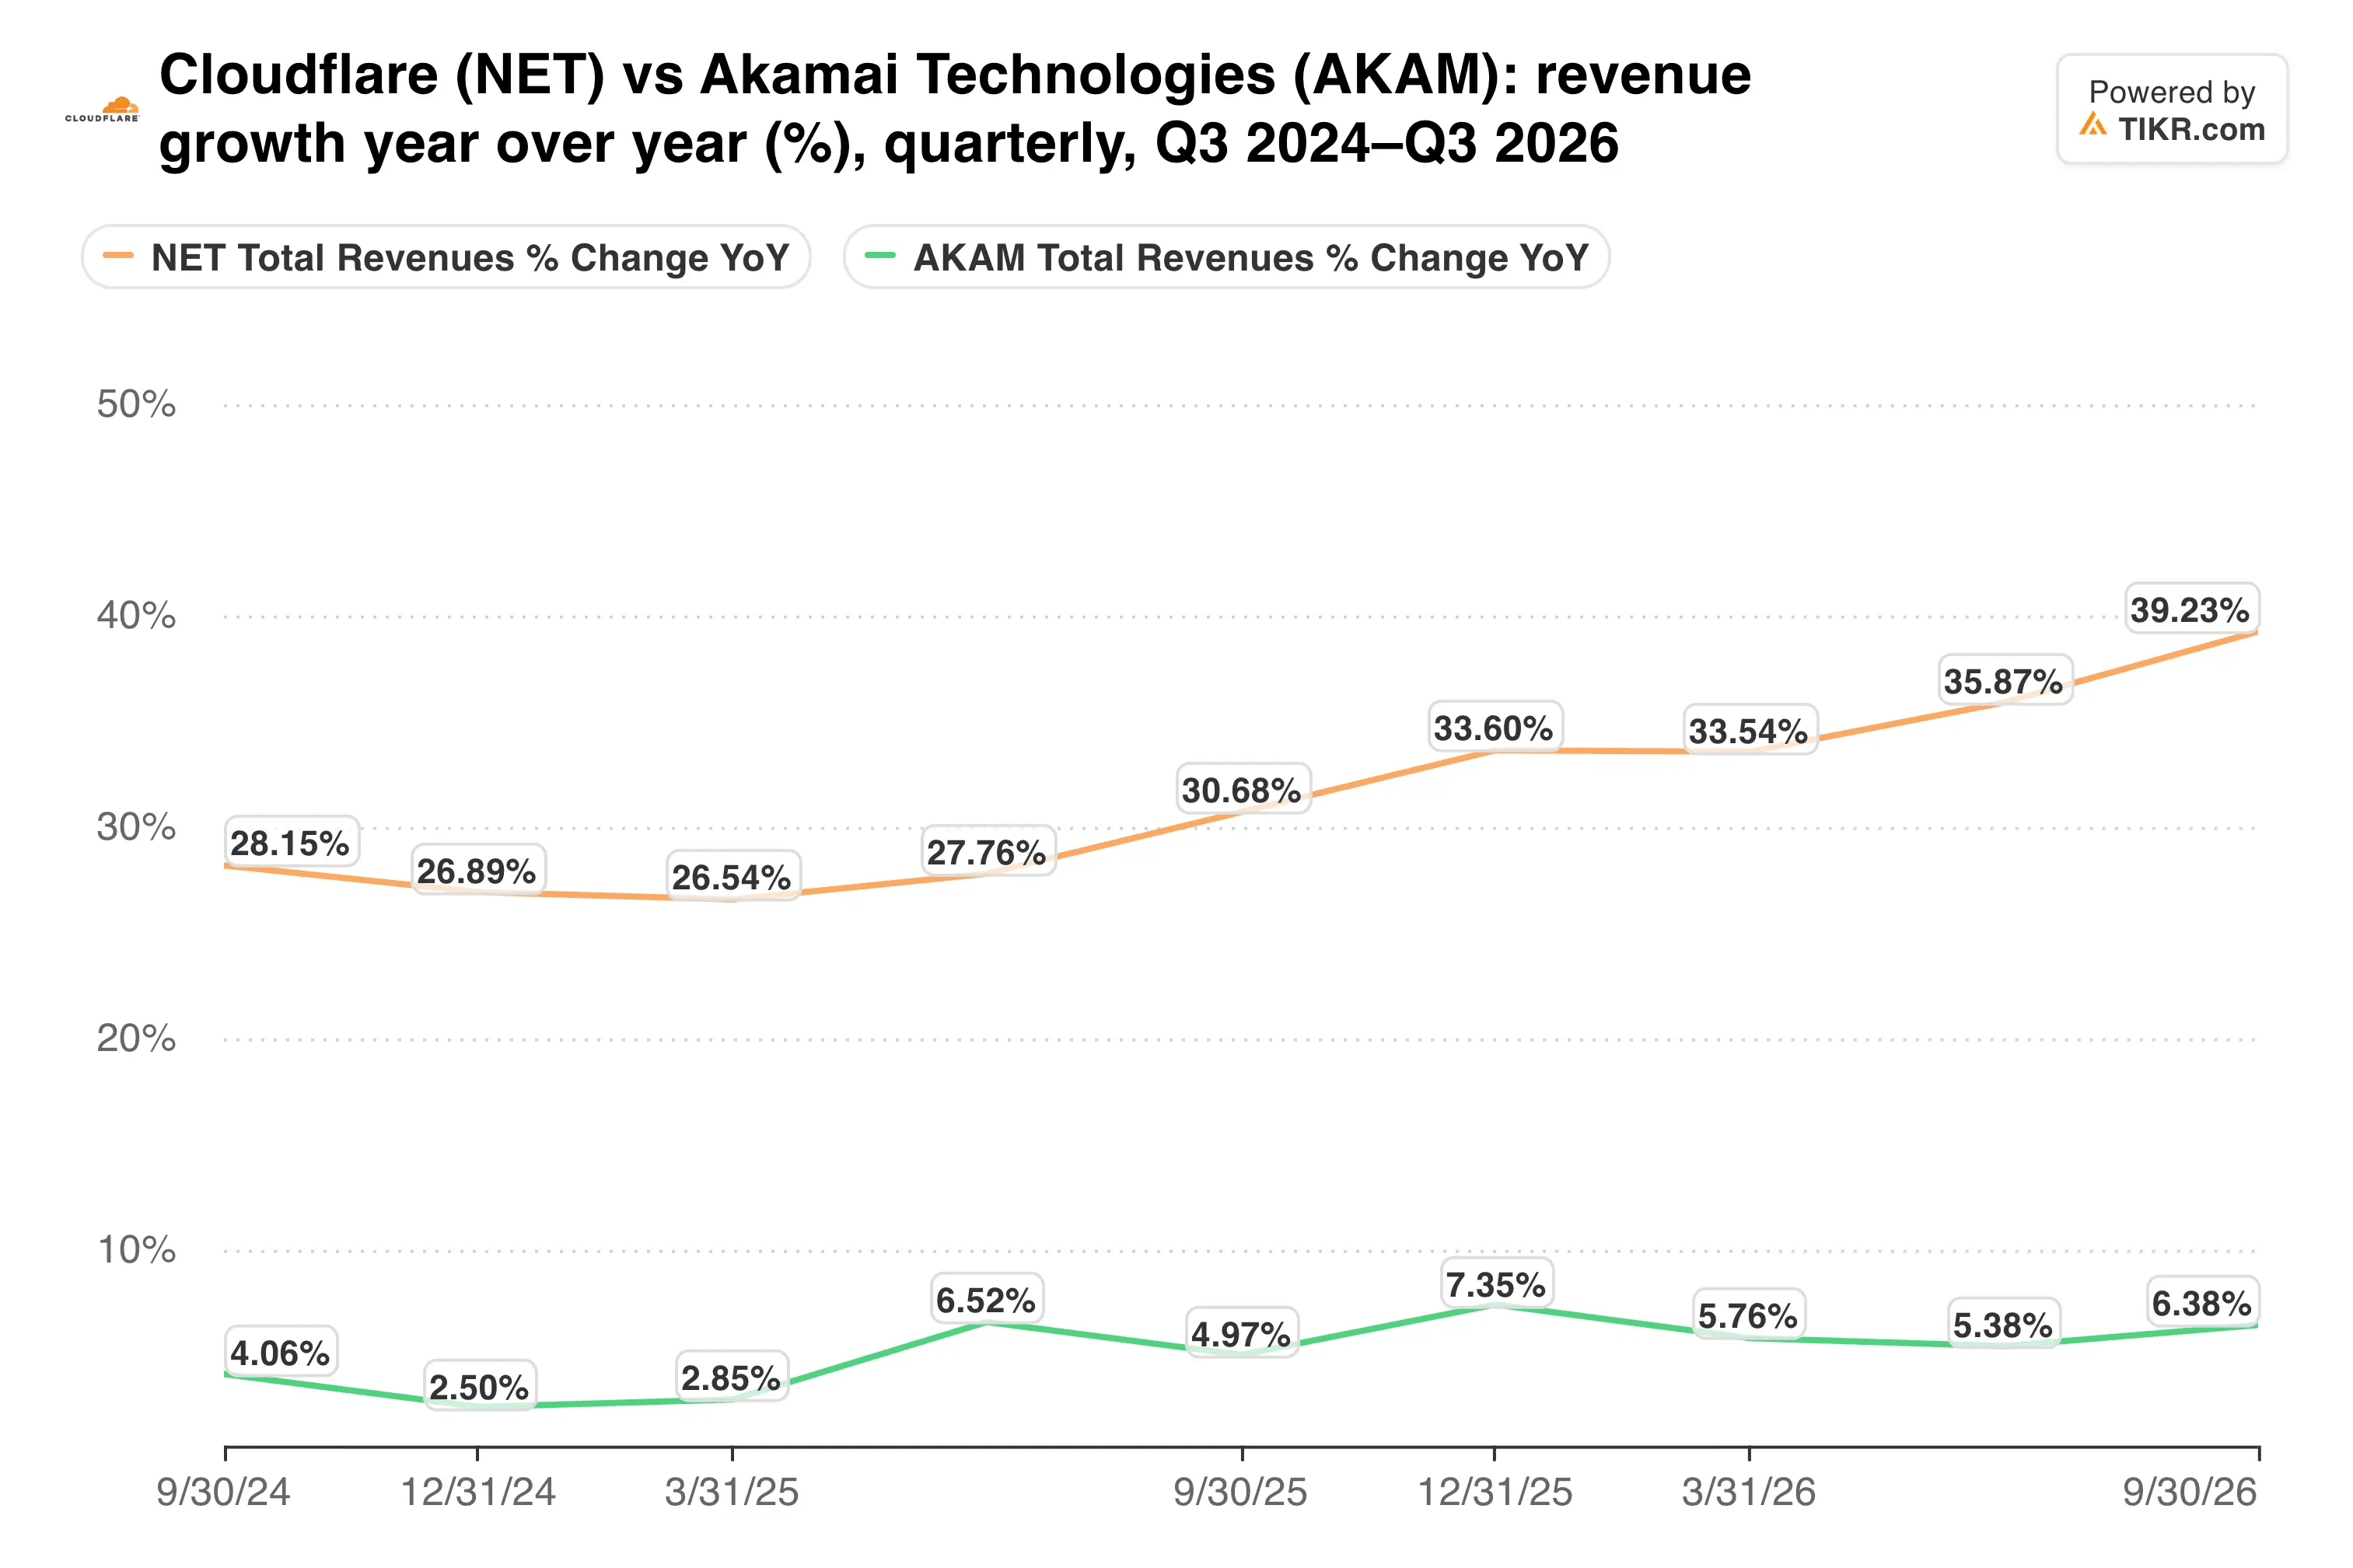
Cloudflare is still the smaller business. At this pace, however, the revenue gap is closing quickly.
TIKR tracks 34 analysts on Cloudflare. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Cloudflare, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cloudflare’s Analyst Ratings
Margins pay for the speed
Management says Workers carries slightly lower gross margins than products like Zero Trust, and the quarter showed it. Cost of revenue rose 54% on third-party services, colocation and server depreciation.
Non-GAAP gross margin fell to 72.4% from 75.3% a year earlier. The trend has been heading one way for a while.
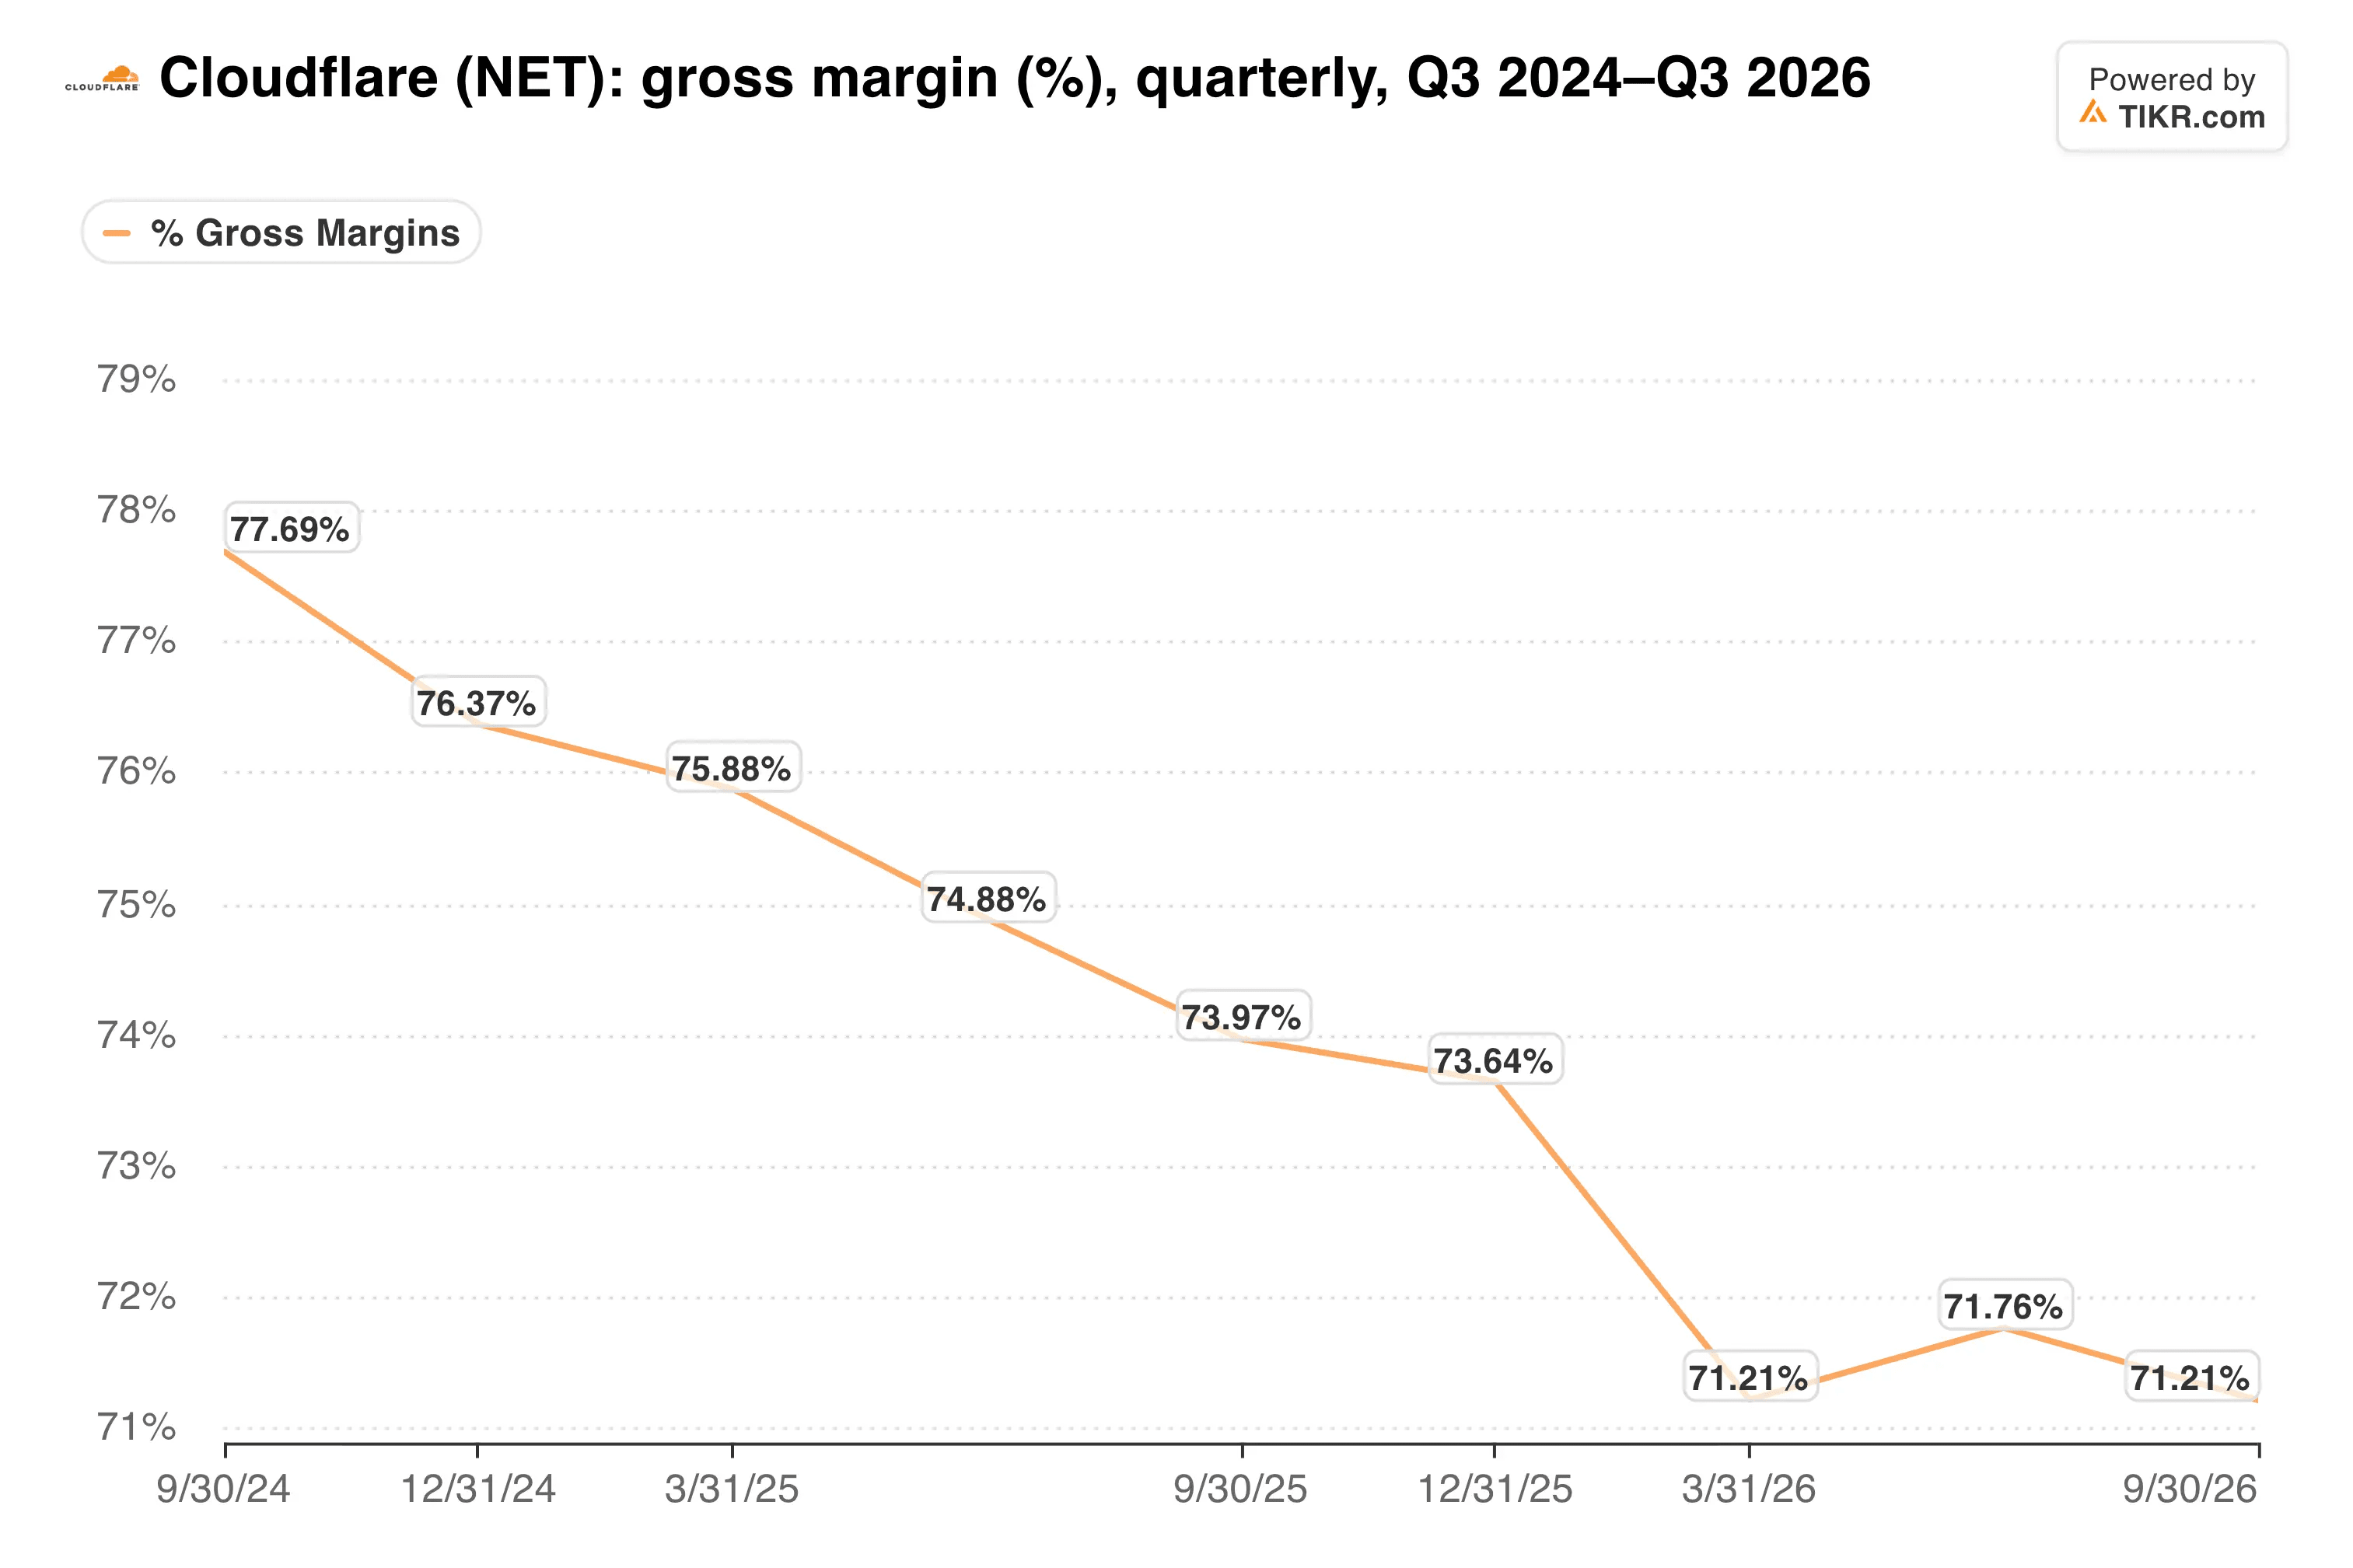
Cash flow tells a similar story. Capex jumped 44% to $121.8 million, so free cash flow rose only 9.5% to $82.1 million, a 10% margin versus 13% a year ago.
GAAP results still show a loss. The operating loss widened to $67.9 million because stock-based compensation and related taxes reached $174.1 million. Even so, management now expects a GAAP profit in the fourth quarter, well ahead of its 2028 target.
Valuation leaves little room for a stumble. Even after this fall’s pullback, Cloudflare still trades at a rich multiple of sales.
My take: The quarter settled the growth question, and I think the raised guide is credible because contracted revenue is growing almost as fast. Still, I would watch gross margin more closely than revenue now. Every point lost to AI workloads makes that GAAP profit harder to hit, so I’d rather add on a pullback than chase this rally.
The next checkpoint is the fourth-quarter report, expected in February 2027. It will show whether revenue lands near the $845 million to $846 million guide and whether the promised GAAP profit actually arrives.
So what is Cloudflare stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cloudflare could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!