Key Takeaways
- Applied Materials reports fiscal fourth-quarter results on Nov. 12 with its stock 47% below its high, after a chip-equipment sell-off that also hit Lam Research and KLA.
- Analysts have raised their numbers through the drop: the fiscal 2027 EPS consensus is $18.62, up from $16.40 at the end of June, so the sell-off has hit only the multiple so far.
- KLA and Lam guided December-quarter revenue higher, ASML expects demand to outrun its supply through 2028, and TSMC approved about $40.9 billion of new capital appropriations on Nov. 10.
- At 22x forward earnings, about its five-year average, Applied looks cheap if its first-quarter guide keeps earnings climbing toward that consensus, and a light guide would pull estimates down after the stock.
Applied Materials (AMAT) reports its fiscal fourth quarter on Thursday, Nov. 12, with the stock sitting 47% below its high. Rivals Lam Research (LRCX) and KLA (KLAC) have taken a similar beating since chip stocks sank after the midterms.
So the question for Thursday is whether the rout broke Applied’s earnings or only its multiple. Two companies on the same spending chain have already given an early read, and both Taiwan Semiconductor (TSM) and ASML (ASML) point to chipmakers that are still spending.
TIKR tracks 41 analysts on Applied Materials. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Materials, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Materials’ Analyst Ratings
Analysts are still raising their numbers
Wall Street’s estimates haven’t followed the stock down. Consensus for Applied’s fiscal 2027 normalized EPS was $16.40 at the end of June, right as its multiple peaked. Today it’s $18.62, from 35 analysts, and the estimates show earnings climbing every year through fiscal 2028:

That’s about 46% EPS growth expected in fiscal 2027 alone. Even B. Riley, which cut its target to $475 from $700 on Nov. 9, kept its Buy rating.
So the whole drop has come out of the multiple. Applied’s forward P/E has fallen from 49x on June 30 to 22x, right around its five-year average of 21x:
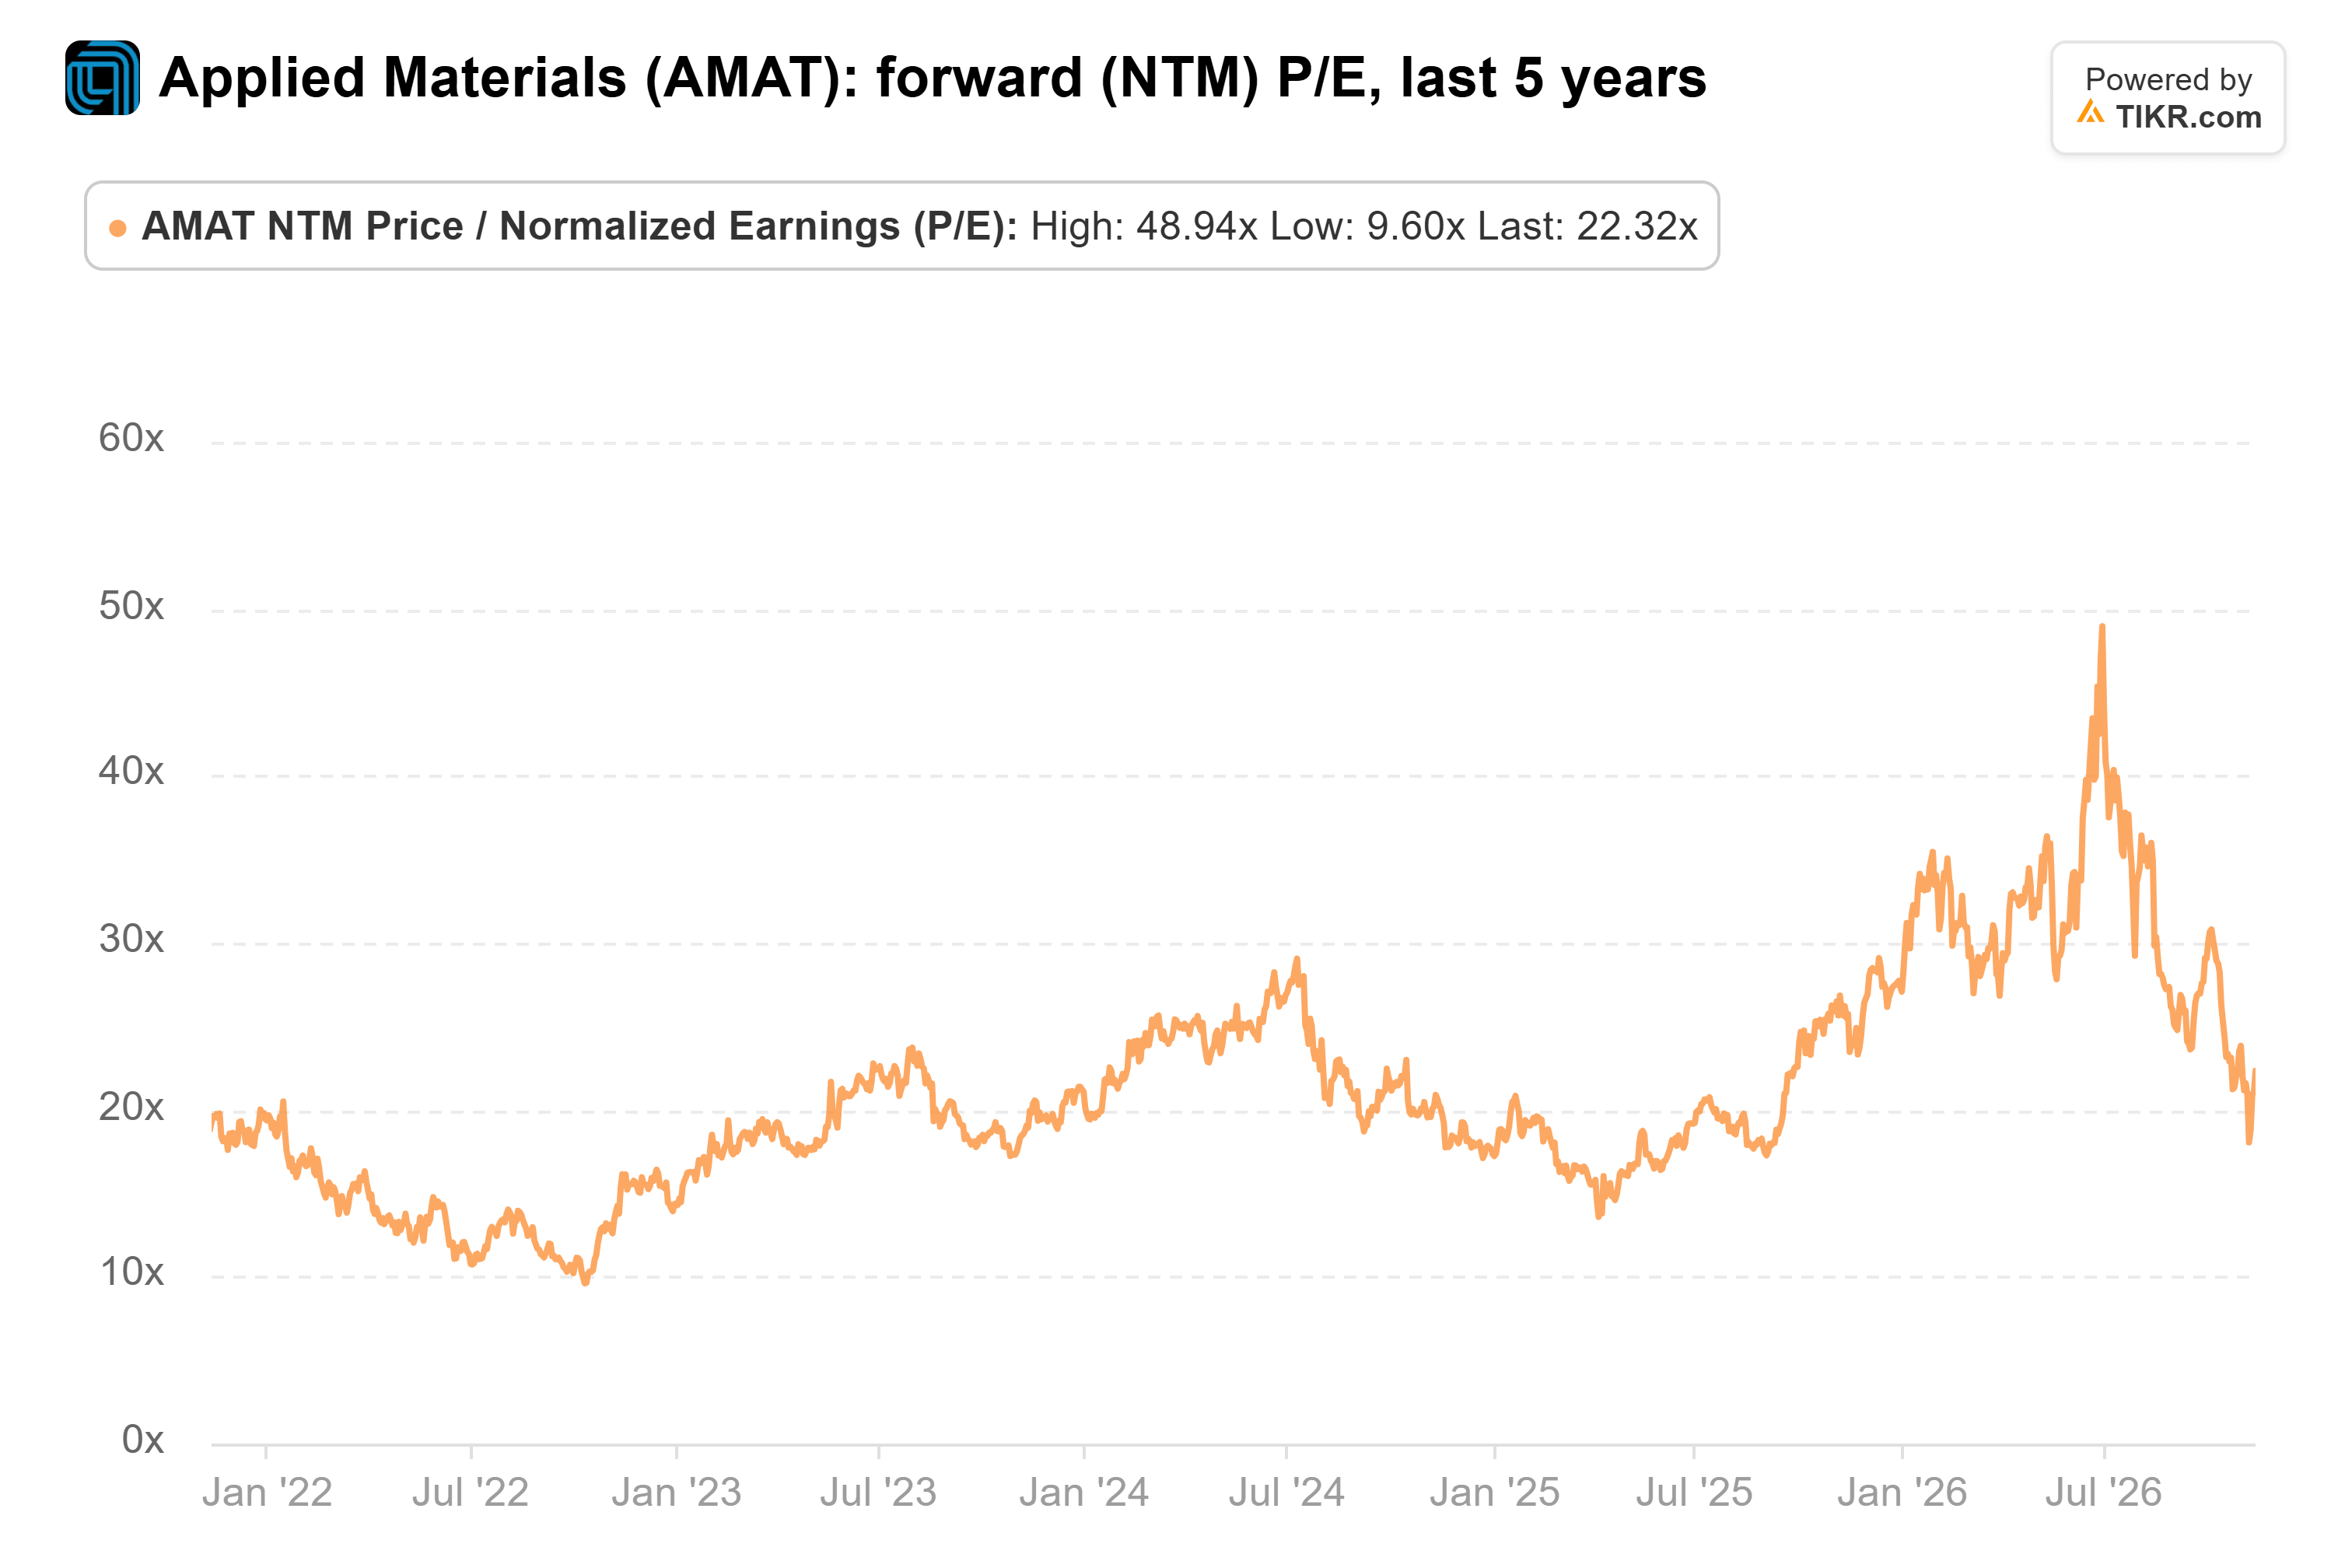
That’s an ordinary price for the earnings analysts expect, and that’s the catch. The last time the cycle turned, the multiple bottomed at 9.6x in October 2022. If estimates start to fall, 21x is no floor.
What Thursday’s guide has to show
Applied guided its fourth quarter to $10.25 billion of revenue and non-GAAP EPS of $4.02, at the midpoints of its ranges. Wall Street sits a hair above that, at about $10.30 billion and $4.06, so a beat is already expected. The guide for the first quarter of fiscal 2027 carries far more weight.
Spread evenly, $18.62 works out to about $4.66 a quarter, well above the $4.02 Applied guided for the October quarter. So the first-quarter guide needs another clear step up. (And that quarter runs 14 weeks, one more than usual, so a guide that barely clears $4.02 would mean the business underneath is flattening.)
Pricing has to hold up too. Applied’s gross margin has climbed from 47.1% in the quarter to October 2023 to 50.3% in the quarter to July 2026:
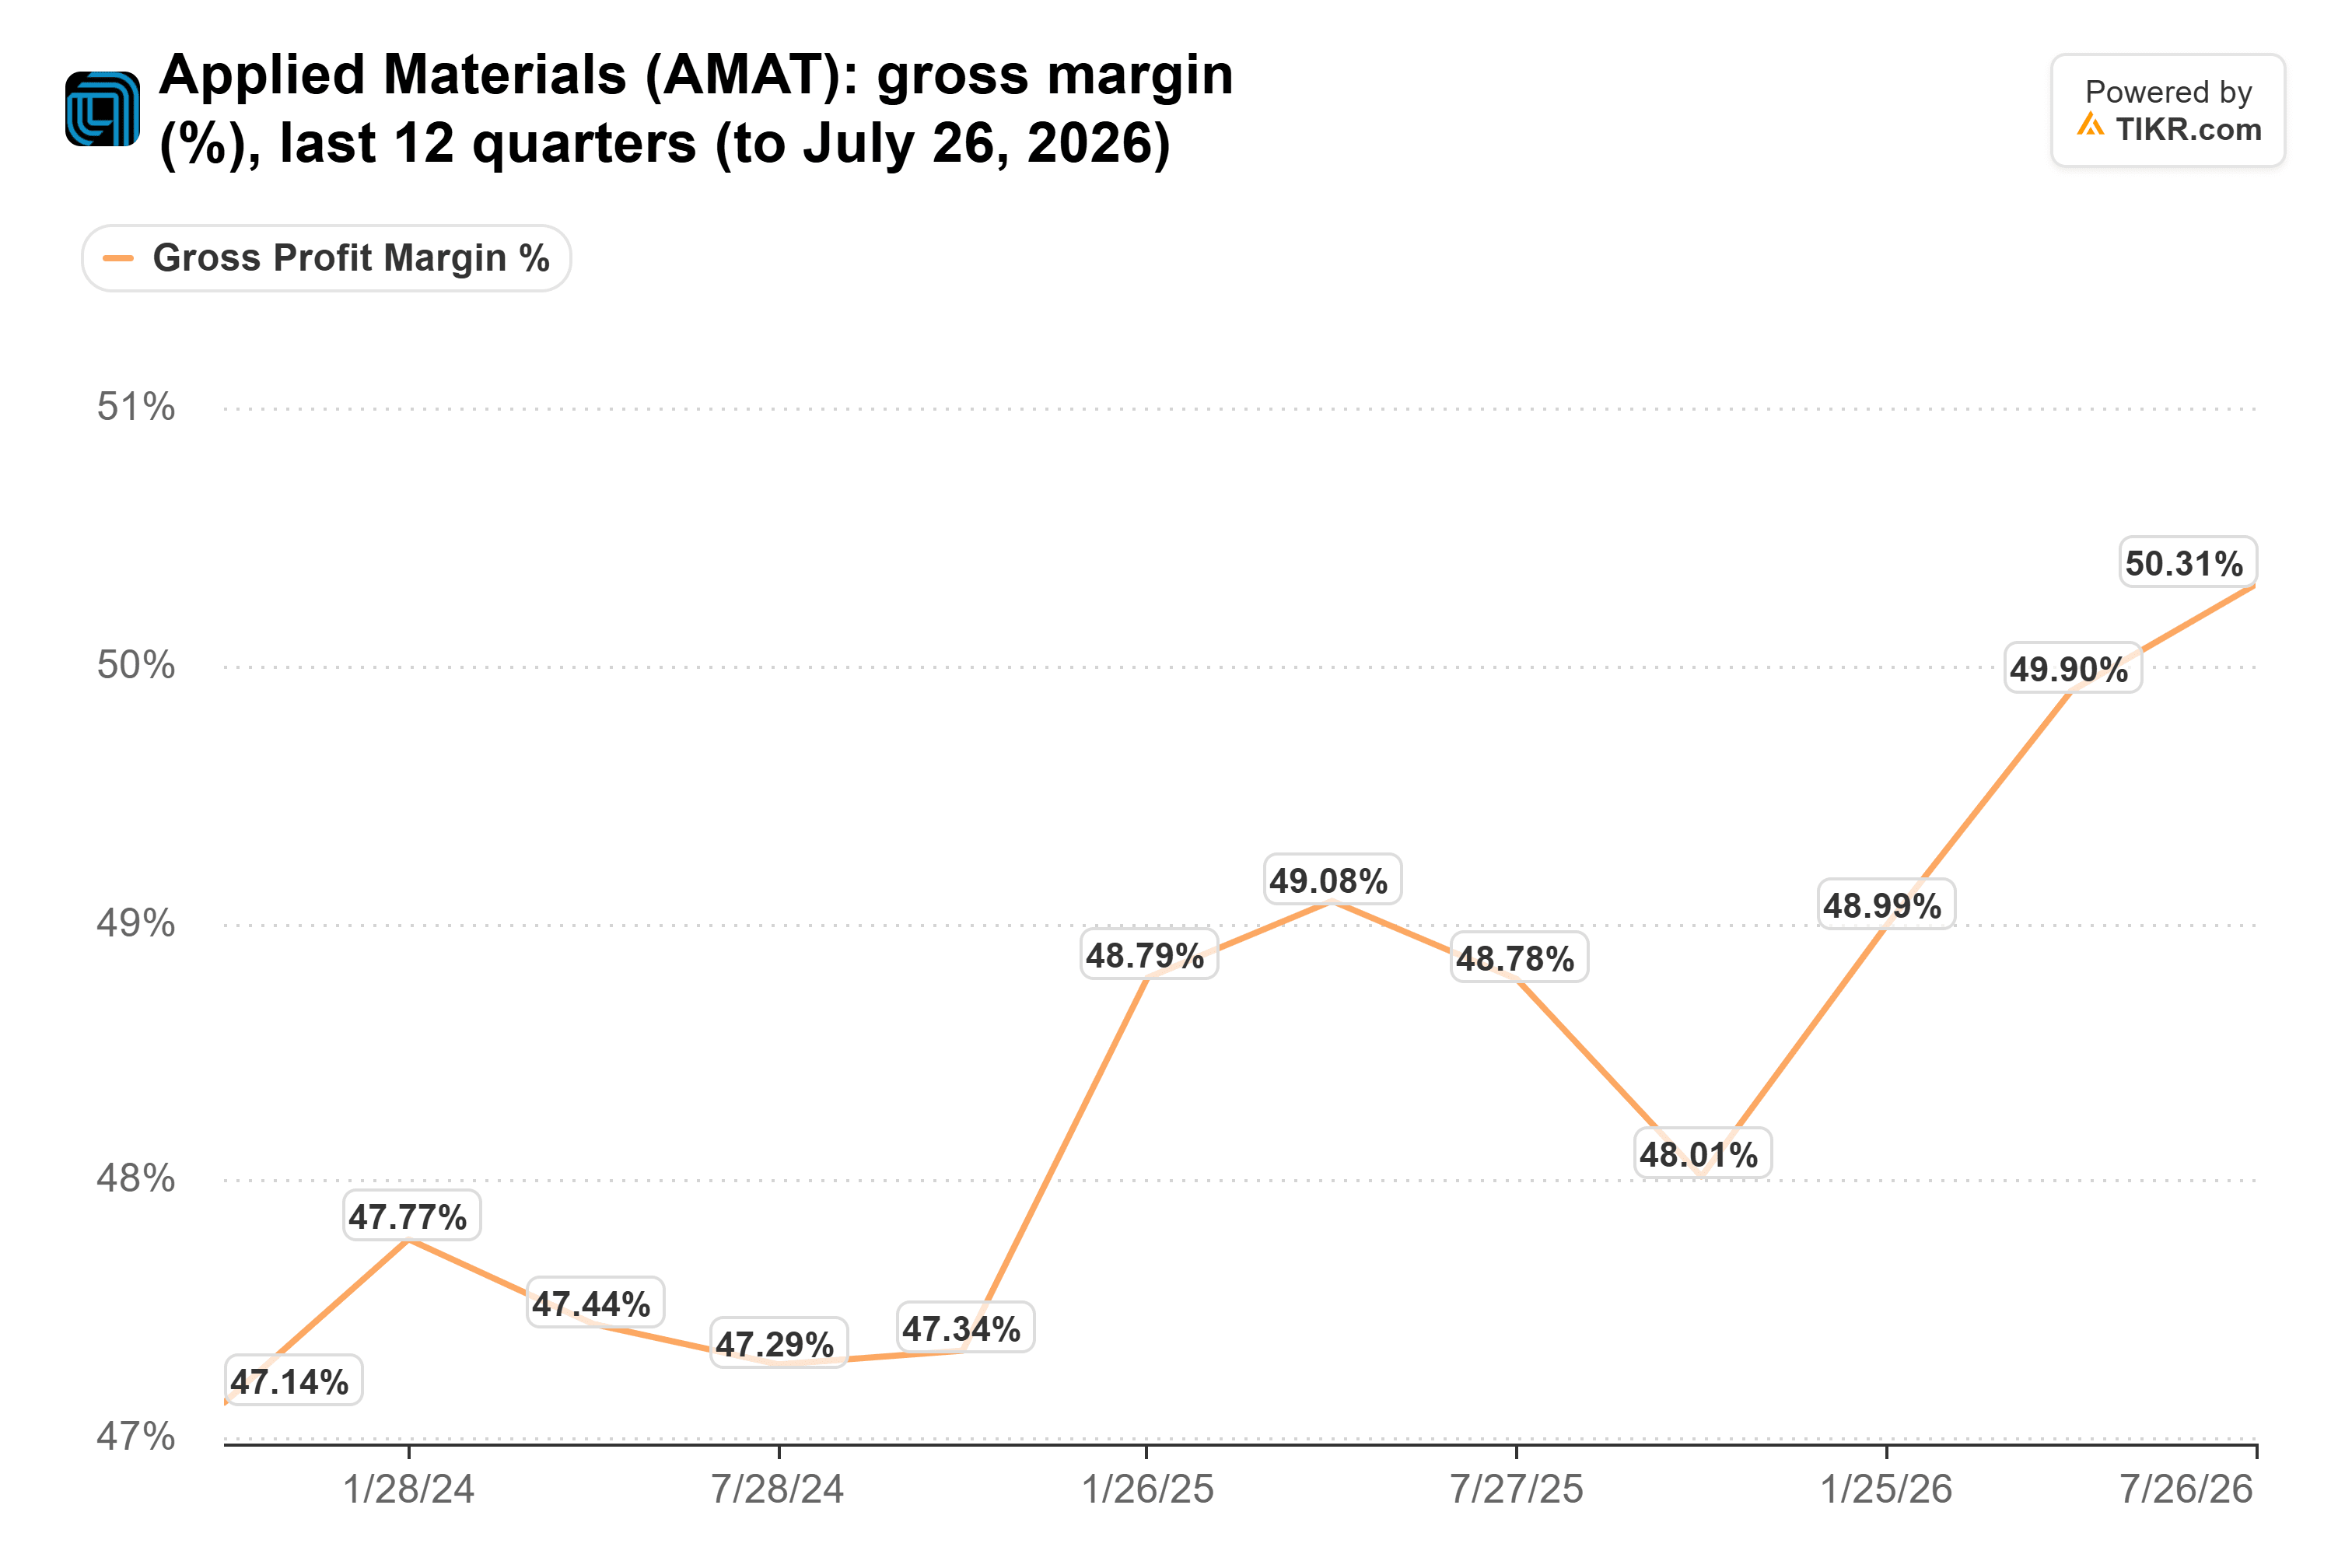
But Applied guided the fourth quarter’s non-GAAP margin flat, at about 50.4%, on roughly 12% more revenue, citing the cost of ramping capacity. Lam’s non-GAAP margin hit a record 52.4% in its September quarter, about two points ahead. A margin at or above 50.4%, and a first-quarter guide that holds it, would mean pricing is still working. A dip below 50% would mean ramp costs are eating into it.
Rivals and customers are still guiding up
Applied’s rivals set the bar. KLA guided December-quarter revenue to $4.7 billion, plus or minus $200 million, up from $4.14 billion in September. Lam guided its December quarter to $8.6 billion, up from $8.22 billion, and CFO Doug Bettinger said on Lam’s earnings call that the figure “would have been a bit higher if not for some near-term supply chain constraints.” With two direct rivals seeing demand rise into year-end, a flat guide from Applied would be hard to pin on the industry.
Customers look just as committed. TSMC’s board approved about $40.9 billion of capital appropriations on Nov. 10, mostly for advanced capacity, packaging and new fabs. That’s the spending Applied’s equipment business runs on, approved two days before it reports.
ASML expects that demand to last. In its third-quarter release, CEO Christophe Fouquet said, “we now expect that our supply as currently planned for both 2027 and 2028 will not fully meet the demand of our customers.” Chipmakers order lithography machines years ahead, so that’s an early look at the 2027 equipment budgets Applied’s outlook has to match.
So far, this looks like a reset
The way I see it, investors have priced in a downturn that nothing in the numbers shows yet. Estimates are rising, and Applied’s rivals and customers are still guiding up. If Thursday’s first-quarter guide keeps EPS climbing toward $18.62, 22x for earnings expected to grow about 46% looks cheap.
The biggest risk is outside Applied’s control: the stock trades with the AI trade, and investors may take their cue from Nvidia’s report later this month more than from anything Applied says Thursday. And if the guide comes in light, estimates will follow the stock down, and a multiple sitting at its average has plenty of room to fall.
So what is Applied Materials stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Materials could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Materials for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!