Key Takeaways
- Amazon reports its third-quarter results after the close on Thursday, Oct. 29, with its forward P/E close to its lowest level of the past five years.
- Amazon’s earnings have grown fast while its stock hasn’t kept up, and the low multiple looks like a mispricing as long as AWS keeps growing.
- Normalized EPS rose from $2.90 in 2023 to $7.17 in 2025, and analysts expect $13.37 in 2028, while the forward P/E has fallen to 28x against a five-year average of 49x.
- The quarter needs to show AWS growing at close to the second quarter’s 37% with its margin holding up, which would show the AI spending is paying off.
Amazon (AMZN) reports its third-quarter results after the close on Thursday, Oct. 29, and it goes into the report with an odd setup:
Its earnings keep climbing, and investors keep paying less for them.
Ritholtz Wealth Management CEO Josh Brown summed it up on Tuesday’s episode of The Compound and Friends, saying “this company’s earnings per share is absolutely exploding. And the stock price has given you nothing as a result of that.”
Brown has the earnings right
TIKR’s numbers back him up. Amazon’s normalized EPS rose from $2.90 in 2023 to $7.17 in 2025, and analysts expect it to keep rising.
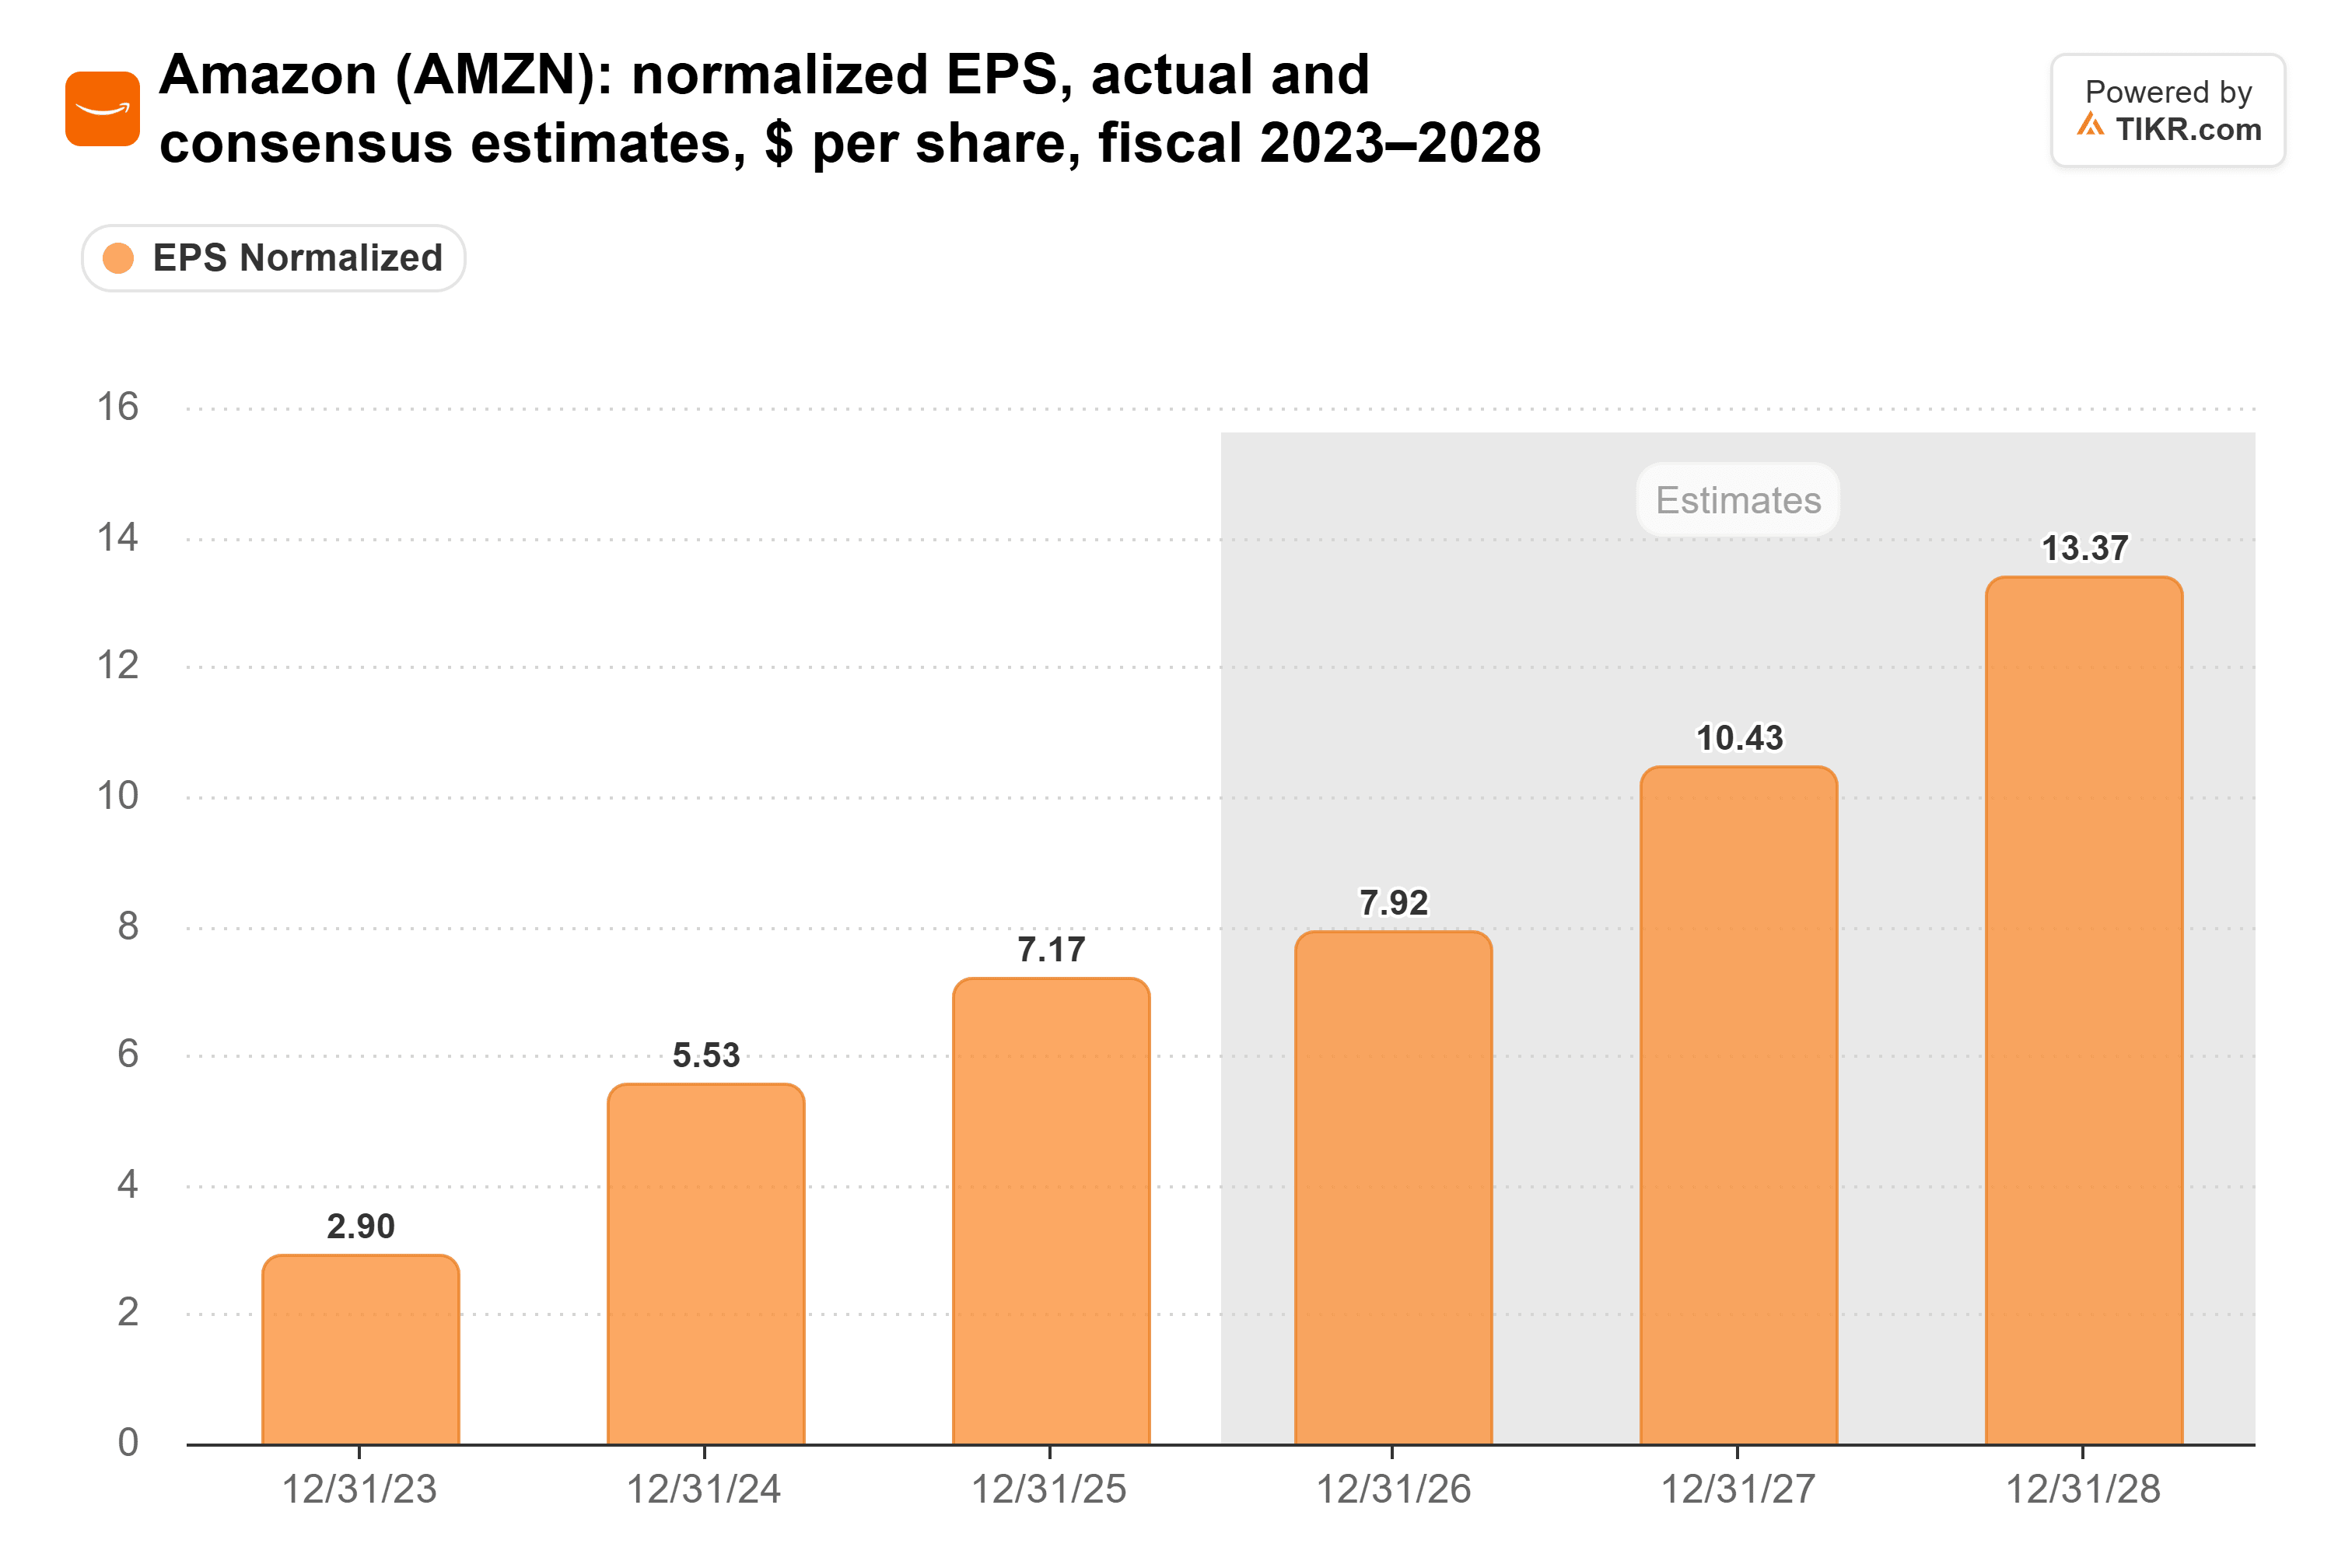
Analysts’ consensus is $10.43 for 2027 and $13.37 for 2028, close to double what Amazon earned last year. (That’s normalized EPS, which leaves out the gains on Amazon’s Anthropic stake that have swelled its reported earnings this year.)
The multiple went the other way
Over the same stretch, Amazon’s forward P/E has fallen to 28x. That’s just above February’s five-year low of 26x and far below its five-year average of 49x.
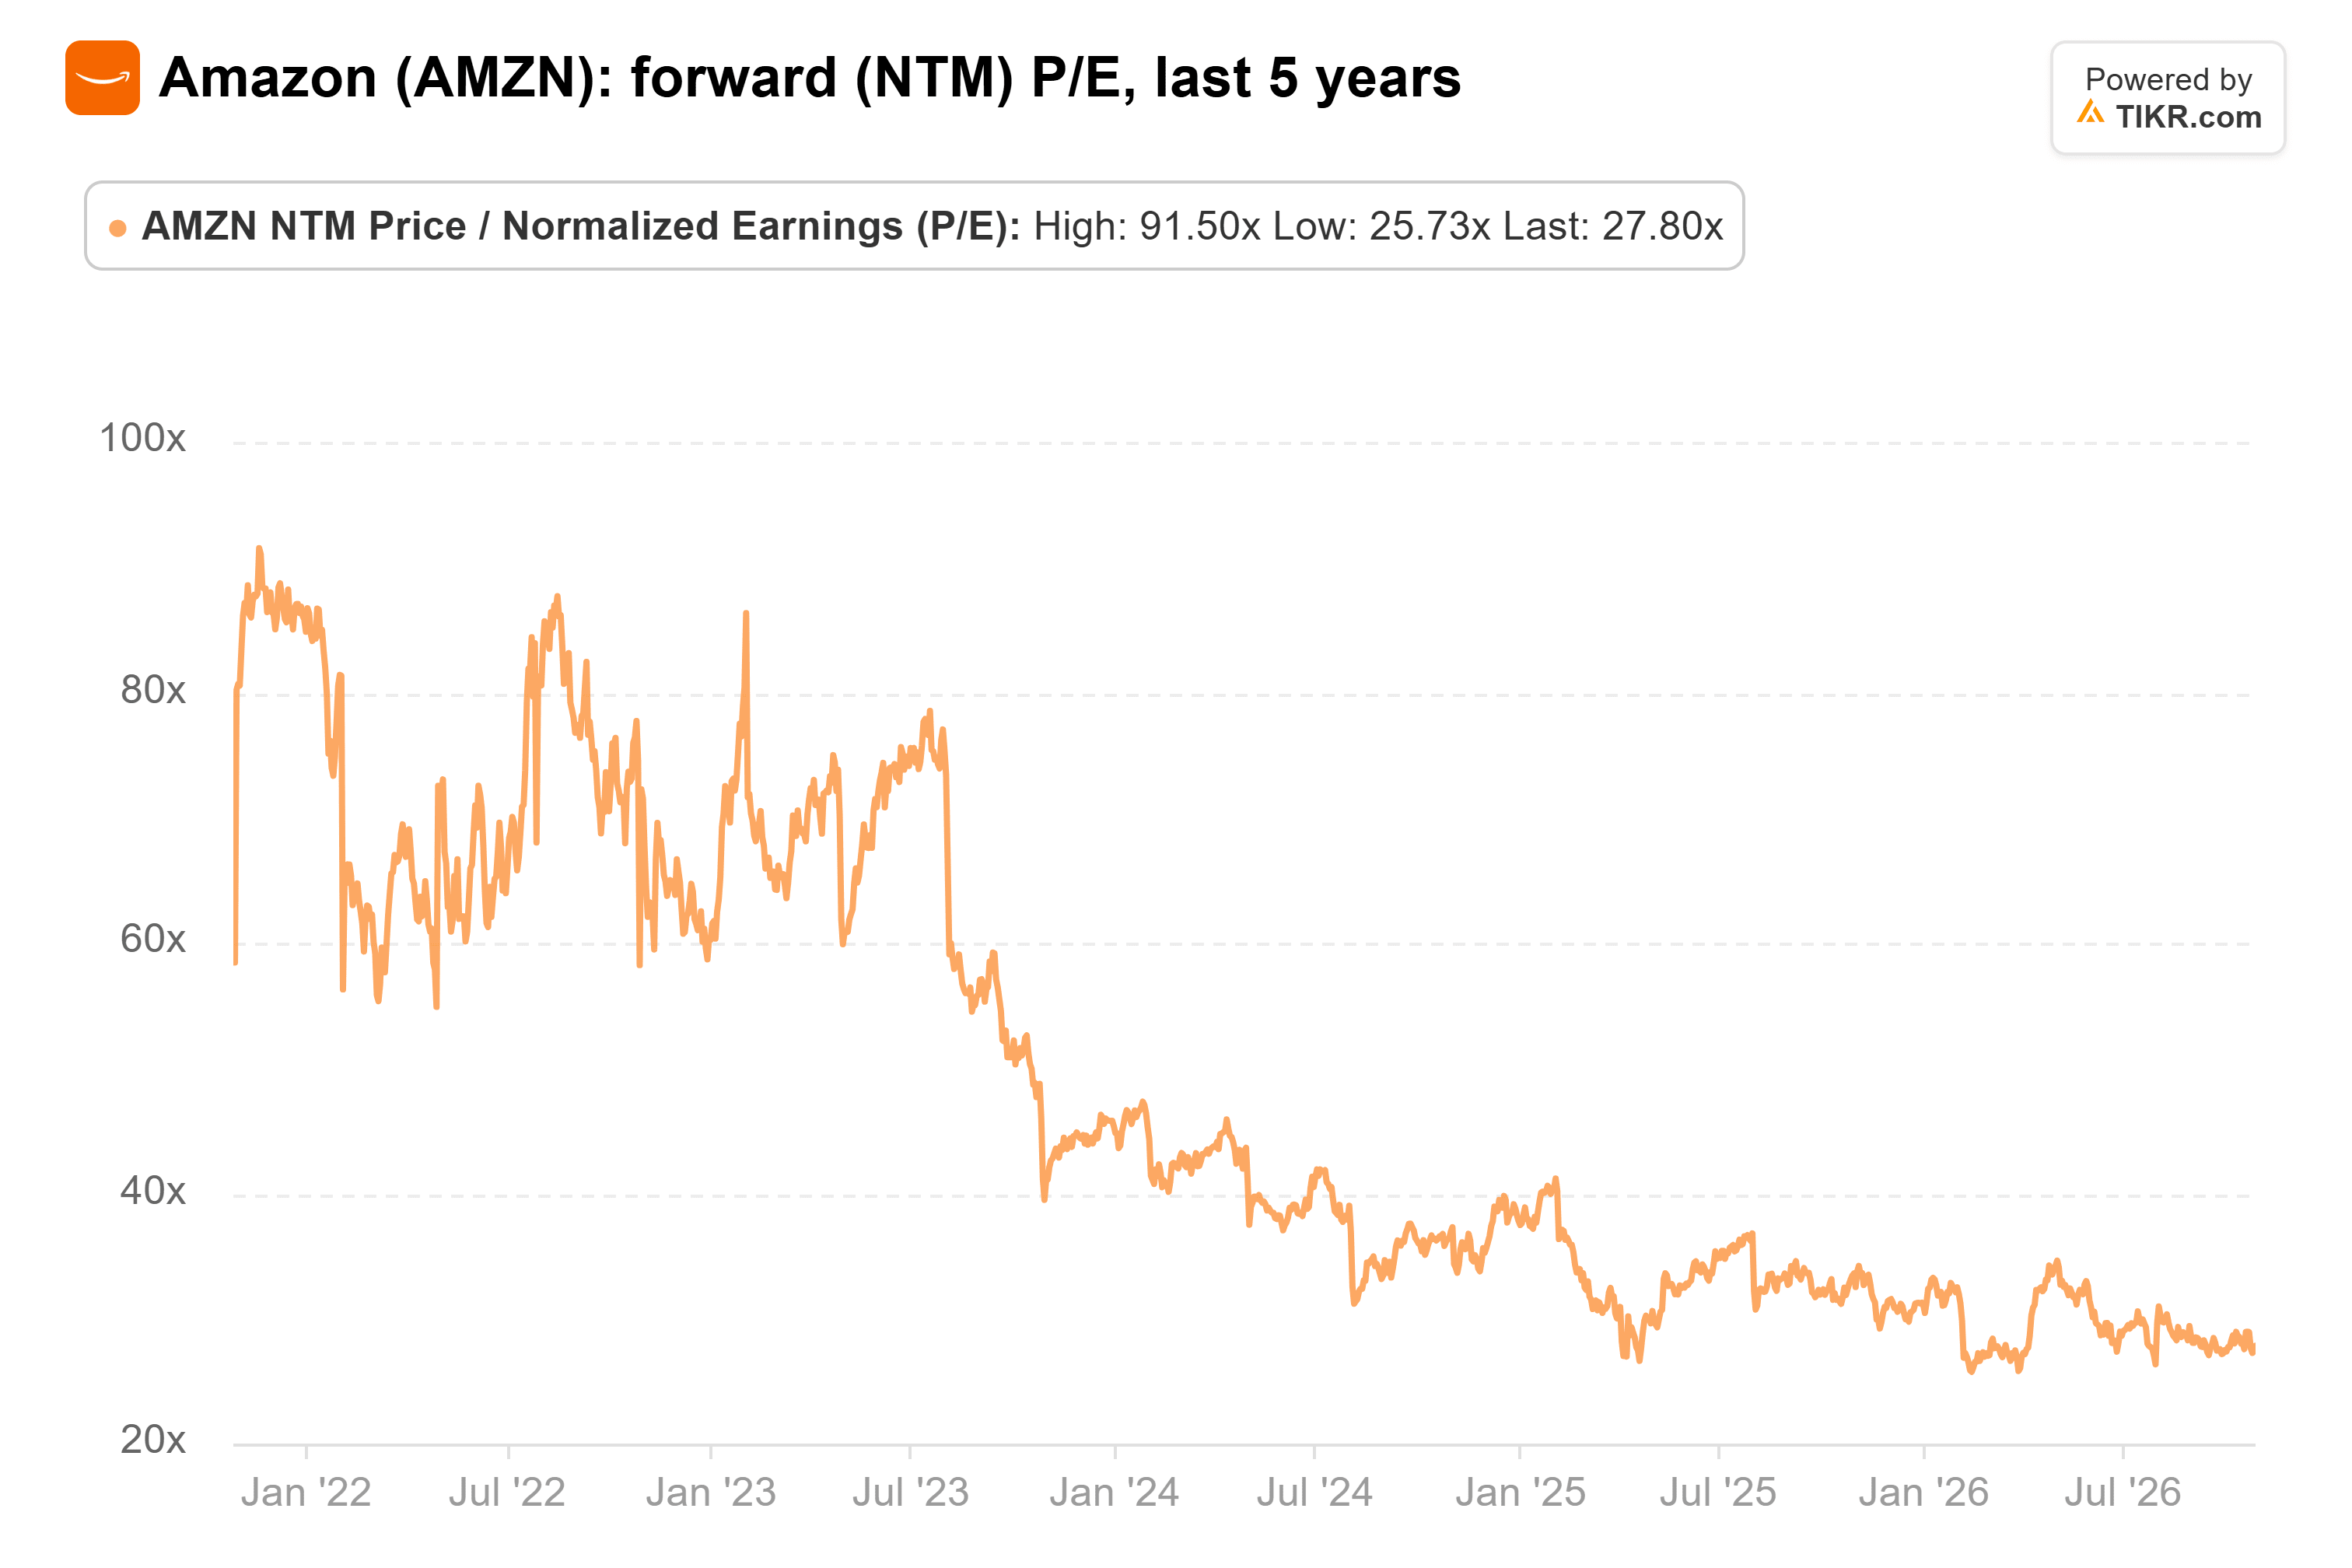
That’s nowhere near the kind of valuation that would worry NYU professor Scott Galloway. On Monday’s episode of Prof G Markets, he said, “I would want to see these hyperscalers trading at ridiculous valuations, trading at 50, 60, 70 times earnings.”
Amazon trades at roughly half the low end of that range.
TIKR tracks 60 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
The market is worried about the bill
The discount comes from the cost of the AI build-out. Charles Schwab’s Liz Ann Sonders noted on X on Monday that an S&P index of U.S.-listed hyperscalers has fallen by roughly a quarter since early May. Her reason: investors are worried about how all that spending gets paid for.
Amazon expects about $220 billion of capital spending this year, up from $128.3 billion in 2025. Free cash flow was a $7.6 billion outflow over the 12 months to June 30, and long-term debt doubled to $128.9 billion in the first half of 2026. AWS’s operating income also fell to 18% of its year-end assets in 2025, from 26% in 2024. (Management says that return recovers as data centers built ahead of demand fill up.)
So the EPS line alone probably won’t move the stock on Thursday. Some investors on X are already speculating that Amazon could raise cash on earnings day, as Meta did. Niles Investment Management’s Daniel Niles agreed.
What Amazon needs to show Thursday
The report has to show the spending is paying off.
- AWS growth at or near the second quarter’s 37%, up from 17% a year earlier.
- An AWS operating margin that holds up near Q2’s 39.4% as depreciation climbs. (That 39.4% included about $551 million of energy-contract gains.)
- Operating income at or above its $22.5 billion to $26.5 billion guide. The low end already tops the $21.7 billion Amazon earned a year ago before FTC and severance charges.
- No jump in the roughly $220 billion capex plan.
My take: at 28x forward earnings, Amazon is priced as if this build-out won’t pay. If AWS holds its pace on Thursday, the de-rating looks like a mispricing, and earnings growth alone gives the stock room to run.
Of course, if AWS growth slips toward 30% while its margin falls, the lower multiple will have been earned. And the bigger test comes with the 2027 capex outlook in early February.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!