Key Takeaways
- Affirm fell 13% in a week with no news of its own, as Upstart and SoFi slid too.
- A hot October inflation report all but locked in a December Fed hike, which would lift Affirm’s funding costs.
- With analysts still raising estimates, the drop makes Affirm a buy if holiday-quarter delinquencies hold near 2.9%.
Affirm (AFRM) stock is down 13% in the past week, with no bad news of its own. Upstart (UPST) is down 12% and SoFi (SOFI) 12% over the same stretch, while the S&P 500 lost 4%. The selling looks like a bet on rates.
Rates are the real worry
October’s consumer prices rose more than expected, and traders fully priced in a December Fed hike. Affirm’s funding costs, which track market rates, rose 27 basis points last quarter. Still, revenue less transaction costs (RLTC) held at 4.3% of gross merchandise volume (GMV), above management’s 3.75%-4% range. CEO Max Levchin put the hit from recent rate moves at 15 to 20 basis points, so Affirm has room to absorb another.
Upstart also relies on outside funders, and it’s already hurting. It cut its full-year outlook on Nov. 3, with CEO Paul Gu saying “Macro is putting pressure on our near-term outlook.” Its early-February report will show whether a hike squeezes it harder than Affirm.
SoFi should feel a hike less, since deposits made up 90% of its average liabilities last quarter, and it raised its 2026 guidance on Oct. 27. Its matching drop tells me investors sold the whole group.
Nothing in the business broke
In the September quarter, Affirm beat its own guide and raised its full-year outlook. On Nov. 17, Truist raised its growth estimate even as it trimmed its target to $86 from $88. Consensus normalized EPS still climbs from $3.96 in fiscal 2027 (the year to June) to $6.24 in fiscal 2029:
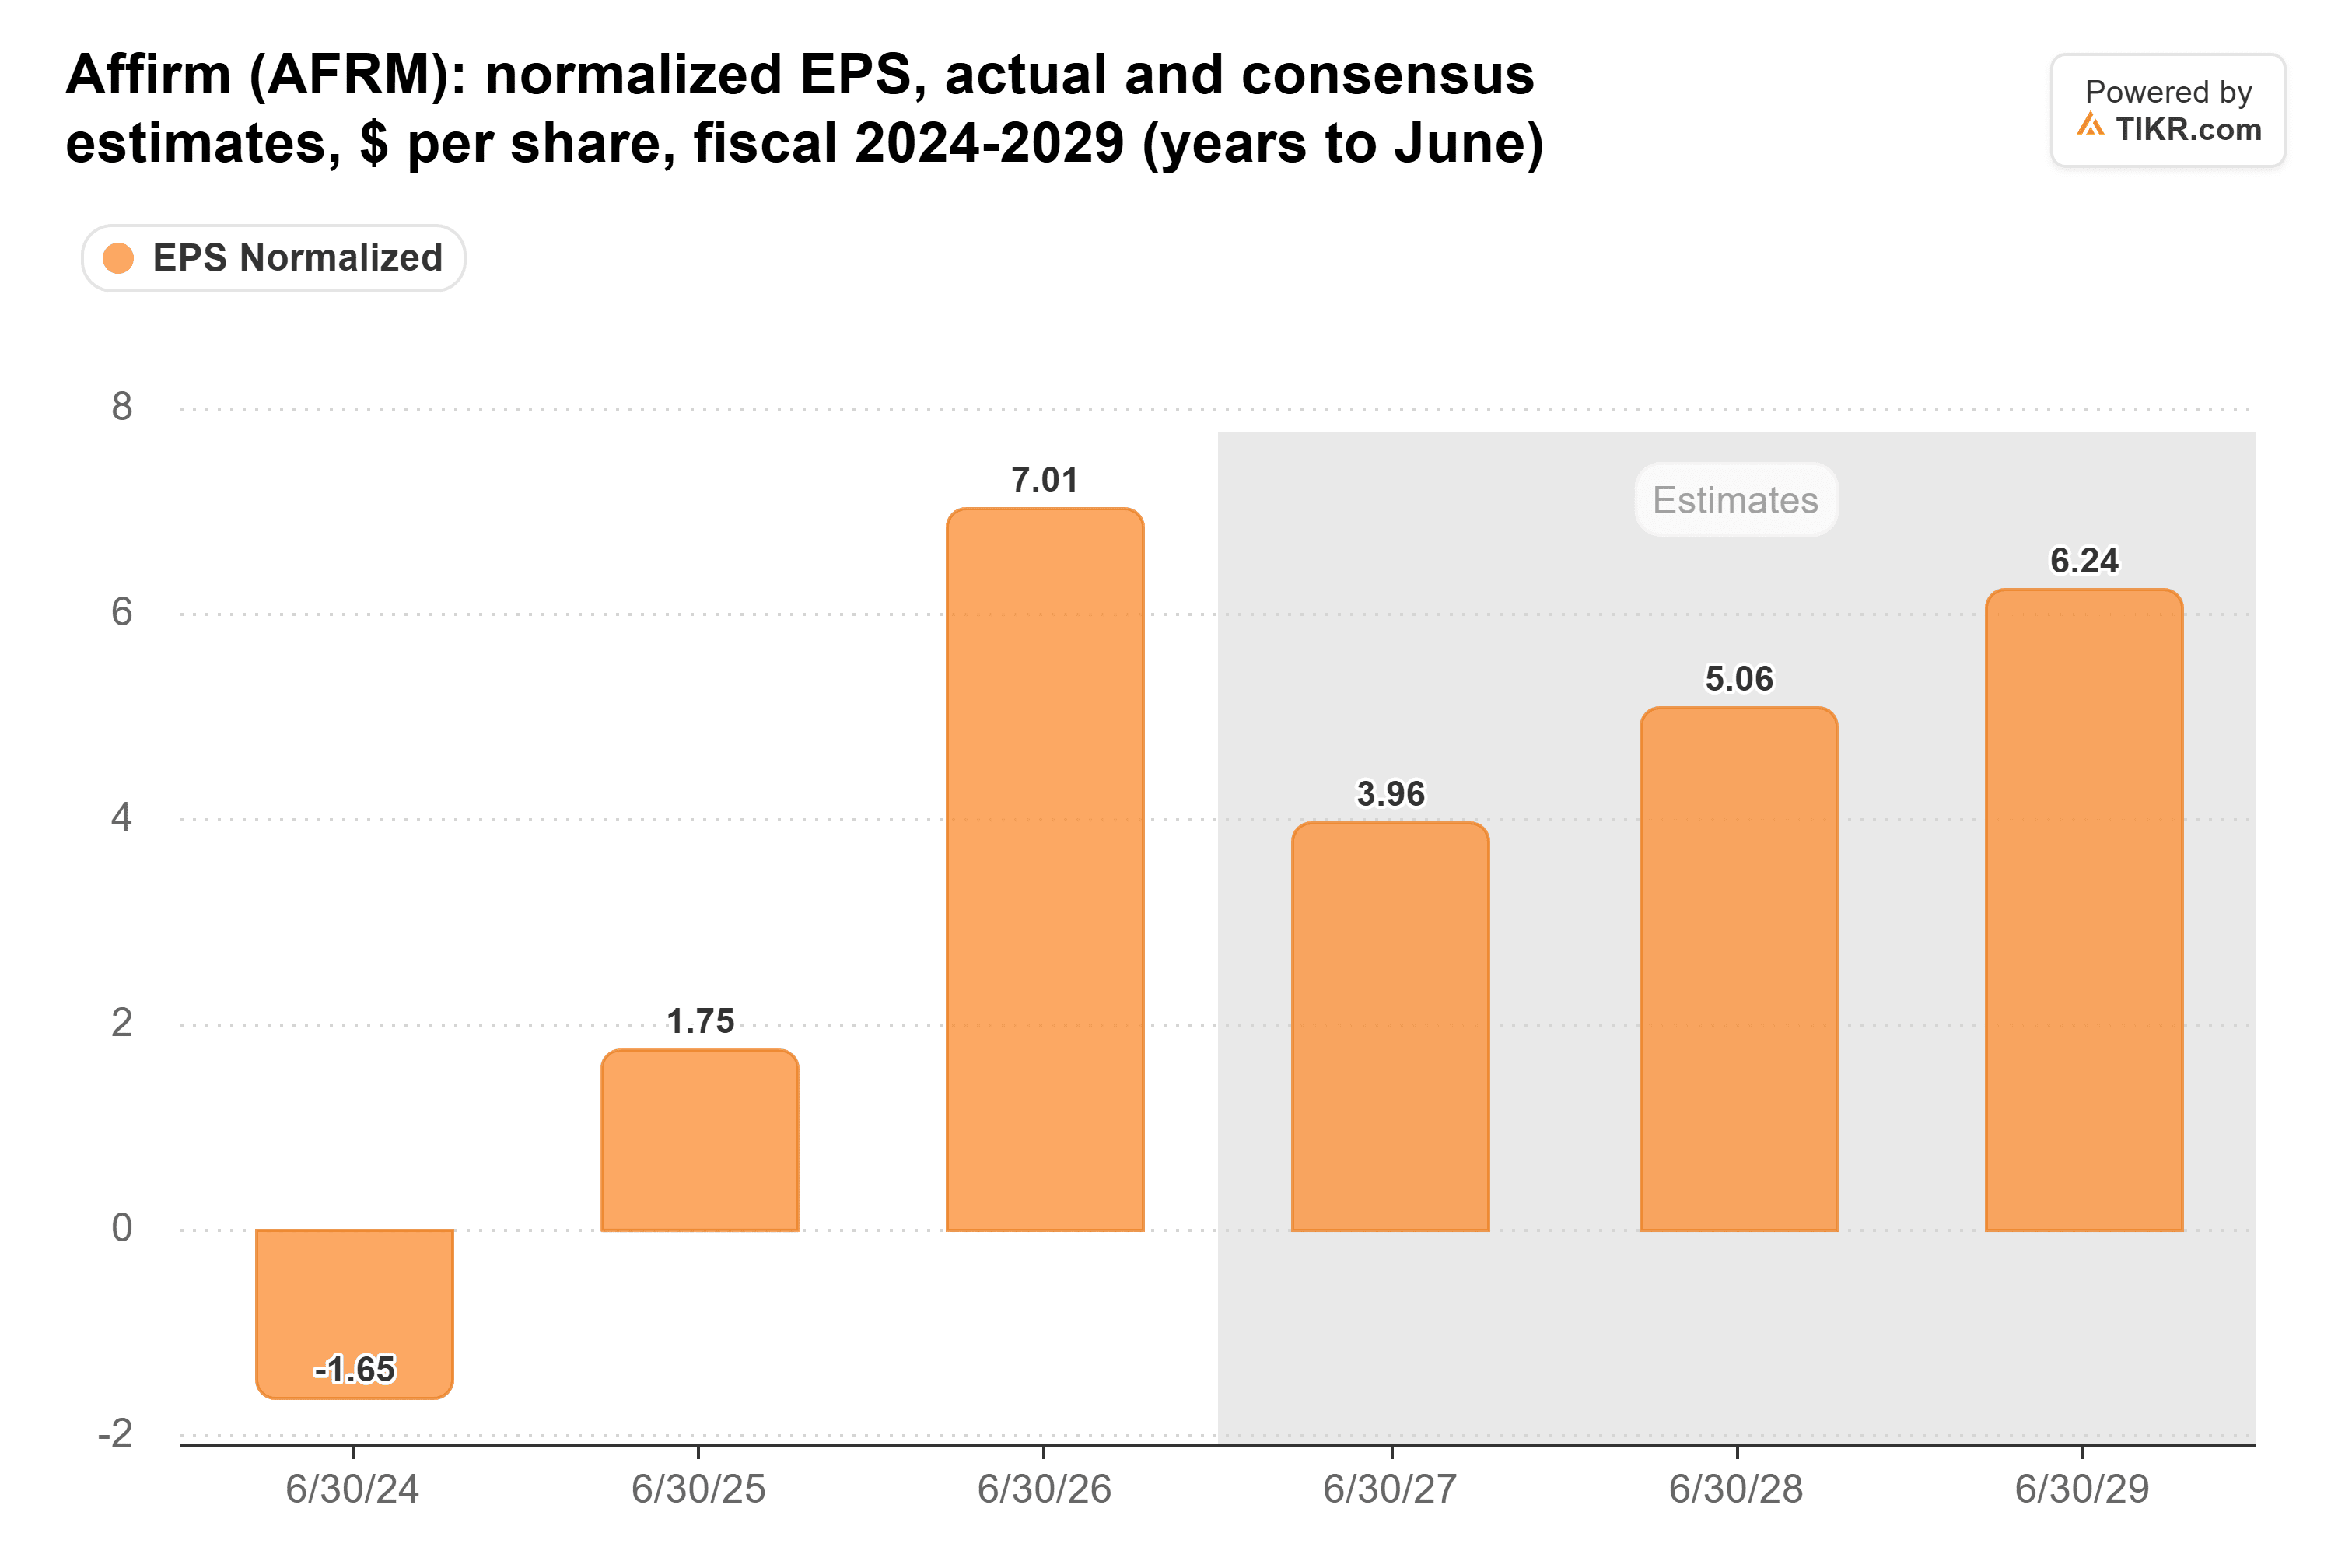
(Fiscal 2026’s spike was a one-time tax benefit.)
TIKR tracks 36 analysts on Affirm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Affirm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Affirm’s Analyst Ratings
About half its usual multiple
Affirm trades at about 14x forward earnings, roughly half the 28x it has averaged since September 2024. The consensus target has barely moved in a year:
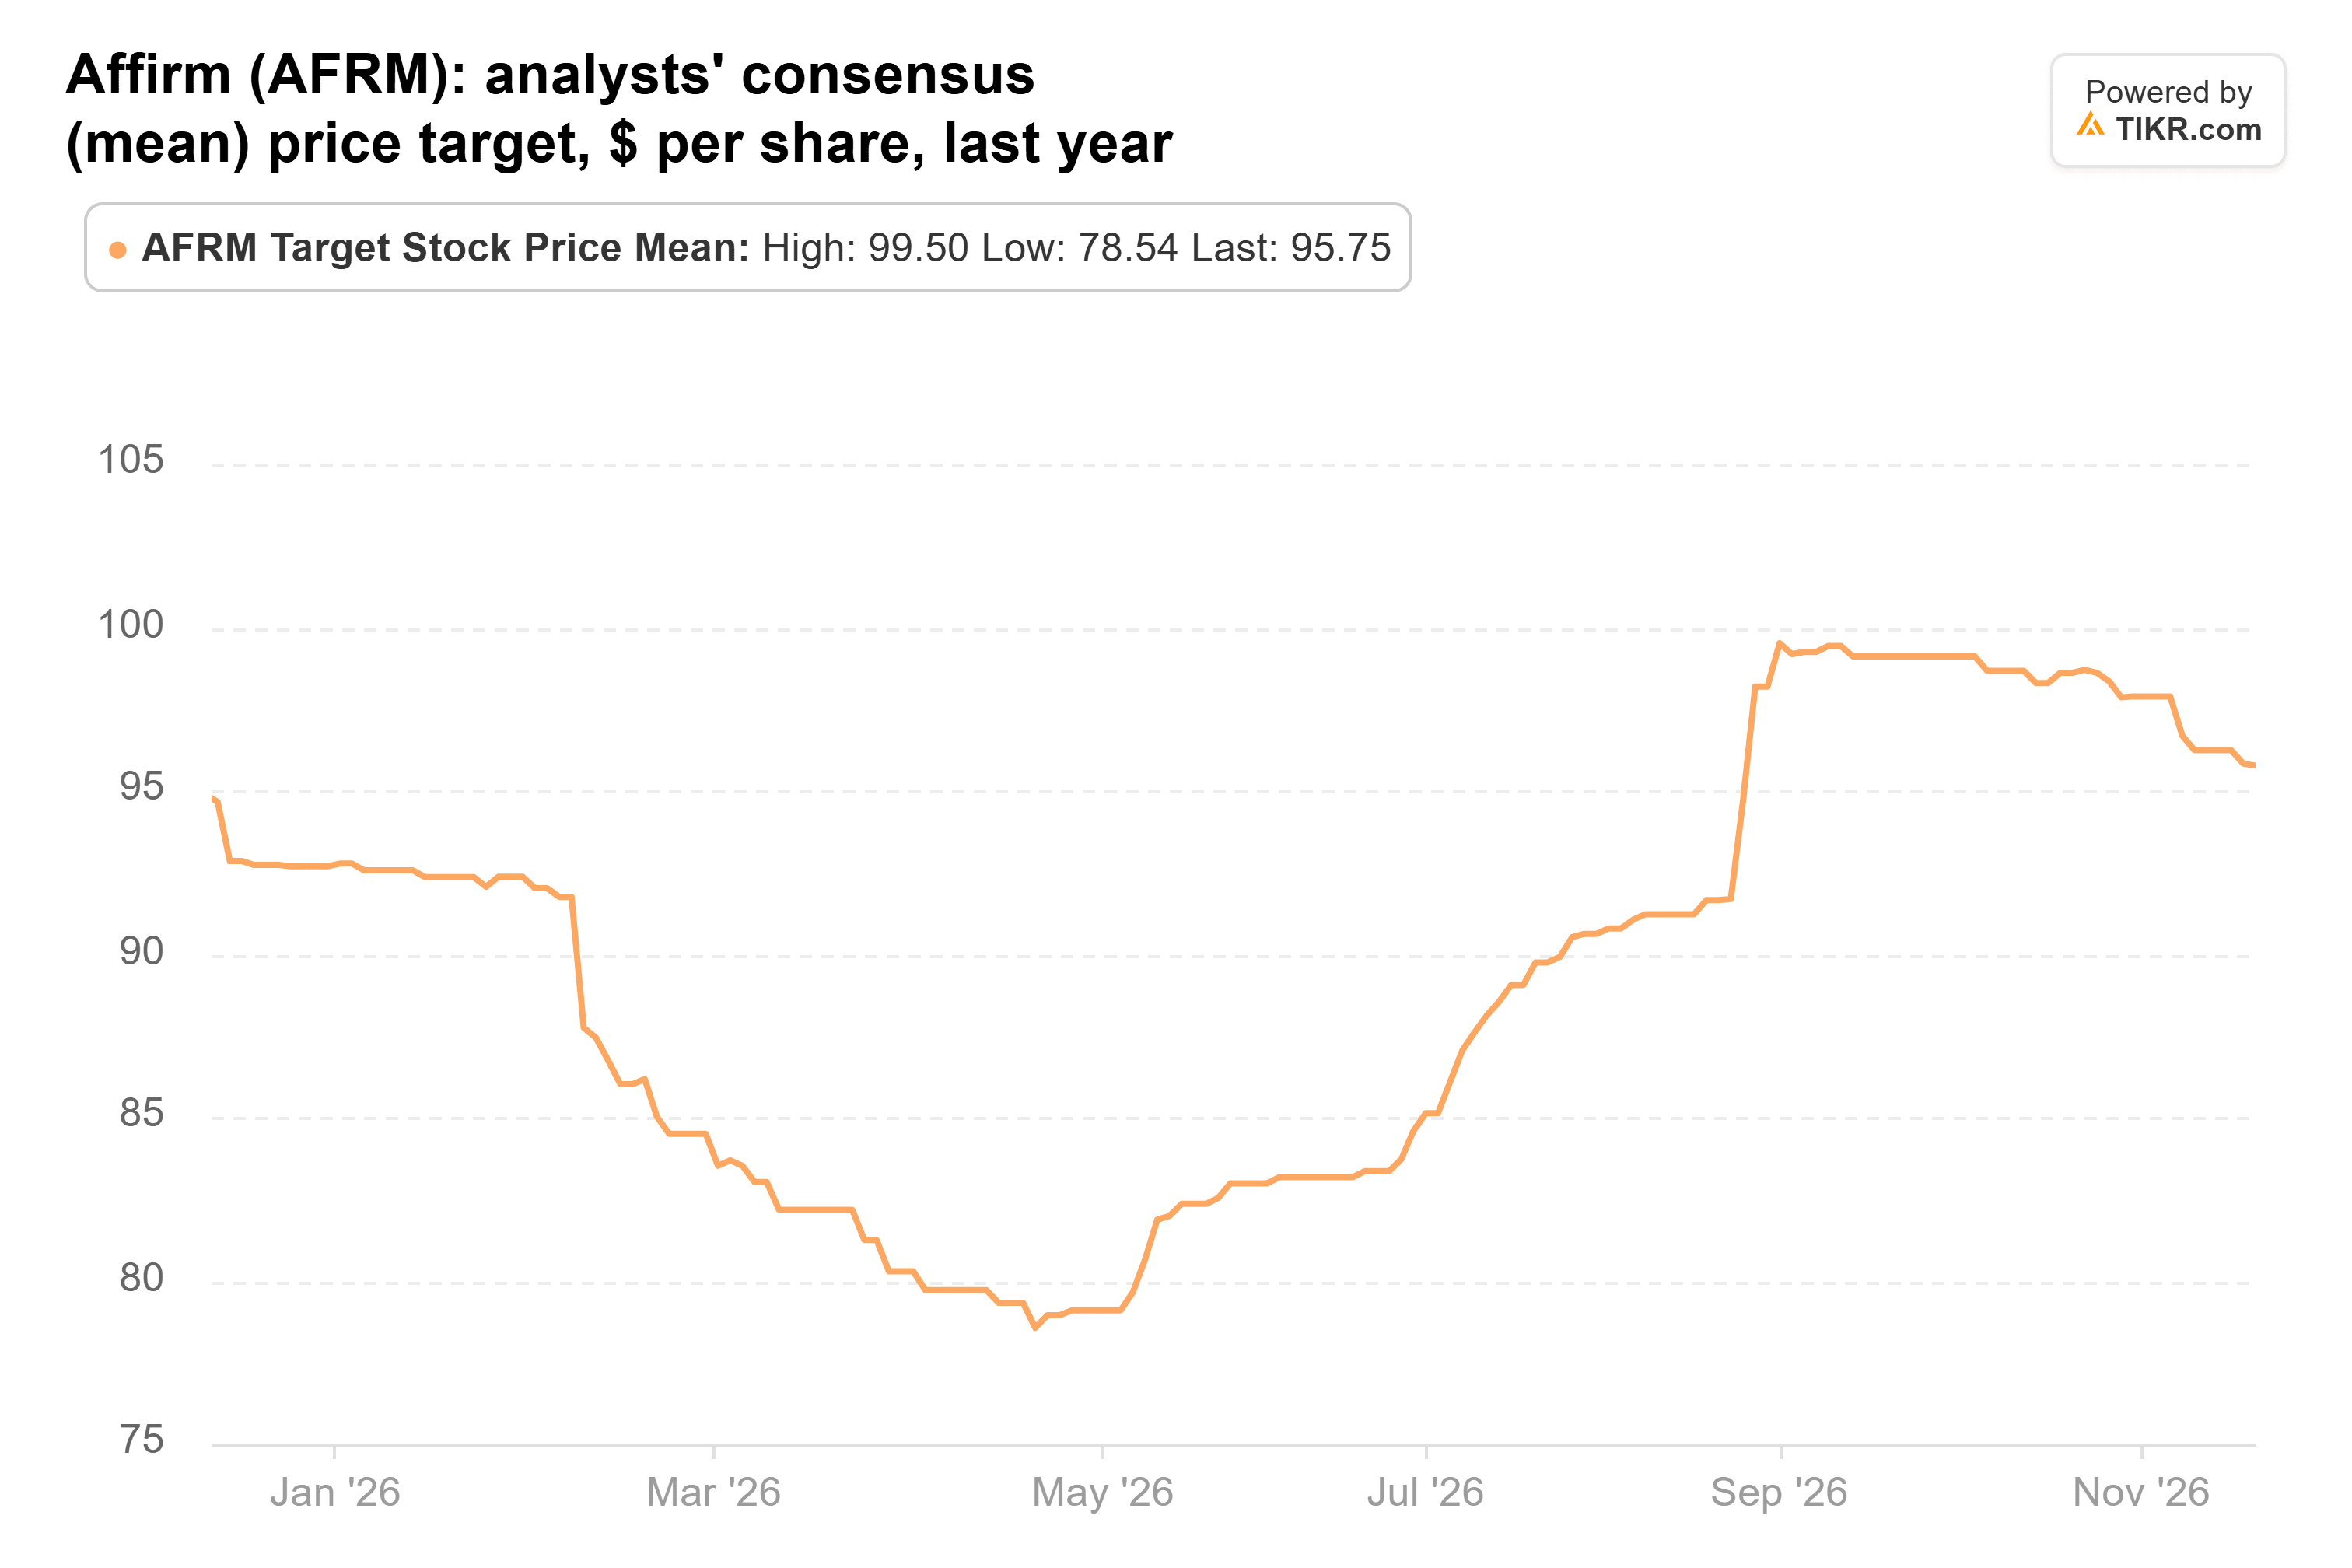
That $96 target is about 63% above the latest close, and it needs only 19x analysts’ $5.06 for fiscal 2028.
The risk is credit. Monthly loans 30 or more days late rose to 2.9% in the September quarter from 2.5% in June. I’d load up anyway, since the price already assumes credit gets worse. The holiday-quarter report in early February is the test: delinquencies at or below 2.9%, with RLTC at 4% of GMV or better, would confirm it.
So what is Affirm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Affirm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!