Key Takeaways
- Affirm is down 23% from its July high after a quarter of fast growth and higher late payments. Citi kept its Buy rating and its $115 target, 69% above today’s price.
- Citi’s case rests on three things: volume growth above guidance, new partners that bring in more merchants, and funding costs Affirm can absorb. The September quarter supported most of it.
- Citi’s $115 target is 27x the earnings analysts expect over the next twelve months. That’s close to the 28x Affirm has averaged since its forward P/E turned positive in 2024.
- The call looks right as long as delinquencies settle after the holidays. Affirm reports that quarter in early February.
Affirm Holdings (AFRM) just grew its volume 34%, and the stock is still down 23% from its July high. Citi’s Bryan Keane reiterated his Buy rating and $115 price target on Nov. 11, 69% above today’s price.
A strong quarter with a credit wrinkle
Affirm’s fiscal first-quarter results, out Nov. 5, beat its own guidance: gross merchandise volume (GMV) rose 34% to $14.4 billion, and revenue rose 35% to $1.26 billion.
But 30-day-plus delinquencies on its monthly loans rose 35 basis points from the June quarter to 2.9%. CFO Rob O’Hare said on the call that Affirm chose to “run some experiments within the approvals and the origination” in September. Affirm also guided its December-quarter GAAP operating margin below what analysts expected, on higher warrant expense for a large partner signing up new users.
TIKR tracks 36 analysts on Affirm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Affirm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Affirm’s Analyst Ratings
How Citi gets to $115
Keane laid out his case in an early-October note, and Affirm delivered on most of it.
He expected GMV growth at the high end of management’s 27% to 30% outlook. Affirm grew 34%, and O’Hare said the business is “growing at a high 30s rate today.”
He also pointed to early-stage partnerships with Intuit’s QuickBooks, ServiceTitan and Amazon in the UK. CEO Max Levchin said on the call that services, the category those software partners feed, was the best performer of the categories Affirm breaks out.
And he put the hit from recent rate moves at 15 to 20 basis points of revenue less transaction costs (RLTC). Funding costs rose 27 basis points from the June quarter, yet RLTC came in at 4.3% of GMV, above management’s 3.75% to 4% medium-term range.
Does $115 add up?
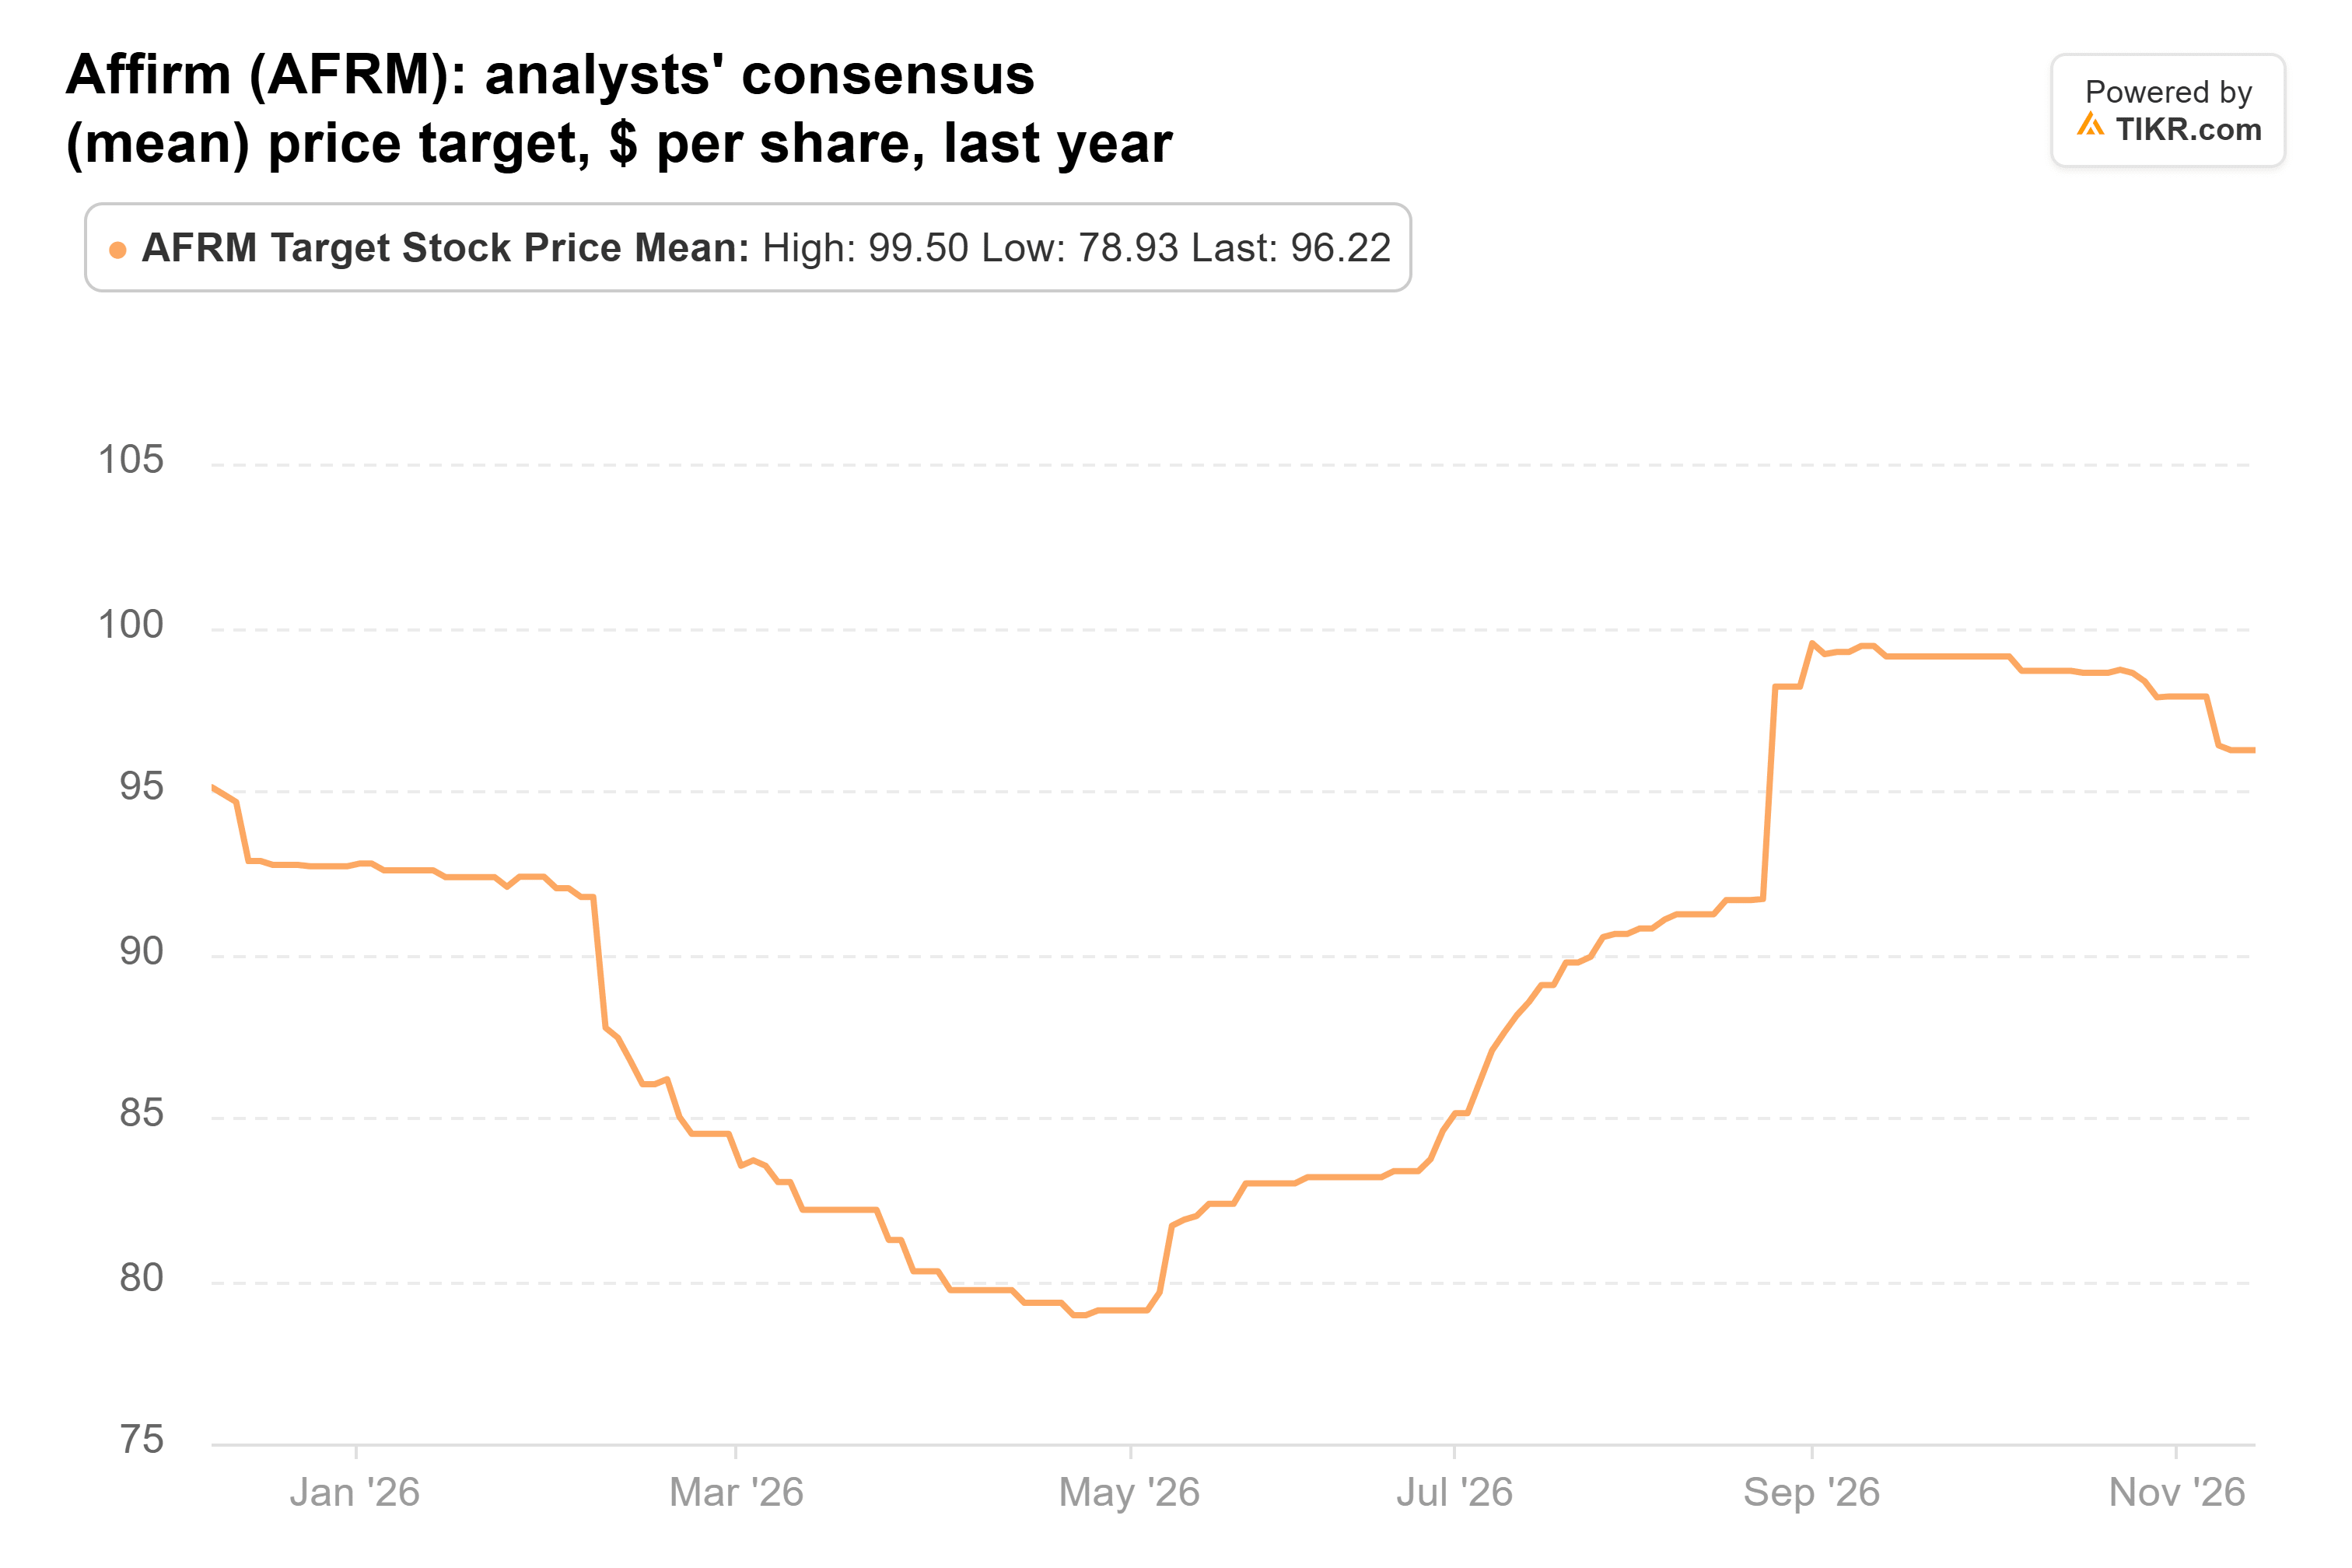
The consensus target is $96, 41% above today’s price but 20% below Citi’s. It’s also about where it was a year ago:
Estimates are rising, though: consensus EPS for the fiscal year to June 2027 is up to $3.95 from $3.72 90 days ago, and fiscal 2028’s is up to $5.02 from $4.73:
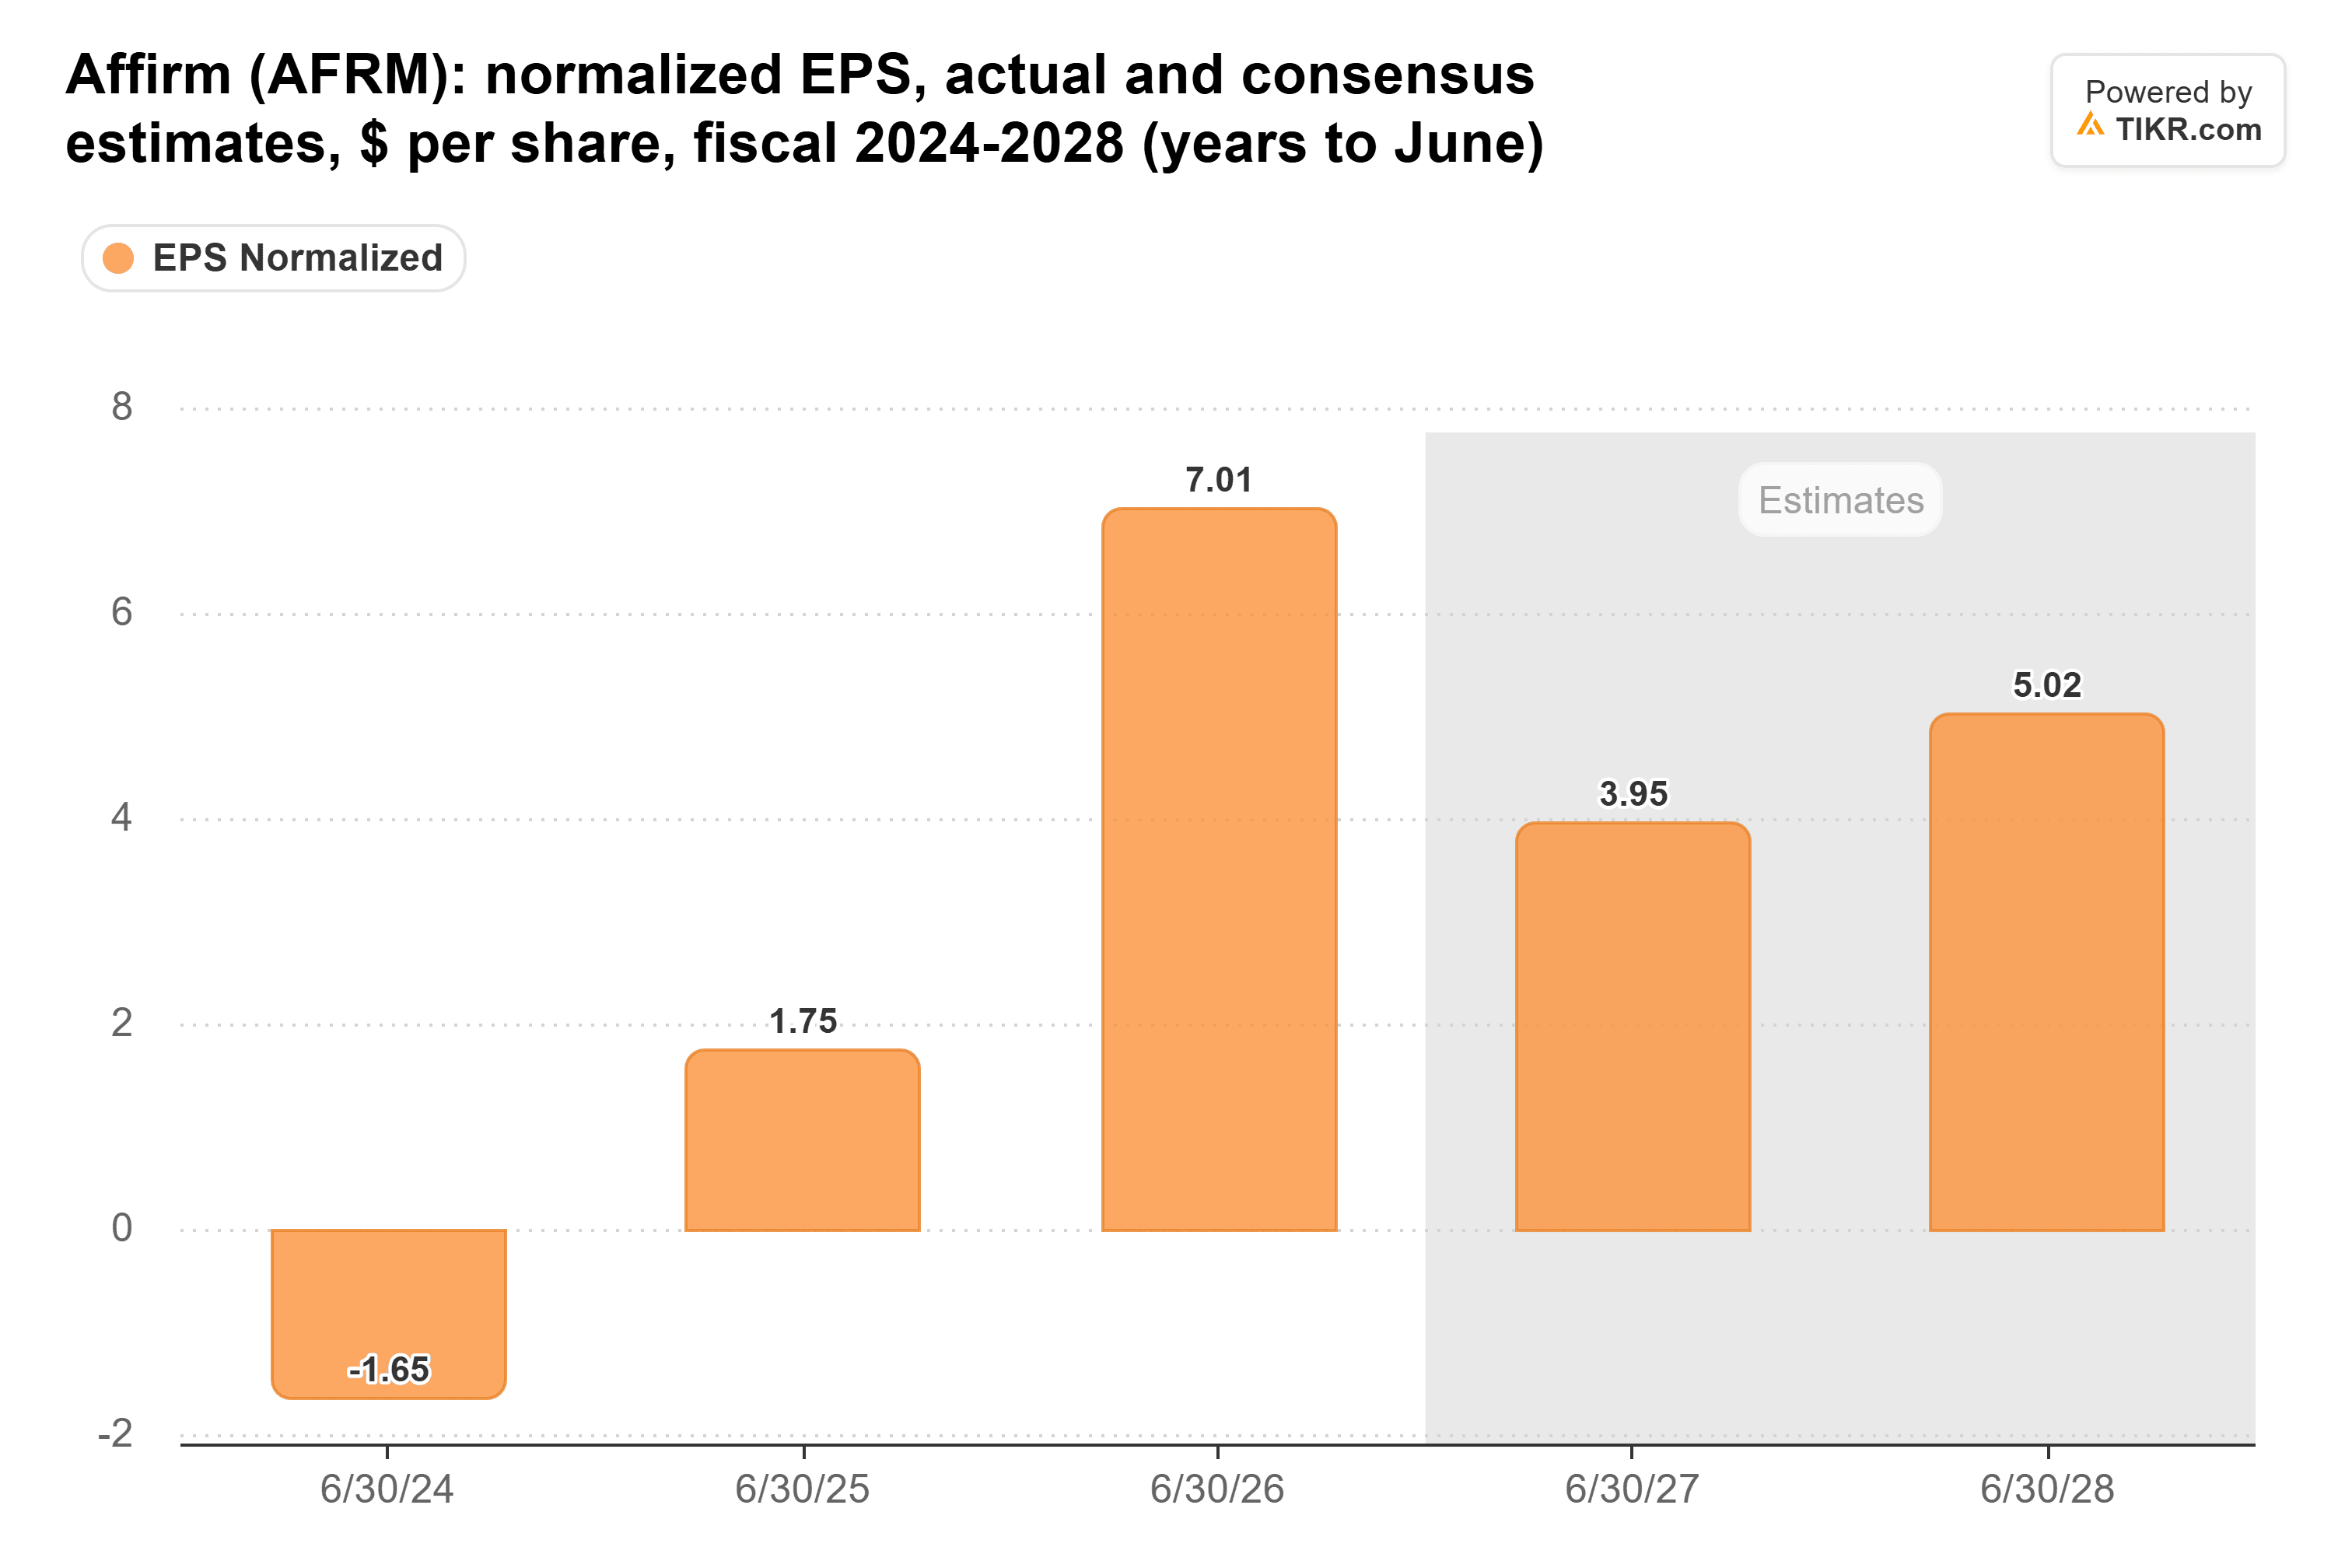
(Fiscal 2026 got a lift from a one-time, non-cash tax benefit of $1.4 billion, so ignore the dip.)
Citi’s $115 is 27x the $4.22 a share analysts expect Affirm to earn over the next twelve months. Affirm has averaged 28x since its forward P/E turned positive in September 2024, and it trades at about 16x today.
Citi’s $115 looks fair to me
Those normalized earnings leave out the stock pay and partner warrants that keep Affirm’s GAAP profit far lower: it earned $0.47 a share under GAAP in the September quarter.
Still, I think Citi has this one right: its target needs only Affirm’s usual multiple on estimates that keep climbing. The December-quarter report, expected in early February, is the next test, and holiday-quarter delinquencies are the number to watch.
So what is Affirm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Affirm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!