


Key Takeaways
- AbbVie’s lutikizumab met its Phase 3 goal in hidradenitis suppurativa, with 31.4% of patients reaching HiSCR75 at Week 16 versus 23.4% on placebo.
- The thin 8-point gap sent rival MoonLake higher and Avalo, which targets a similar pathway, sharply lower.
- Shares sit near $285, above the $283.50 Street target, after a 40.7% total return in six months on Skyrizi and Rinvoq growth.
- Q3 results on October 30 will show whether immunology momentum keeps revenue guidance moving higher.
AbbVie (ABBV) won a Phase 3 trial on Thursday, and its competitors threw the party.
Lutikizumab, AbbVie’s IL-1α/β antibody for hidradenitis suppurativa, hit its primary endpoint. But the margin over placebo was thin, so MoonLake Immunotherapeutics (MLTX) jumped as competition fears eased, while Avalo Therapeutics (AVTX), which targets a similar pathway, plunged.
AbbVie itself barely moved, trading near $285. That calm says a lot about what actually drives this stock right now.
It also raises a valuation question. Shares sit slightly above the $283.50 average Street target after a 40.7% total return in six months.
Eight points of daylight
The headline numbers from the INTREPID study:
- 31.4% of patients on weekly lutikizumab reached HiSCR75 at Week 16
- 23.4% reached it on placebo
- Fewer flares, better pain scores and a placebo-like safety profile
An 8-point placebo-adjusted gain clears the statistical bar. However, it falls short of what many investors hoped for in a crowded HS market. The Phase 2 trial had shown HiSCR75 rates of up to 45.9% in higher-dose groups versus 17.5% on placebo, albeit in patients who had failed anti-TNF therapy.
AbbVie plans to file in the second half of 2027 using 36-week extension data. It also wants to test the drug alongside a weight-loss treatment.
MoonLake and Avalo have traded on every HS headline this year, including this one…

AbbVie’s line barely registers HS news, while the two smaller names swing hard on it.
Skyrizi and Rinvoq still do the lifting
Lutikizumab was always a side dish. The main course is Skyrizi and Rinvoq.
In Q2, revenue rose 10.2% to $16.99 billion and adjusted EPS rose 22.9% to $3.65. Immunology grew 15.1% to $8.79 billion, with Skyrizi at $5.51 billion and Rinvoq at $2.53 billion, each up about 24%.
Management then raised 2026 revenue guidance by $300 million to $67.2 billion to $68.2 billion, its second increase this year. AbbVie is also buying Apogee Therapeutics (APGE) for $135.11 per share in cash to add long-acting immunology assets as Skyrizi and Rinvoq mature.
Competition keeps coming, though. Johnson & Johnson (JNJ) grew Tremfya 68% last quarter, and roughly 20,000 patients have already started its oral psoriasis pill, Icotyde.
Here is the top line, actual and expected.

Revenue has fully climbed out of the Humira trough, and consensus sees 9.7% annual growth over the next two years.
TIKR tracks 30 analysts on AbbVie. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AbbVie, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AbbVie’s Analyst Ratings
Earnings catch up to the price
The trailing numbers look alarming. AbbVie trades at 80.5x trailing earnings with a 189.8% payout ratio, both inflated by acquired pipeline charges. Q3 alone carries $216 million of acquired IPR&D and milestone expense.
Forward numbers tell a cleaner story. AbbVie trades at 18.9x forward earnings, below J&J at 23.2x, and consensus expects EPS to grow 27.3% a year over the next two years versus 3.8% at J&J.
Debt is the trade-off, with net debt at 2.06x EBITDA as AbbVie keeps buying growth.
So how steep is that EPS path?
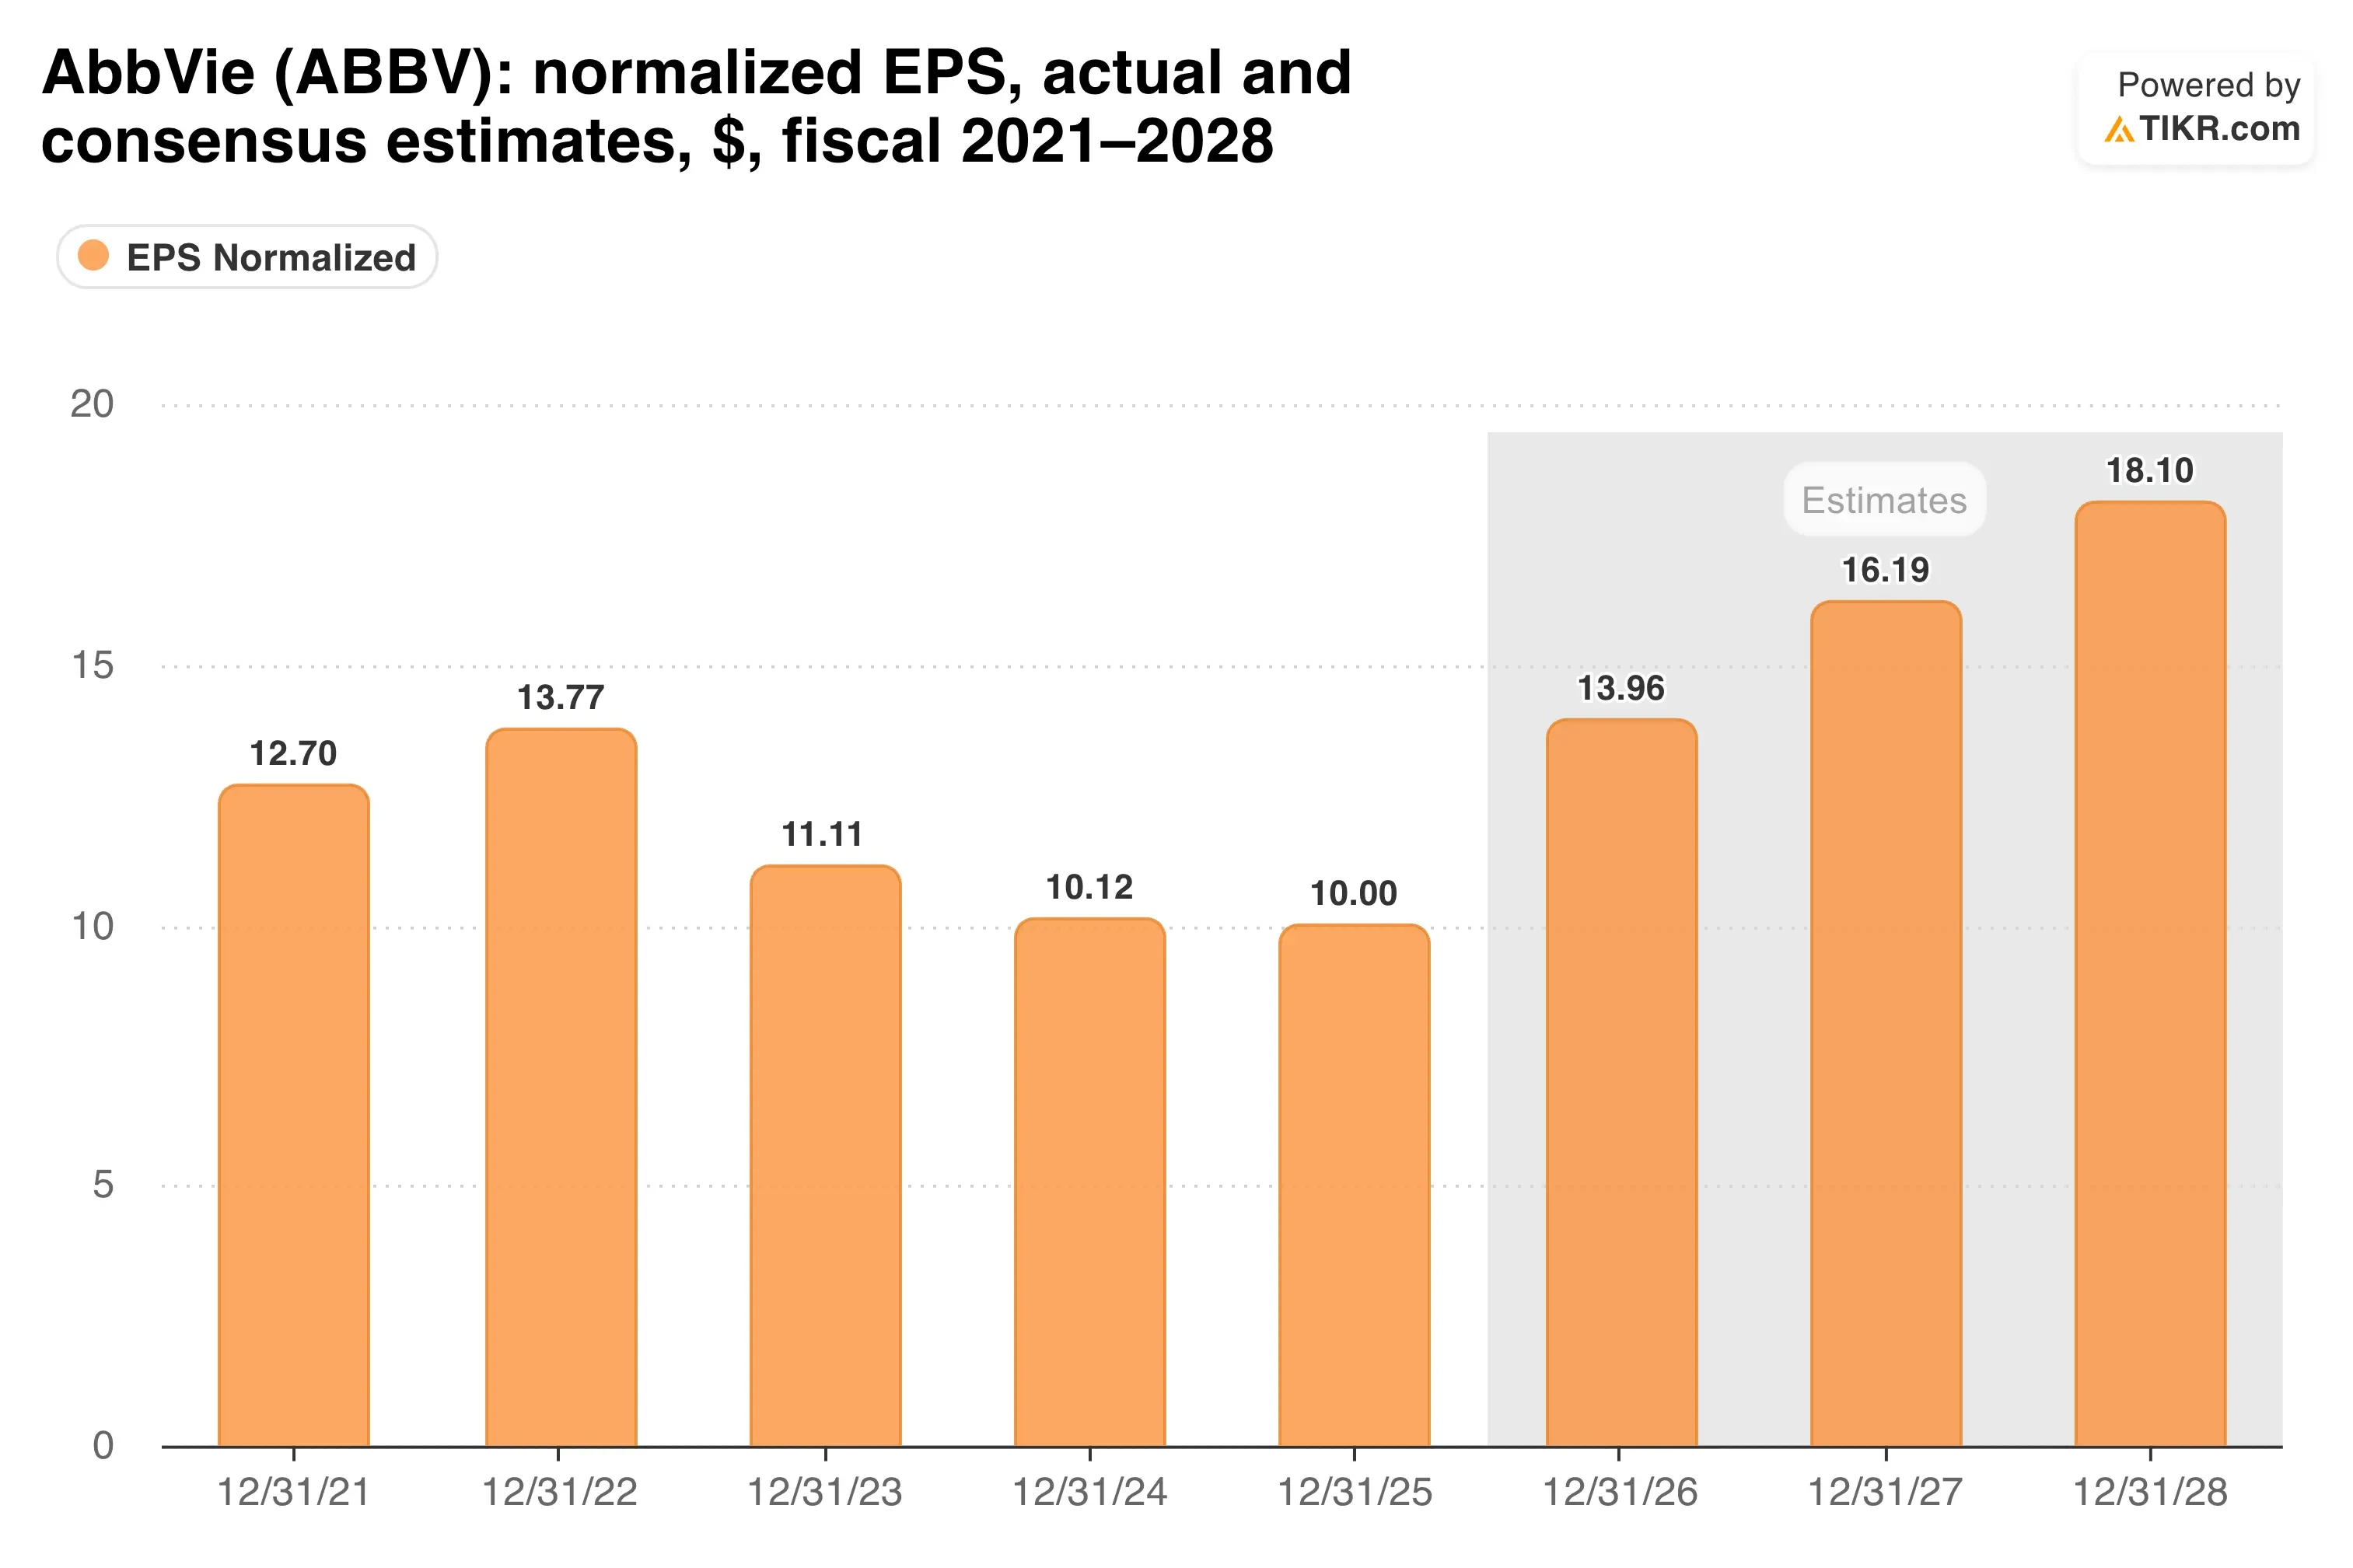
My take: Lutikizumab disappointed, but HS was never going to decide AbbVie’s next five years. The stock already sits above its Street target, so more upside likely needs another guidance raise and proof that Apogee’s assets can extend the franchise into the 2030s.
Q3 results on October 30 are the next test. Look for Skyrizi and Rinvoq growth above 20% and a third revenue guidance raise.
So what is AbbVie stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AbbVie could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


