Key Takeaways
- A fund holding $7.2 billion of US stocks made Alphabet, Amazon and Lam Research its three biggest new or added positions in the third quarter.
- Alphabet and Lam Research have fallen 21% and 38% since Sept. 30, while Amazon is up 3%.
- Analysts’ average targets sit 47% above Alphabet’s price, 27% above Amazon’s and 78% above Lam’s.
- Alphabet is the one to buy first: it trades at about 20x forward earnings, and even Wall Street’s lowest target is above its price.
Following a fund’s 13F often means buying stocks that have already run. This one is different: two of its three biggest new bets are far cheaper today than they were at the end of September.
Evergreen Quality Fund GP’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows it made Alphabet (GOOGL), Amazon (AMZN) and Lam Research (LRCX) its three biggest new or added positions. Together they were worth about $2 billion at quarter-end prices, more than a quarter of the $7.2 billion of US stocks the 13F holds.
Alphabet is now its biggest bet
Evergreen held only a sliver of Alphabet at June 30. By Sept. 30, it owned 2.69 million shares worth $925 million, 12.8% of its 13F and its biggest holding.
The stock has fallen 21% from its Sept. 30 price, to its lowest close of the past year on Nov. 19. The biggest blow came after third-quarter results on Oct. 28: Alphabet fell 13% the next day, after spending $51.4 billion on capex in the quarter, more than the $42.3 billion of cash its operations brought in. Management expects that spending to rise significantly in 2027.
Alphabet fell another 3% on Nov. 19, the day Anthropic debuted on Nasdaq. Per Anthropic’s amended S-1, Google will own 13.7% of Anthropic after the IPO and Amazon 14.7%, so the new stock’s swings now run through both companies’ earnings, and nearly 40% of the deal was free to trade on day one.
TIKR tracks 58 analysts on Alphabet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
Amazon has held up, and AWS is why
Amazon was a new position: 2.61 million shares worth $650 million, 9.0% of the 13F and the fund’s No. 2 holding. It’s the only one of the three that’s risen since Sept. 30, by 3%.
On Oct. 29, Amazon reported third-quarter AWS sales up 39% to $46.0 billion, the cloud’s fastest growth in nearly five years, and a 13.9% operating margin for the whole company, its highest ever. CEO Andy Jassy then said on CNBC on Nov. 17 that compute is largely reserved for 2027, “a good chunk” of 2028 and “a fair bit” of 2029.
He also expects about $220 billion of capex this year and “meaningfully more” in 2027, and consensus has free cash flow at a $41.2 billion outflow this year before it turns positive in 2028.
Lam Research has taken the hardest hit
Lam was new to the fund too: 1.30 million shares worth $428 million, 5.9% of the 13F and its fourth-largest holding. It has fallen 38% from its Sept. 30 price and sits 54% below its 52-week high.
Chip-equipment stocks were already sliding when the selloff deepened after the midterms. Lam answered with a $25 billion buyback, close to a tenth of its market value at the last close. Even after the drop, the stock is well above the $149 it closed at a year ago.
Wall Street hasn’t followed the prices down
Analysts’ average targets for all three are higher than a year ago, even with two of the stocks well off their highs. Alphabet’s consensus target rose to $400 from $318 over the past year:
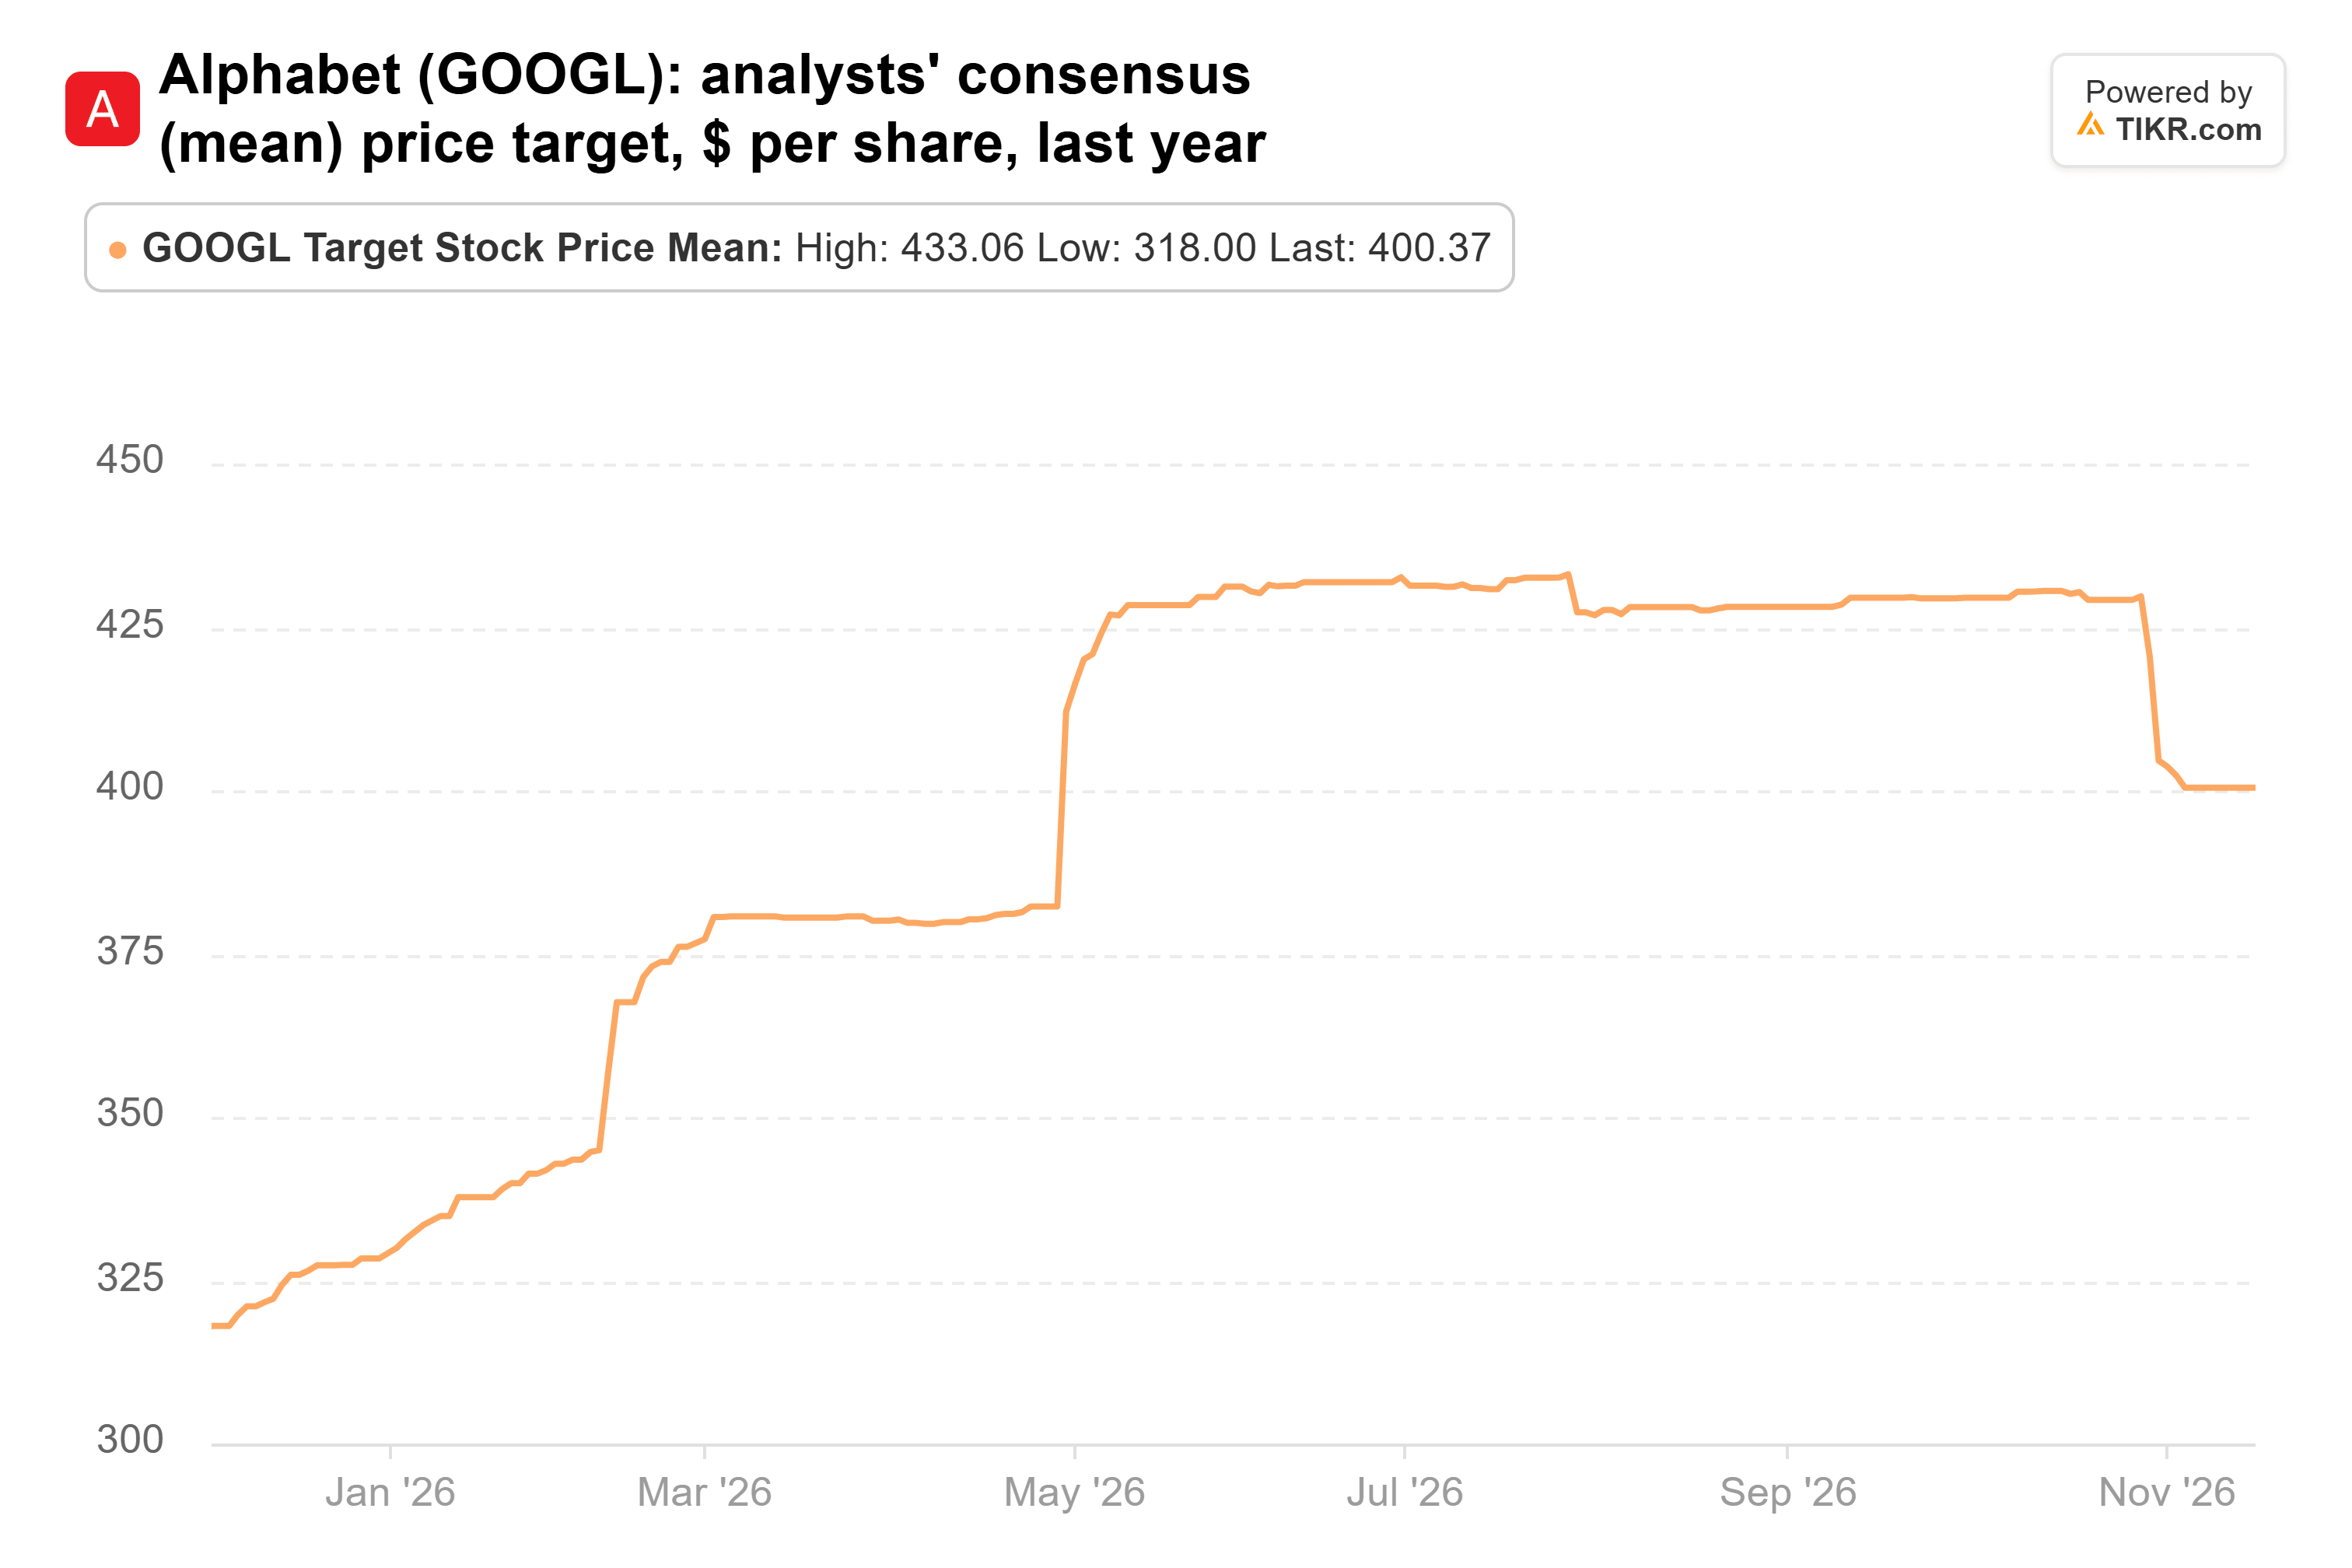
That’s 47% above the last close, and even the lowest target, $300, is above the price. Alphabet trades at about 20x forward earnings.
Amazon’s consensus target climbed to $326 from $293 over the same stretch:
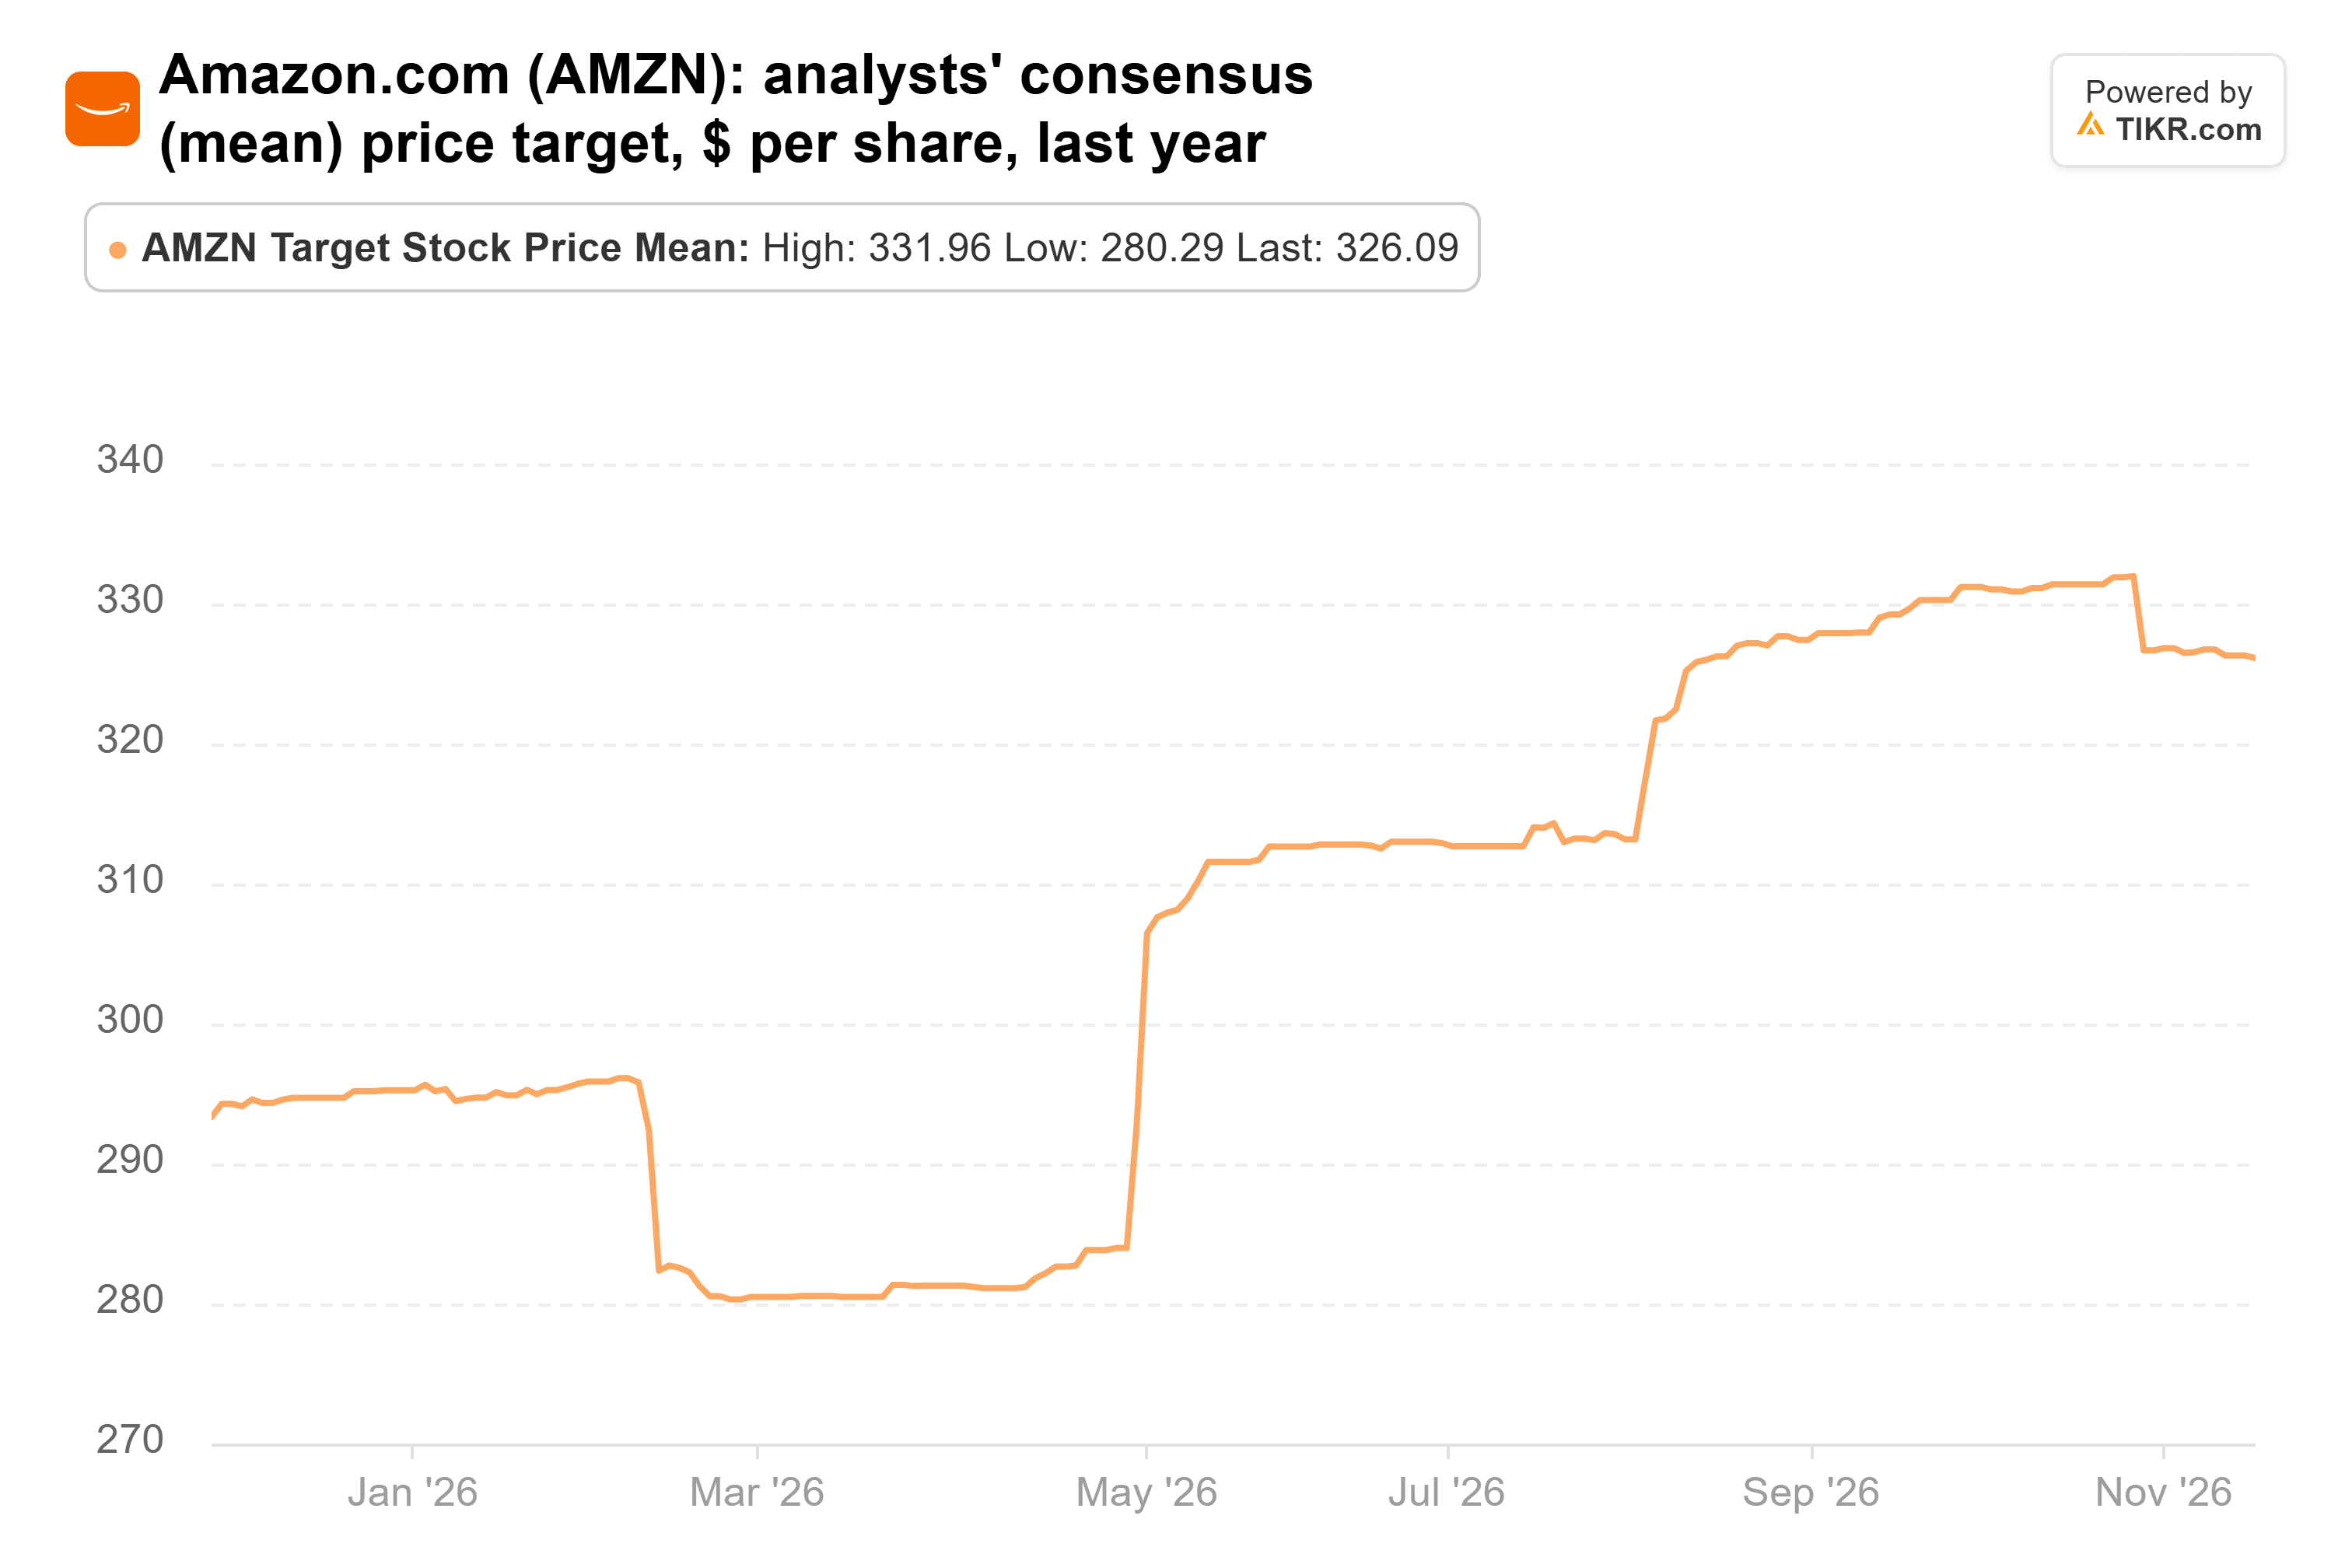
That’s 27% above the price. Amazon trades at about 26x forward earnings, right around its lowest quarter-end reading since 2014 (about 27x, in March 2026) and far below its five-year average of about 49x.
Lam’s average target more than doubled, to $362 from $159, and has slipped only a little from its $378 peak in October:
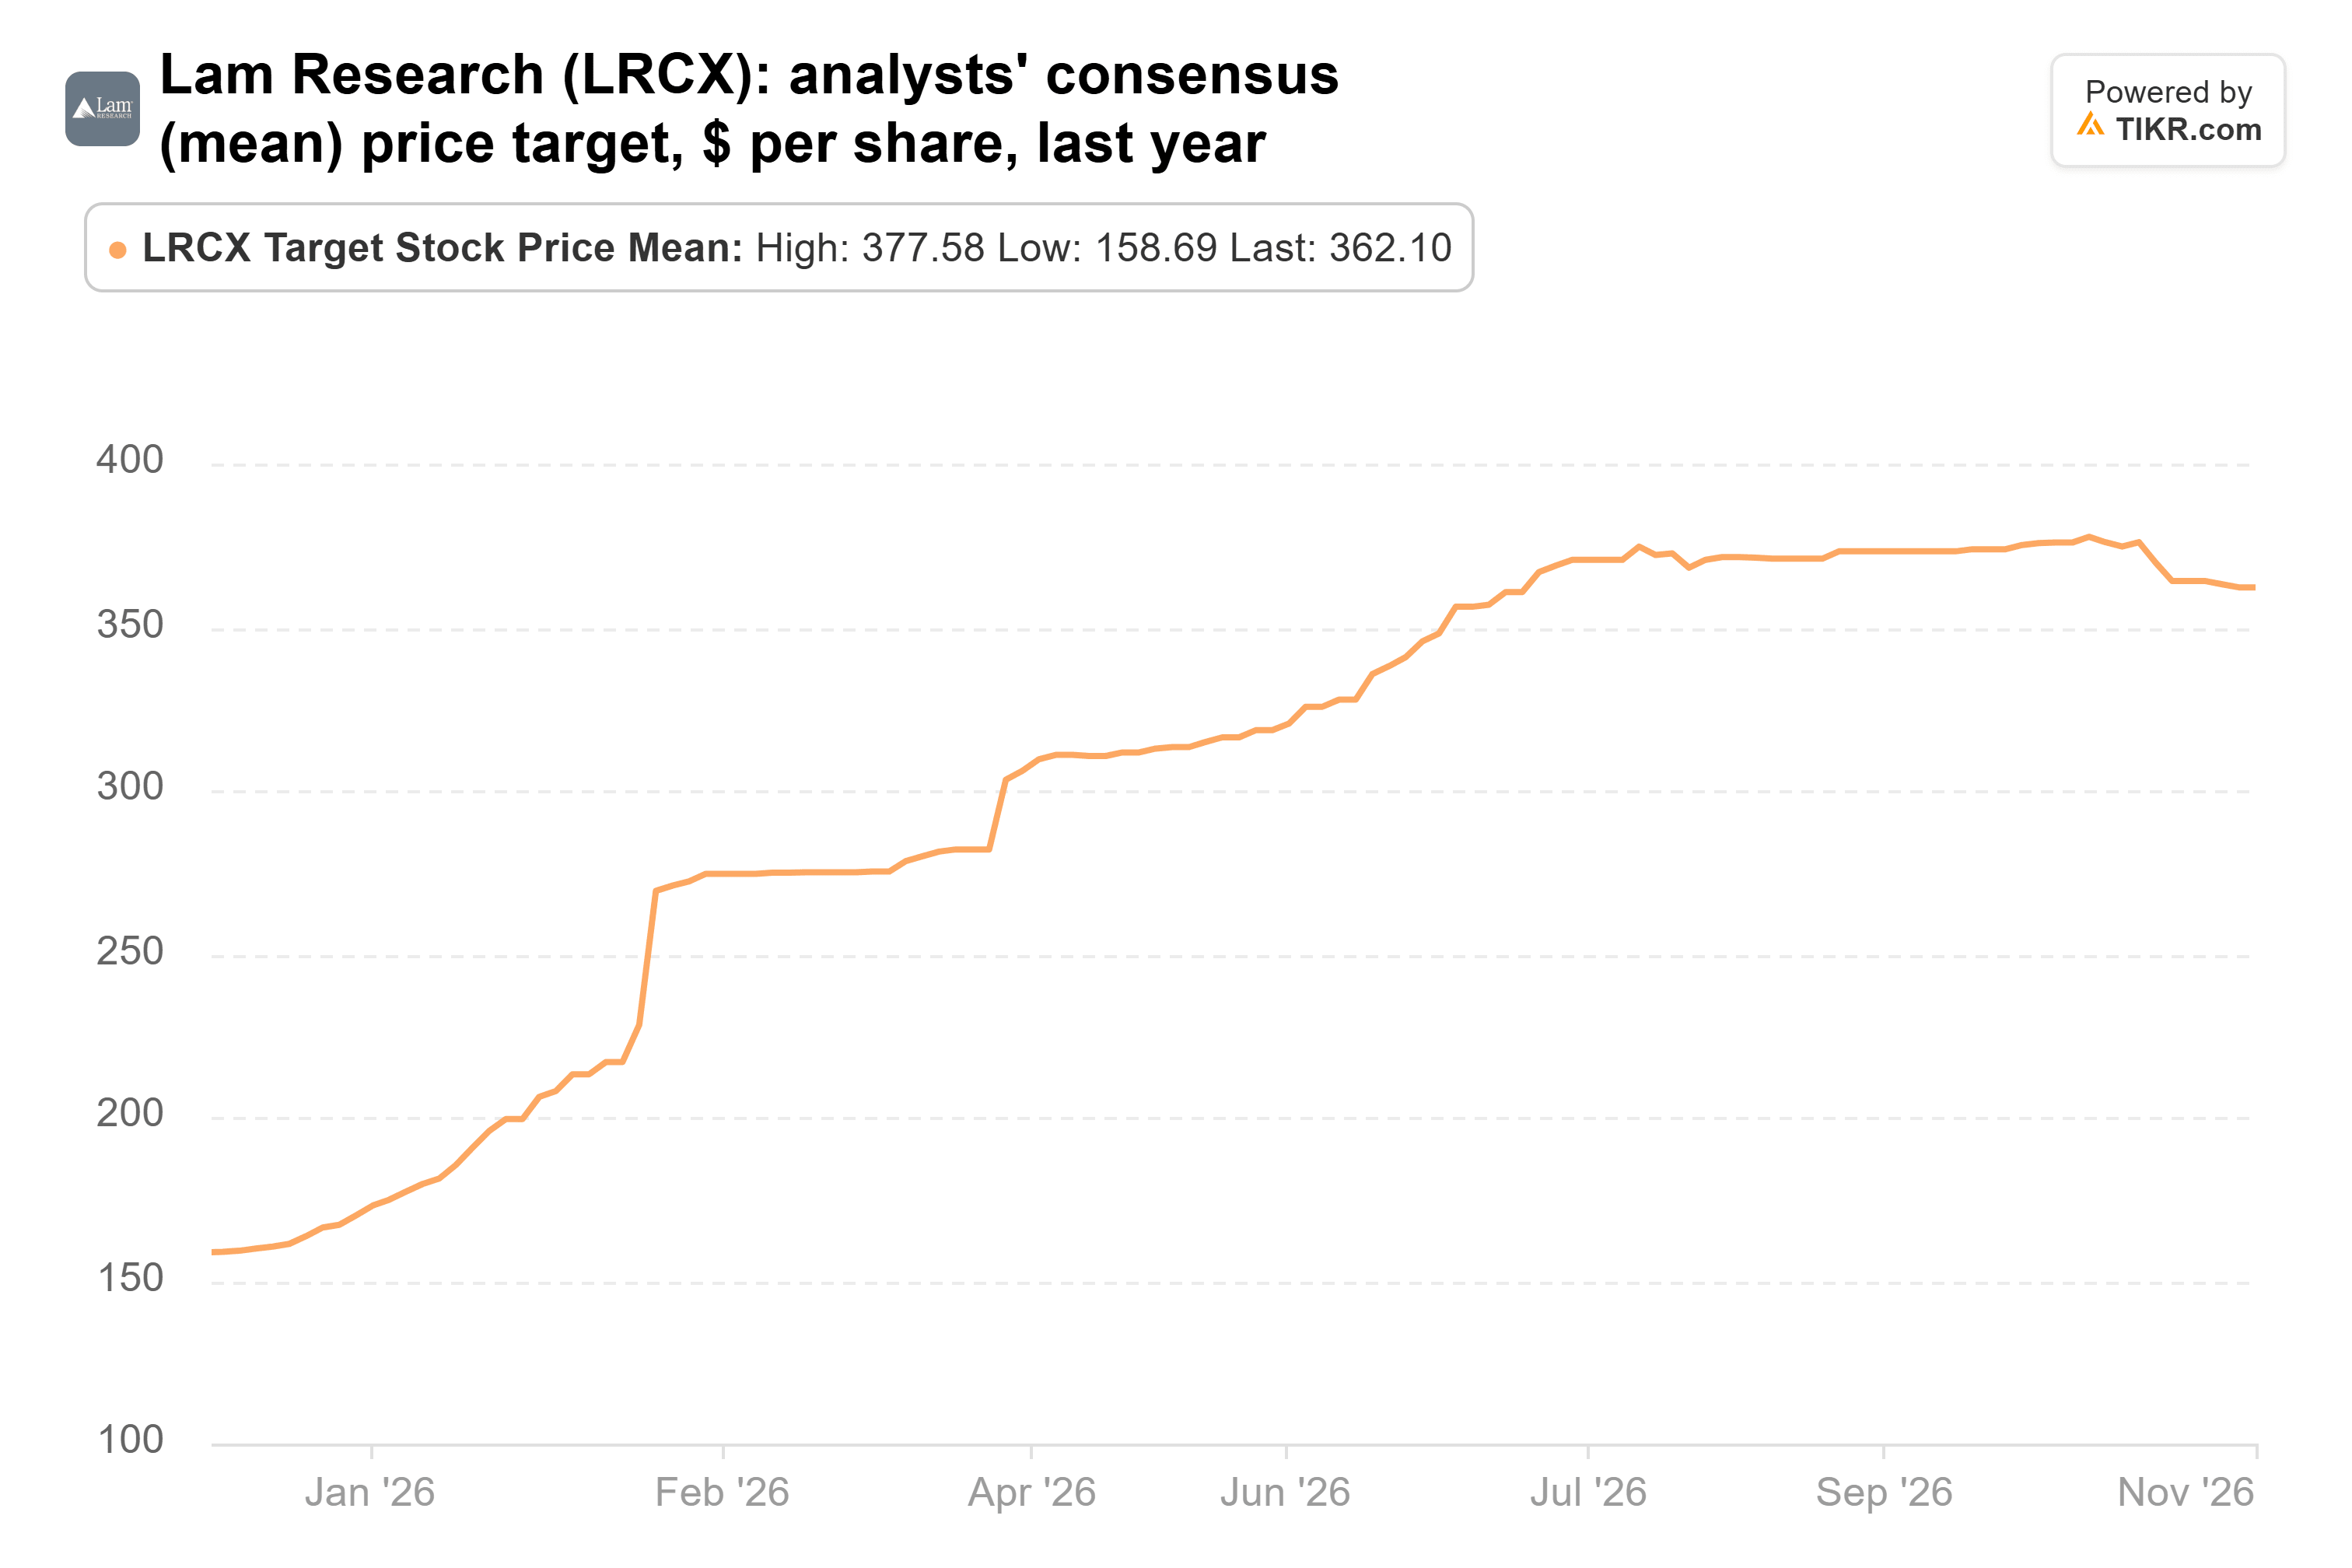
That’s 78% above the price, at about 20x forward earnings, and even the lowest target, $255, sits above it.
Alphabet is the one to buy first
All three need the AI buildout to keep paying off, and the two biggest are borrowing to pay for their part of it: Alphabet’s total debt reached $142 billion at Sept. 30, up from $33.7 billion a year earlier.
If I had to pick one of the three today, it’d be Alphabet. Its spending is outrunning its operating cash for now, but it also held $265 billion of cash and short-term investments at Sept. 30, which is plenty to carry the build until it pays off. Buying the fund’s top pick for well below its quarter-end price looks like a good deal to me. Lam has the most upside to its average target, but I’d want to see chip-equipment stocks find a floor first.
The next test comes early next year, when all three report their fourth quarters and Alphabet and Amazon put numbers on 2027’s spending. For Alphabet, the figure to watch is whether cash from operations catches back up to capex. Evergreen’s next 13F, due in mid-February, will show whether it held on.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!