Key Takeaways
- Lam Research shares jumped 9% today after its board approved a $25 billion buyback, outpacing ASML and the other chip-equipment makers in the rebound.
- Lam had no other news, so the buyback is the clearest reason for the extra gain, and it’s a strong vote of confidence.
- Analysts still expect Lam’s earnings to more than double from fiscal 2026 to 2028.
- KLA’s next report and TSMC’s 2027 spending plan will show whether Lam’s call for over $200 billion of equipment spending next year holds.
Lam Research (LRCX) jumped 9% today after its board approved a $25 billion buyback, worth more than a tenth of its market value. It came after Thursday’s close, when the stock had fallen 14% in the post-midterm chip rout.
Chip equipment bounced across the board, just not as hard: ASML (ASML) rose 5% and Applied Materials (AMAT) rose 6%. The buyback is Lam betting that chipmakers keep buying its tools. That bet matters just as much to KLA (KLAC), and it depends on buyers like Taiwan Semiconductor Manufacturing (TSM).
A vote of confidence
Applied Materials and ASML had no news of their own, so Lam’s extra few points belong to the buyback.
And Lam can pay for it. It brought in a record $3.24 billion of free cash flow in the September quarter alone, so $25 billion is about two years of cash at that pace. (The program has no end date and doesn’t oblige Lam to buy anything.)
The estimates still point up
As of late October, analysts expected Lam’s normalized EPS to more than double from fiscal 2026 to fiscal 2028:
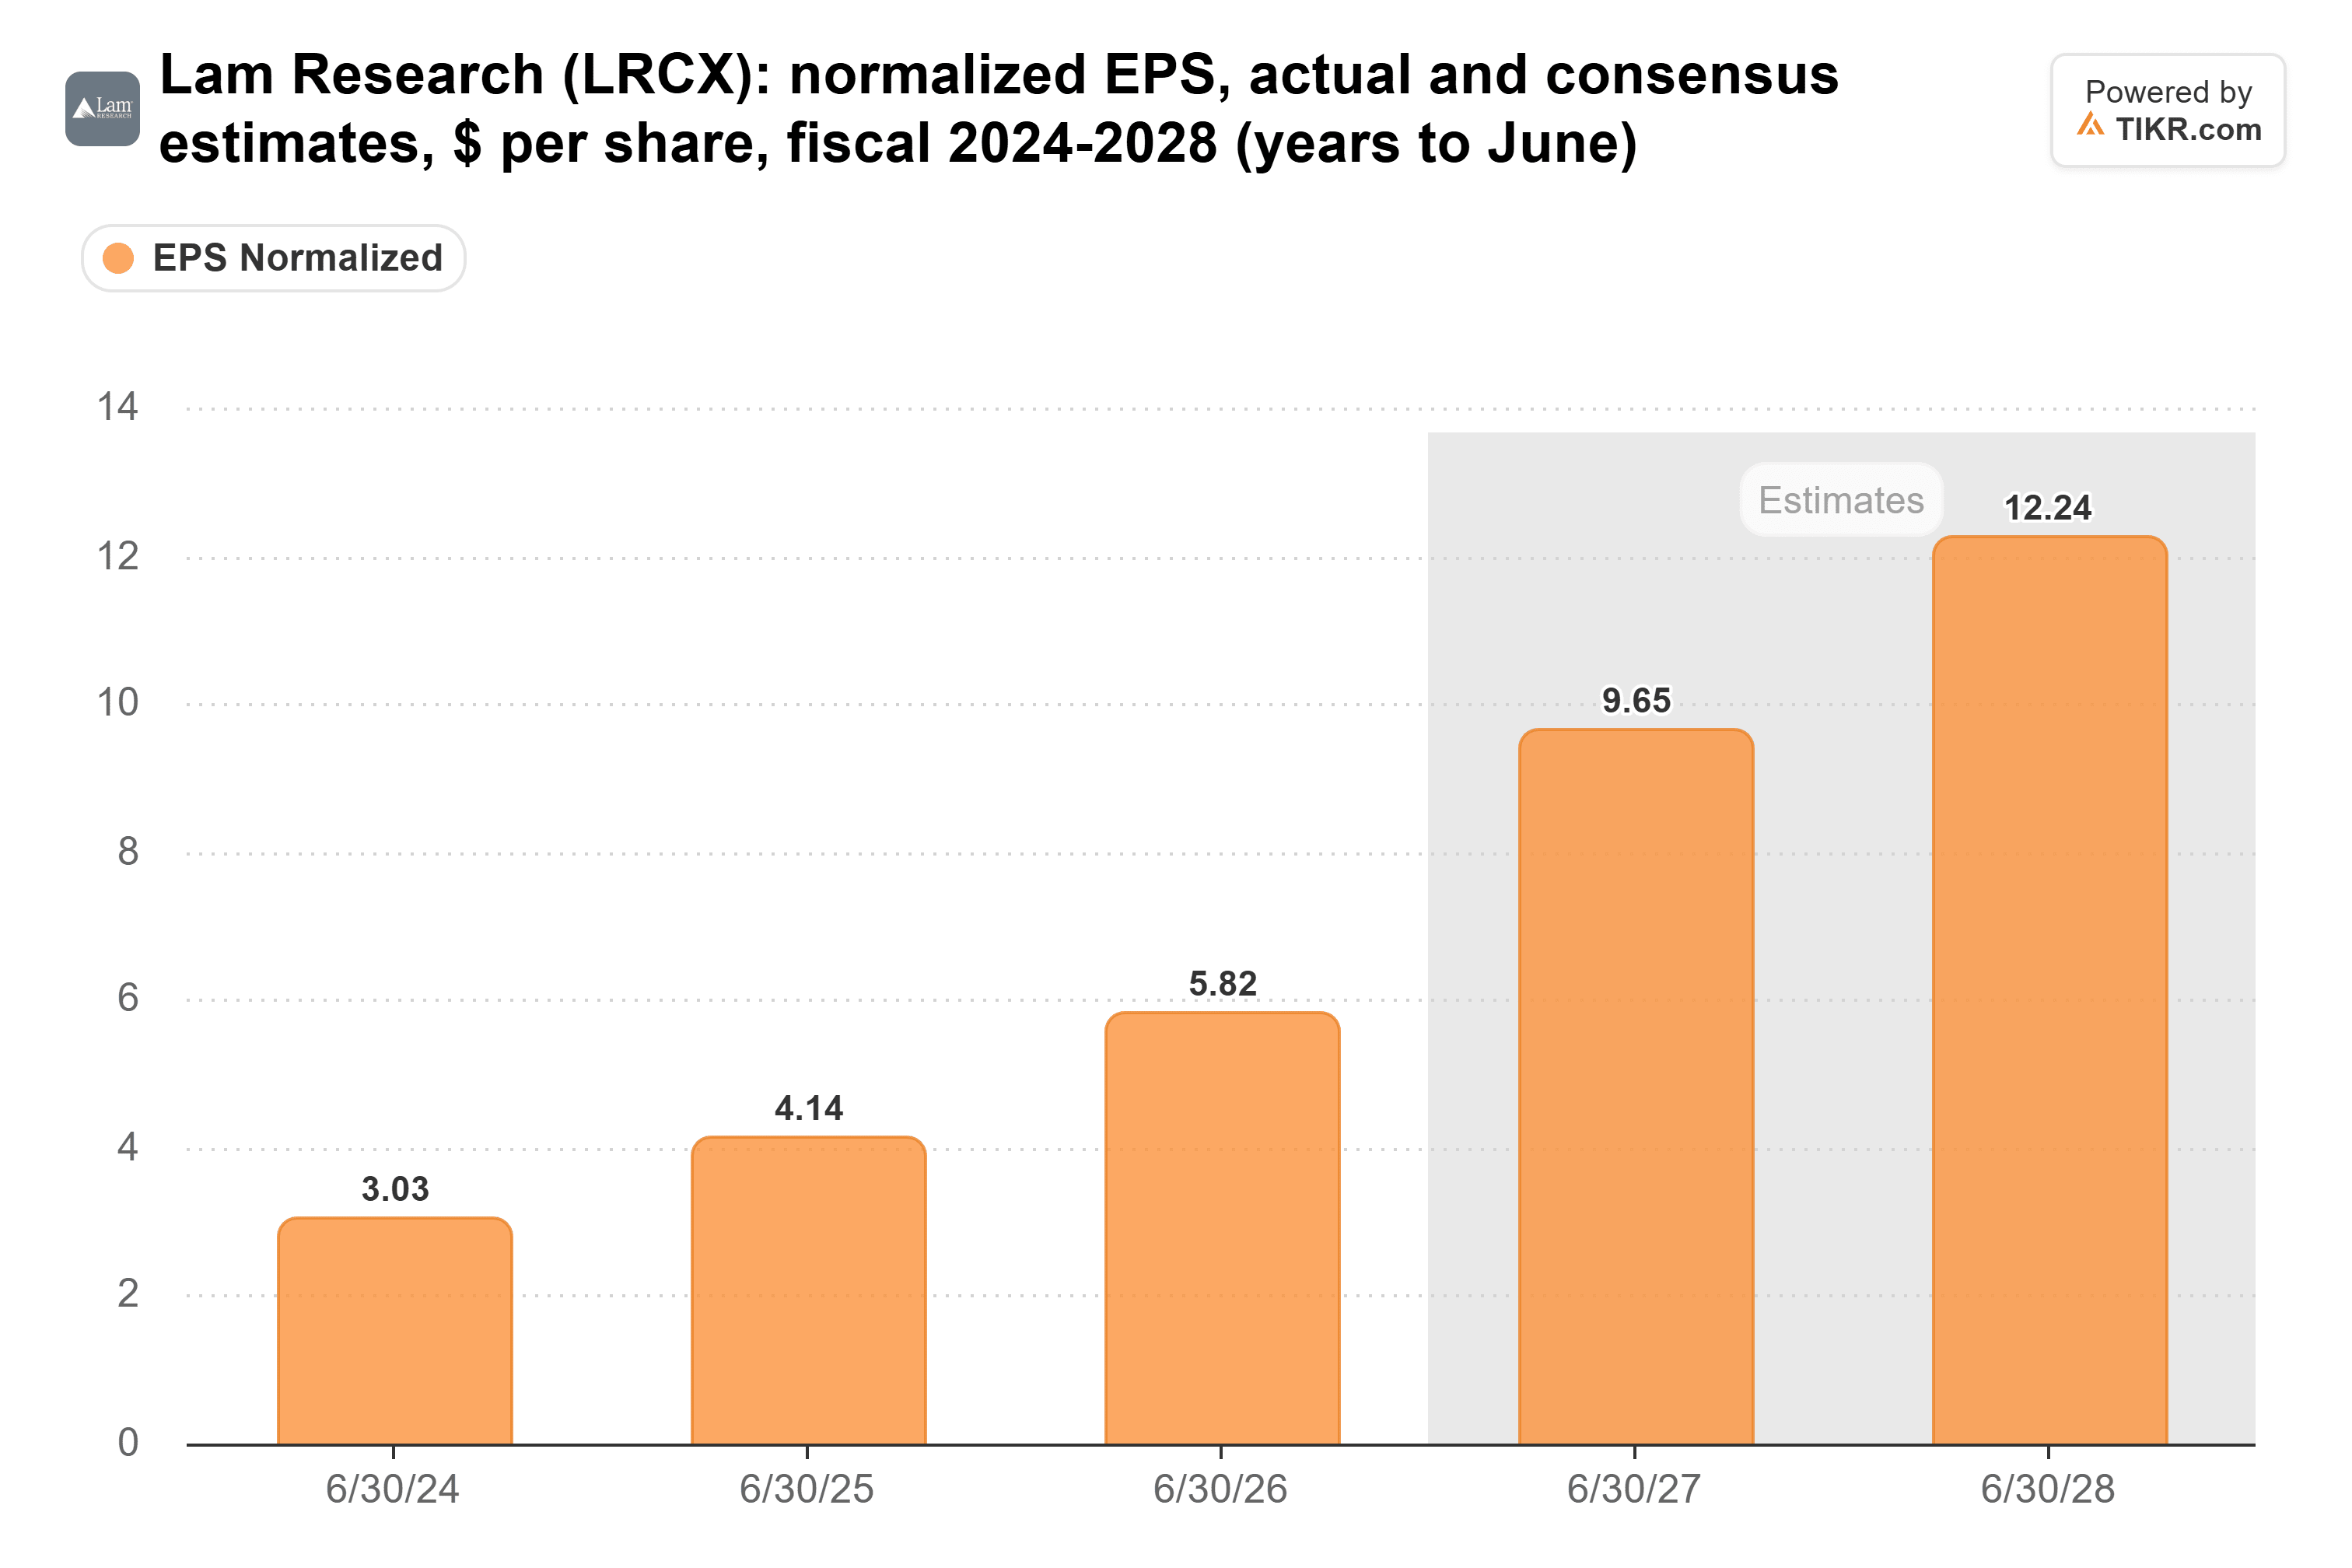
That fits management’s call for wafer fab equipment spending above $200 billion in 2027, up from the mid-$150 billion range this year.
And the selloff left Lam at 22x forward earnings at the last close, under its five-year average of 24x and far off its 57x peak in June:
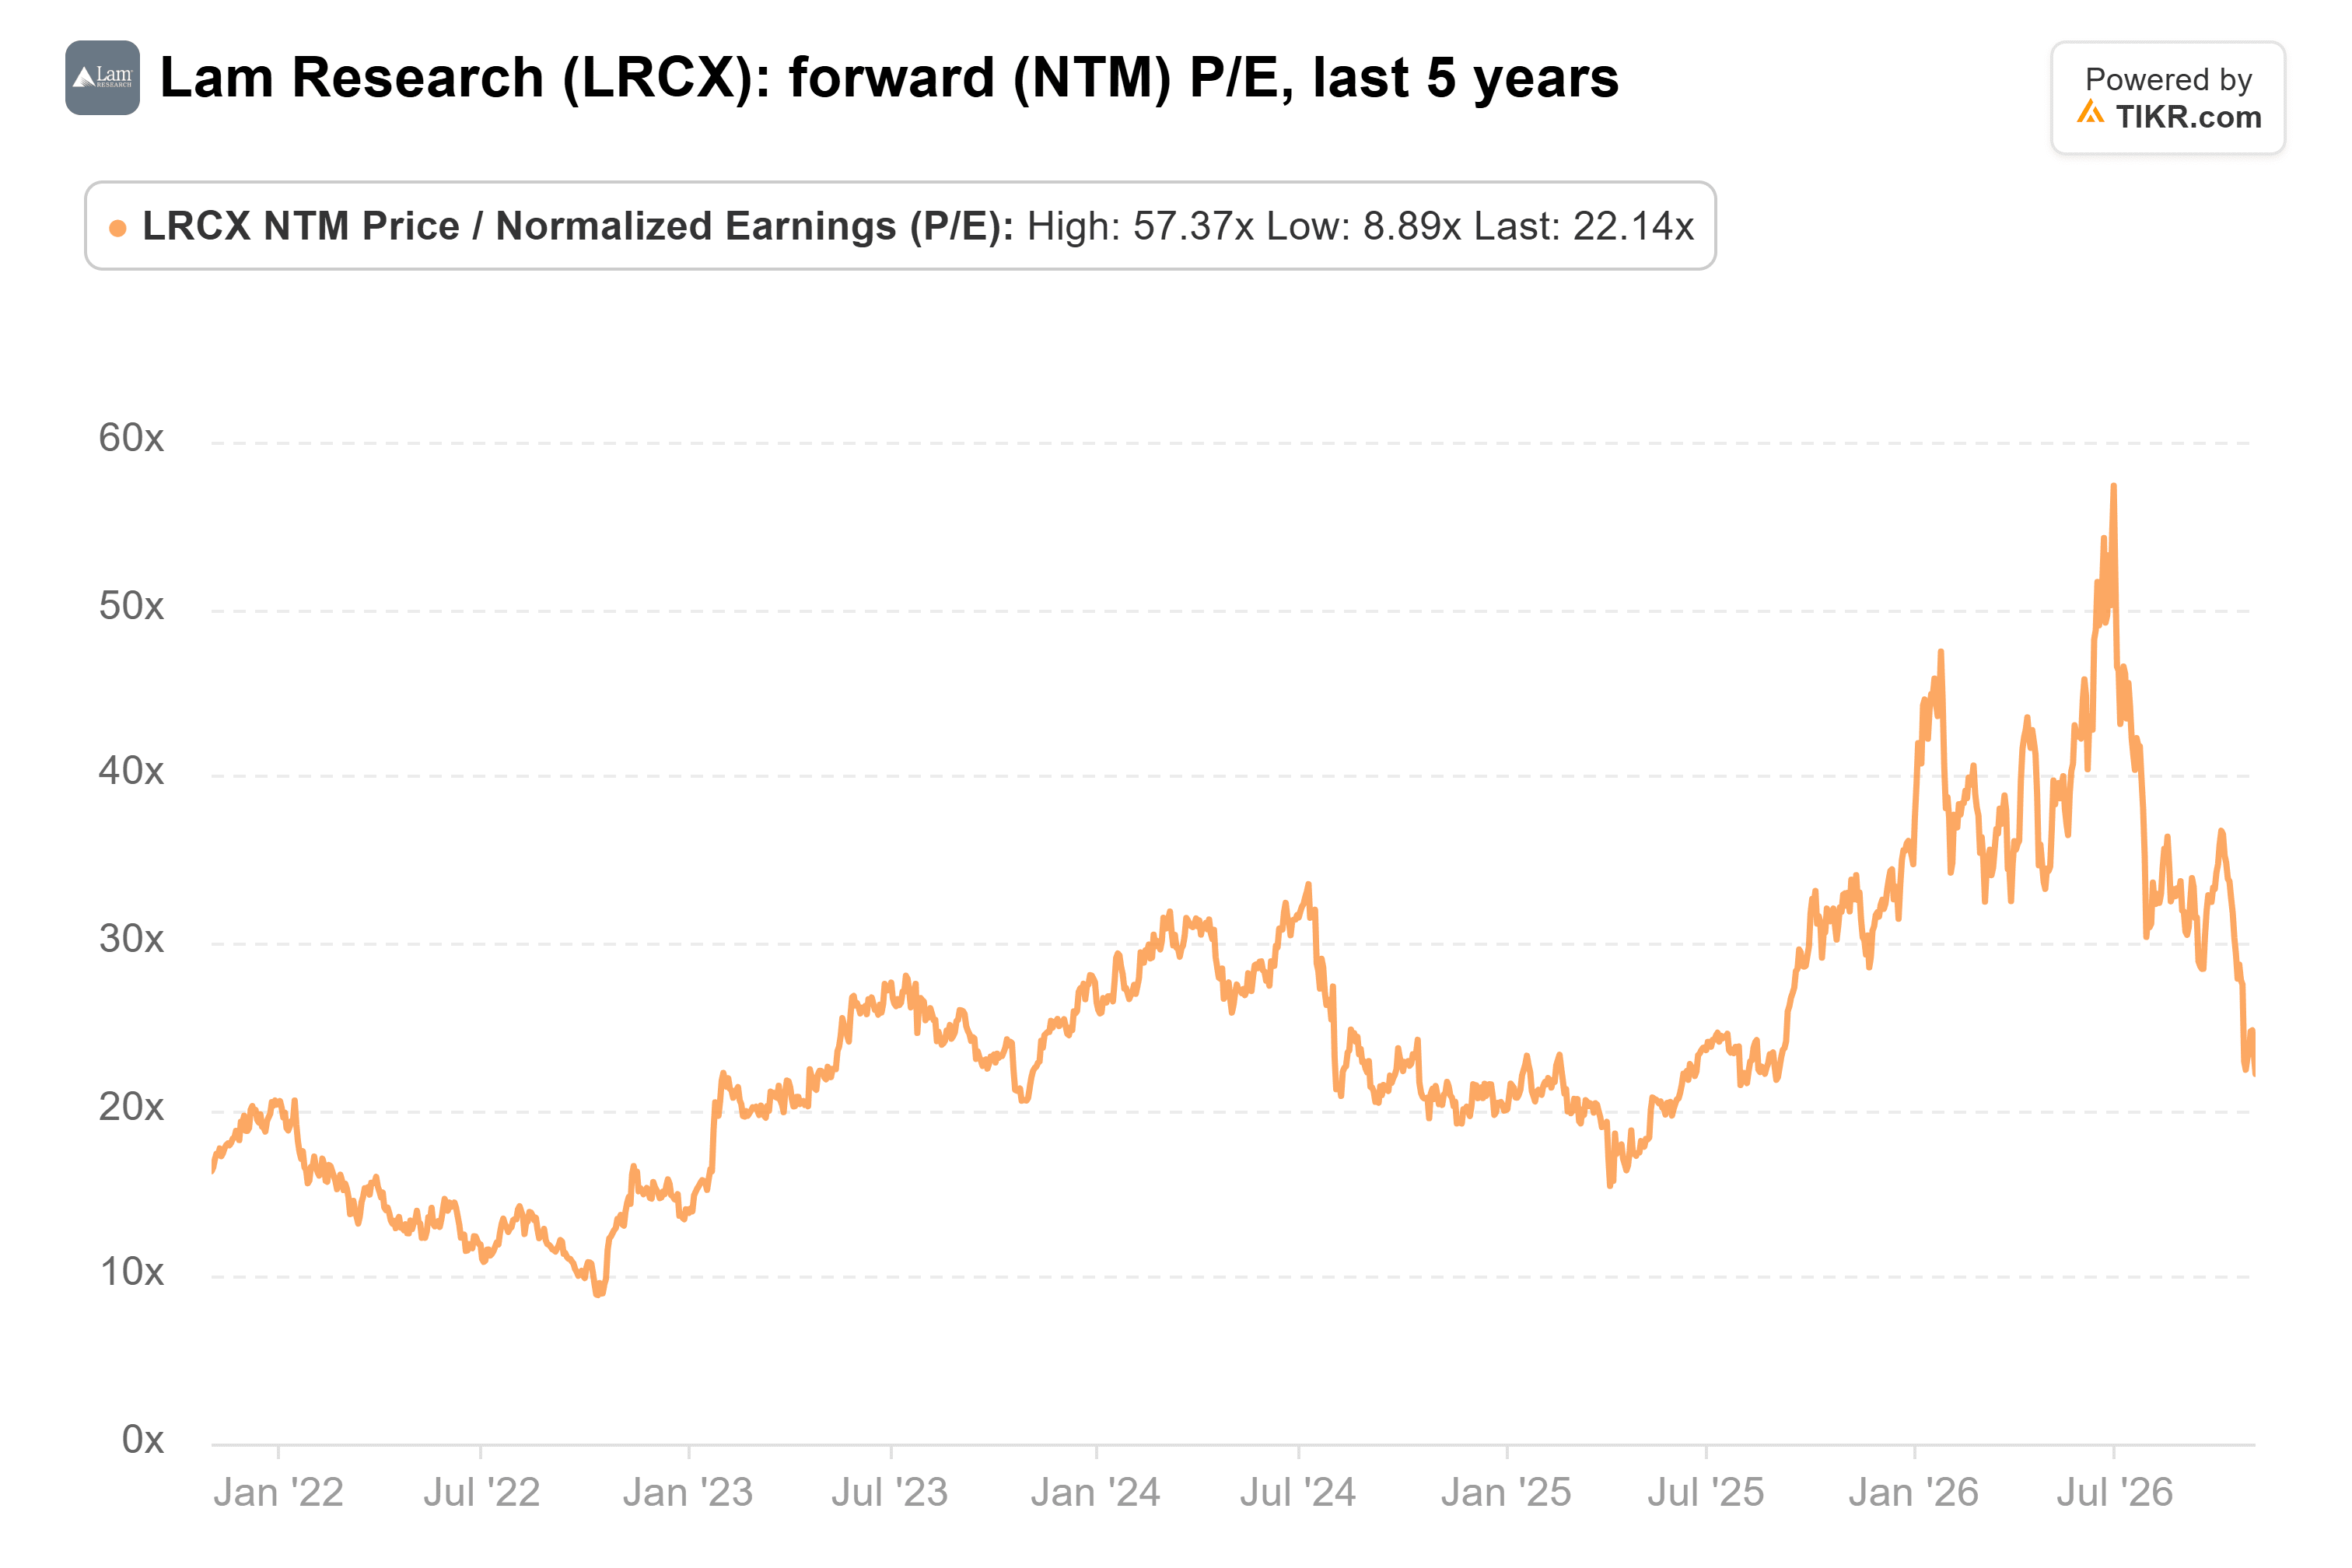
At today’s price, it’s about back at that average.
TIKR tracks 34 analysts on Lam Research. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Lam Research, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Lam Research’s Analyst Ratings
KLA and TSMC come next
KLA lives off the same spending. Its September-quarter revenue rose to $4.14 billion from $3.21 billion a year earlier, and it guided December-quarter revenue to $4.7 billion at the midpoint. Its next report will show whether it sees 2027 the way Lam does.
TSMC is one of the chipmakers that would have to spend that $200 billion. It raised its 2026 capital spending target to $60 billion-$64 billion in July. Its 2027 plan, due in mid-January, is the best early read on Lam’s number.
The bounce looks earned
I think Lam earned its extra few points. Estimates still point up, cash is coming in at a record pace, and the stock trades near its usual multiple.
Of course, if AI spending cools after the midterms, 2027 could fall short of $200 billion. Lam plans to update that forecast on its January call.
So what is Lam Research stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Lam Research could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!