Key Takeaways
- Veritas Asset Management, a firm that manages $19.1 billion, added to Intercontinental Exchange, Vulcan Materials and Stryker in the third quarter, its new 13F shows.
- All three stocks are up 16% or more since Sept. 30, so analysts’ average targets now sit just 6% to 10% above the latest close.
- Intercontinental Exchange’s earnings are growing fast. Stryker just cut its 2026 outlook, and Vulcan costs the most for its earnings.
- Intercontinental Exchange is the one the numbers back best, even near its 52-week high.
When a fund that owns only 22 US stocks adds to three of them at once, it’s worth asking what it sees.
Veritas Asset Management manages $19.1 billion in all, according to its latest Form ADV. Its 13F for the quarter ended Sept. 30, filed Nov. 5, shows 22 US stocks worth $5.37 billion. (A 13F leaves out stocks listed outside the US, so that’s only part of what the firm runs.) Its three biggest additions were Intercontinental Exchange (ICE), Vulcan Materials (VMC) and Stryker (SYK).
Intercontinental Exchange has earned its run
Veritas grew its Intercontinental Exchange stake 26% in the third quarter, to 2.49 million shares worth $379 million at Sept. 30. That’s 7.1% of its 13F stocks and its sixth-biggest position. The stock is up 19% since then and sits a hair below its 52-week high.
The business has kept up. ICE’s third-quarter release on Oct. 29 showed net revenue up 15% to $2.8 billion and adjusted EPS up 18% to $2.02, with energy trading revenue up 25%. It also bought back $1.6 billion of its stock in the first nine months of the year.
Analysts’ consensus target has barely moved over the past year, going from $192 to $194:
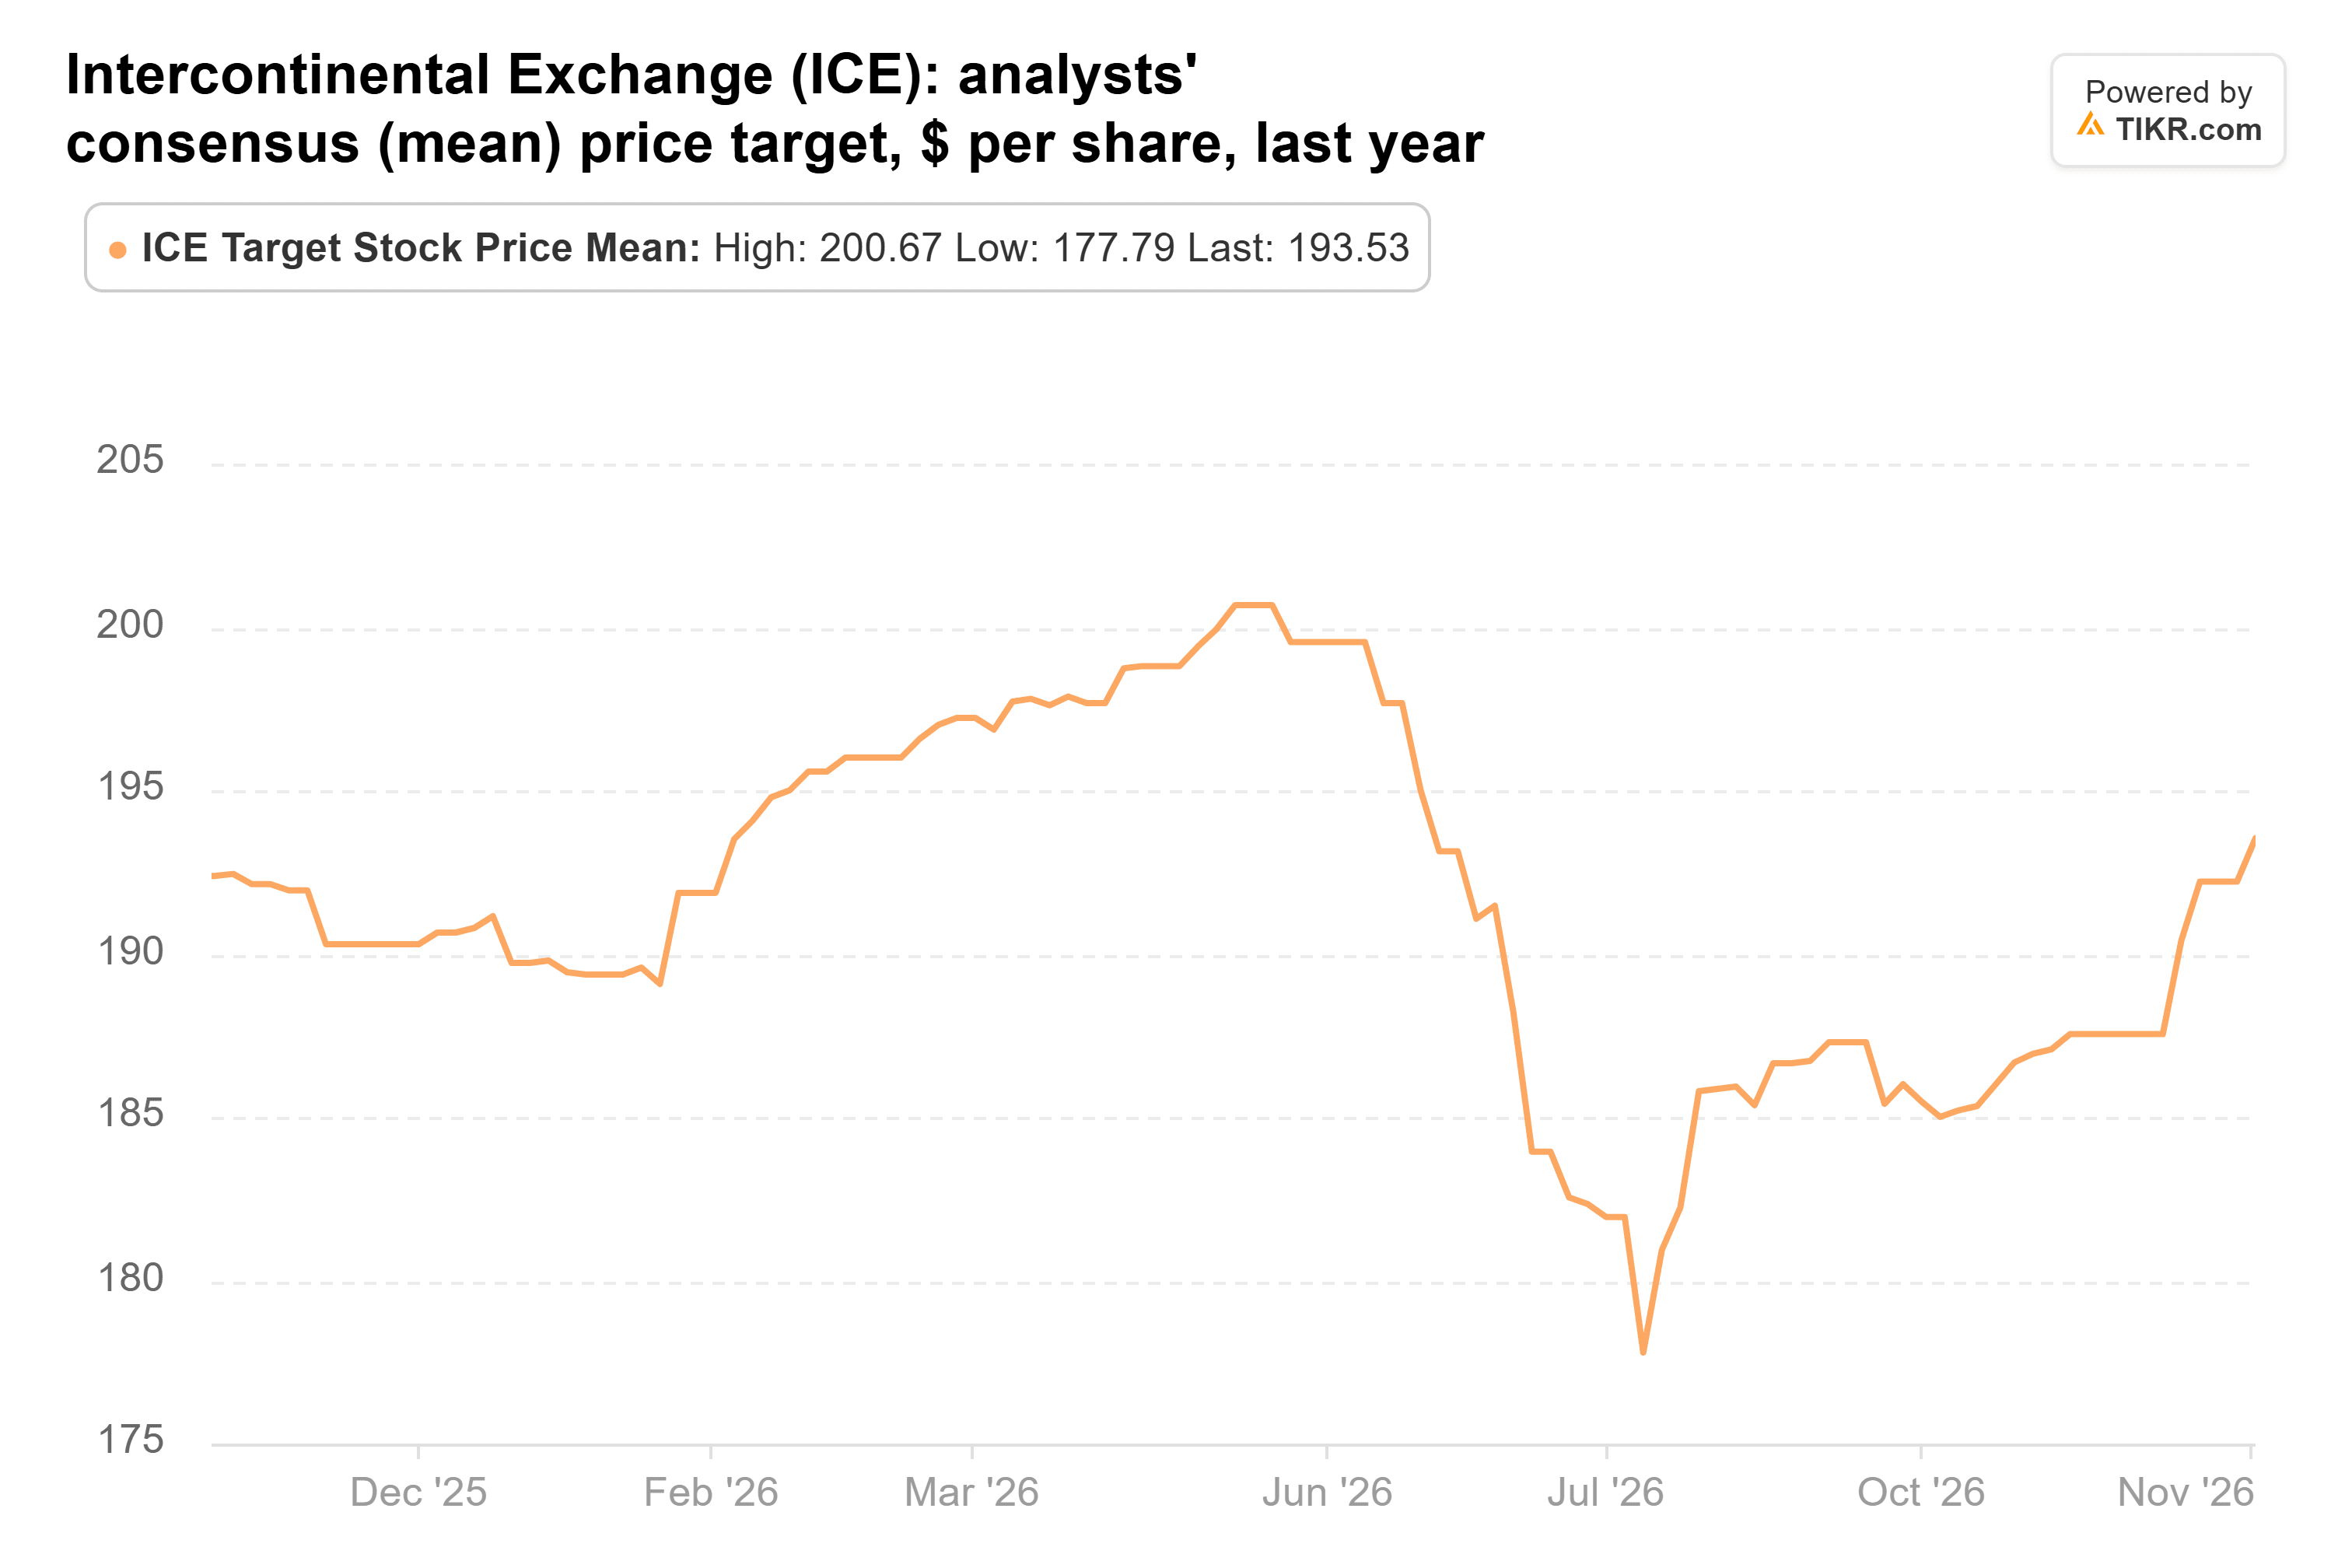
So the stock has caught up to the Street. The $194 average is just 7% above the latest close, and the stock trades at about 21x forward earnings.
TIKR tracks 16 analysts on Intercontinental Exchange. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Intercontinental Exchange, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Intercontinental Exchange’s Analyst Ratings
Vulcan Materials costs more for its upside
Veritas added even more to Vulcan, raising its stake 33% in the third quarter to 1.38 million shares worth $339 million. That’s 6.3% of its 13F stocks and its eighth-biggest holding. The stock is up 16% since Sept. 30, but it’s still 14% below its 52-week high.
Analysts’ consensus target has stayed between $307 and $329 all year. It sits at $313 now:

That’s 10% above the latest close, and analysts nudged it up from $307 at the end of October. Over the year, the lowest target among the 24 analysts who cover Vulcan rose from $198 to $240, so even the most cautious one has warmed up. But at about 30x forward earnings, investors are already paying a lot for Vulcan’s profits.
Stryker got cheaper for a reason
Stryker comes with a bad quarter behind it. Veritas added 33% to its stake in the third quarter, to 708,935 shares worth $195 million, or 3.6% of its 13F stocks.
On Oct. 29, Stryker reported 7.7% organic sales growth for the quarter, short of what Wall Street expected. It also cut its 2026 organic growth outlook to 6.5%-7.0%, from 8.3%-9.3%. CEO Kevin Lobo admitted in the release that the quarter “did fall short of our expectations.” Stryker blamed a slower market for hips and knees, but Johnson & Johnson grew those businesses faster in the same quarter. That makes more of the slowdown look like Stryker’s own problem.
Analysts have cut their consensus target hard over the past year, from $429 to $338:
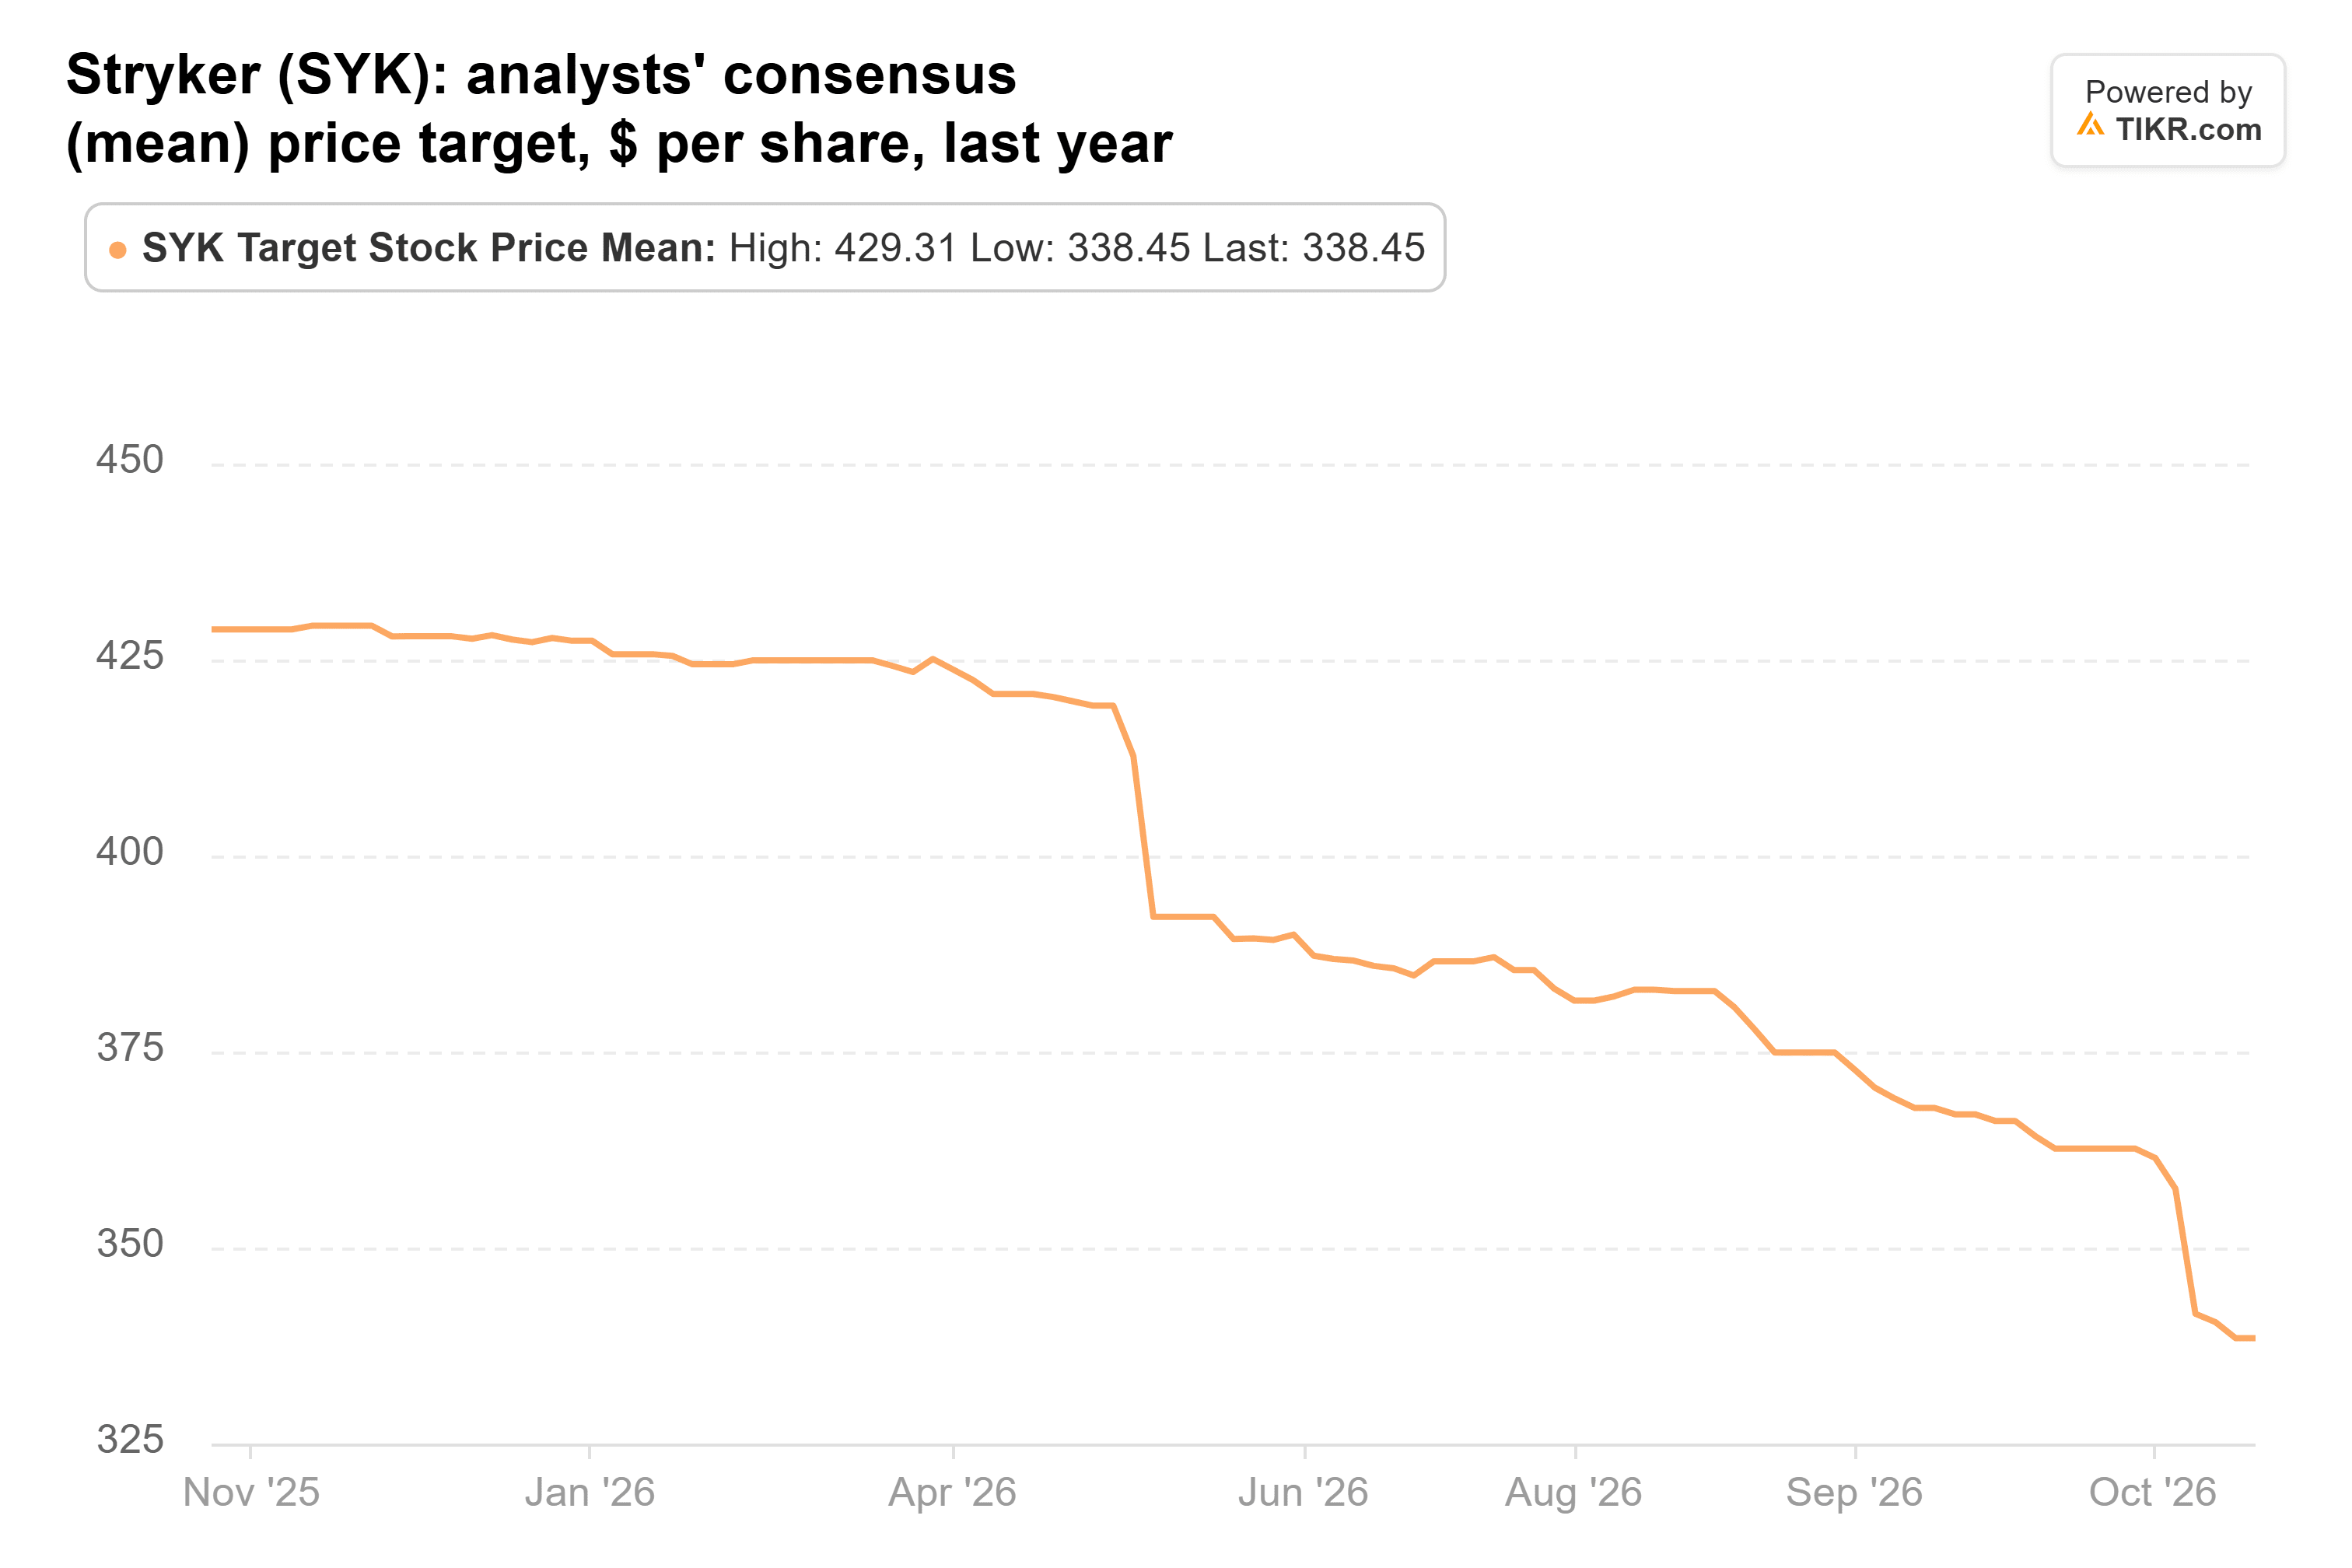
Even after that cut, the average target is 6% above the latest close. The stock is up 16% since Sept. 30 but still 18% below its 52-week high, at about 20x forward earnings.
Intercontinental Exchange is the one I’d follow
So far, Veritas’s adds look good on paper. That’s the price change since Sept. 30, though, and we don’t know what it paid.
If I could only buy one right now, it’d be Intercontinental Exchange. Its adjusted EPS just grew 18%, against Stryker’s 10%, and 21x is barely more than Stryker’s 20x for a business that just posted a record third quarter. The risk is that the stock has already run, so a slower stretch for trading could leave it flat for a while.
Vulcan has the widest gap to its target, but at 30x it has little room for a miss. Stryker’s 20x looks cheap next to the others. But its 2026 outlook came in below what analysts expected, and the Street has kept marking its target down.
Veritas’s next 13F, due in mid-February, will show whether it kept adding after the run. Before then, all three report fourth-quarter results early next year, and Stryker’s will show us whether its hips-and-knees slowdown lasted more than one quarter.
So what is Intercontinental Exchange stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Intercontinental Exchange could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Intercontinental Exchange for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!