Key Takeaways
- NVIDIA stock is 29% below its October high after a scandal around CEO Jensen Huang. Morgan Stanley dropped it as a Top Pick but kept its $300 target, 72% above today’s price.
- Morgan Stanley’s case is that the AI build-out will last, and that NVIDIA will gain share as data center land and power run short.
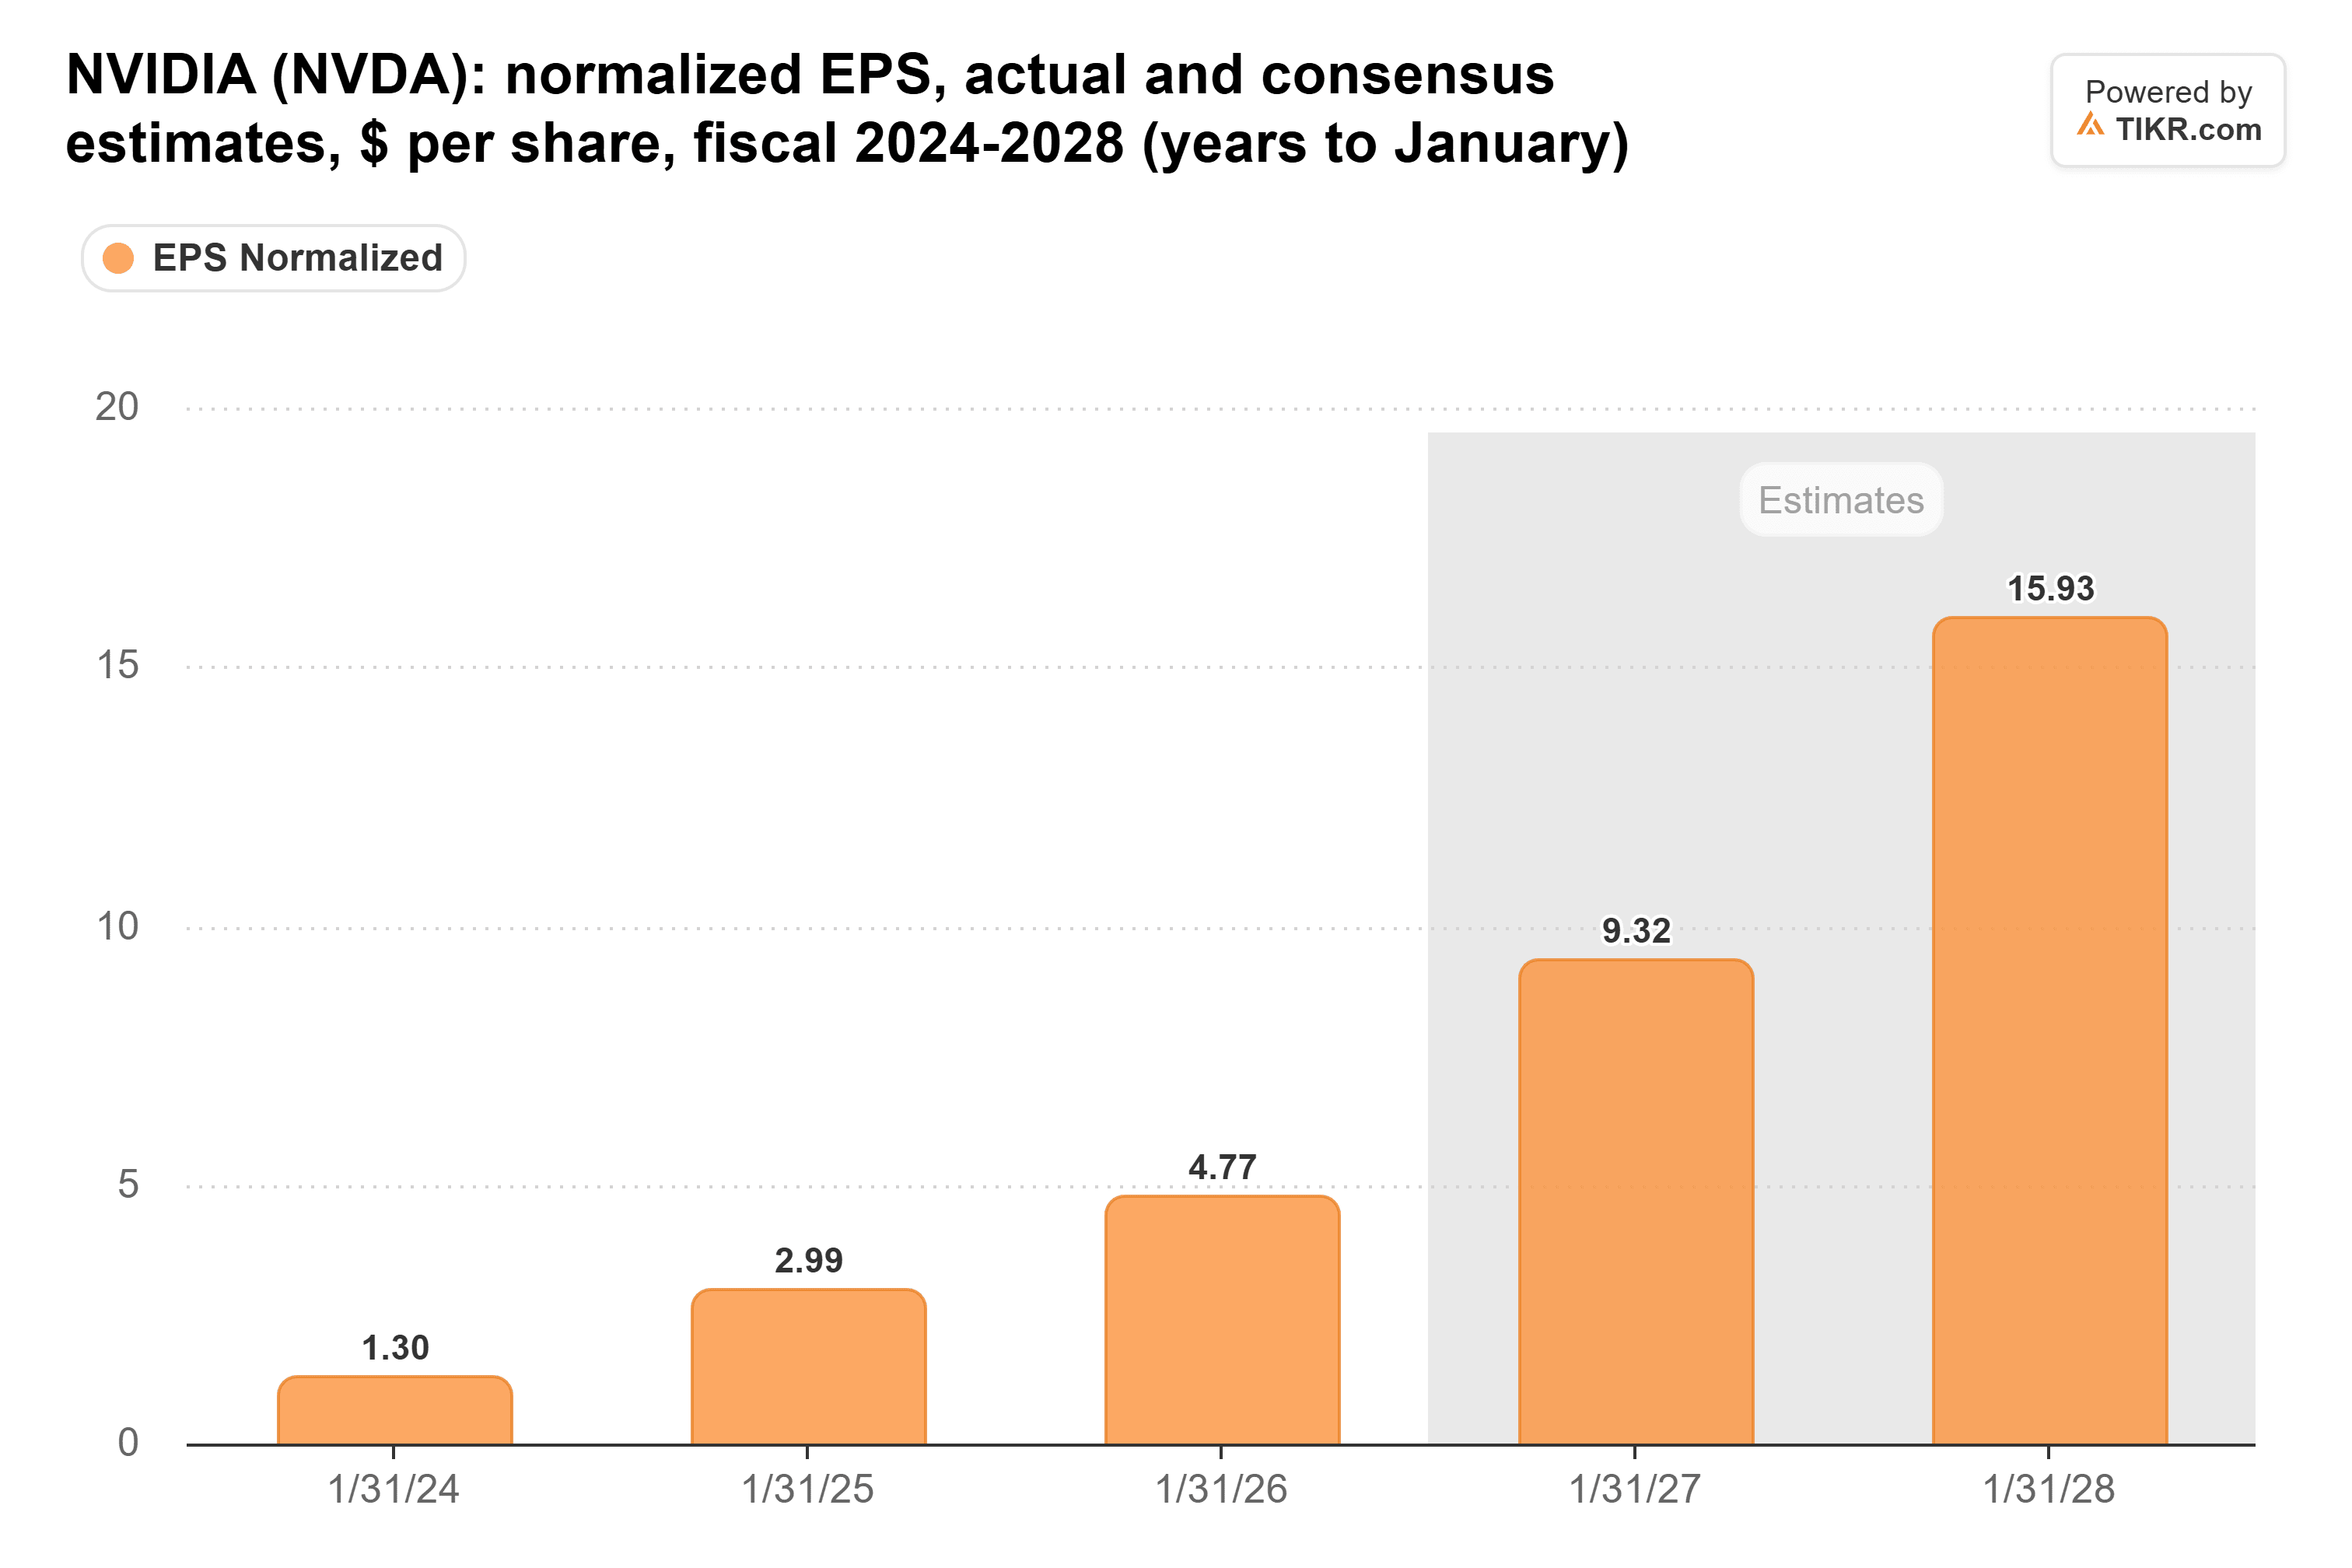
- At $300, NVIDIA would trade at about 25x forward earnings, close to its one-year average and well below its five-year average of 36x. Fiscal 2028 earnings estimates rose from $12.84 to $15.93 over three months.
- The target looks reasonable on the numbers, as long as Huang’s future and Washington’s response don’t push those estimates down.
NVIDIA (NVDA) stock sits 29% below its Oct. 6 closing high after a scandal around CEO Jensen Huang. Today, Morgan Stanley’s Joseph Moore dropped it as a Top Pick under the bank’s stop-loss rule, but kept his Overweight rating and $300 target, 72% above today’s price.
A CEO scandal with a China problem attached
Huang admitted this week to an affair with Alice Huang, a Megaspeed executive whom U.S. officials reportedly suspect is a Chinese intelligence source. On Nov. 10, The Information reported that a network tied to her moved at least $7.5 billion of NVIDIA chips to Chinese firms since 2023, and NVIDIA’s board hired a law firm to investigate Huang. Lawmakers are now pushing for tighter chip export rules, The Wall Street Journal reported. My read: new rules would hit the AI clouds NVIDIA sells to, part of a group that brought in 45.3% of data center revenue in the July quarter.
TIKR tracks 62 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Morgan Stanley is betting on power
Moore named NVIDIA his Top Pick on Oct. 2 with the same $300 target. His case rests on “a strong and durable AI buildout, with potential for share gains if and when land power shell emerges as a constraint,” he wrote.
Buyers have “got to go secure the land, power and shell,” Huang said on NVIDIA’s second-quarter call, and NVIDIA did just that in Ohio, where its SB Energy partnership will host about 4.25 gigawatts for OpenAI. When power is the limit, buyers want the most work per megawatt, and NVIDIA says Vera Rubin delivers 30x the throughput per megawatt of Grace Blackwell Ultra.
Does $300 add up?
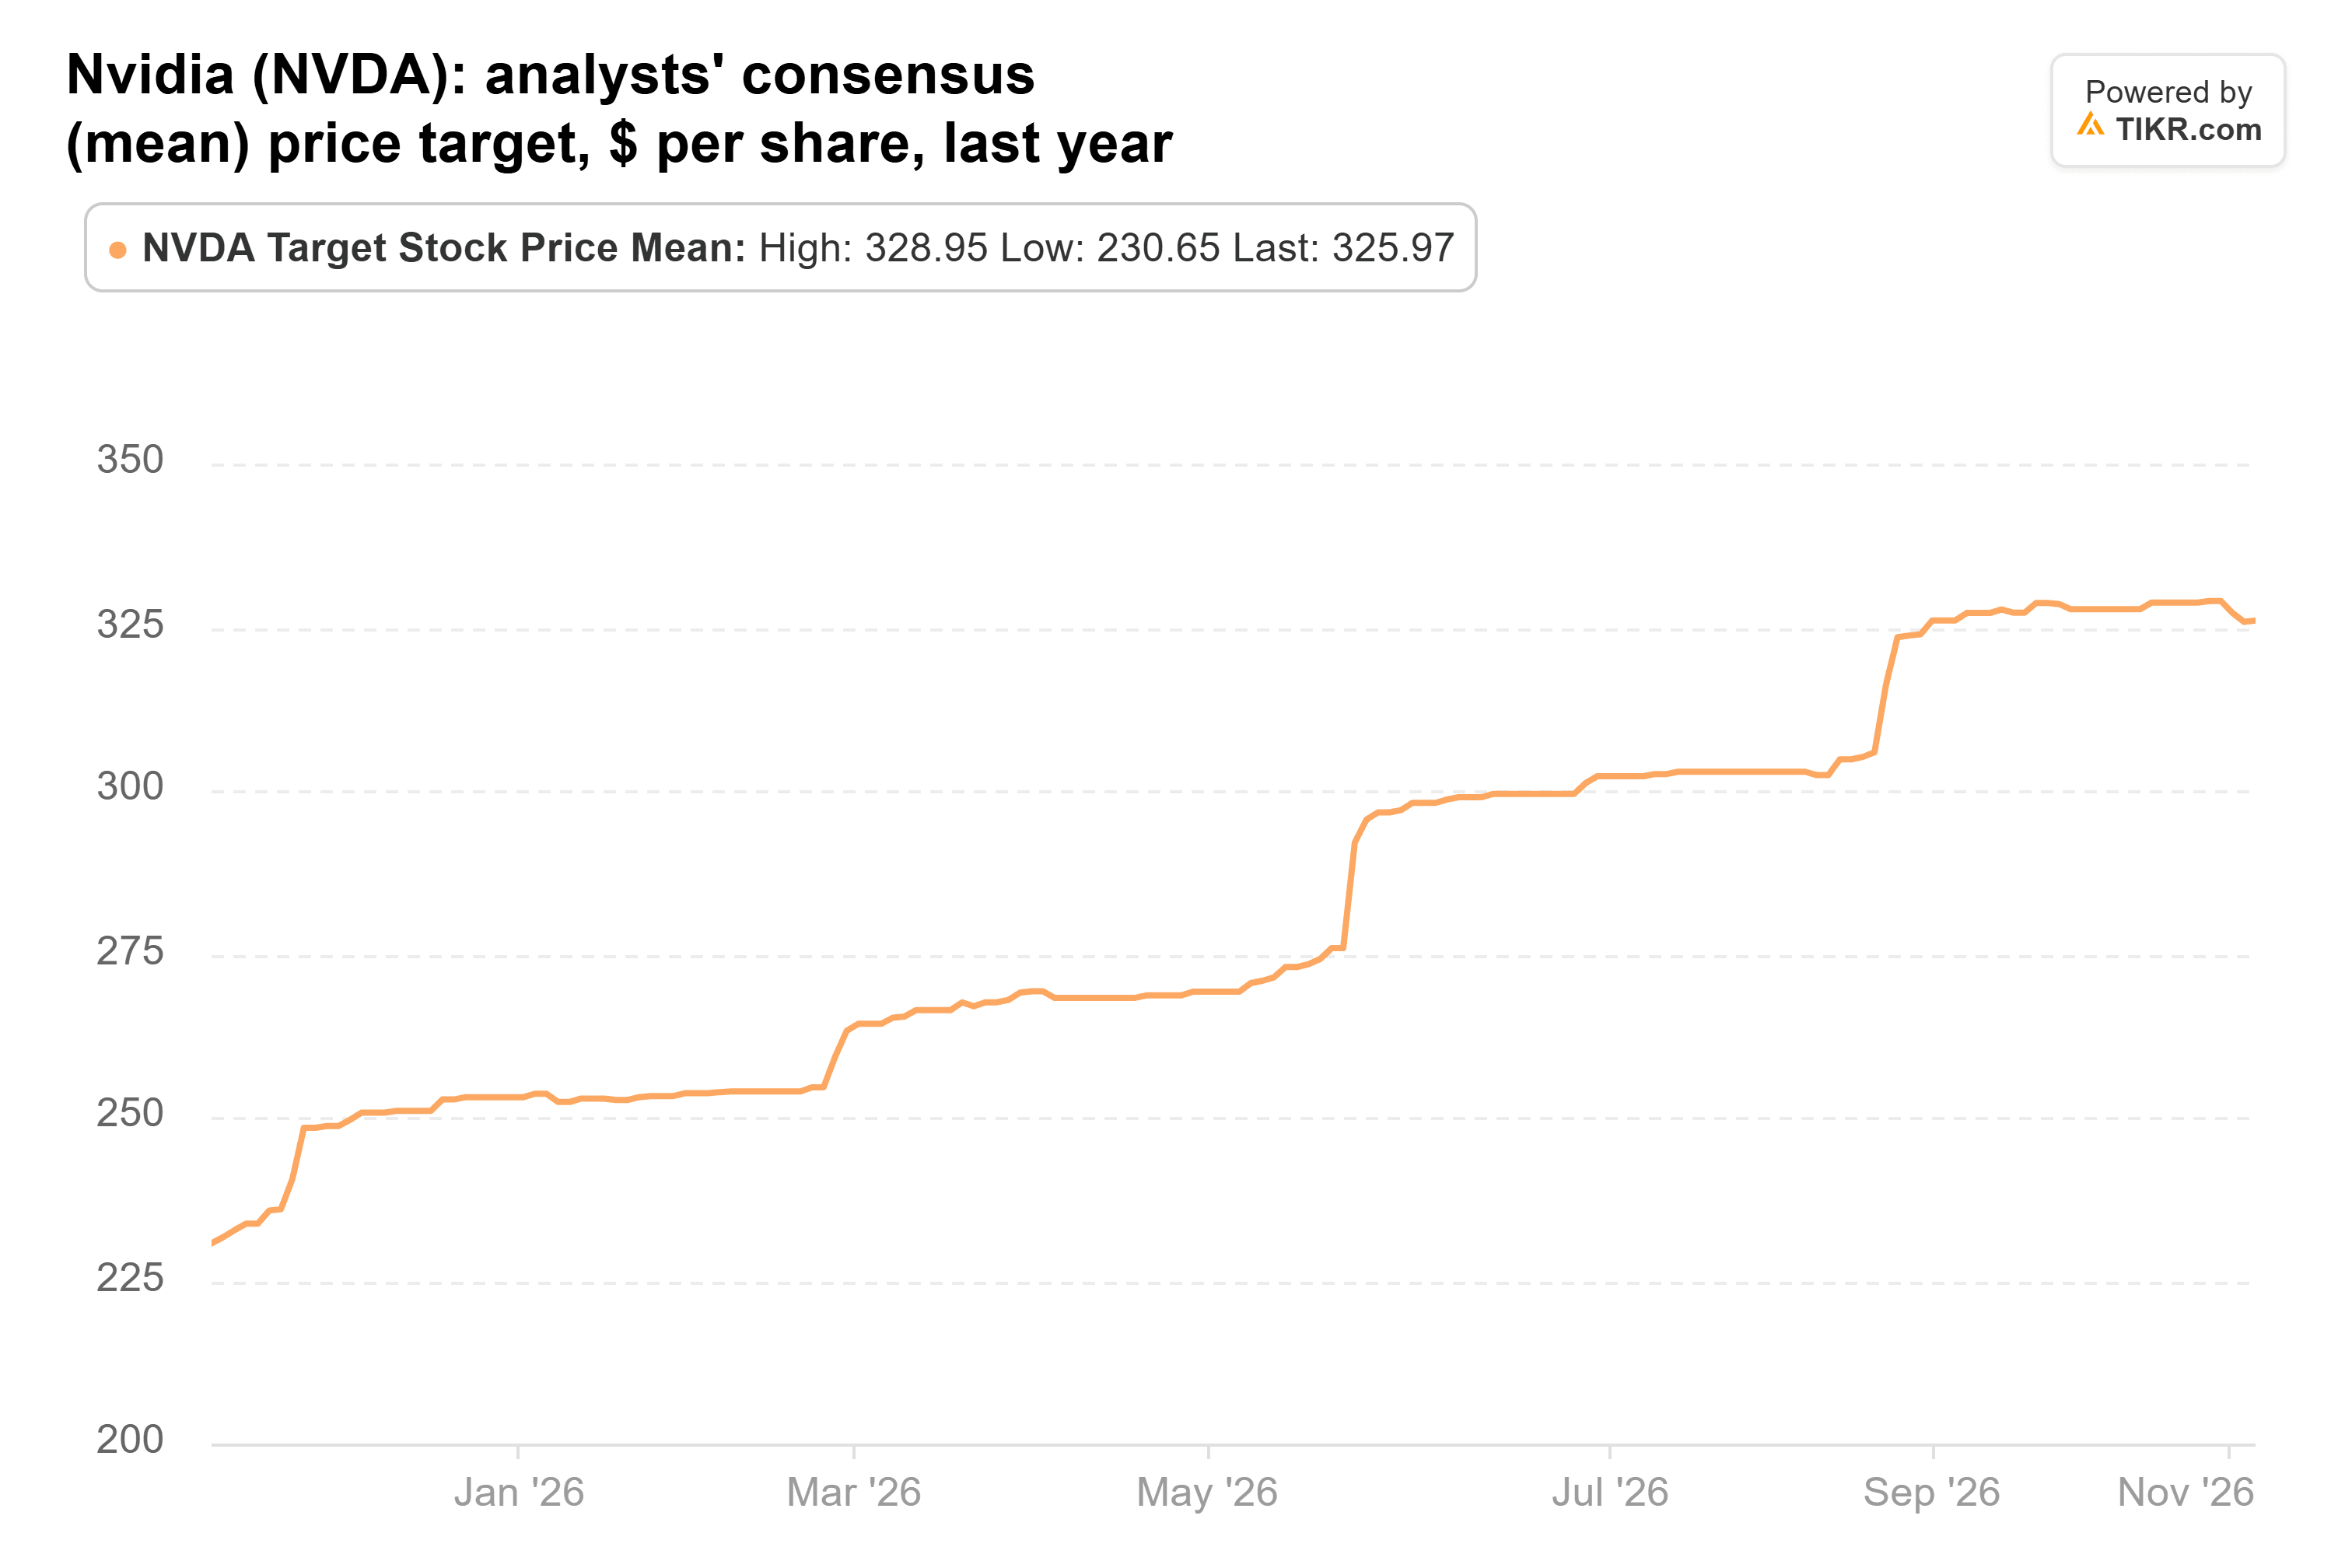
Sixty-one analysts cover NVIDIA, and their average target climbed from $231 a year ago to $326 on Nov. 10. Moore’s $300 sits 8% below it:
The estimates behind those targets kept rising after August’s report. Consensus for fiscal 2028 (the year to January 2028) is $15.93 a share, up from $12.84 three months ago:
With no China data center revenue in NVIDIA’s outlook, analysts have no obvious sales number to cut over this week’s news.
The forward P/E fell to 14x at the Nov. 10 close, its lowest in five years and far below its 36x five-year average:
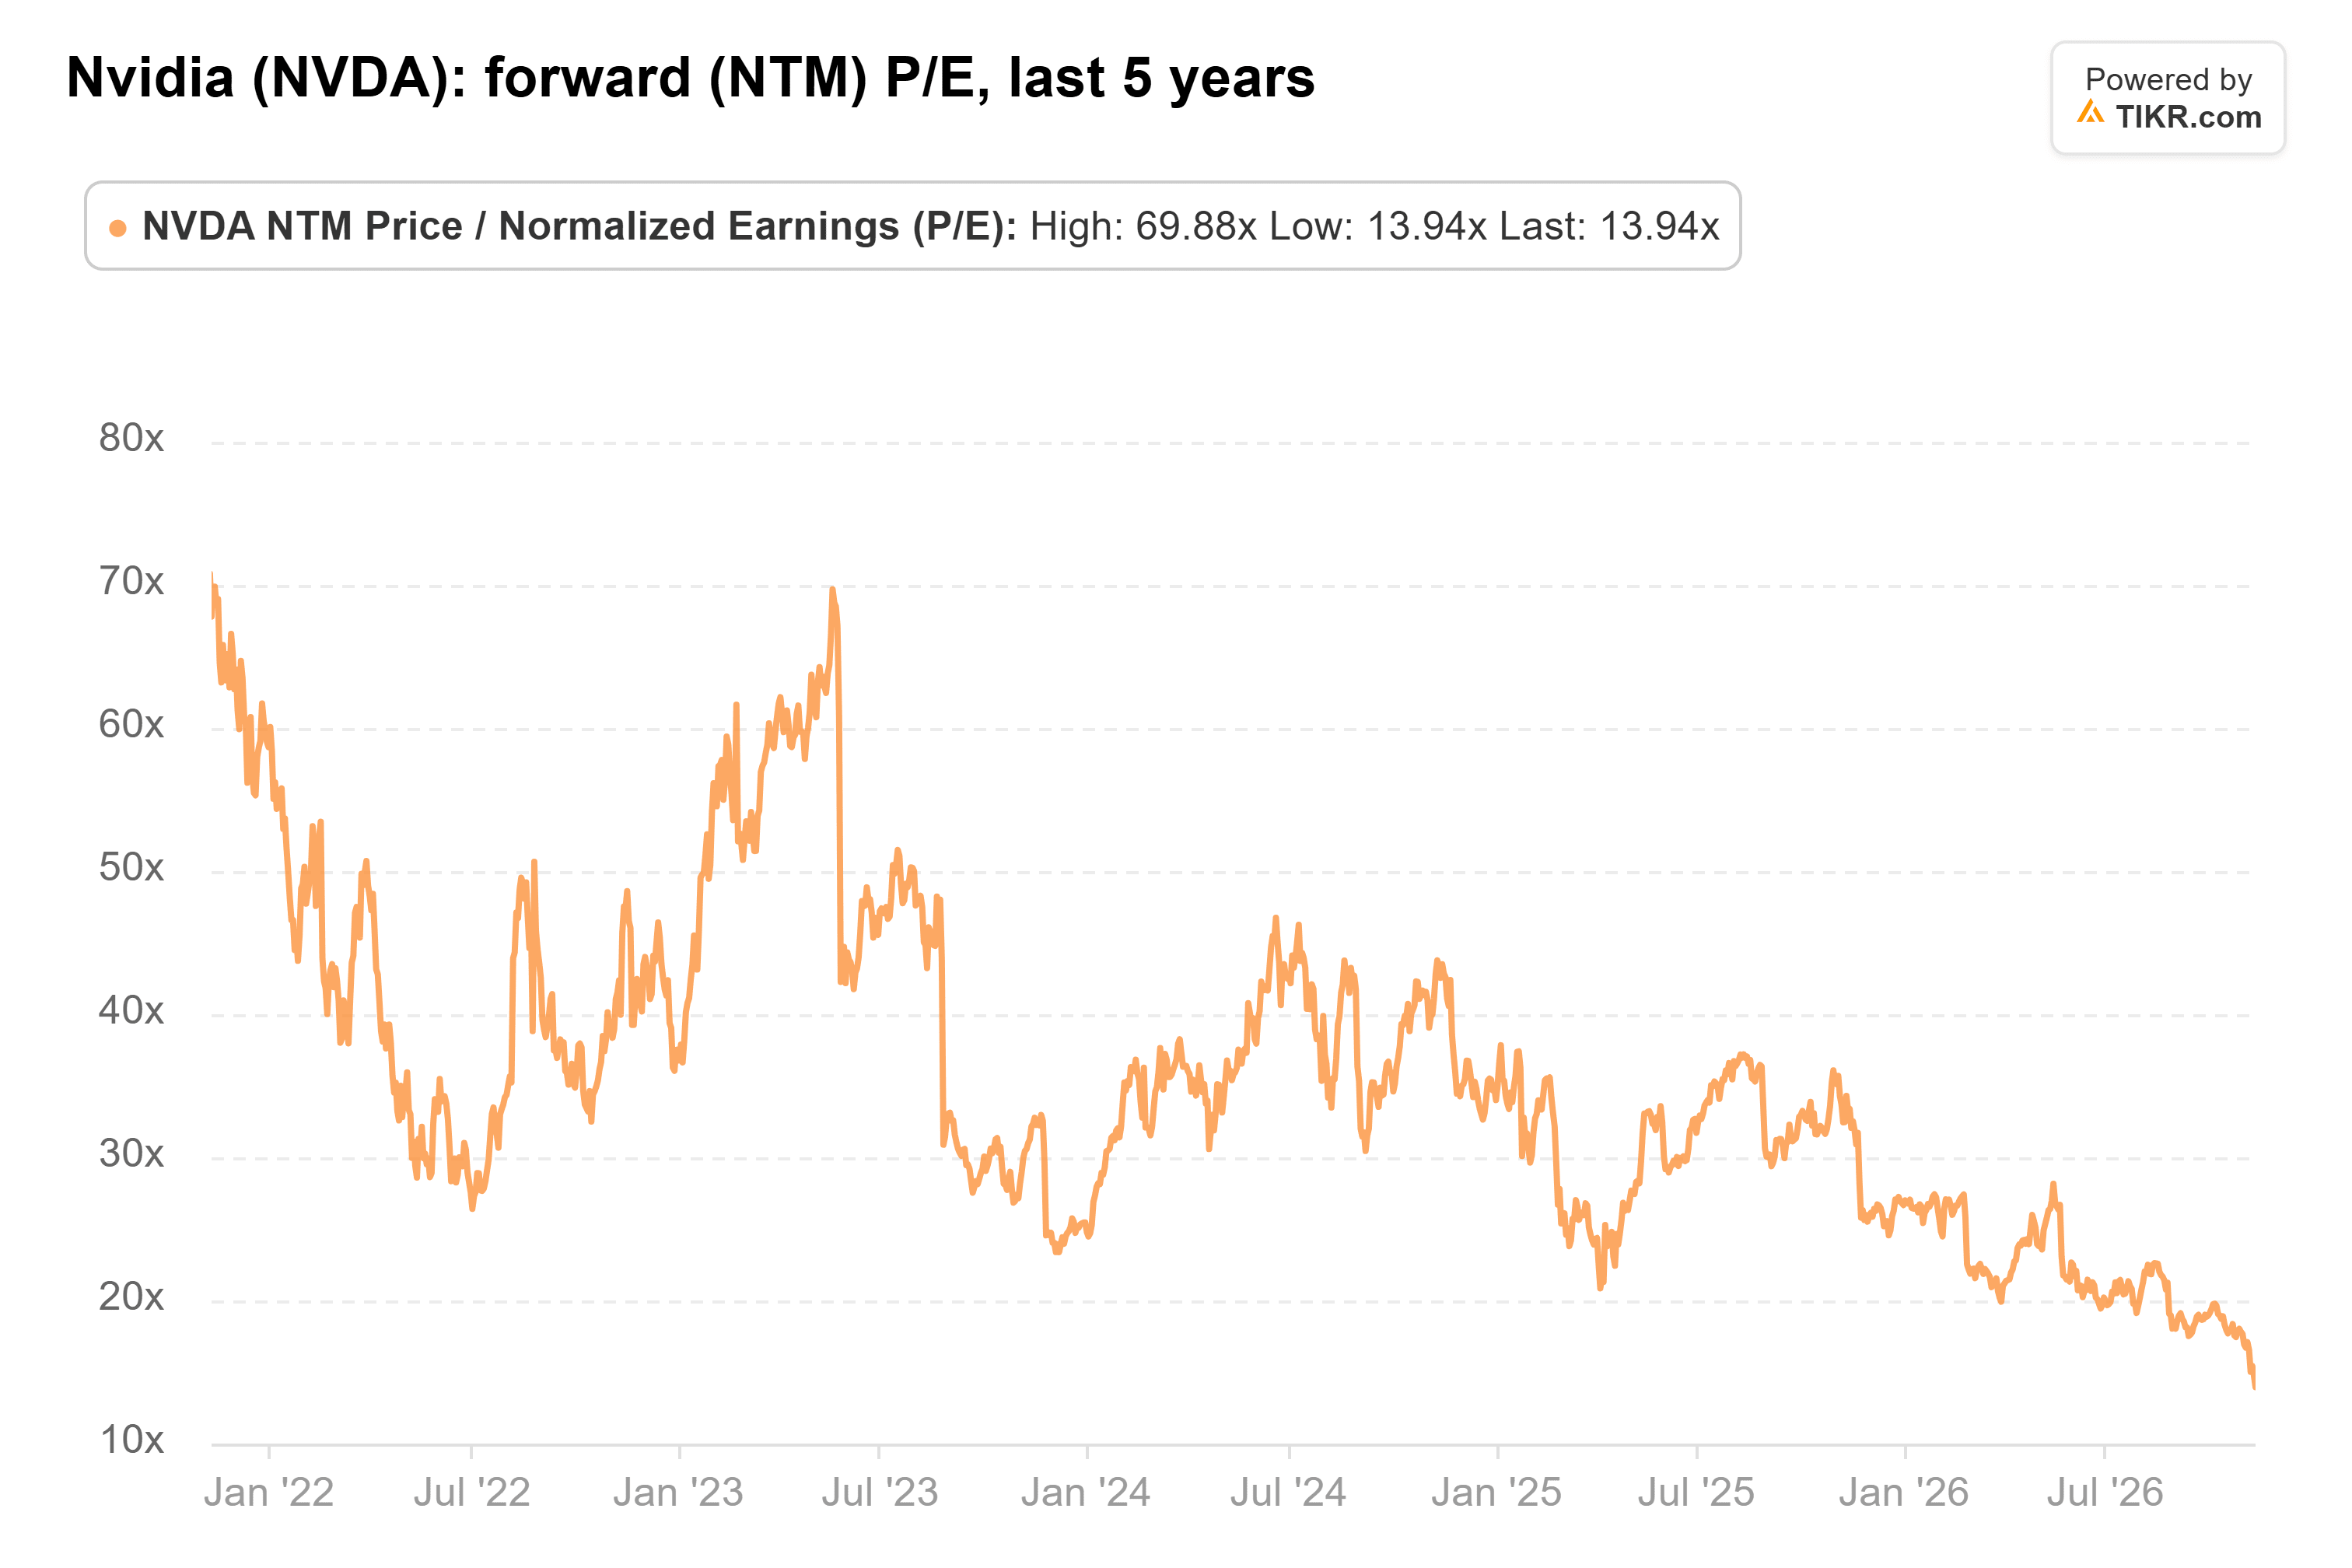
Divide $300 by the $12.12 a share analysts expect over the next twelve months, and you get about 25x, close to its 24x average over the past year.
Huang and Washington are the risks
Baird cut the stock to Neutral today with a $200 target, citing supply limits, a murkier 2027 and the questions around Huang. Even Moore wrote that Huang’s leadership “is crucial to the company’s strategic direction in our view.”
Still, I think Moore’s $300 is reasonable: NVIDIA can get there without its old premium, as long as estimates hold. NVIDIA reports third-quarter results on Nov. 17, and the board hasn’t said when its review will end. If that review costs NVIDIA its CEO, or Washington goes after the overseas clouds, I’d want a lower target too.
So what is NVIDIA stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!