Key Takeaways
- ACR Alpine Capital Research manages about $11 billion. It added 25% to its Elevance Health (ELV) stake in Q3, which brought the stake to 4.9% of its 13F holdings.
- Elevance has raised its 2026 earnings guidance every quarter this year, most recently to adjusted EPS of at least $29.
- Analysts expect EPS to rise to $34.57 by 2028, and the stock trades at 15x forward earnings, close to its five-year average.
- The numbers support ACR’s bet at the current price, and Elevance’s next report, early next year, will test its 2027 growth goal.
An $11 billion fund just made Elevance Health one of the 10 biggest positions in its latest 13F. The health insurer has given it good reason to: Elevance has raised its earnings forecast every quarter of 2026.
ACR added 25% in Q3
ACR Alpine Capital Research’s 13F for the quarter ended Sept. 30, filed Nov. 2, shows 919,031 Elevance shares worth $357 million at quarter-end. That’s 25% more shares than it held three months earlier. The stake is 4.9% of the $7.35 billion of US stocks in its 13F, its ninth-largest of 40 positions.
The firm manages $10.79 billion in all, according to its latest Form ADV.
A 13F only shows what a fund held on the last day of the quarter, so it doesn’t say when ACR bought the extra shares or what it paid.
Elevance stock is up 8% from its Sept. 30 close to Friday’s, though that’s the stock’s gain, and ACR’s own return depends on what it paid.
TIKR tracks 22 analysts on Elevance Health. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Elevance Health, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Elevance Health’s Analyst Ratings
Elevance keeps beating its own forecasts
Elevance raised its 2026 guidance to adjusted EPS of at least $26.75 with its Q1 results, then to at least $27.00 with the Q2. In late October, its Q3 release raised it again to at least $29.00.
That quarter’s adjusted EPS came in at $6.99, though $1.85 a share of it was a net non-operating benefit. Operating revenue rose 0.7% from Q3 2025 to $50.4 billion.
Analysts expect 2026 to be the low point for earnings, with EPS back above 2023’s level by 2028:
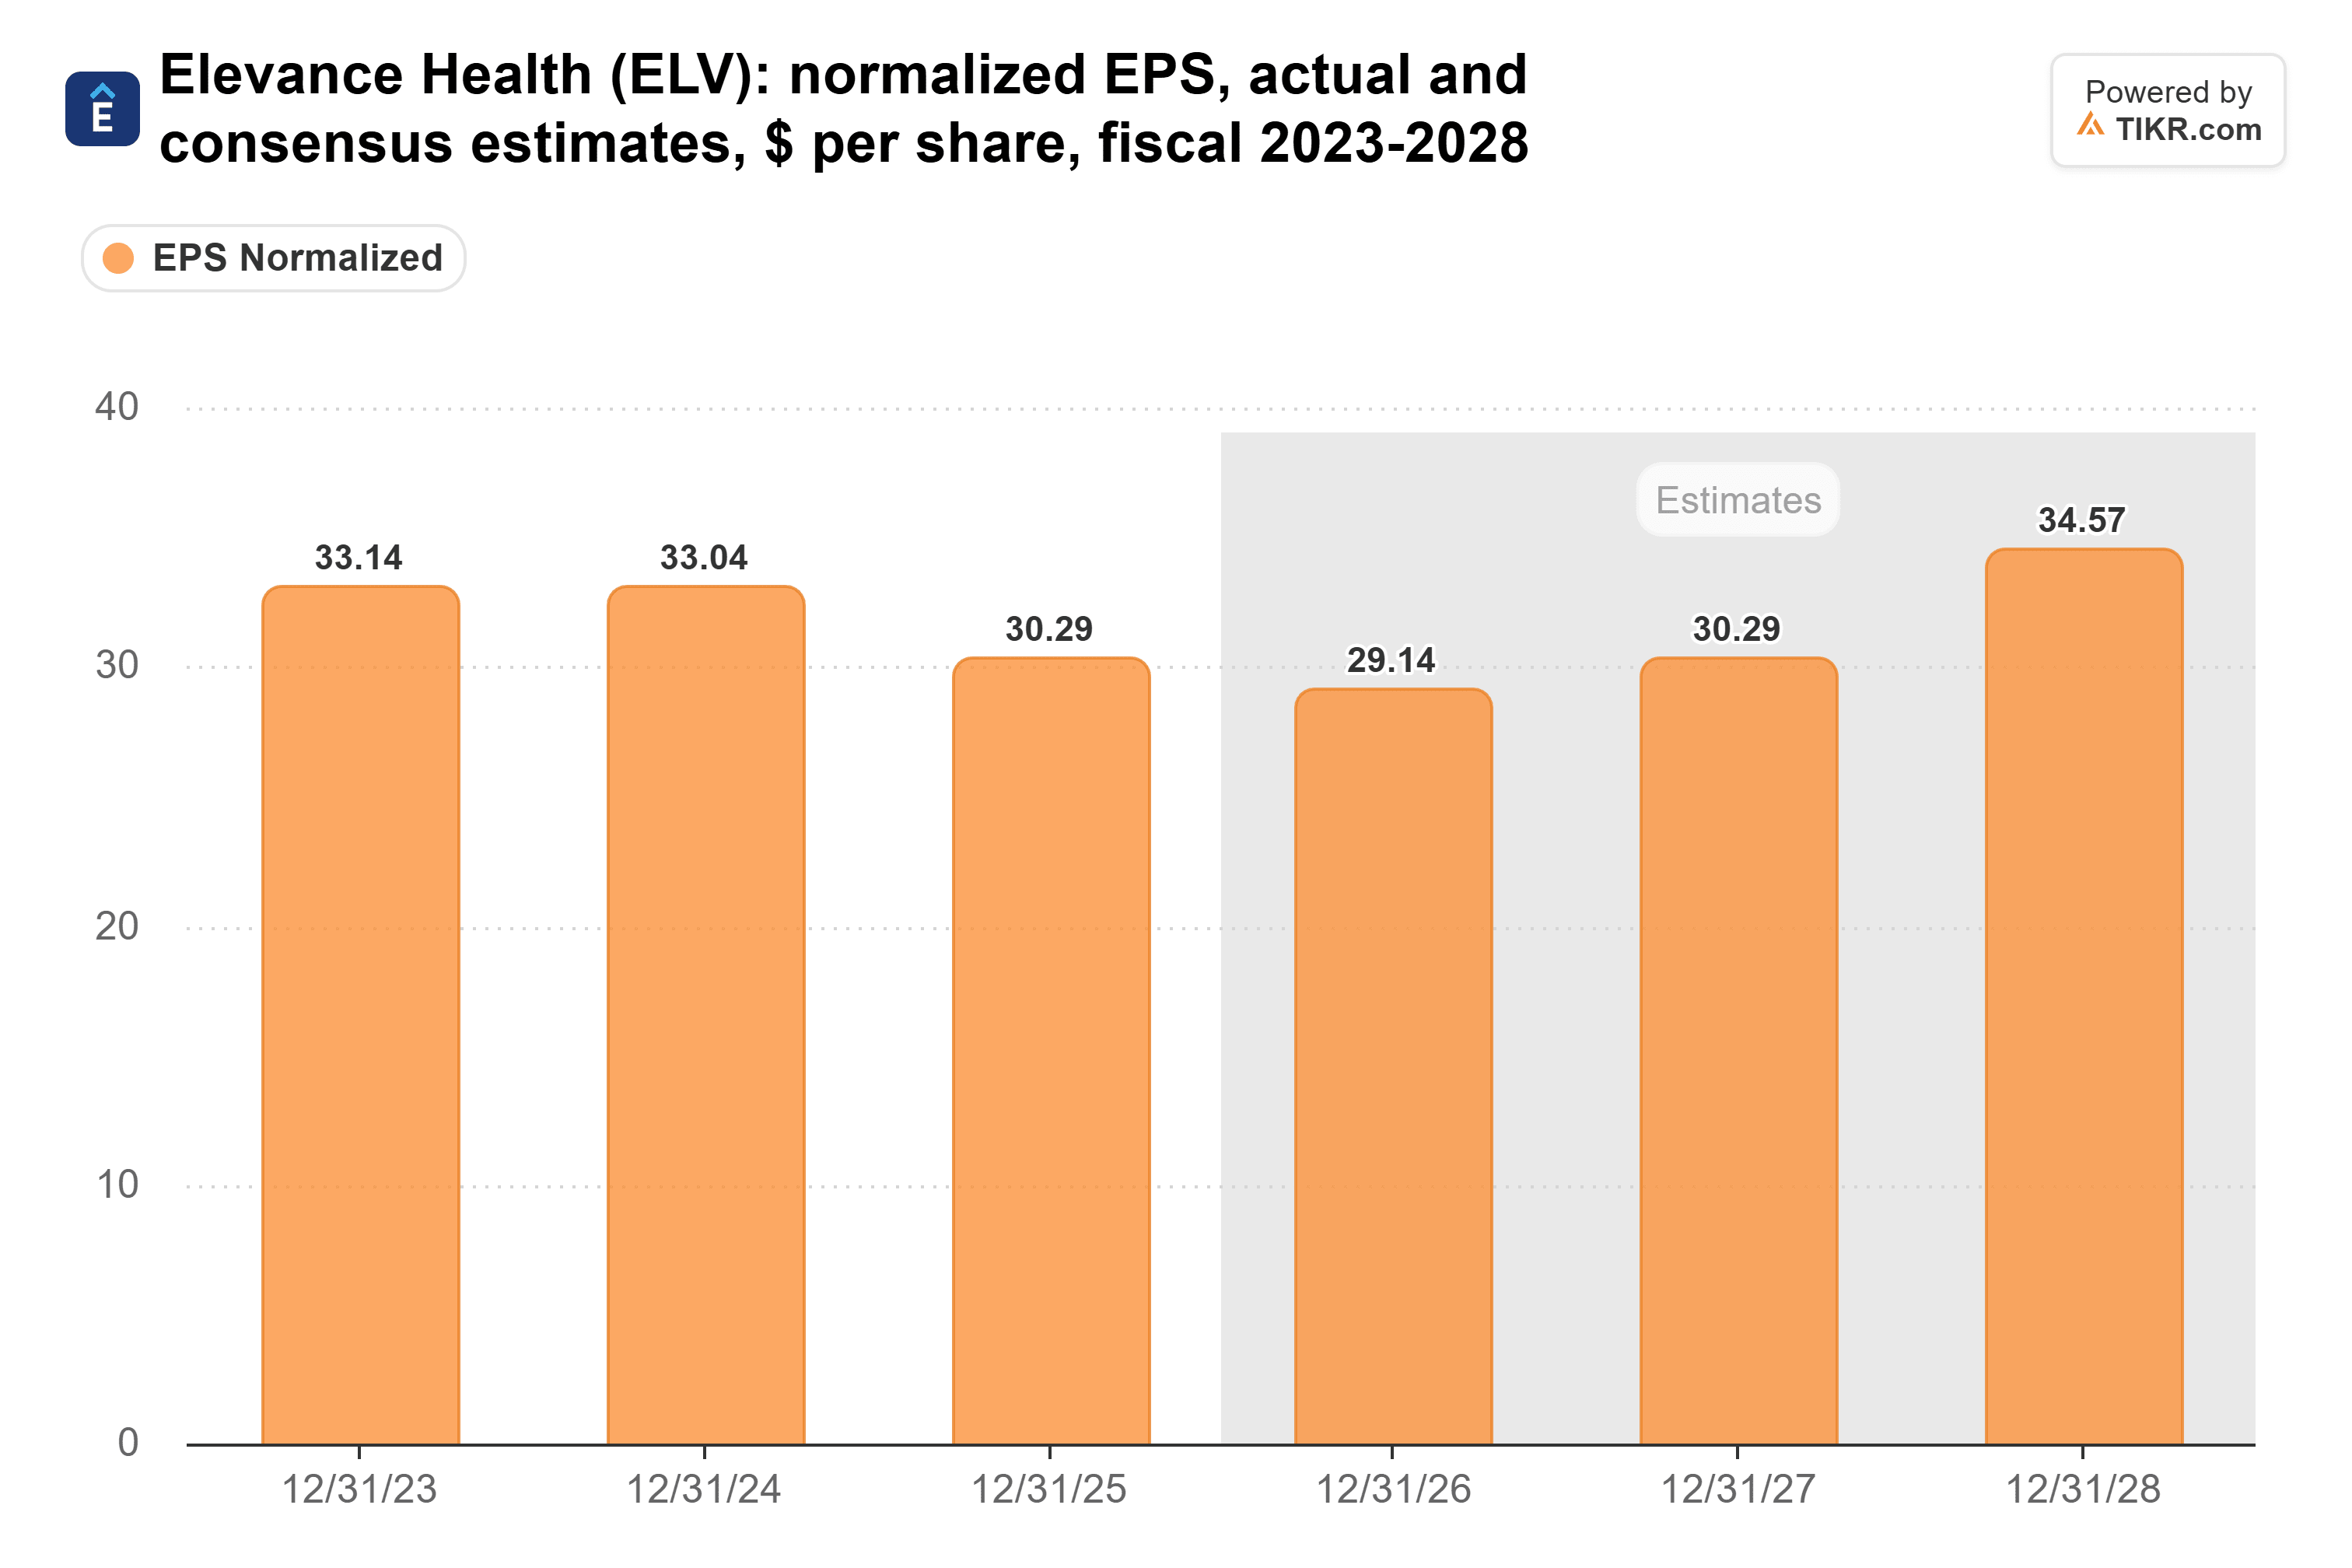
On the chart, 2027 looks like a slow year: $30.29 a share, against $29.14 for 2026. But the 2026 figure includes those one-off gains.
In its Q3 release, Elevance said it’s still confident of at least 12% adjusted EPS growth in 2027. That growth is measured from a 2026 baseline of at least $26.75, which leaves out one-time investment income and other non-operating items.
That works out to about $30 a share, right where the consensus sits. So analysts are counting on Elevance to hit its own floor, and no more.
The price still makes sense
Elevance trades at 15x forward earnings, a bit above its five-year average of 14x.
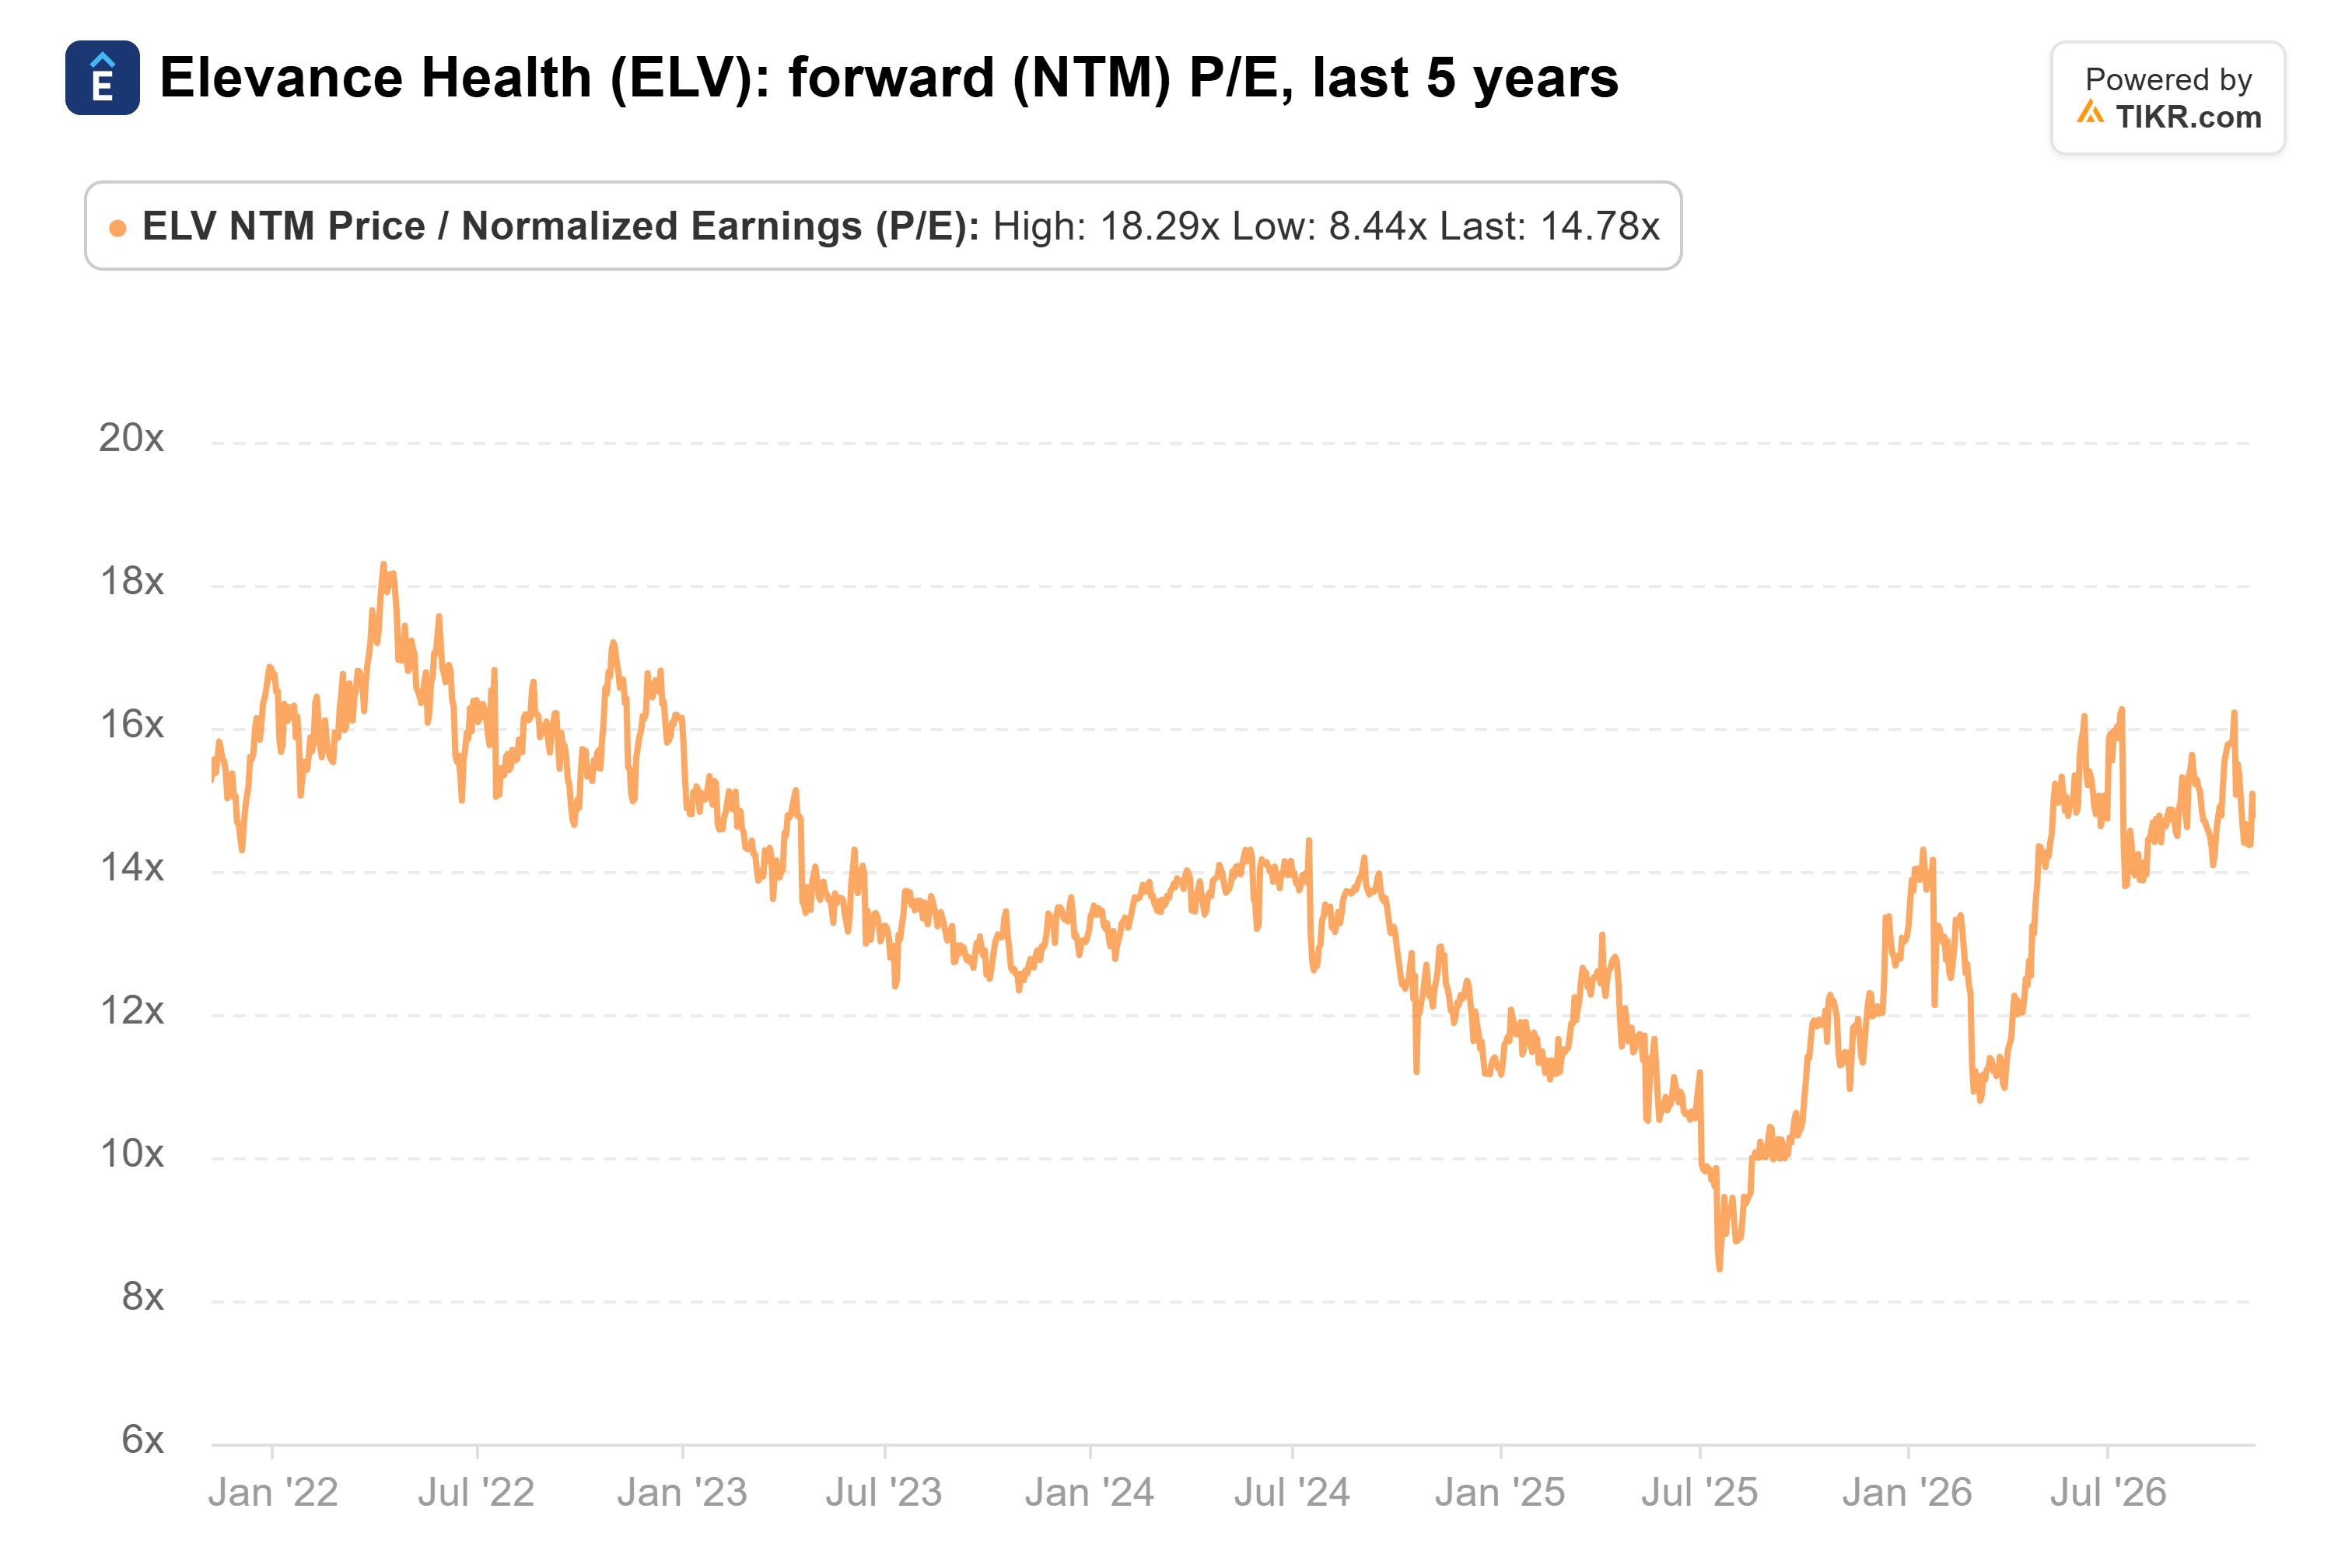
That’s well below the 18x it reached in April 2022, and above its 8.4x low in July 2025. Elevance has raised its outlook three times this year, so paying about its usual multiple looks fair to me.
Analysts have been raising their targets all year. Their consensus target has climbed from $386 a year ago to $482. It first hit that high on Oct. 26, after the Q3 report:

The 22 analysts who cover Elevance have an average target 15% above Friday’s $425.62 close. Their targets run from $406 to $523, so even the lowest is less than 5% below the price.
A bet worth following
The biggest risk is that analysts’ 2027 figure depends on Elevance hitting a growth target it set for itself.
Its costs are also creeping up: the adjusted operating expense ratio rose 90 basis points from Q3 2025 to 11.3%.
Still, I’d follow ACR here. Analysts expect earnings to climb back past $34 a share by 2028, so at 15x, Elevance doesn’t need a higher multiple to reward shareholders. It just needs to keep doing what it has done all year.
Elevance’s Q4 report, early next year, will show whether that 12% floor still holds. And ACR’s next 13F, due by mid-February, will show whether it kept adding.
So what is Elevance Health stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Elevance Health could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Elevance Health for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!